
 Automatic Liquid Dispenser Machine Market | 2026-2036
Automatic Liquid Dispenser Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Liquid Dispenser Machine Market Outlook
Asset-light leasing models for precision dispensing equipment are reshaping competitive dynamics in the automatic liquid dispenser machine space. Nordson Corporation leverages its aftermarket service contracts to sustain recurring revenue streams across adhesive and sealant dispensing lines. Graco Inc. anchors its position through backward integration into pump and valve manufacturing, controlling critical component supply. IVEK Corporation specializes in ceramic pump technology for pharmaceutical dosing applications, differentiating on fluid accuracy and contamination resistance.
An automatic liquid dispenser machine is an electromechanical or pneumatic device engineered to meter, transport, and deposit controlled volumes of liquid through precision pumps, sensors, and nozzle assemblies, typically achieving dispensing accuracies within one to five percent of target volume. These systems serve industrial coating, adhesive bonding, pharmaceutical filling, sanitation, and beverage portioning operations where repeatability and hygiene compliance are non-negotiable. Wall-mounted dispensers dominate healthcare and hospitality installations due to space optimization and standardized mounting protocols, while sensor-based technology leads growth trajectories as infrared and capacitive triggering mechanisms replace manual contact points in hygiene-critical environments. Floor-standing units occupy stable demand in food service and chemical processing settings where bulk reservoir capacity and high-throughput output offset footprint requirements.
The FDA enforces liquid contact surface standards under 21 CFR for food and pharmaceutical dispensing equipment, compelling manufacturers to validate stainless steel grades and elastomer compatibility. EPA regulations on volatile organic compound emissions from adhesive and coating dispensers shape pneumatic system design, particularly in industrial automation deployments. ISO 9001 quality management and ISO 13485 medical device standards further constrain market access for suppliers targeting regulated end uses. Stakeholders must monitor evolving material compliance thresholds and sensor interoperability protocols to secure specification wins in procurement cycles.
Market Dynamics
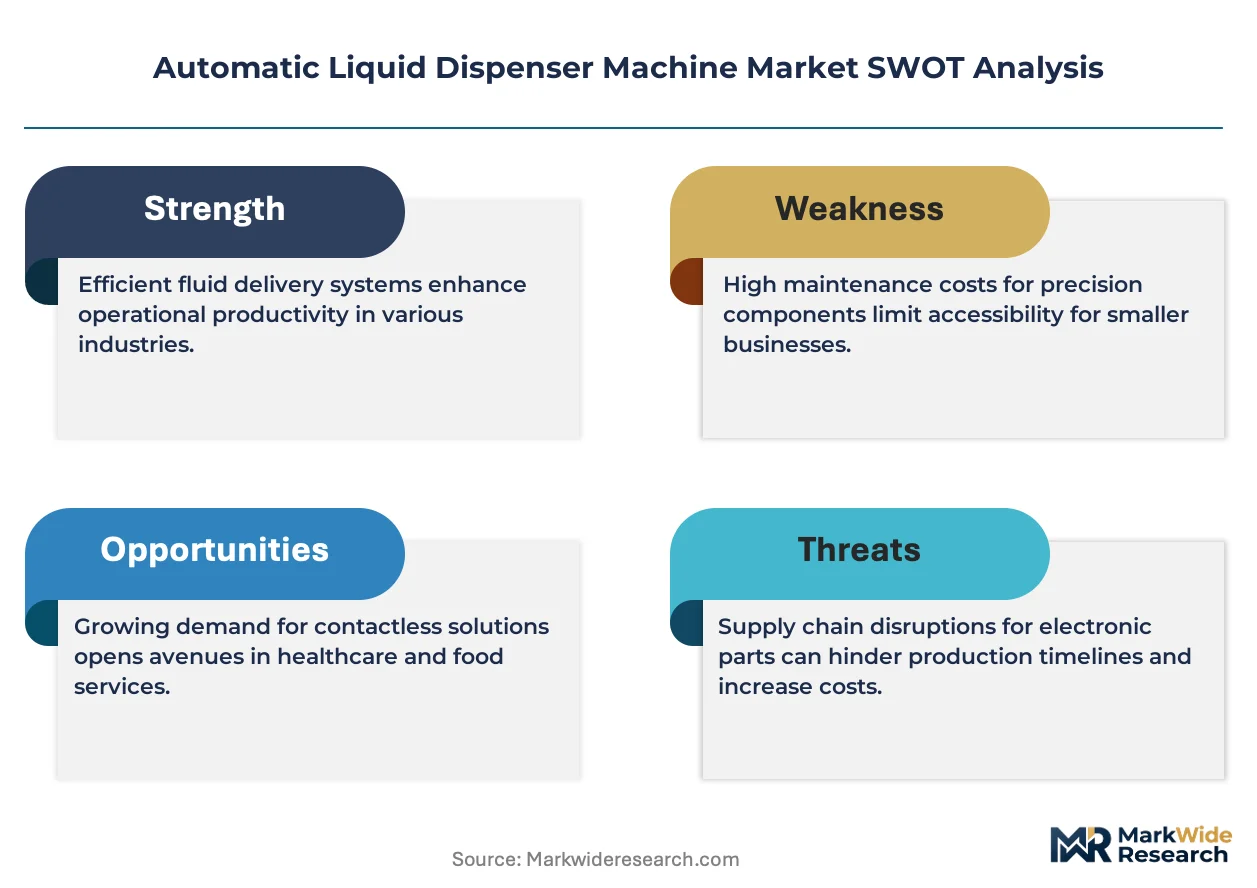
Touchless sensor architecture is displacing mechanical actuation across healthcare and food processing installations, compressing replacement cycles and rewiring supplier qualification criteria toward infrared and capacitive module certification.
Growth Catalysts
- EU MDR sanitation protocols:Healthcare facilities in Germany and France face mandatory compliance timelines for contact-free dispensing systems, accelerating procurement of certified wall-mounted units in hospital networks.
- Stuttgart automation cluster:Precision-engineered dispenser demand concentrates in Baden-Württemberg, where pharmaceutical packaging lines require ceramic pump technology for micro-liter dosing accuracy.
- Infrared triggering mechanisms:Capacitive proximity sensors are eliminating manual contact points in hygiene-critical environments, driving specification wins in hospitality and clinical settings.
Market Restraints
- Stainless steel grade volatility:316L and 304 stainless input costs fluctuate with nickel pricing, squeezing margin structures for device housing manufacturers serving FDA-regulated food contact applications.
- Pump mechanism supply concentration:Ceramic piston and peristaltic pump sourcing clusters in southern Germany and northern Italy, creating single-source vulnerability for North American dispenser assemblers.
- EPA VOC emission thresholds:Pneumatic adhesive dispensing systems face incremental compliance costs under evolving volatile organic compound regulations, disadvantaging legacy compressed-air architectures.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO-aligned dosing equipment demand is accelerating in Hyderabad and Mumbai as domestic vaccine and injectable production capacity expands.
- Asset-light leasing models:Precision dispensing equipment rental programs are penetrating mid-tier food processors in Spain and Poland, converting capex barriers into recurring service relationships.
- ISO 13485 certification convergence:Medical device quality management standards are creating procurement preference for dual-certified suppliers spanning pharmaceutical filling and diagnostic reagent dispensing.
Industry Challenges
- Multi-standard sensor interoperability:Infrared, ultrasonic, and capacitive detection modules lack unified communication protocols, forcing integrators to maintain redundant control system inventories.
- Legacy pneumatic infrastructure retrofit:Food service operators with existing compressed-air lines face displacement costs when transitioning to electric precision pumps for portion control compliance.
- Fluid compatibility validation timelines:Elastomer and seal material testing for novel sanitizer chemistries extends FDA 21 CFR submission cycles, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Liquid Dispenser Machine Market |
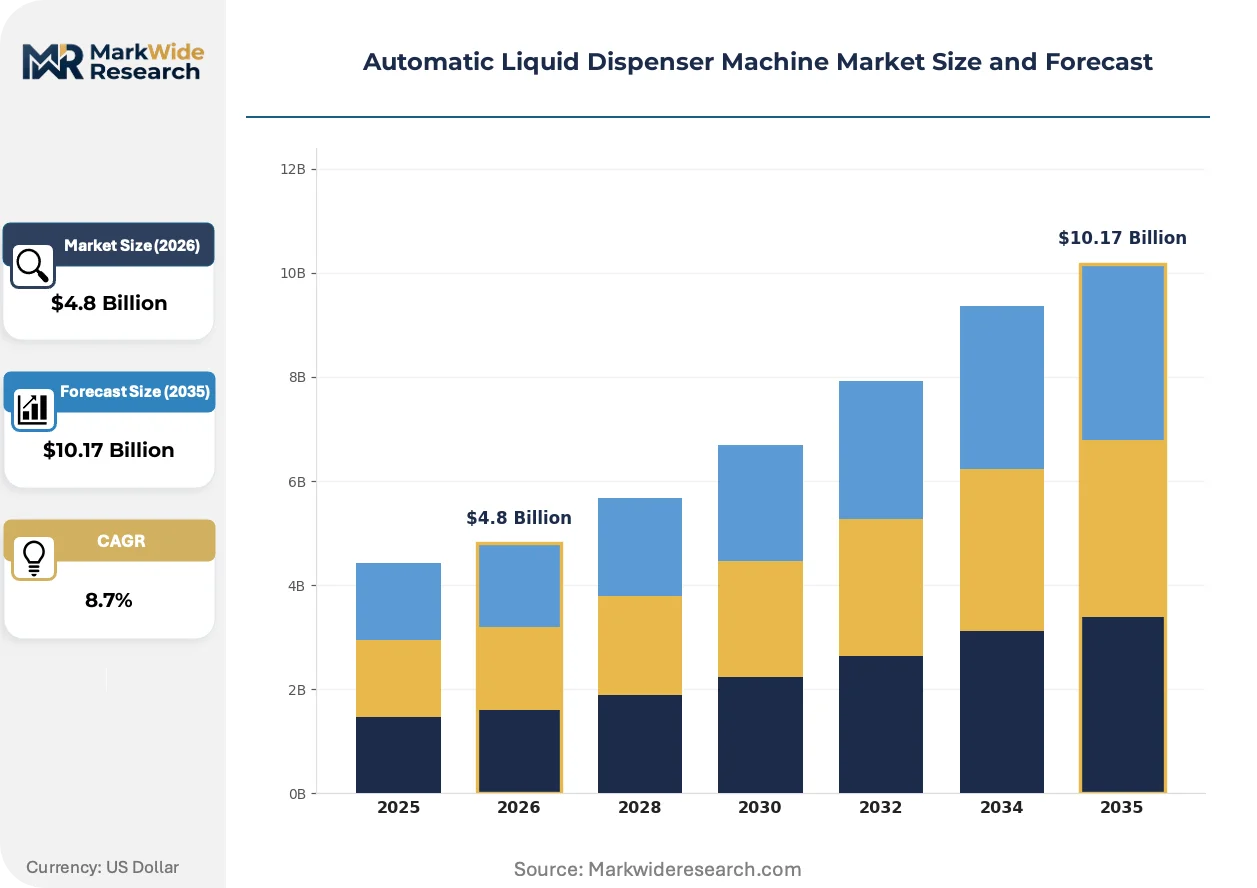
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Dispensers, Wall-Mounted Dispensers, Floor-Standing Dispensers, Portable Dispensers End User: Hospitality, Healthcare, Food Services, Retail Technology: Sensor-Based, Manual, Pneumatic, Electric Application: Liquid Soap, Sanitizers, Beverages, Chemical Solutions |
| Companies Covered | Valco Melton Inc., Nordson Corporation, Graco Inc., IVEK Corporation, Dymax Corporation, GPD Global, Hernon Manufacturing Inc., Techcon Systems, TechnoDigm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Liquid Dispenser Machine Market Strategic Shifts
Electromechanical dispensing architectures are converging with IoT-enabled predictive maintenance platforms, compressing downtime windows and shifting competitive advantage toward data-integrated service ecosystems.
Ceramic piston pump technology is hybridizing precision dosing with contamination resistance for pharmaceutical applications. Biologics manufacturers in Switzerland and Massachusetts are specifying zirconia-based pump heads for monoclonal antibody filling lines. This convergence is hybridizing equipment procurement criteria, merging fluid accuracy specifications with material traceability requirements that exclude traditional stainless steel alternatives.
REACH substance restrictions on perfluorinated compounds are reshaping elastomer selection for seal and gasket components in European dispenser manufacturing. Industrial coating applications face reformulation mandates for adhesive dispensing nozzles. German automotive suppliers are responding fastest, qualifying hydrogenated nitrile rubber substitutes ahead of 2026 restriction deadlines.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles into discrete subscription tiers. Mid-size contract manufacturers in the Netherlands and Belgium are piloting usage-based dispensing fees tied to actual volume throughput rather than capital purchase. This model is compressing supplier-customer relationships into continuous performance contracts with penalty clauses for accuracy deviation.
Automatic Liquid Dispenser Machine Market Segmentation
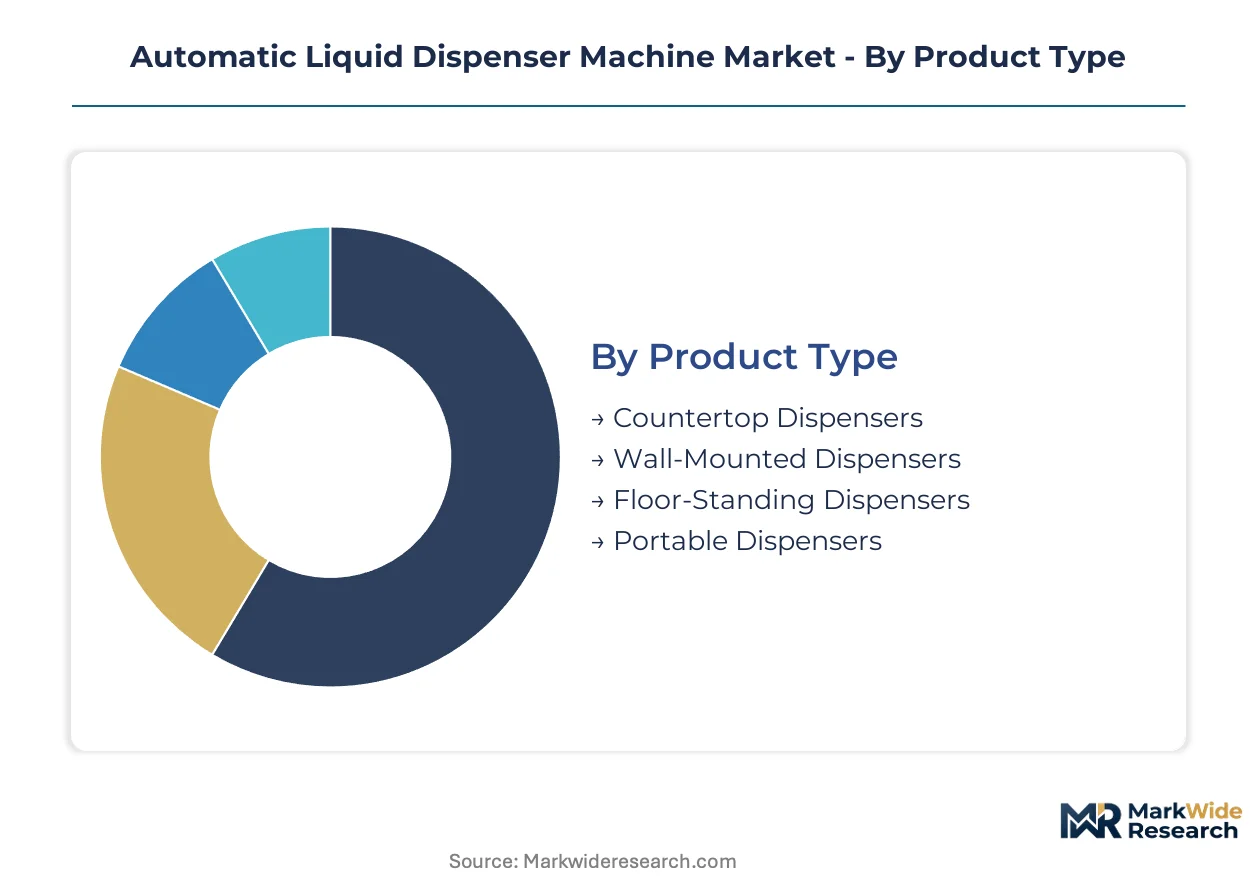
Segmentation in automatic liquid dispenser machines reveals divergent replacement rhythms across installation types and triggering technologies. Procurement cycles stretch from five-year industrial deployments to eighteen-month hospitality refresh schedules, creating distinct margin profiles and aftermarket attachment opportunities for suppliers.
Product Type:
Replacement cycles vary dramatically by mounting configuration and reservoir capacity, with compact units turning over fastest and industrial floor-standing systems persisting longest.
- Countertop Dispensers:Compact units with integrated reservoirs under five liters dominate quick-service restaurants and hotel lobbies. North American hospitality chains in Florida and California are standardizing on modular countertop formats for rapid reconfiguration during seasonal demand swings.
- Wall-Mounted Dispensers:Space-optimized units with concealed plumbing and bulk refill systems achieve the tightest footprint in clinical corridors and food processing lines. German hospital networks in Bavaria specify wall-mounted sensor units under EU MDR sanitation mandates, compressing procurement timelines for certified suppliers.
- Floor-Standing Dispensers:High-capacity systems with fifty-plus liter tanks serve chemical processing and beverage manufacturing where throughput outweighs space constraints. Stainless steel housing grades face FDA 21 CFR validation for food contact surfaces.
- Portable Dispensers:Battery-powered mobile units with manual or capacitive triggers support field sanitation and temporary healthcare facilities. Indian pharmaceutical manufacturers in Hyderabad deploy portable dispensers for cleanroom flexibility during batch changeovers.
Wall-mounted dispensers dominate installed base across healthcare and food processing. Portable dispensers are where expansion concentrates in emerging pharmaceutical manufacturing clusters.
End User:
Compliance intensity and hygiene protocol rigor separate high-specification healthcare procurement from price-sensitive retail deployments.
- Hospitality:Hotels, restaurants, and cruise lines prioritize aesthetic integration and rapid refill protocols over precision dosing. Mediterranean resort chains in Spain and Greece are specifying touchless sensor units to align with post-pandemic guest expectations.
- Healthcare:Hospitals, clinics, and long-term care facilities demand touchless actuation and antimicrobial surface treatments under infection control mandates. French hospital procurement networks face mandatory EU MDR compliance deadlines for contact-free dispensing systems.
- Food Services:Commercial kitchens and processing plants require NSF-certified materials and portion control accuracy for cost management. Italian pasta manufacturers in Emilia-Romagna specify pneumatic dispensers for sauce portioning consistency.
- Retail:Supermarkets, convenience stores, and fuel stations prioritize vandal resistance and minimal maintenance in high-traffic installations. Polish retail chains are piloting usage-based leasing models to convert capital expenditure barriers.
Healthcare commands premium pricing tiers through certification requirements. Food services represent the steepest expansion trajectory as processing automation accelerates in Southern Europe.
Technology:
Actuation mechanism selection determines maintenance burden, energy consumption, and compatibility with legacy infrastructure across installation environments.
- Sensor-Based:Infrared and capacitive proximity triggers eliminate manual contact through non-touch detection algorithms. Swiss pharmaceutical fill-finish lines specify ceramic pump integration with sensor triggers for monoclonal antibody dosing accuracy.
- Manual:Mechanical push-button or lever systems persist in cost-constrained retail and institutional settings with lower hygiene sensitivity. Indian contract manufacturers maintain manual dispenser production for domestic price-tier markets.
- Pneumatic:Compressed-air driven pumps deliver high-viscosity fluids in industrial coating and adhesive bonding applications. EPA VOC emission thresholds are forcing pneumatic system redesigns in US automotive supplier plants.
- Electric:Stepper motor and servo-driven precision pumps achieve micro-liter accuracy for pharmaceutical and diagnostic reagent dispensing. Massachusetts biologics manufacturers specify electric ceramic piston systems for contamination resistance.
Sensor-based systems dominate new specification activity in hygiene-critical environments. Electric precision pumps are gaining share fastest in pharmaceutical manufacturing quality upgrades.
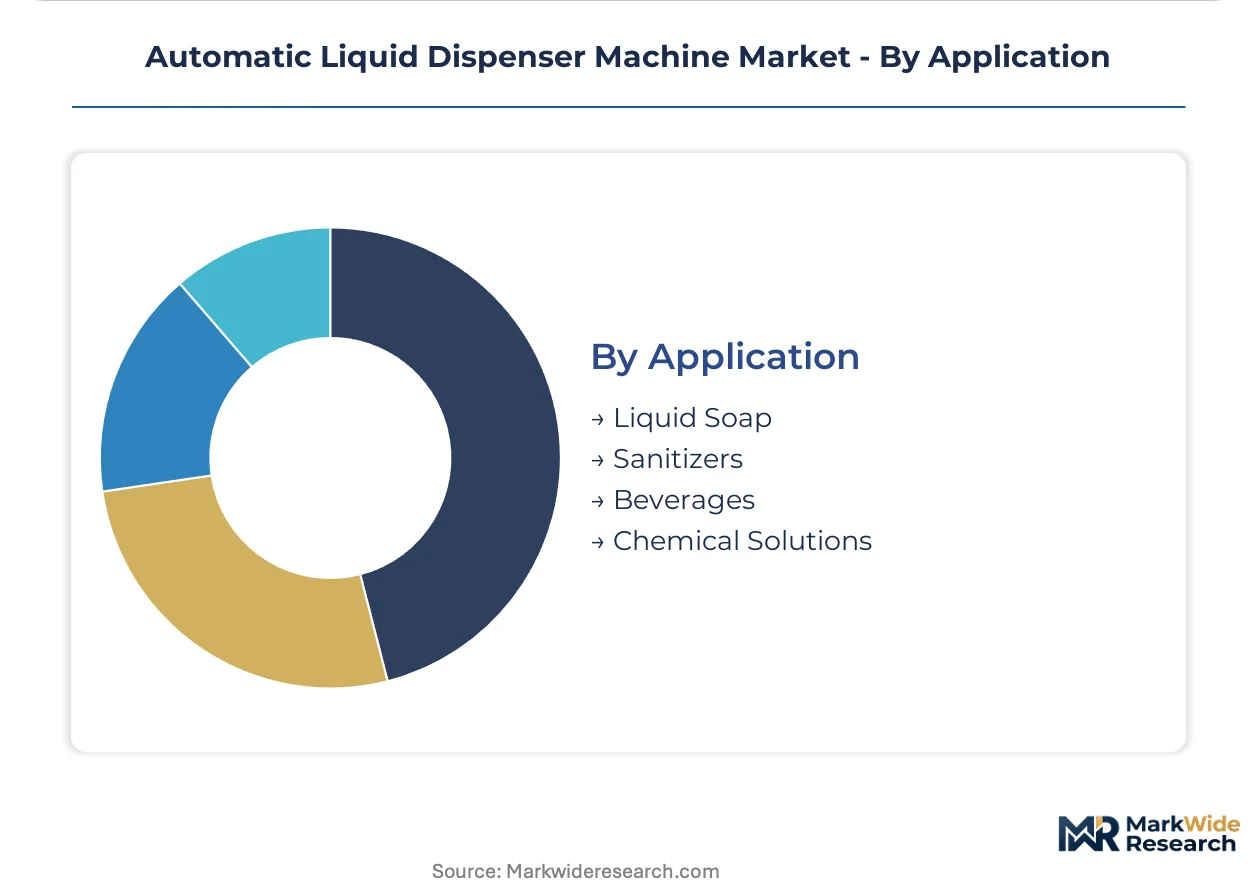
Application:
Fluid chemistry and viscosity requirements dictate material compatibility validation and pump mechanism selection across end-use categories.
- Liquid Soap:Mild surfactant formulations with moderate viscosity suit standard peristaltic and piston pump architectures. German automotive suppliers qualify hydrogenated nitrile rubber seals ahead of REACH perfluorinated compound restrictions.
- Sanitizers:Alcohol-based and quaternary ammonium chemistries demand elastomer compatibility testing under FDA 21 CFR timelines. Extended validation cycles delay product launches for novel sanitizer formulations.
- Beverages:Carbonated and still liquid dispensing requires pressure-rated systems and food-grade stainless steel contact surfaces. Italian prosecco bottling lines specify pressure-compensated electric pumps for foam control.
- Chemical Solutions:Industrial coatings, adhesives, and cleaning agents drive corrosion-resistant pump material specifications. Dutch industrial coating applicators face reformulation mandates under evolving EPA emission thresholds.
Sanitizer dispensing dominates installed base following pandemic-driven healthcare facility upgrades. Beverage applications are where expansion concentrates in automated portion control for food service chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR sanitation mandates and FDA food-contact regulations are accelerating touchless dispenser procurement across healthcare and food processing clusters. Germany's industrial automation corridor anchors precision-engineered demand, while emerging pharmaceutical manufacturing in India and biologics expansion in Switzerland reshape supply chain geography.
Germany
Baden-Württemberg's pharmaceutical packaging lines specify ceramic pump technology for micro-liter dosing accuracy in monoclonal antibody filling. EU MDR compliance deadlines for contact-free dispensing systems compress procurement timelines in Bavarian hospital networks. Stuttgart's automation cluster drives precision-engineered dispenser demand for automotive adhesive bonding and industrial coating lines.
United States
Massachusetts biologics manufacturers specify electric ceramic piston systems for contamination resistance in diagnostic reagent dispensing. FDA 21 CFR validation requirements for stainless steel food-contact surfaces constrain material sourcing for device housing manufacturers. EPA VOC emission thresholds force pneumatic system redesigns in automotive supplier plants across the Midwest.
India
Hyderabad and Mumbai pharmaceutical manufacturers deploy CDSCO-aligned dosing equipment as domestic vaccine and injectable production capacity expands. Portable dispensers support cleanroom flexibility during batch changeovers in emerging manufacturing clusters. Contract manufacturers maintain manual dispenser production for domestic price-tier markets while importing precision pumps from European suppliers.
Switzerland
Swiss pharmaceutical fill-finish lines specify ceramic pump integration with sensor triggers for monoclonal antibody dosing accuracy. Swissmedic medical device standards create procurement preference for dual-certified suppliers spanning pharmaceutical filling and diagnostic applications. Basel's biologics manufacturing concentration drives specification of zirconia-based pump heads ahead of traditional stainless alternatives.
France
French hospital procurement networks face mandatory EU MDR compliance deadlines for contact-free dispensing systems in clinical corridors. ANSM pharmaceutical regulations align with broader European medical device quality management standards. Lyon and Paris healthcare clusters standardize on wall-mounted sensor units with antimicrobial surface treatments under infection control mandates.
Automatic Liquid Dispenser Machine Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base spans multinational fluid handling conglomerates with captive distribution networks alongside precision pump specialists serving niche pharmaceutical applications. Three archetypes dominate: precision ceramic pump specialists, adhesive dispensing system integrators, and industrial coating equipment providers. Competitive moves concentrate on backward integration into pump manufacturing and aftermarket service contract unbundling.
Among North American precision dispensing specialists, Nordson Corporation, Graco Inc., and IVEK Corporation occupy distinct positioning vectors. Nordson represents the adhesive dispensing system integrator archetype with established aftermarket service infrastructure. Graco exemplifies backward integration strategy through captive pump and valve manufacturing. IVEK sits within the ceramic pump specialist tier, anchoring pharmaceutical dosing applications where fluid accuracy and contamination resistance determine specification outcomes.
| Leading Market Players |
|---|
| Valco Melton Inc. |
| Nordson Corporation |
| Graco Inc. |
| IVEK Corporation |
| Dymax Corporation |
| GPD Global |
| Hernon Manufacturing Inc. |
| Techcon Systems |
| TechnoDigm |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese stainless steel component fabrication is compressing margin structures for European device housing manufacturers, forcing procurement teams to rebalance supplier portfolios between cost efficiency and FDA 21 CFR validation requirements.
Pricing Analysis
Certification level creates the primary spread between ISO 13485 medical-grade units and standard industrial dispensers. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and ceramic pump precision grades. Pricing pressure stems from nickel price volatility affecting 316L stainless input costs, with food processing OEMs showing highest price sensitivity versus biologics manufacturers prioritizing contamination resistance.
Supply Chain Analysis
Upstream feedstock dependencies center on zirconia ceramic powders from Japan, precision stepper motors from Germany, and elastomer compounds from the United States. Ceramic piston pump sourcing clusters in southern Germany and northern Italy create single-source vulnerability for North American assemblers. Distribution runs through captive OEM service networks for pharmaceutical applications and industrial distributors for food service deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized ceramic pump engineering talent pools are thinning across Stuttgart and Basel clusters, constraining expansion velocity for precision dosing equipment suppliers and amplifying acquisition premiums for certified manufacturing assets.
For Market Incumbents: Build certification moats by accelerating dual ISO 13485 and EU MDR compliance timelines ahead of 2026 restriction deadlines. Deepen backward integration into zirconia ceramic pump head manufacturing to offset Japanese powder supply concentration. Secure long-term service contracts with Bavarian hospital networks to lock out emerging sensor-technology competitors. For New Entrants and Emerging Players: Build out portable dispenser production capacity targeting Hyderabad and Mumbai pharmaceutical clusters where CDSCO-aligned equipment demand outpaces domestic supply. Target mid-tier Spanish and Polish food processors with asset-light leasing models that convert capex barriers into recurring revenue relationships. Lead with usage-based pricing tied to volume throughput guarantees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sensor-technology sub-segments as infrared module commoditization accelerates. Over a five-to-ten year viability window, acquisition targets should display captive ceramic pump manufacturing and established FDA 510(k) submission track records. Watch for inflection signals in REACH elastomer restriction compliance timelines affecting seal material substitution costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Pump Manufacturing | Captive zirconia pump head production insulates against Japanese powder supply bottlenecks and REACH compliance delays. |
| Dual Certification Investment (ISO 13485 + EU MDR) | Dual-certified suppliers capture procurement preference in Bavarian hospital networks and Swiss biologics manufacturing. |
| Asset-Light Leasing Model Expansion | Usage-based dispensing fees convert mid-tier food processor capex barriers into recurring service relationships in Poland and Spain. |
| Sensor Technology Platform Integration | Infrared and capacitive trigger modules displace mechanical actuation in EU MDR-mandated healthcare installations. |
| Geographic Manufacturing Footprint Expansion | Hyderabad and Mumbai production capacity addresses CDSCO-aligned dosing equipment demand in domestic vaccine manufacturing. |
Study Parameters
The analysis maps precision pump technology tiers, sensor actuation architectures, and regulatory compliance pathways, each validated through plant engineers at pharmaceutical fill-finish facilities, procurement managers at German hospital networks, and aftermarket service heads at adhesive dispensing OEMs. Primary interview intelligence was cross-referenced against FDA 510(k) filings, EMA medical device registrations, CDSCO import records, and SEC 10-K equipment revenue disclosures. Bottom-up unit demand estimates and top-down market sizing were triangulated to constrain projection variance.
Fixed assumptions across the analysis window include sustained EU MDR enforcement timelines, REACH perfluorinated compound restriction implementation, and FDA 21 CFR stainless steel grade validation requirements. Modeled segmentation spans mounting configuration, actuation technology, pump mechanism type, and end-use compliance intensity. CAGRs were derived from install-base replacement cycle analysis and emerging capacity expansion announcements. Forecast inputs incorporated nickel price trajectory assumptions and ceramic powder supply elasticity parameters.
Stress conditions across nickel price volatility bands, REACH restriction acceleration scenarios, and pneumatic-to-electric transition speeds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory timeline delays or ceramic supply disruptions could revise trajectory estimates. Cross-checking against hospital procurement database contract values and pharmaceutical capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Extruder Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Fish Feed Pellet Making Machine Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Electric Kebab Machine Market