
 Taro Market | 2026-2036
Taro Market Size, Share, and Industry Trends Forecast 2026-2036
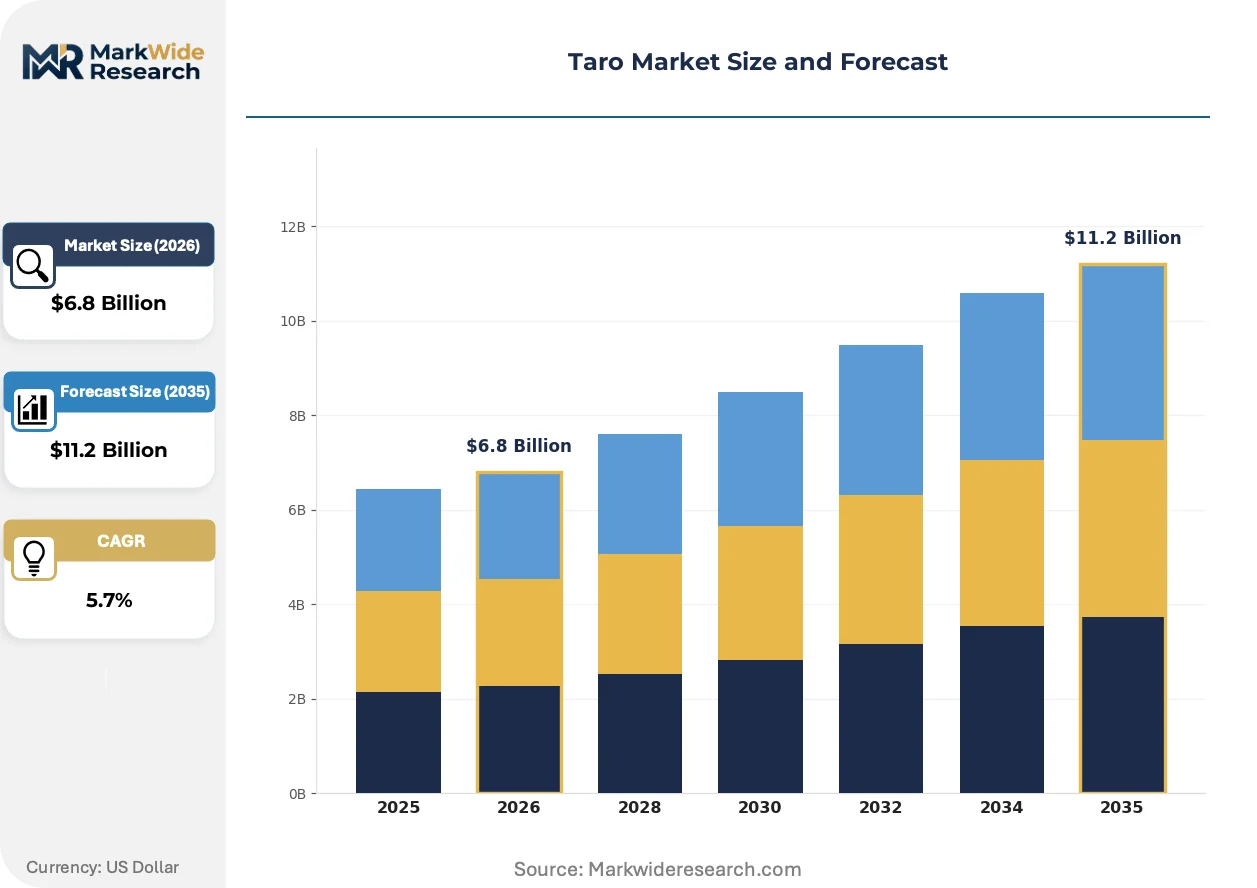
Taro Market Outlook
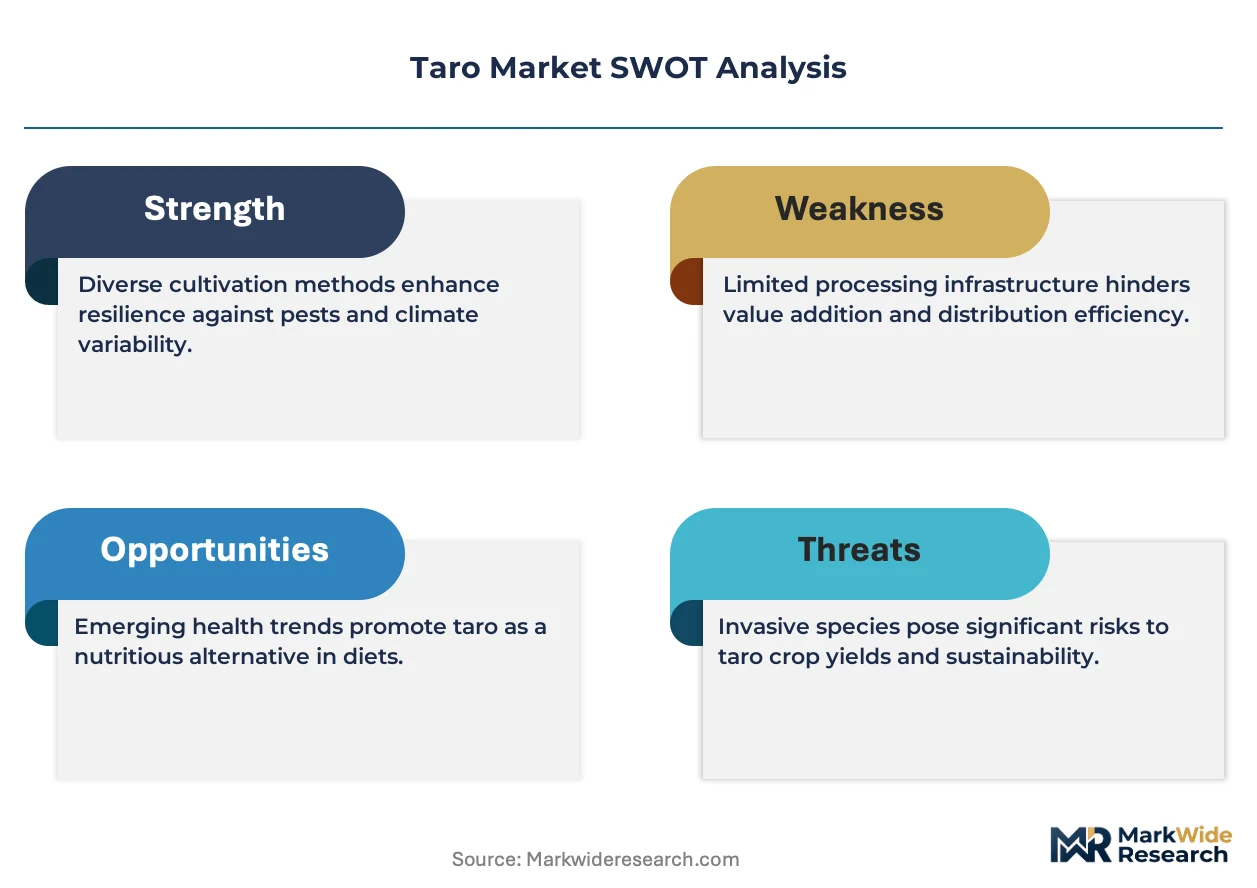
EU novel food authorization under EFSA is decoupling European market access from traditional commodity trading frameworks. Hawaiian Taro Company leverages its integrated cultivation and processing operations on Kauai to command premium positioning. Wismettac Asian Foods anchors North American distribution through its specialized Asian foodservice channels. Dole Food Company extends its tropical produce logistics infrastructure into taro cold-chain management.
Taro is a tropical root vegetable of the Araceae family, containing 25-30% starch by dry weight with a mucilaginous texture from calcium oxalate crystals that requires cooking for safe consumption. The corm serves as a staple carbohydrate source across Pacific Island, Southeast Asian, and African cuisines, while processed derivatives supply industrial food manufacturing. Raw taro dominates volume trade but carries thin margins due to perishability and freight costs. Taro flour occupies a premium tier targeting gluten-free and clean-label formulations where functional starch properties command price separation from commodity alternatives. Frozen taro segments are expanding fastest as food manufacturers seek year-round supply stability independent of harvest cycles.
FDA food safety modernization rules govern taro import inspections and processing facility registrations for US-bound shipments. EFSA novel food classifications create compliance thresholds for value-added taro products entering European markets. Japan's Ministry of Health, Labour and Welfare maintains strict phytosanitary protocols through PMDA-aligned food import channels that shape supplier qualification requirements. Stakeholders must monitor how diverging allergen labeling mandates across these jurisdictions reshape formulation and packaging investment priorities.
Market Dynamics
Food manufacturers across Vietnam, Thailand, and the Philippines are consolidating taro procurement through dedicated processing facilities, compressing traditional spot-market trading and forcing upstream suppliers into contract farming arrangements to secure volume commitments.
Growth Catalysts
- EFSA Novel Food Pathway:European food safety authorization for processed taro derivatives is creating a compliance-based moat that rewards early-mover suppliers with premium market access.
- Gluten-Free Formulation Demand:Bakery and snack manufacturers in North America are substituting wheat starch with taro flour for clean-label product lines targeting celiac and health-conscious consumers.
- Frozen Taro Processing:Industrial blast-freezing technology adoption in Vietnamese processing zones is extending shelf stability from weeks to months, enabling year-round supply to foodservice distributors.
Market Restraints
- Calcium Oxalate Processing Costs:The mandatory cooking and leaching required to neutralize taro's natural irritant crystals adds 15-20% to raw material processing overhead versus cassava or potato alternatives.
- Harvest Cycle Dependency:Fresh corm supply concentrates in monsoon-aligned growing windows across Pacific Island and Southeast Asian cultivation zones, creating six-month supply gluts and shortages.
- Freight Density Economics:Taro's high water content (70% by weight) inflates refrigerated container shipping costs versus dehydrated commodity starches, compressing margins on intercontinental raw corm trade.
Strategic Opportunities
- Japanese Functional Food Channel:PMDA-aligned health claim applications for resistant starch taro derivatives remain underexploited by non-domestic suppliers despite established consumer acceptance of root vegetable nutraceuticals.
- South Korean Convenience Store Chains:CU and GS25 retail networks are expanding private-label taro-based dessert SKUs, creating direct procurement contracts that bypass traditional import brokerage layers.
- US FDA GRAS Self-Determination:Taro flour's established safety profile allows manufacturers to bypass pre-market notification requirements, accelerating new product launch timelines versus novel alternative starches.
Industry Challenges
- Phytosanitary Certification Delays:Japan's Ministry of Agriculture, Forestry and Fisheries maintains extended inspection protocols for taro corm imports, creating 4-6 week customs hold periods that disrupt just-in-time manufacturing schedules.
- Specialized Processing Equipment Scarcity:Industrial-scale taro peeling and slicing machinery requires customization beyond standard root vegetable processing lines, constraining capacity expansion for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taro Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
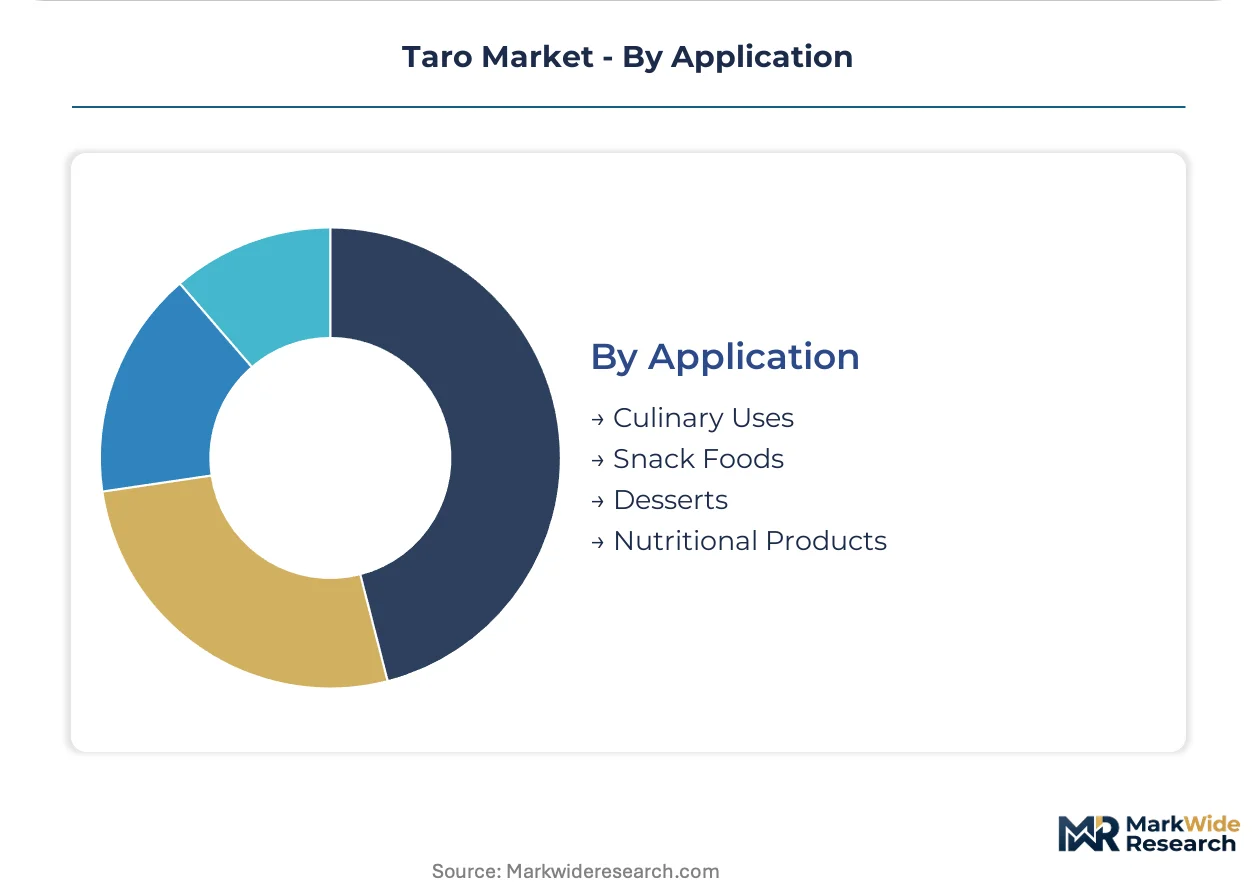
| Segmentation | Product Type: Raw Taro, Processed Taro, Taro Flour, Frozen Taro End User: Restaurants, Grocery Stores, Food Manufacturers, Households Distribution Channel: Online Retail, Supermarkets, Wholesale, Farmers' Markets Application: Culinary Uses, Snack Foods, Desserts, Nutritional Products |
| Companies Covered | Hawaiian Taro Company, Wismettac Asian Foods, Inc., Dole Food Company, Tainong Seeds Inc., Taiwan Sugar Corporation, Fresh Del Monte Produce, Green Giant, JFC International Inc., Taro King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taro Market Strategic Shifts
Processing technology convergence with cold-chain logistics is reconfiguring how taro moves from field to formulation, while regulatory fragmentation across import jurisdictions is forcing suppliers to maintain parallel compliance systems.
Modified atmosphere packaging (MAP) technology is integrating vacuum-sealed, nitrogen-flushed barrier films with real-time temperature monitoring for fresh taro corm shipments. Southeast Asian exporters to North American ethnic grocery chains are adopting this combination to extend shelf life from 14 to 35 days. The technology is integrating perishable produce into e-commerce fulfillment networks previously inaccessible to tropical root vegetables.
REACH chemical safety registrations in the European Union are extending to food-contact materials used in taro processing equipment, requiring stainless steel alloy certifications and lubricant compliance documentation. Equipment manufacturers serving EU-bound taro flour facilities must now maintain substance dossiers for all processing surface materials. Small-scale Vietnamese and Thai processors lacking regulatory affairs capacity are outsourcing this compliance burden to third-party certification bodies.
Direct contracting between food manufacturers and cultivation cooperatives is displacing traditional auction-market procurement in Vietnam's Mekong Delta and the Philippines' Bicol region. Snack and dessert producers in South Korea and Taiwan are establishing minimum guaranteed offtake agreements with named farming collectives, replacing spot purchases through Bangkok and Ho Chi Minh City wholesale markets. This pattern concentrates most visibly in taro varieties selected for specific starch content and color profiles.
Taro Market Segmentation
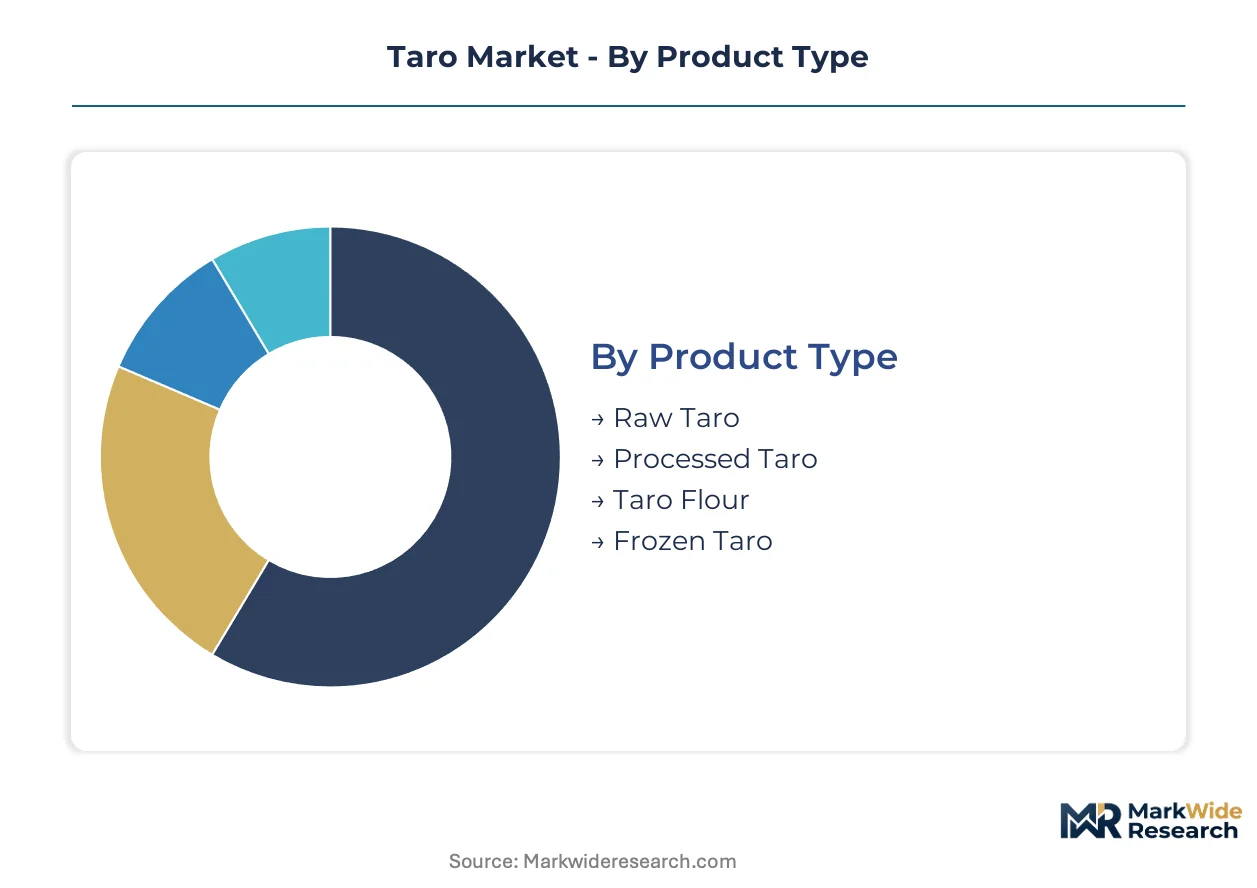
Taro procurement patterns diverge sharply across buyer categories. Food manufacturers prioritize functional starch specifications and year-round supply stability, while restaurants and households trade freshness for convenience and price accessibility.
Product Type:
Buyers in this category separate by processing tolerance and margin capture potential—raw material handlers accept perishability risks for cost position, while derivative processors invest in equipment to extract premium tiers.
- Raw Taro:Fresh corms retain 70% water content and require refrigerated transport chains. Vietnamese and Thai exporters dominate spot-market volume, though thin margins force consolidation around contract farming arrangements with named Mekong Delta cooperatives.
- Processed Taro:Pre-cooked and vacuum-sealed formats neutralize calcium oxalate crystals for foodservice operators lacking on-site processing infrastructure. South Korean convenience chains and Taiwanese bubble tea suppliers anchor demand through direct procurement contracts.
- Taro Flour:Dehydrated starch powder targets gluten-free bakery formulations and clean-label snack applications. EFSA novel food authorization creates compliance-based segmentation between EU-accessible and non-authorized supply sources.
- Frozen Taro:Industrial blast-freezing extends shelf stability from weeks to months, enabling year-round manufacturing schedules independent of monsoon harvest windows. Vietnamese processing zones are expanding dedicated frozen product capacity for regional export.
Volume sits with raw taro; growth tilts toward frozen taro.
End User:
Procurement scale and specification rigor distinguish this category—institutional buyers impose food safety certifications and volume guarantees, while household purchasers prioritize retail accessibility and unit economics.
- Restaurants:Foodservice operators source frozen and processed formats for menu consistency across locations. Hawaiian regional cuisine specialists and Southeast Asian restaurant chains in North America specify taro varieties by starch content and purple color intensity.
- Grocery Stores:Ethnic grocery chains in California, New York, and Texas stock fresh corms for diaspora consumers, while mainstream retailers carry taro chips and frozen desserts for health-conscious segments.
- Food Manufacturers:Snack and dessert producers in Vietnam, Thailand, and the Philippines consolidate procurement through dedicated processing facilities, compressing traditional auction-market trading.
- Households:Direct consumption concentrates in Pacific Island communities and Southeast Asian domestic markets where taro serves as a staple carbohydrate source.
Food manufacturers command the largest contract volumes; restaurants are expanding most quickly as frozen supply chains mature.
Distribution Channel:
Channel selection reflects buyer urgency, lot size requirements, and tolerance for supply intermediation—wholesale and direct contracts displace spot markets for institutional purchasers, while convenience-driven segments migrate online.
- Online Retail:E-commerce platforms serve diaspora consumers seeking specific taro varieties unavailable through local ethnic grocers. Modified atmosphere packaging integration is extending perishable produce into fulfillment networks previously inaccessible to tropical root vegetables.
- Supermarkets:Mainstream retail placement requires standardized sizing, consistent quality grading, and barcode traceability systems that smallholder cooperatives struggle to maintain without aggregator support.
- Wholesale:Bangkok and Ho Chi Minh City wholesale markets still handle significant fresh corm volume, though direct contracting between manufacturers and cultivation cooperatives is displacing traditional auction-market procurement.
- Farmers' Markets:Localized sales persist in Hawaii, Fiji, and Samoa where cultural significance supports premium pricing for named varieties, though volume remains negligible for industrial supply chains.
Wholesale retains volume dominance; online retail is gaining share fastest among diaspora consumer segments.
Application:
Functional requirements and formulation complexity differentiate this category—culinary applications demand sensory authenticity, while industrial processing prioritizes starch yield and binding properties.
- Culinary Uses:Traditional preparation methods—boiling, steaming, and pounding—dominate Pacific Island and Southeast Asian domestic consumption. Purple-fleshed varieties command aesthetic premiums for ceremonial and restaurant presentations.
- Snack Foods:Taro chips and crisps target gluten-free and clean-label positioning in North American and European markets. Starch content specifications determine fry texture and oil absorption rates.
- Desserts:Bubble tea chains, frozen yogurt shops, and Asian bakery concepts drive demand for taro paste and flavoring concentrates. South Korean CU and GS25 retail networks are expanding private-label taro-based dessert SKUs.
- Nutritional Products:Resistant starch derivatives and fiber-enriched formulations target functional food channels in Japan, where PMDA-aligned health claim applications remain underexploited by non-domestic suppliers.
Culinary uses anchor volume consumption; nutritional products show the steepest expansion trajectory as Japanese functional food channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta processing zones attract concentrated investment through preferential tax treatment for agricultural export facilities. Thai and Philippine processors replicate this model, creating regional competition for frozen taro capacity. Japanese import protocols and EFSA novel food pathways shape compliance investment across all three supply bases.
Vietnam
Food manufacturers from South Korea and Taiwan drive frozen taro contract demand through dedicated Mekong Delta processing facilities. Vietnam's Ministry of Agriculture and Rural Development enforces phytosanitary certification aligned with Japanese MAFF import requirements. Can Tho and An Giang provinces host expanding blast-freezing capacity serving year-round regional export schedules.
Thailand
Bangkok-based snack producers and dessert manufacturers consolidate procurement through direct cooperative arrangements in the Central Plains. The Thai Food and Drug Administration maintains GMP-HACCP facility registration requirements for export-oriented processors. Nakhon Pathom and Ratchaburi cultivation zones specialize in purple-fleshed varieties for premium foodservice specifications.
Philippines
Bicol Region cooperatives supply taro paste and frozen derivatives to Taiwanese bubble tea chains and bakery concepts. The Philippines' Bureau of Plant Industry regulates corm export phytosanitary documentation under ASEAN harmonized standards. Camarines Sur and Albay provinces develop contract farming systems replacing spot-market auction trading.
United States
Hawaiian regional cuisine specialists and mainland ethnic grocery chains sustain fresh corm demand through cold-chain distribution networks. FDA food safety modernization rules govern import inspections and processing facility registrations for Pacific Island and Southeast Asian shipments. Kauai hosts integrated cultivation and processing operations commanding premium positioning in domestic specialty markets.
Japan
Functional food manufacturers explore resistant starch taro derivatives for PMDA-aligned health claim applications. Japan's Ministry of Health, Labour and Welfare maintains strict phytosanitary protocols through MAFF-coordinated import channels creating extended customs hold periods. Tokyo and Osaka distribution hubs filter non-domestic suppliers through qualification requirements that favor established trading relationships.
Taro Market Competitive Environment
Southeast Asian producers anchor volume supply; Hawaiian and North American specialists hold premium-tier positioning through integrated operations. The vendor base separates into three functional tiers: plantation-scale cultivators with captive processing, dedicated taro processors serving food manufacturing contracts, and diversified tropical produce traders extending logistics infrastructure. Competitive dynamics center on cold-chain capacity expansion and direct contracting relationships that displace traditional wholesale brokerage layers.
Among diversified tropical produce operators, Dole Food Company exemplifies scale-driven logistics extension into perishable root vegetable cold-chain management. Hawaiian Taro Company represents geographic-origin specialization through integrated Kauai-based cultivation and processing. Wismettac Asian Foods occupies the ethnic foodservice distribution tier, anchoring North American market access through specialized Asian restaurant and grocery channels. These three archetypes illustrate how competitive positioning derives from supply chain control depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Hawaiian Taro Company |
| Wismettac Asian Foods, Inc. |
| Dole Food Company |
| Tainong Seeds Inc. |
| Taiwan Sugar Corporation |
| Fresh Del Monte Produce |
| Green Giant |
| JFC International Inc. |
| Taro King |
| Others |
Value Chain & Pricing Dynamics
EFSA novel food authorization requirements for processed taro derivatives gate qualified supply access to European markets, creating a compliance-based pricing tier that rewards early-mover Vietnamese and Thai processors with premium positioning while excluding uncertified competitors from value-added segments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations between South Korean convenience chains and Mekong Delta processors, while spot-market raw corm trades at discounts reflecting perishability risks and harvest-cycle gluts. Three-tier pricing structure across EFSA-authorized premium, GMP-HACCP standard, and uncertified economy levels separates frozen taro flour from commodity raw corms. Cost compression in fresh corm exports is intensifying because refrigerated container freight absorbs margin on high-water-content shipments. Food manufacturers exhibit lowest price sensitivity due to formulation lock-in requirements, while ethnic grocery spot buyers drive hardest bargain during monsoon harvest peaks.
Supply Chain Analysis
Reverse-logistics flows for returned or temperature-compromised frozen taro shipments remain underdeveloped across Southeast Asian export corridors, forcing write-offs that inflate landed costs for North American distributors. Vietnam, Thailand, and the Philippines anchor cultivation concentration, with Mekong Delta cooperatives supplying frozen derivatives and Bicol Region farms feeding Taiwanese bubble tea chains. Calcium oxalate leaching equipment and blast-freezing capacity constitute critical input dependencies that constrain mid-scale processor expansion. Single-source vulnerability concentrates in Vietnamese blast-freezing zones where South Korean contract demand outstrips installed capacity. Distribution runs through direct manufacturer-cooperative contracts that displace Bangkok and Ho Chi Minh City wholesale auction layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive cultivation control and in-house blast-freezing capacity determine contract eligibility for premium food manufacturing offtake.
For Market Incumbents: Hedge against EFSA regulatory tightening by diversifying authorization submissions across multiple processed taro derivatives rather than single-SKU compliance. Secure backward integration into named Mekong Delta and Bicol Region farming collectives before direct contracting exhausts available cooperative capacity. Channel control through dedicated frozen product facilities offers defensive moat against emerging Thai processors replicating Vietnamese tax-incentive models. For New Entrants and Emerging Players: The price-point gap between EFSA-authorized premium tiers and uncertified economy raw corm supply creates entry space for mid-tier processors investing in GMP-HACCP facility registration without full novel food dossier costs. Target Japanese functional food channels where PMDA-aligned health claim applications for resistant starch derivatives remain underexploited by non-domestic suppliers. Go-to-market angle should emphasize year-round supply stability guarantees to North American gluten-free bakery manufacturers frustrated by harvest-cycle disruptions. For Investors and Strategic Acquirers: Vietnamese Ministry of Agriculture and Rural Development announcements of expanded phytosanitary certification capacity are the leading indicator that Japanese MAFF import hold periods will compress, unlocking working capital efficiency for export-oriented processors. Long-term viability favors acquisition targets with integrated cultivation-processing footprints in Kauai or Mekong Delta zones where geographic-origin branding commands persistent premium. Monitor South Korean CU and GS25 private-label expansion announcements for early signals of contract volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Cooperatives | Captive Mekong Delta and Bicol Region supply secures volume commitments for frozen taro export contracts. |
| EFSA Novel Food Authorization Investment | Processed taro flour access to European markets creates compliance-based price separation from commodity alternatives. |
| Blast-Freezing Capacity Expansion | Industrial shelf-life extension from weeks to months enables year-round manufacturing schedules independent of monsoon windows. |
| PMDA-Aligned Health Claim Application | Japanese functional food channel entry leverages established consumer acceptance of root vegetable nutraceuticals. |
| Direct-to-Manufacturer Contracting | Bypassing Bangkok and Ho Chi Minh City wholesale markets captures margin previously absorbed by brokerage layers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with Vietnamese processing facility managers, South Korean convenience chain procurement directors, Japanese functional food R&D leads, and FDA-registered US import distributors. EFSA novel food authorization databases, Japanese MAFF phytosanitary inspection protocols, and Vietnamese Ministry of Agriculture export facility registrations supplied compliance pathway documentation. Bottom-up cultivation volume estimates from Mekong Delta and Bicol Region cooperative records were triangulated against top-down food manufacturer demand aggregation.
Data-stream reconciliation across raw corm spot-market transactions, frozen derivative contract terms, and taro flour formulation demand generated consistent volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user category, distribution channel, and application with regional regulatory cluster overlays. CAGRs were derived from time-series analysis of trade flow data and processor capacity expansion announcements. Industry-specific forecast inputs incorporated blast-freezing technology adoption curves and EFSA authorization pipeline status.
Inputs from Vietnamese agricultural export associations and Japanese customs clearance databases were available through the study window; gaps in real-time South Korean convenience chain inventory data introduce uncertainty bands around near-term demand elasticity assumptions. Forecasts reflect documented assumptions regarding phytosanitary certification processing timelines and frozen logistics cost trajectories. Practitioners should monitor EFSA authorization decision announcements and Vietnamese tax incentive policy revisions for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Pure Plant Oil Market