
 Global Paracetamol Market | 2026-2036
Global Paracetamol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paracetamol Market Foresight
Para-aminophenol is restructuring cost dynamics across paracetamol supply chains as manufacturers pivot from coal-tar derivatives to petroleum-based feedstocks. Granules India Ltd. anchors bulk API production through backward integration into acetanilide intermediates. Sun Pharmaceutical Industries Ltd. leverages formulation specialization across regulated markets. Sanofi sustains brand equity in over-the-counter channels through sustained pharmacist-level promotion.
Paracetamol, or N-acetyl-para-aminophenol, functions as a centrally acting analgesic and antipyretic with a recommended adult dose of 500–1000 mg and a narrow therapeutic window requiring hepatotoxicity monitoring above 4 g daily. Its primary purpose spans fever management, mild-to-moderate pain relief, and perioperative analgesia in hospital settings. Standard paracetamol tablets occupy mature volume pools with compressed margins, while extended-release formulations capture premium positioning through patent-protected delivery technologies. Pediatric formulations represent the fastest-expanding category as liquid dosage development addresses swallowing difficulties in children under twelve.
The FDA enforces current Good Manufacturing Practice standards for paracetamol API facilities supplying the United States, while the EMA's revised Module 3 guidelines tighten impurity profiling requirements for European market access. India's CDSCO mandates batch-release testing under Schedule M of the Drugs and Cosmetics Rules, shaping export competitiveness for domestic manufacturers. Stakeholders must monitor evolving pharmacovigilance obligations around hepatotoxicity warnings as regulators in multiple jurisdictions reassess labeling requirements.
Market Dynamics
Hospital procurement of intravenous paracetamol is accelerating as surgical volumes recover across developed markets, while the European Union's revised F-Gas Regulation and REACH compliance protocols are elevating manufacturing standards for active pharmaceutical ingredients. This dual pressure on supply security and environmental accountability is restructuring competitive positioning across the value chain.
Growth Catalysts
- Surgical Volume Recovery:Elective procedure backlogs in the United States, Germany, and Japan are driving hospital formulary restocking of parenteral analgesics.
- REACH Compliance Protocols:The European Chemicals Agency's tightened impurity profiling requirements are favoring manufacturers with advanced quality management systems.
- Petroleum-Based Feedstock Pivot:The shift from coal-tar derivatives to para-aminophenol from petroleum sources is reducing batch-to-batch variability in API synthesis.
Market Restraints
- Input Cost Volatility:Crude oil price fluctuations directly transmit to para-aminol and acetanilide intermediate costs, compressing margin predictability for non-integrated producers.
- Supply Concentration Risk:Andhra Pradesh and Telangana pharmaceutical clusters in India account for disproportionate global API capacity, creating geographic vulnerability to regional disruptions.
- Regulatory Friction:The FDA's current Good Manufacturing Practice enforcement for API facilities supplying the United States imposes compliance costs that disproportionately burden smaller manufacturers.
Strategic Opportunities
- Pediatric Liquid Formulations:Swallowing difficulties in children under twelve are driving demand for palatable, stable liquid dosage development.
- Extended-Release Delivery Technologies:Patent-protected modified-release formulations capture premium positioning above commoditized immediate-release tablets.
- PLI Scheme Incentives:India's production-linked incentive scheme for bulk drugs is attracting capital investment into backward-integrated API manufacturing.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Hepatotoxicity monitoring and signal detection capabilities require specialized clinical pharmacology expertise that remains concentrated in regulatory agencies and large multinationals.
- Legacy Equipment Retrofit Costs:Continuous manufacturing adoption demands capital-intensive replacement of batch reactor infrastructure, straining mid-tier manufacturers.
- Labeling Harmonization Complexity:Divergent hepatotoxicity warning requirements across the FDA, EMA, and CDSCO force multi-jurisdictional packaging strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paracetamol Market |
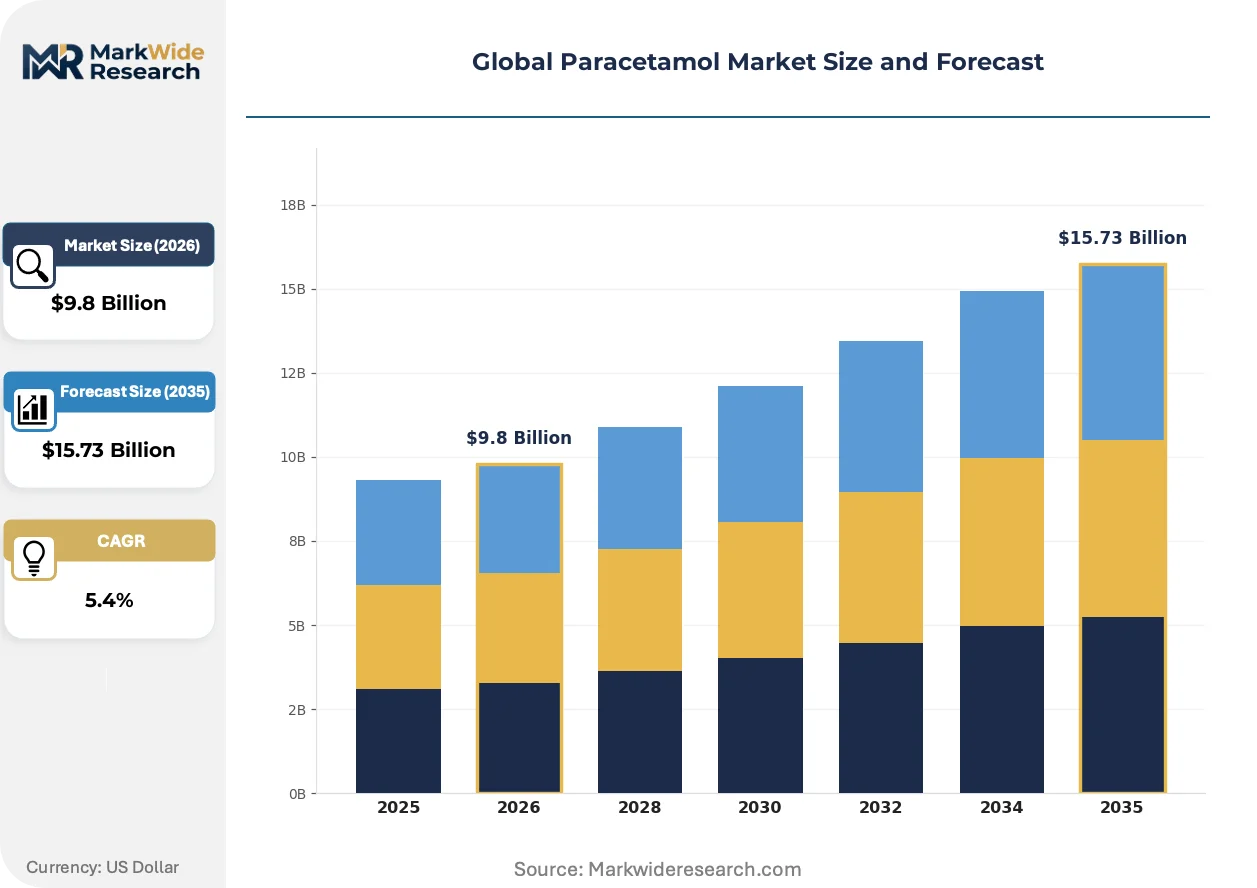
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Paracetamol, Extended-Release, Pediatric Formulations, Combination Drugs Therapy Area: Fever Management, Pain Relief, Inflammation Reduction, Cold & Flu Treatment End User: Hospitals, Clinics, Pharmacies, Home Healthcare Packaging Type: Blister Packs, Bottles, Sachets, Strip Packs |
| Companies Covered | Granules India Ltd., Sun Pharmaceutical Industries Ltd., Sanofi, Johnson & Johnson, Bayer AG, GlaxoSmithKline plc, Teva Pharmaceuticals, Inc., Anqiu Lu'an Pharmaceutical, Mallinckrodt Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paracetamol Market Shifts & Advancements
Continuous flow chemistry is unifying process efficiency with quality assurance in paracetamol synthesis, while regulatory digitization and hospital procurement centralization are reshaping how value is captured across the supply chain.
Continuous manufacturing technology is unifying reaction, separation, and crystallization into integrated processing trains. Large-scale API producers in India and Germany are retrofitting pilot facilities at accelerated timelines. This convergence is compressing batch release cycles from weeks to days while reducing solvent waste volumes.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon use in pharmaceutical manufacturing cooling systems. API facilities must retrofit refrigeration infrastructure or switch to alternative heat transfer fluids. European manufacturers with early compliance investments are securing preferred supplier status with EMA-audited formulation partners.
Hospital group purchasing organizations are consolidating procurement of perioperative analgesics under centralized formulary management. Independent surgical centers and regional hospital networks are ceding purchasing autonomy to national buying consortia. This concentration is most visible in the United States, where three major GPOs now control the majority of intravenous paracetamol hospital volume.
Global Paracetamol Market Segmentation
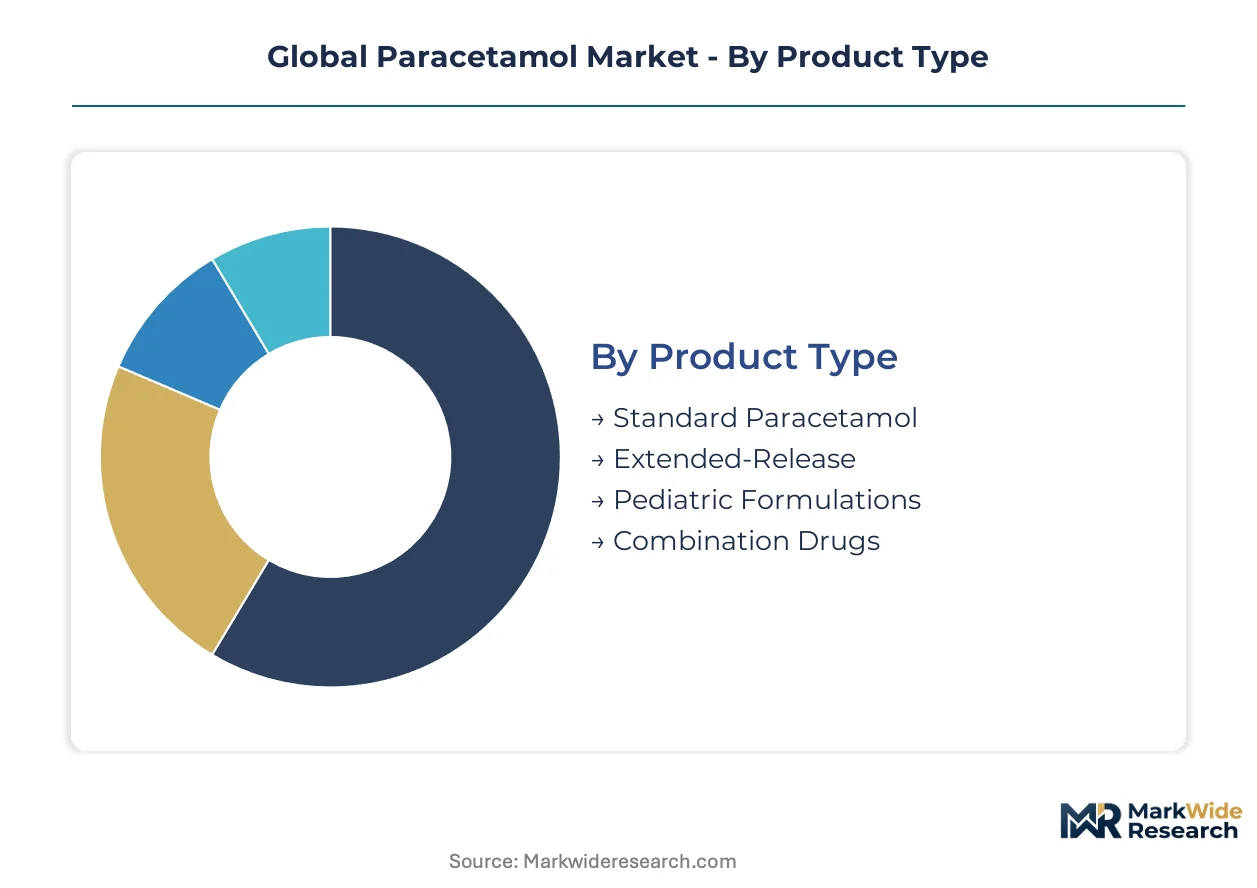
Paracetamol segmentation reflects divergent capital requirements across formulation complexity and regulatory stringency. Investment intensity varies sharply between commodity tablet production and specialized delivery systems requiring dedicated manufacturing lines.
Product Type:
Capital intensity peaks in modified-release technologies demanding specialized coating equipment and dissolution-testing infrastructure, while standard formulations require lower barrier-to-entry investments.
- Standard Paracetamol:Immediate-release tablets and capsules dominate volume procurement through established compression and granulation equipment. Hospital formularies in the United States and Germany restock these formulations as surgical volumes recover, though margin compression intensifies from API cost volatility and procurement centralization.
- Extended-Release:Matrix-based and osmotic pump delivery systems require patent-protected polymer technologies and specialized dissolution apparatus. European manufacturers with EMA-audited facilities capture premium positioning through controlled-release pharmacokinetics that reduce dosing frequency in chronic pain management.
- Pediatric Formulations:Liquid suspensions and dispersible tablets demand palatability engineering and stability testing for pediatric populations.
- Combination Drugs:Fixed-dose combinations with caffeine or codeine require additional API handling infrastructure and controlled-substance compliance protocols.
Standard Paracetamol absorbs the bulk of installed capacity; Pediatric Formulations is expanding most quickly.
Therapy Area:
Application-driven segmentation reveals distinct reimbursement pathways and prescriber behavior across acute versus chronic indications.
- Fever Management:Antipyretic use spans outpatient retail and inpatient settings with universal reimbursement coverage. Demand concentrates in India's domestic retail channels and Southeast Asian markets where self-medication rates for pyrexia remain elevated.
- Pain Relief:Analgesic applications command perioperative premium pricing in hospital settings. German and Japanese surgical centers drive intravenous formulation adoption as opioid-sparing protocols gain institutional traction.
- Inflammation Reduction:Adjunctive use in inflammatory conditions competes with NSAID alternatives on formulary positioning.
- Cold & Flu Treatment:Seasonal demand volatility shapes inventory planning for combination cough-cold products.
Pain Relief claims the steepest expansion trajectory from surgical volume recovery; Fever Management retains the broadest geographic penetration.
End User:
Customer-type segmentation tracks procurement autonomy erosion as purchasing concentrates under centralized contracts.
- Hospitals:Parenteral and high-volume oral formulations flow through group purchasing organization contracts. Three major United States GPOs now control the majority of intravenous paracetamol hospital volume, compressing supplier margins while securing supply security.
- Clinics:Ambulatory surgical centers and specialist practices require flexible procurement of multi-dose presentations.
- Pharmacies:Retail channels sustain brand equity through pharmacist-level promotion and over-the-counter accessibility.
- Home Healthcare:Long-term care and post-discharge settings drive demand for patient-compliant packaging formats.
Hospitals absorb the bulk of parenteral capacity investment; Home Healthcare is climbing the fastest from aging-in-place trends.
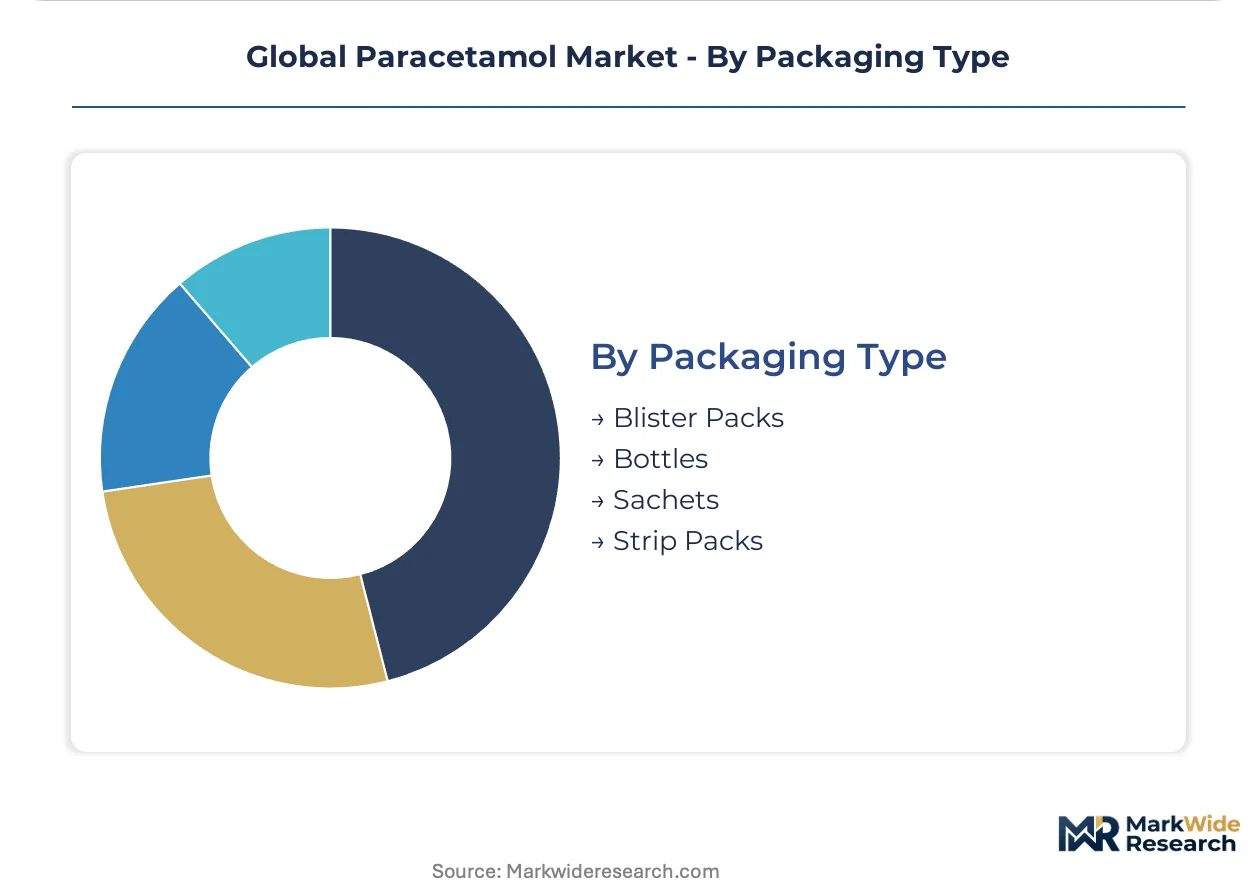
Packaging Type:
Packaging segmentation aligns with stability requirements, patient compliance engineering, and distribution channel specifications.
- Blister Packs:Unit-dose aluminum-PVC configurations dominate European retail and hospital unit-dose dispensing. EMA serialization mandates and F-Gas Regulation compliance for forming equipment elevate capital requirements for European suppliers.
- Bottles:High-density polyethylene containers serve pediatric liquid formulations and high-volume institutional dispensing. Andhra Pradesh manufacturers supply bulk bottle formats to African and Latin American markets where cost minimization overrides unit-dose convenience.
- Sachets:Single-use powder presentations address portability requirements in emerging markets.
- Strip Packs:Polymer-laminate strips provide moisture protection for tropical distribution climates.
Blister Packs retain the majority of regulatory-compliant capacity; Sachets are gaining share fastest from rural market penetration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of intravenous paracetamol concentrates in the United States, Germany, and Japan as surgical volumes recover. India's Andhra Pradesh and Telangana pharmaceutical clusters supply disproportionate global API capacity. European REACH compliance and F-Gas Regulation retrofit costs are elevating manufacturing standards.
United States
Three major hospital group purchasing organizations now control the majority of intravenous paracetamol volume, compressing supplier margins while securing supply security. The FDA enforces current Good Manufacturing Practice standards for API facilities supplying domestic markets. New Jersey and Puerto Rico host formulation facilities serving hospital formulary restocking.
Germany
German surgical centers drive intravenous formulation adoption as opioid-sparing protocols gain institutional traction. The EMA's revised Module 3 guidelines tighten impurity profiling requirements for European market access. North Rhine-Westphalia and Bavaria maintain EMA-audited formulation partnerships with preferred supplier status.
India
Andhra Pradesh and Telangana pharmaceutical clusters have expanded API production capacity substantially, creating geographic concentration risk. The CDSCO mandates batch-release testing under Schedule M of the Drugs and Cosmetics Rules. Hyderabad anchors backward-integrated manufacturing through the PLI scheme for bulk drugs.
Japan
Japanese surgical centers accelerate parenteral analgesic restocking as elective procedure backlogs clear. The PMDA maintains stringent pharmacovigilance obligations around hepatotoxicity warnings. The Kansai region around Osaka sustains formulation specialization for regulated export markets.
China
Anqiu Lu'an Pharmaceutical anchors domestic API production serving internal and export demand. The NMPA aligns with international GMP standards for facilities supplying developed markets. Shandong Province concentrates para-aminophenol synthesis capacity with petroleum-based feedstock pivot.
Global Paracetamol Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement centralization favoring scale-driven suppliers and retail OTC channels sustaining brand equity investments. The vendor base organizes around three archetypes: backward-integrated API producers, formulation specialists with EMA-audited facilities, and multinational brand owners with pharmacist-level promotion capabilities. Dominant competitive moves include capacity expansion in Indian pharmaceutical clusters and strategic partnerships for extended-release delivery technologies.
Among India-based manufacturers, Granules India Ltd. and Sun Pharmaceutical Industries Ltd. occupy positions within the API and formulation tiers respectively. Sanofi represents the multinational branded specialist archetype with sustained OTC channel presence. These three entities exemplify the competitive structure: domestic backward-integrated production, regulated-market formulation specialization, and global brand equity maintenance through healthcare professional engagement.
| Leading Market Players |
|---|
| Granules India Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Sanofi |
| Johnson & Johnson |
| Bayer AG |
| GlaxoSmithKline plc |
| Teva Pharmaceuticals, Inc. |
| Anqiu Lu'an Pharmaceutical |
| Mallinckrodt Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Commodity-standard bifurcation between patent-protected extended-release formulations and immediate-release tablets manifests in divergent margin structures and sourcing configurations across the paracetamol value chain. EMA-audited facilities command premium positioning through controlled-release pharmacokinetics, while Andhra Pradesh API producers feed high-volume, low-margin hospital procurement through concentrated petrochemical feedstock corridors.
Pricing Analysis
Volume procurement of immediate-release tablets absorbs capacity at compressed margins, while extended-release formulations capture premium positioning through patent-protected polymer technologies. Price differentiation hinges on EMA certification tier and backward integration into para-aminophenol intermediates. Cost compression in standard formulations is intensifying because crude oil volatility transmits directly to acetanilide input costs. Hospital group purchasing organizations exhibit highest price sensitivity; formulation specialists with EMA-audited facilities demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Andhra Pradesh and Telangana pharmaceutical clusters, where disproportionate global API capacity creates geographic concentration risk. Para-aminophenol, acetanilide intermediates, and petroleum-based feedstocks anchor upstream dependencies. Tariff exposure on Chinese intermediate imports threatens margin stability for non-integrated producers. Distribution runs through hospital group purchasing organization contracts in the United States, Germany, and Japan, with retail pharmacy channels sustaining OTC brand equity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow chemistry is displacing legacy batch reactor infrastructure across paracetamol synthesis, compressing release cycles from weeks to days while reducing solvent waste volumes.
For Market Incumbents: Anchor supply security through backward integration into para-aminophenol intermediates in Indian pharmaceutical clusters. EMA Module 3 impurity profiling requirements threaten non-compliant facilities; prioritize certification investment in North Rhine-Westphalia and Bavaria partnerships. Capacity consolidation under group purchasing organization contracts demands volume scale defense. For New Entrants and Emerging Players: Launch via pediatric liquid formulation specialization targeting swallowing difficulties in children under twelve. White-space sits with palatability-engineered suspensions for ambulatory surgical centers outside consolidated GPO networks. Regulatory digitization in European markets creates entry pathway through EMA-audited contract manufacturing partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated API producers given India's PLI scheme capital inflows into bulk drug manufacturing. Long-term viability favors facilities with continuous manufacturing retrofit completion and REACH-compliant refrigeration infrastructure. Monitor F-Gas Regulation compliance timelines as inflection indicator for preferred supplier status consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | Batch-to-continuous conversion in Hyderabad facilities compresses release cycles and solvent waste volumes. |
| Backward Integration into Intermediates | Captive acetanilide production in Andhra Pradesh insulates margin from crude oil price transmission. |
| EMA Module 3 Compliance Investment | Impurity profiling capabilities secure preferred supplier status with German formulation partners. |
| Pediatric Liquid Formulation Development | Palatability engineering addresses fastest-expanding category for children under twelve. |
| F-Gas Refrigeration Retrofit | Alternative heat transfer fluid adoption aligns with ECHA phasedown timelines for pharmaceutical cooling. |
Research Methodology
Independent corroboration across API facility audits, hospital procurement databases, and regulatory filing disclosures underwrites the qualitative findings. Primary interviews with pharmaceutical manufacturing executives, regulatory affairs specialists, hospital formulary directors, and group purchasing organization contract managers combined with secondary validation from FDA filings, EMA submissions, CDSCO Schedule M batch records, and customs trade data. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to surgical volume recovery trajectories in the United States, Germany, and Japan structured the forecast window across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and regional regulatory cluster. CAGRs derived from weighted average of historical trend extrapolation and demand driver elasticity analysis. Forecast inputs incorporate para-aminophenol feedstock cost indices and hospital procurement centralization rates.
Crude oil price volatility, REACH compliance timeline acceleration, and hepatotoxicity warning label harmonization delays are the dominant revision risks. Forecasts reflect documented assumptions around surgical volume recovery persistence and PLI scheme incentive continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Adamantane Antiviral Drugs Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Europe Pharmaceutical Contract Sales Outsourcing (CSO) Market
Pharmaceuticals
Hepatic Antiviral Drugs Market