
 Reinforced Thermoplastic Pipes Market | 2026-2036
Reinforced Thermoplastic Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Reinforced Thermoplastic Pipes Market Outlook
A capital-intensity divergence between integrated pipe-lay specialists and component suppliers is unwinding competitive stability in the sector. Shawcor leverages its full-service offshore installation capability to capture bundled project awards. Baker Hughes anchors its position through proprietary connection systems and downhole integration expertise. TechnipFMC competes by combining subsea engineering heritage with thermoplastic manufacturing scale.
Reinforced thermoplastic pipes consist of a thermoplastic liner, helically wound continuous fiber reinforcement layers, and an external protective jacket, typically rated for pressures exceeding 150 bar and temperatures up to 65°C, engineered to transport hydrocarbons, chemicals, and water without internal corrosion. Pipelines dominate product-level value capture due to extended meterage requirements in offshore tiebacks, while fittings and couplings concentrate margin pools through specialized metallurgy and fatigue-resistant design. Polyethylene leads material adoption for sour service and water injection lines, though polyamide variants are gaining traction in high-temperature gas gathering where permeation resistance commands premium positioning.
API 15S governs qualification testing and quality assurance for spoolable reinforced plastic line pipe in US hydrocarbon service, while ISO 14692 provides international design and installation standards for fiberglass-reinforced thermosetting and thermoplastic piping systems. Brazil's national petroleum regulator ANP mandates specific traceability protocols for flexible pipes deployed in pre-salt fields, directly shaping supplier certification requirements. Stakeholders must monitor evolving subsea tieback economics and polymer recycling mandates to calibrate capacity commitments and material platform strategies.
Market Dynamics
Offshore field economics are compressing project timelines and forcing operators to abandon rigid steel risers in favor of spoolable thermoplastic systems that slash installation vessel days and eliminate corrosion mitigation costs.
Growth Catalysts
- API 15S qualification protocols:Standardized spoolable pipe testing requirements in US hydrocarbon service reduce buyer due diligence burden and accelerate supplier onboarding for mid-scale producers.
- Pre-salt basin developments:Brazil's ultra-deepwater fields generate sustained demand for flexible flowlines rated to 300 bar operating pressure and sour gas compatibility.
- Carbon fiber reinforcement:Advanced filament winding techniques enable thinner wall constructions without pressure rating degradation, reducing transport weight and offshore handling complexity.
Market Restraints
- Aramid fiber supply concentration:European and Japanese specialty fiber producers control 80% of high-tenacity reinforcement supply, exposing pipe manufacturers to input cost volatility and allocation risk during aerospace demand surges.
- Temperature ceiling limitations:Standard polyethylene liners degrade above 65°C, excluding RTP from high-temperature gas injection and steamflood applications where thermoset composites dominate.
- ISO 14692 certification friction:International design standard harmonization gaps force dual-track qualification for projects spanning multiple regulatory jurisdictions, extending engineering cycles.
Strategic Opportunities
- Decommissioning wave in UK North Sea:Aging steel infrastructure replacement creates retrofit demand for corrosion-resistant tieback systems with 25-year design life.
- Hydrogen blending infrastructure:Polyamide barrier layers demonstrate permeation resistance for H2 transport, opening pipeline repurposing opportunities as gas grids decarbonize.
- Modular factory fabrication:Shore-based spool manufacturing with offshore reel-ship deployment compresses project schedules versus field welding of rigid pipe strings.
Industry Challenges
- Polymer welding technician scarcity:Qualified electrofusion and butt-fusion specialists command premium wages as training pipeline fails to match installation capacity expansion.
- End-fitting metallurgy integration:Dissimilar material interfaces between thermoplastic liners and steel termination hardware create fatigue failure modes requiring proprietary design solutions.
- DNV-ST-F119 qualification timelines:Subsea thermoplastic pipe integrity standard compliance requires 18-24 month test programs, constraining supplier response to spot market opportunities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reinforced Thermoplastic Pipes Market |
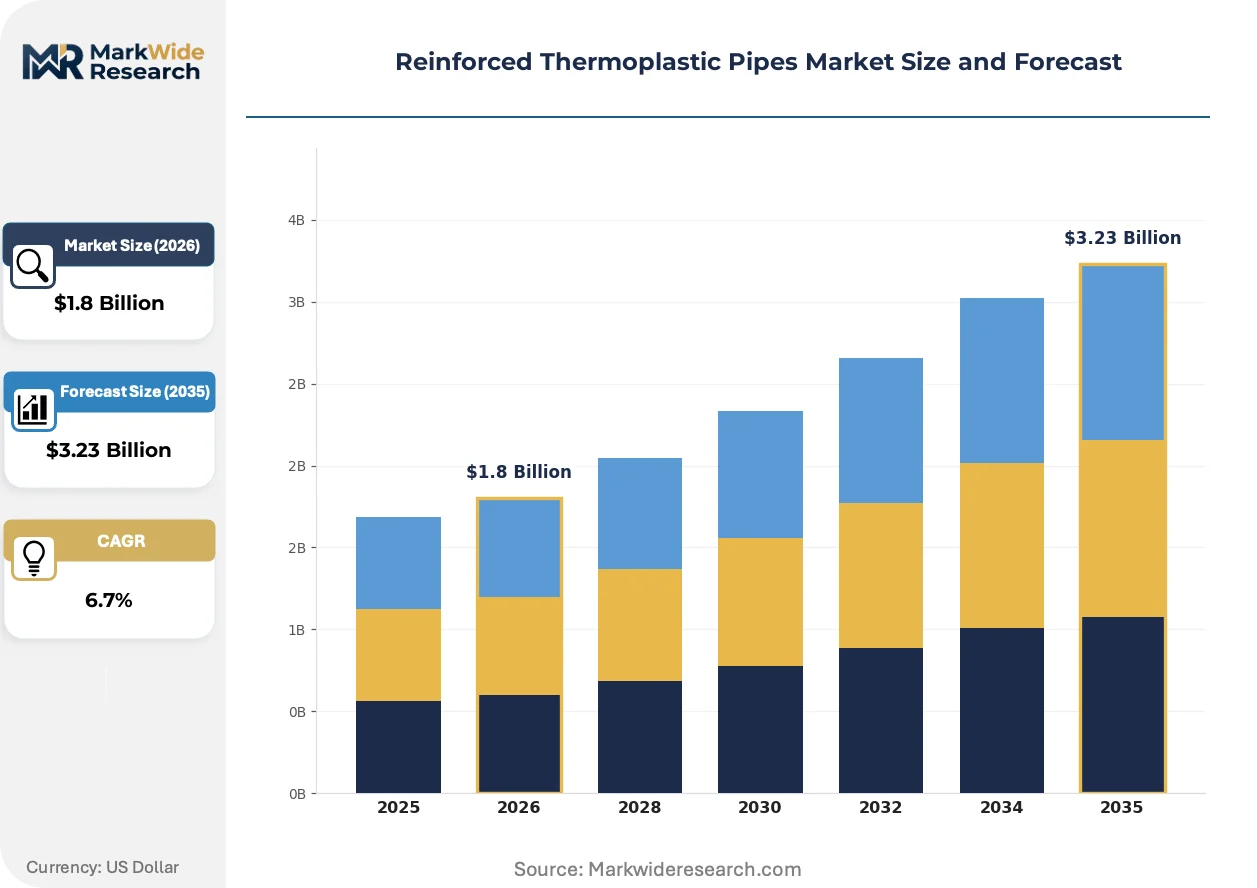
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipelines, Fittings, Valves, Couplings End Use Industry: Oil & Gas, Water Supply, Chemicals, Mining Installation Type: Above Ground, Below Ground, Underwater, Onshore Material: Polyethylene, Polypropylene, Nylon, Others |
| Companies Covered | Shawcor, Georg Fischer, Baker Hughes, Airborne Oil & Gas, Wienerberger, TechnipFMC, Prysmian Group, Polyflow, National Oilwell Varco (NOV), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reinforced Thermoplastic Pipes Market Strategic Shifts
Material science advances and installation method refinements are fragmenting the historically unified flexible pipe category into purpose-built thermoplastic and thermoset product families.
Polyamide liner technology is bifurcating the gas gathering segment. PA11 and PA12 barrier layers block methane permeation at elevated temperatures, enabling operators to extend RTP service into high-pressure gas condensate fields previously reserved for metallurgically complex steel catenary risers. Adoption concentrates in Middle East sour gas developments where hydrogen sulfide corrosion accelerates steel degradation.
EU Green Deal methane emission regulations are tightening fugitive gas standards across energy infrastructure. The F-Gas Regulation revision and CSRD disclosure mandates compel operators to quantify pipeline permeation losses, redirecting capital toward thermoplastic systems with documented barrier performance. North Sea operators respond fastest, embedding polymer selection criteria into front-end engineering contracts.
Integrated service contracting is displacing component-only procurement in deepwater projects. Operators bundle pipe supply, installation, and integrity monitoring into single-source awards, compressing vendor lists and favoring firms with captive reel-lay vessel capacity. Brazil's pre-salt cluster exhibits this pattern most acutely, where Petrobras tieback packages rarely separate pipe manufacturing from offshore deployment scope.
Reinforced Thermoplastic Pipes Market Segmentation
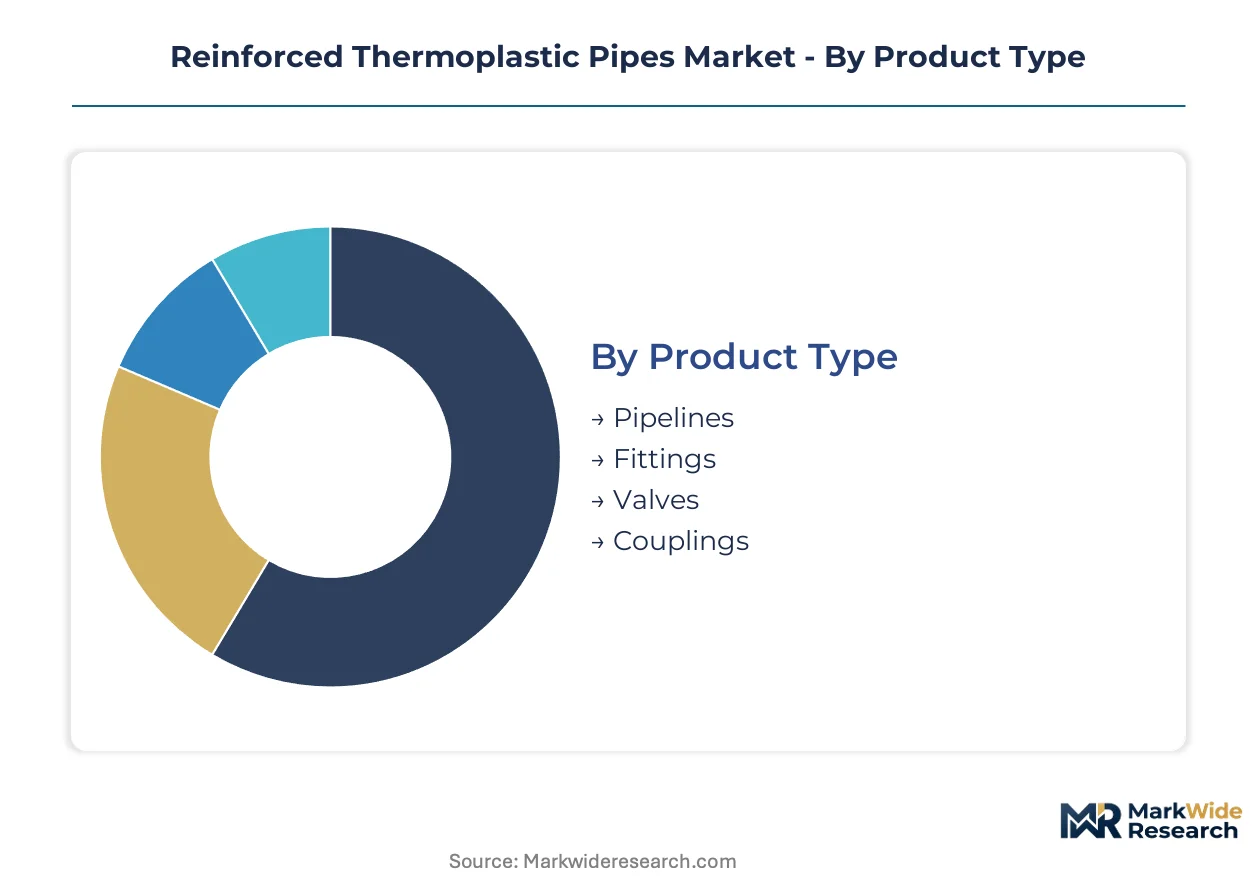
Segmentation in the reinforced thermoplastic pipes market reveals divergent supply chain configurations and margin structures across product categories. Each dimension exposes distinct competitive dynamics between standardized commodity offerings and engineered solutions requiring certification depth.
Product Type:
Domestic fabrication dominates pipeline and fittings production, while couplings and specialized valves flow through export-oriented manufacturing hubs serving deepwater project clusters.
- Pipelines:Continuous extrusion of thermoplastic liners with helically wound fiber reinforcement creates kilometer-length spoolable sections rated to 300 bar. Demand concentrates in Brazil's pre-salt basin tiebacks where Petrobras specifications mandate API 15S qualification and integrated installation contracting.
- Fittings:Injection-molded or machined termination hardware incorporates electrofusion sockets and flanged interfaces for pressure-containing joints. The UK North Sea decommissioning wave drives retrofit procurement as operators replace corroded steel jumpers with corrosion-resistant thermoplastic alternatives.
- Valves:Custom-engineered ball and gate configurations with thermoplastic wetted surfaces serve chemical injection manifolds.
- Couplings:Metallic compression sleeves and gripper inserts bridge dissimilar pipe materials in hybrid installations.
Pipelines command the established base. The steepest expansion runs through fittings as brownfield retrofit intensity accelerates.
End Use Industry:
Cost tier stratification separates capital-intensive offshore hydrocarbon projects from municipal water infrastructure with compressed procurement cycles.
- Oil & Gas:Offshore production systems, gathering networks, and water injection lines exploit RTP's corrosion immunity and reduced installation vessel requirements. Middle East sour gas developments in Saudi Arabia and UAE deploy polyamide-lined systems for high-pressure condensate service where hydrogen sulfide degrades steel.
- Water Supply:Municipal distribution networks and industrial cooling water systems leverage polyethylene's chemical inertness and fusion-welded joint integrity. Australia's Murray-Darling irrigation modernization and India's Jal Jeevan Mission rural connectivity programs concentrate procurement volume.
- Chemicals:Acid transfer lines and process piping in sulfuric acid and caustic soda service exploit thermoplastic corrosion resistance.
- Mining:Heap leach solution distribution and tailings transport systems operate in remote, high-elevation sites.
Oil & Gas anchors revenue concentration. Water Supply is climbing the fastest as infrastructure replacement cycles synchronize with polymer cost competitiveness.
Installation Type:
Volume distribution skews toward below-ground burial for onshore gathering systems, while underwater deployment commands premium positioning through integrated vessel contracting.
- Below Ground:Direct burial with sand bedding and cathodic protection isolation dominates onshore oilfield gathering and water distribution networks. The Permian Basin and Bakken shale plays in the US deploy spoolable RTP for multi-well pad tiebacks eliminating corrosion mitigation costs.
- Underwater:Reel-lay vessel installation of continuous pipe strings from shore-based factories enables rapid subsea tieback deployment. Norway's Johan Sverdrup phase developments and Brazil's Buzios field expansions specify thermoplastic risers and flowlines with DNV-ST-F119 integrity monitoring.
- Above Ground:Elevated supports and pipe racks in processing facilities accommodate thermal expansion and inspection access.
- Onshore:Surface-laid configurations with concrete weight coating or anchor blocks traverse unstable terrain.
Below Ground holds the installed base. Underwater applications are expanding most quickly as deepwater economics favor spoolable systems over rigid steel.
Material:
Supply concentration in polyethylene resin production contrasts with polyamide's specialized polymerization requirements and import dependency in most manufacturing regions.
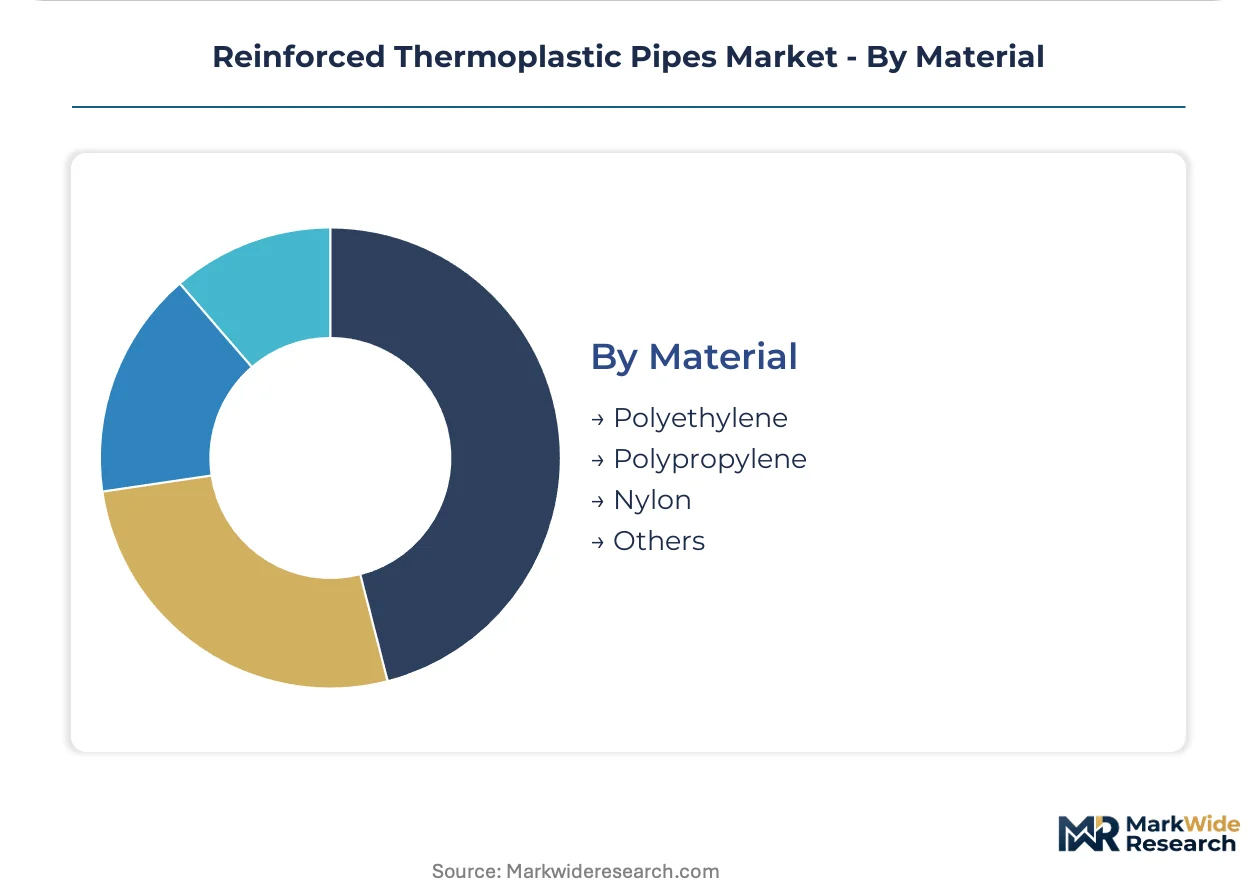
- Polyethylene:High-density and medium-density grades dominate water injection, sour service, and standard hydrocarbon gathering through proven fusion welding protocols and extensive supplier qualification. US Gulf Coast ethane feedstock advantages and Middle East integrated polyethylene complexes anchor global supply.
- Polyamide:PA11 and PA12 barrier layers block methane and hydrogen permeation at temperatures exceeding polyethylene limits, enabling high-pressure gas condensate service. Arkema's bio-based PA11 from castor oil feedstock and Evonik's PA12 production in Germany supply specialty resin for Middle East and North Sea gas developments.
- Polypropylene:Random copolymer grades offer elevated temperature resistance for geothermal and hot water applications.
- Others:PVDF and PEEK specialty polymers serve ultra-aggressive chemical and high-temperature niche requirements.
Polyethylene commands the established base. Polyamide is gaining share fastest as gas gathering temperature requirements rise and permeation regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Saudi Arabia demonstrate low price elasticity for high-pressure sour service systems, while municipal water authorities in India and Australia prioritize polyethylene cost competitiveness over performance premiums. This demand-elasticity contrast shapes divergent go-to-market strategies across geographies.
Brazil
Pre-salt basin tiebacks at Buzios and Mero fields drive procurement of API 15S-qualified flexible flowlines rated to 300 bar. ANP traceability protocols mandate material documentation from resin batch through installation. Rio de Janeiro's cluster of flexible pipe fabricators and reel-lay vessel operators coordinates integrated project delivery for Petrobras.
Saudi Arabia
High-pressure gas condensate developments in Ghawar and Jafurah fields deploy polyamide-lined systems for hydrogen sulfide service. Saudi Aramco technical specifications exceed ISO 14692 baseline requirements for permeation resistance. Eastern Province manufacturing complexes supply specialty resin and filament winding capacity for regional projects.
United States
Permian Basin multi-well pad tiebacks and Gulf of Mexico shallow-water rejuvenations consume spoolable polyethylene gathering lines. EPA methane regulations and FERC pipeline safety standards accelerate corrosion-resistant material substitution. Houston's subsea engineering corridor hosts integrated service contractors bundling pipe supply with offshore installation.
United Kingdom
North Sea decommissioning and brownfield retrofit programs replace aging steel jumpers with corrosion-resistant thermoplastic alternatives. EU Green Deal methane disclosure mandates and CSRD reporting requirements embed polymer selection criteria into engineering contracts. Aberdeen's subsea technology cluster concentrates integrity monitoring and reel-lay vessel operations.
India
Jal Jeevan Mission rural water connectivity and industrial cooling water systems procure medium-density polyethylene distribution networks. BIS certification protocols for plastic piping materials standardize fusion-welded joint specifications. Gujarat's petrochemical corridor and Maharashtra's infrastructure manufacturing belt anchor domestic extrusion and reinforcement capacity.
Reinforced Thermoplastic Pipes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated offshore contractors commanding premium positioning through bundled installation scope while specialized pipe fabricators compete on polyethylene resin efficiency and spool manufacturing scale. The market structures around three tiers: full-service subsea houses with captive vessel fleets, component specialists with proprietary connection systems, and regional extrusion houses serving onshore gathering and water infrastructure. Dominant competitive moves include integrated service contracting that compresses vendor lists, and capacity expansion in shore-based spool manufacturing to capture reel-lay deployment economics.
Among North American integrated service providers, Shawcor and Baker Hughes exemplify contrasting strategic positions. Shawcor anchors the full-service tier through bundled project awards combining pipe manufacturing with offshore installation. Baker Hughes occupies a technology-specialist position anchored by proprietary connection systems and downhole integration expertise. TechnipFMC represents the European-engineering heritage archetype, combining subsea project execution with thermoplastic manufacturing scale. These three players illustrate how competitive positioning fragments across service integration, technology ownership, and manufacturing scale vectors.
| Leading Market Players |
|---|
| Shawcor |
| Georg Fischer |
| Baker Hughes |
| Airborne Oil & Gas |
| Wienerberger |
| TechnipFMC |
| Prysmian Group |
| Polyflow |
| National Oilwell Varco (NOV) |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month DNV-ST-F119 qualification timelines concentrate supplier pricing power among certified incumbents while compressing margin capture for late entrants. This lead-time band shapes procurement patterns across Brazil's pre-salt developments and Middle East sour gas projects, where operators absorb premium positioning for documented integrity assurance.
Pricing Analysis
After-market integrity monitoring and recertification service contracts drive lifetime value capture for installed thermoplastic systems. Three-tier pricing structure across API 15S-qualified premium systems, standard polyethylene gathering lines, and economy-grade water infrastructure separates segments by certification depth and fiber reinforcement specification. Cost compression in standard-grade polyethylene lines intensifies as Gulf Coast resin capacity expands and Chinese extrusion houses enter export markets. Municipal water authorities in India and Australia exhibit highest price sensitivity, while offshore operators in Brazil and Saudi Arabia prioritize pressure rating and sour service compatibility over unit cost.
Supply Chain Analysis
Aramid fiber supply concentration across European and Japanese specialty producers creates a chokepoint exposing pipe manufacturers to allocation risk during aerospace demand surges. Manufacturing draws from Germany and France for high-tenacity reinforcement, Saudi Arabia and UAE for regional filament winding capacity, and the US Gulf Coast for polyethylene resin feedstock. Carbon fiber tow, polyamide barrier resins from Arkema's bio-based PA11 operations, and steel end-fitting forgings constitute critical input dependencies. Tariff exposure on Chinese-manufactured reinforcement fabrics compounds margin pressure. Distribution runs through shore-based spool manufacturing hubs serving reel-lay vessel operators in integrated project contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified electrofusion specialists and DNV-certified integrity engineers represent the scarcest capabilities in this market, constraining installation capacity expansion and creating bottlenecks for project execution timelines.
For Market Incumbents: Consolidate proprietary connection system portfolios through targeted certification investments in hydrogen transport barrier technologies, defending against steel pipe retrofit alternatives and emerging thermoset composite entrants. Capture backward integration into carbon fiber filament winding to secure reinforcement supply and compress cost structures in high-pressure sour service tiers. For New Entrants and Emerging Players: Anchor in UK North Sea decommissioning retrofit demand where aging steel infrastructure replacement creates procurement windows outside integrated Petrobras-style contracting. Target modular factory fabrication partnerships with regional reel-lay vessel operators as the most penetrable entry vector, leveraging shore-based spool manufacturing to bypass 18-month qualification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-replacement cycle play because corrosion-resistant tieback systems face sustained demand from brownfield integrity mandates and methane emission regulations. Acquisition targets should exhibit captive PA11/PA12 barrier layer technology or integrated reel-lay vessel access. Watch hydrogen blending infrastructure pilot projects as the signal indicating polyamide-lined system demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API 15S Certification Investment | Accelerates supplier onboarding for US hydrocarbon service and mid-scale producer procurement. |
| Backward Integration into Carbon Fiber | Reduces transport weight and mitigates aramid supply concentration risk in high-pressure tiers. |
| Modular Factory Fabrication Partnership | Compresses project schedules versus field welding through shore-based spool manufacturing. |
| Hydrogen Barrier Layer Development | Opens pipeline repurposing opportunities as EU Green Deal methane regulations tighten. |
| Integrated Reel-Lay Vessel Contracting | Captures bundled project awards in Brazil's pre-salt basin and North Sea decommissioning wave. |
Study Parameters
A standing panel of subsea project engineers, polymer welding technicians, reel-lay vessel operators, and ANP regulatory compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from API 15S qualification records, ISO 14692 harmonization documentation, DNV-ST-F119 test protocols, and Petrobras technical specifications. Bottom-up meterage demand modeling and top-down resin consumption analysis triangulated volume estimates.
Consistency checks against external benchmarks validated outputs across the projection horizon. Segmentation modeling captured product type, material platform, installation configuration, and end-use industry tier. CAGRs derived from weighted average of historical deployment trajectories and project pipeline visibility. Forecast inputs included subsea tieback economics, polymer recycling mandate timelines, and hydrogen infrastructure pilot progress.
Decision-makers should treat outputs as directional under sustained oil price assumptions supporting pre-salt development economics; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ANP traceability protocol revisions and EU methane emission enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Global Titanium Tube Market