
 Global Polyethylene Pipes and Fittings Market | 2026-2036
Global Polyethylene Pipes and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyethylene Pipes and Fittings Market Foresight
A chronic shortage of certified fusion-welding technicians is unwinding project timelines across the polyethylene piping supply chain. JM Eagle leverages vertical integration from resin compounding through extrusion to buffer labor constraints across North American infrastructure bids. China Lesso Group Holdings Limited anchors its position through captive HDPE resin sourcing and massive extrusion scale across Guangdong and Guizhou facilities. Aliaxis competes through a distributed manufacturing footprint that reduces dependence on any single labor pool.
Polyethylene pipes and fittings comprise thermoplastic conduit systems extruded from high-density, medium-density, or low-density polyethylene resins, typically specified by ASTM D3035 or ISO 4427 dimensional standards, with fusion-welded or mechanical joint configurations designed to transport pressurized fluids, gases, or protect electrical cabling across buried, above-ground, or trenchless installations. HDPE pipes dominate municipal water supply and gas distribution applications due to superior stress-crack resistance and leak-free fusion joints, while PE fittings command margin pools through proprietary electrofusion socket technology and custom fabrication services. LDPE pipes retain niche positions in low-pressure agricultural drip and sprinkler irrigation where flexibility and cost minimization outweigh pressure ratings.
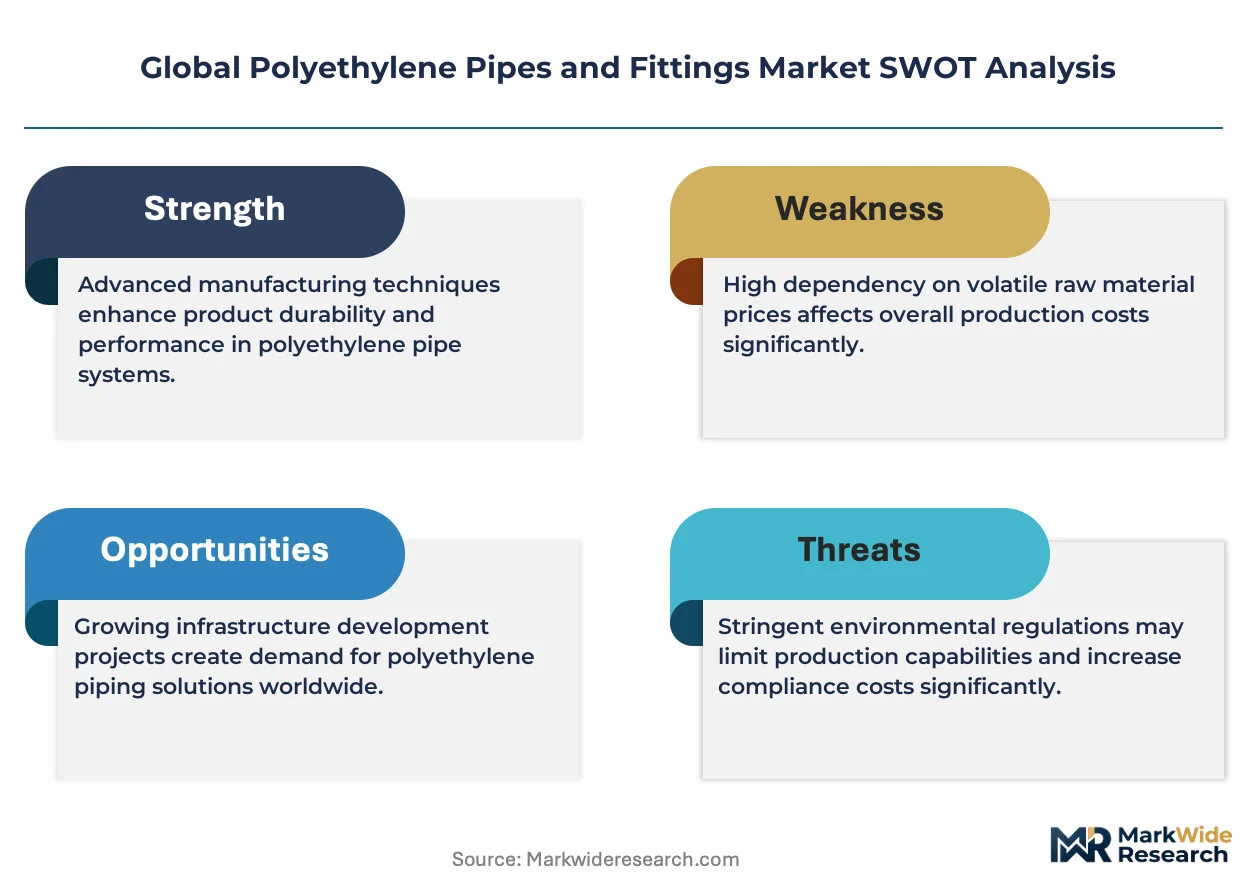
The US EPA's Lead and Copper Rule revisions and India's BIS certification requirements for plastic piping under IS 4984 are tightening material traceability and joint integrity standards, forcing resin upgrades and third-party testing investments. Europe's REACH regulation and F-Gas Regulation indirectly shape polyethylene demand by restricting competing material systems and accelerating polymer-based alternatives in HVAC and refrigeration piping networks. Stakeholders must monitor regulatory divergence between ASTM and ISO testing protocols, as specification fragmentation threatens interoperability and cross-border project qualification.
Market Dynamics
Fusion-welding technician scarcity is compressing project timelines across municipal water and gas distribution networks, forcing contractors to absorb premium labor costs or delay commissioning schedules.
Growth Catalysts
- India's BIS certification under IS 4984:Mandatory third-party testing for plastic piping is accelerating material-grade upgrades and displacing unorganized suppliers from government irrigation tenders.
- Urban gas distribution buildouts:India's City Gas Distribution networks are specifying HDPE for medium-pressure polyethylene pipelines, creating sustained demand for electrofusion fittings and saddle tapping equipment.
- REACH compliance in Europe:ECHA restrictions on competing material systems are redirecting HVAC and refrigeration piping specifications toward polymer-based alternatives.
Market Restraints
- HDPE resin price volatility:Ethylene feedstock fluctuations and naphtha-cracker operating rates in the Middle East transmit directly to pipe extrusion margins.
- Certified welder supply concentration:North American infrastructure bids face 12-18 month lead times for qualified butt-fusion and electrofusion technicians.
- Cross-linked polyethylene (PEX) substitution:Residential plumbing segments in North America are specifying PEX for hot-water distribution, compressing LDPE demand in building construction.
Strategic Opportunities
- Vietnam's Mekong Delta irrigation modernization:Government-funded drip and sprinkler conversions specify PE laterals and micro-tubes for rice-paddy water efficiency programs.
- Smart pigging integration:HDPE gas distribution networks are embedding RFID tags and fiber-optic sensing cables during fusion welding for real-time leak detection.
- China's dual carbon goals:MEE mandates for buried utility networks favor corrosion-resistant polyethylene over ductile iron in new municipal water specifications.
Industry Challenges
- Fusion technician certification bottlenecks:AWS and ISO 21307 qualification programs cannot scale to match India's PM-Gati Shakti infrastructure timelines.
- ASTM-ISO protocol divergence:Specification fragmentation threatens interoperability for multinational EPC contractors bidding cross-border water transmission projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyethylene Pipes and Fittings Market |
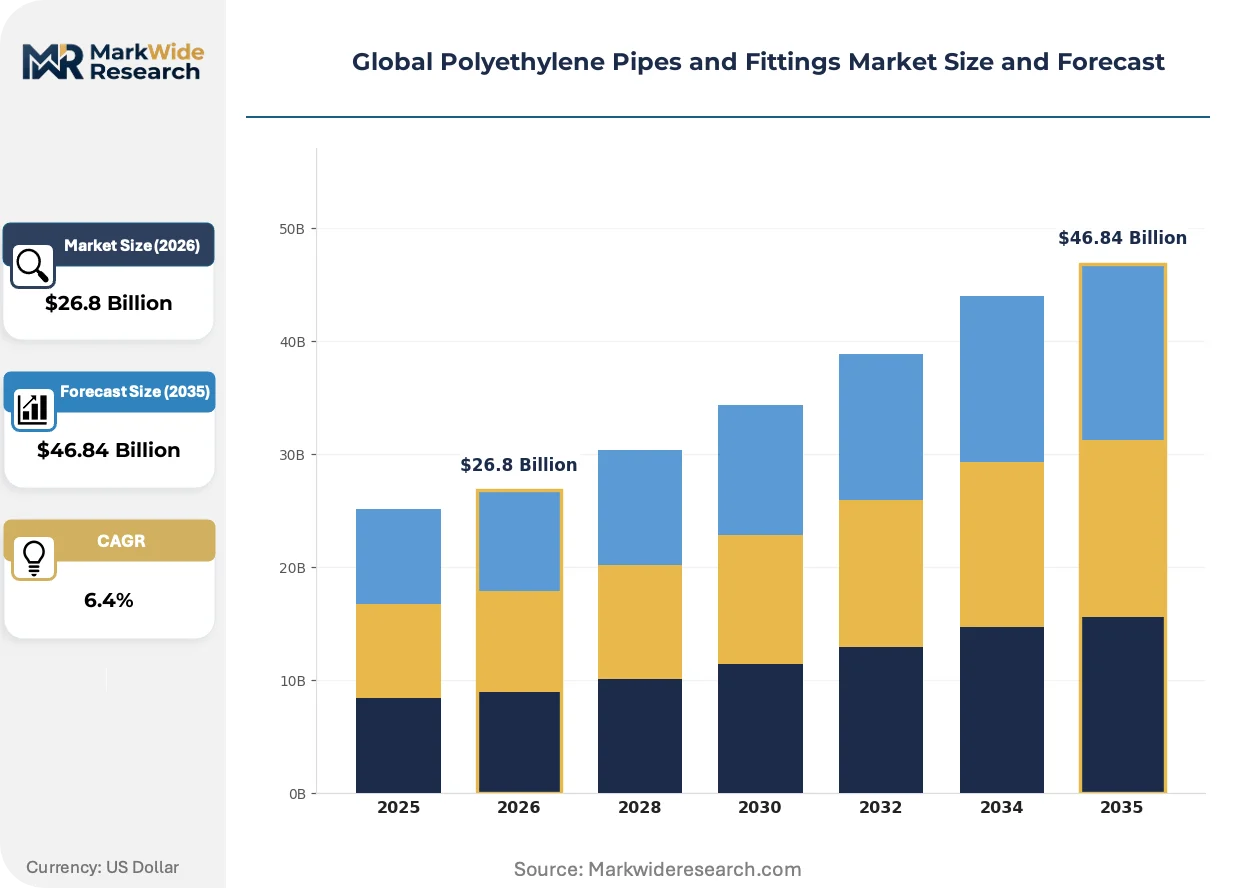
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE Pipes, MDPE Pipes, LDPE Pipes, PE Fittings Application: Water Supply, Gas Distribution, Irrigation Systems, Electrical Conduits Installation Type: Buried, Above Ground, Underwater, Trenchless End User Industry: Construction, Agriculture, Utilities, Telecommunications |
| Companies Covered | JM Eagle, Aliaxis, China Lesso Group Holdings Limited, Chevron Phillips Chemical Company, WL Plastics, Advanced Drainage Systems, Wavin, Jain Irrigation Systems, Pipelife International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyethylene Pipes and Fittings Market Shifts & Advancements
Material science advances and regulatory tightening are converging to reshape specification standards across water, gas, and agricultural distribution networks.
Co-extruded multilayer HDPE pipe with embedded aluminum or fiberglass reinforcement layers is miniaturizing wall thickness requirements for equivalent pressure ratings. Municipal utilities in Germany and the Netherlands are specifying these composite structures for directional drilling beneath urban roadways. The technology is compressing trenchless installation costs and reducing fusion joint counts per kilometer.
REACH Annex XVII restrictions on lead stabilizers in PVC compounding are redirecting potable water specifications toward PE100 and PE100-RC resins across EU member states. ECHA substance evaluations are accelerating polymer substitution in building services piping. French and Italian municipal water authorities are now mandating polyethylene for all buried distribution renewals.
Integrated service contracts bundling pipe supply with fusion-welding crews and digital-as-built documentation are displacing traditional material-only procurement in Australian and Canadian infrastructure tenders. EPC contractors are accepting total-installation liability in exchange for specification control. This model concentrates most visibly in urban gas distribution buildouts where joint integrity guarantees determine operator licensing.
Global Polyethylene Pipes and Fittings Market Segmentation
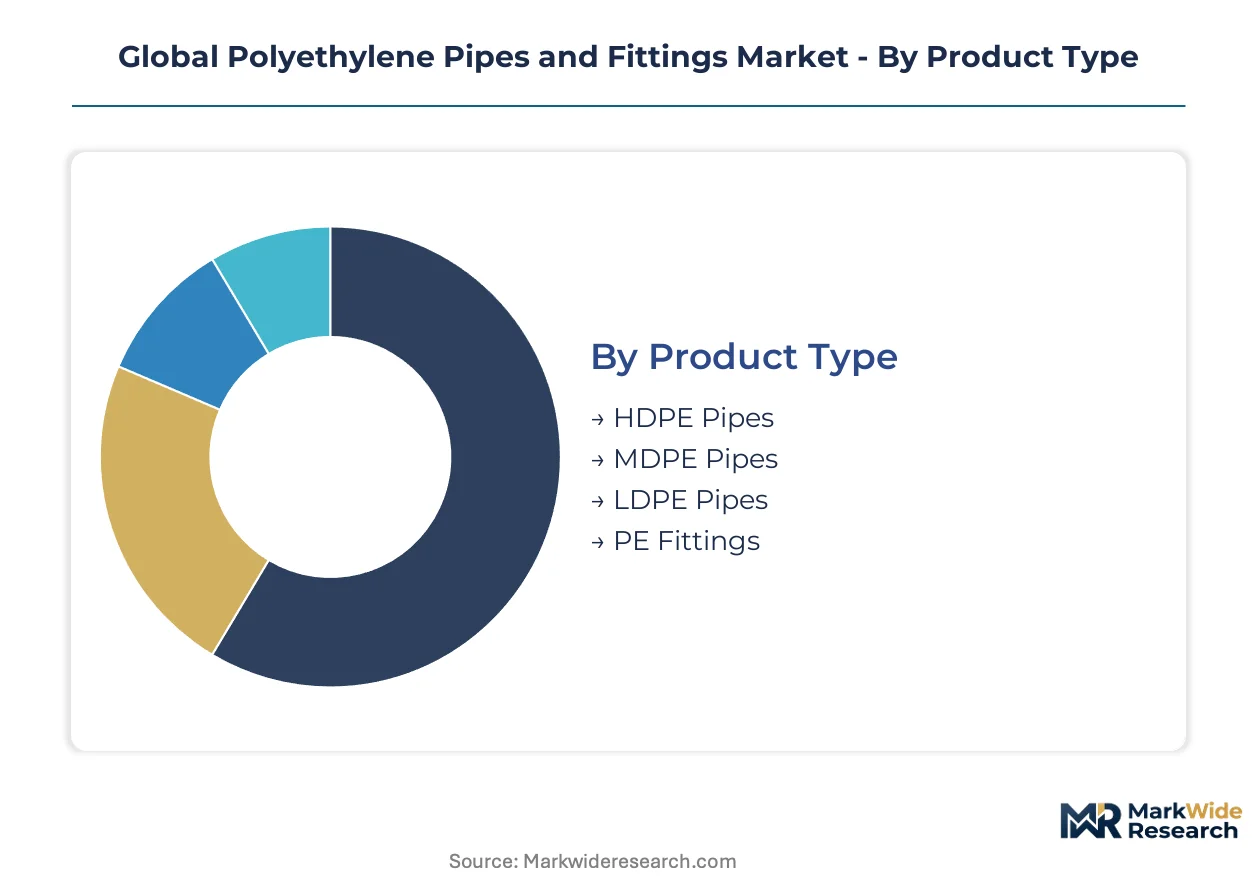
Segmentation in polyethylene piping reveals how resin grade, pressure rating, and joint technology determine project economics. Specification choices cascade through installation methods, regulatory compliance, and lifecycle cost calculations for municipal and industrial buyers.
Product Type:
Margin pools concentrate in fittings and high-performance resins where proprietary electrofusion technology commands premium pricing over commodity pipe extrusion.
- HDPE Pipes:Extruded from PE100 or PE100-RC resins per ISO 4427, these pipes deliver stress-crack resistance and leak-free butt-fusion joints for pressurized applications. Municipal water utilities in Germany and India's City Gas Distribution networks specify HDPE for medium-pressure transmission, with REACH compliance in Europe accelerating displacement of legacy materials.
- PE Fittings:Electrofusion sockets, saddles, and fabricated segments incorporate embedded heating coils and barcode traceability for joint integrity verification. Custom fabrication services and proprietary socket designs capture margin premiums in urban gas buildouts where third-party testing under BIS IS 4984 is mandatory.
- MDPE Pipes:PE80 resin formulations balance flexibility and pressure ratings for low-pressure gas distribution and rural water schemes.
- LDPE Pipes:Low-density formulations serve agricultural drip irrigation and electrical conduit where cost minimization outweighs mechanical strength requirements.
HDPE pipes hold installed capacity across municipal infrastructure. PE fittings are rotating up the share rankings through bundled installation contracts.
Application:
Volume concentrates in water and gas utilities where regulatory tightening and network expansion drive specification upgrades.
- Water Supply:Buried distribution networks and transmission mains specify HDPE for corrosion resistance and trenchless installation compatibility. The US EPA's Lead and Copper Rule revisions and China's MEE mandates for buried utilities are redirecting specifications from ductile iron toward polyethylene across municipal procurement.
- Gas Distribution:Medium-pressure polyethylene pipelines with electrofusion jointing dominate India's City Gas Distribution buildouts and European network renewals. Smart pigging integration with RFID tags and fiber-optic sensing is embedding digital monitoring capabilities during fusion welding.
- Irrigation Systems:Government-funded modernization in Vietnam's Mekong Delta and India's PM-Gati Shakti programs specify PE laterals for rice-paddy water efficiency.
- Electrical Conduits:HDPE and MDPE protect cabling for telecommunications and power distribution in buried and trenchless installations.
Water supply commands the largest existing footprint. Gas distribution is climbing the fastest as urbanization accelerates pipeline density targets.
Installation Type:
Cost structure and labor intensity diverge sharply between open-cut burial and trenchless methods requiring specialized equipment.
- Buried:Open-cut trenching remains standard for municipal water and gas distribution in greenfield developments across India and Southeast Asia.
- Trenchless:Directional drilling and pipe bursting with co-extruded multilayer HDPE minimize surface disruption in German and Dutch urban renewals.
- Above Ground:Surface-mounted installations serve temporary construction supply and industrial process piping.
- Underwater:Weighted ballast and anchoring systems adapt polyethylene for outfall pipelines and crossing applications.
Buried installation holds the dominant share of project volume. Trenchless methods are gaining share fastest where urban surface restoration costs dominate economics.
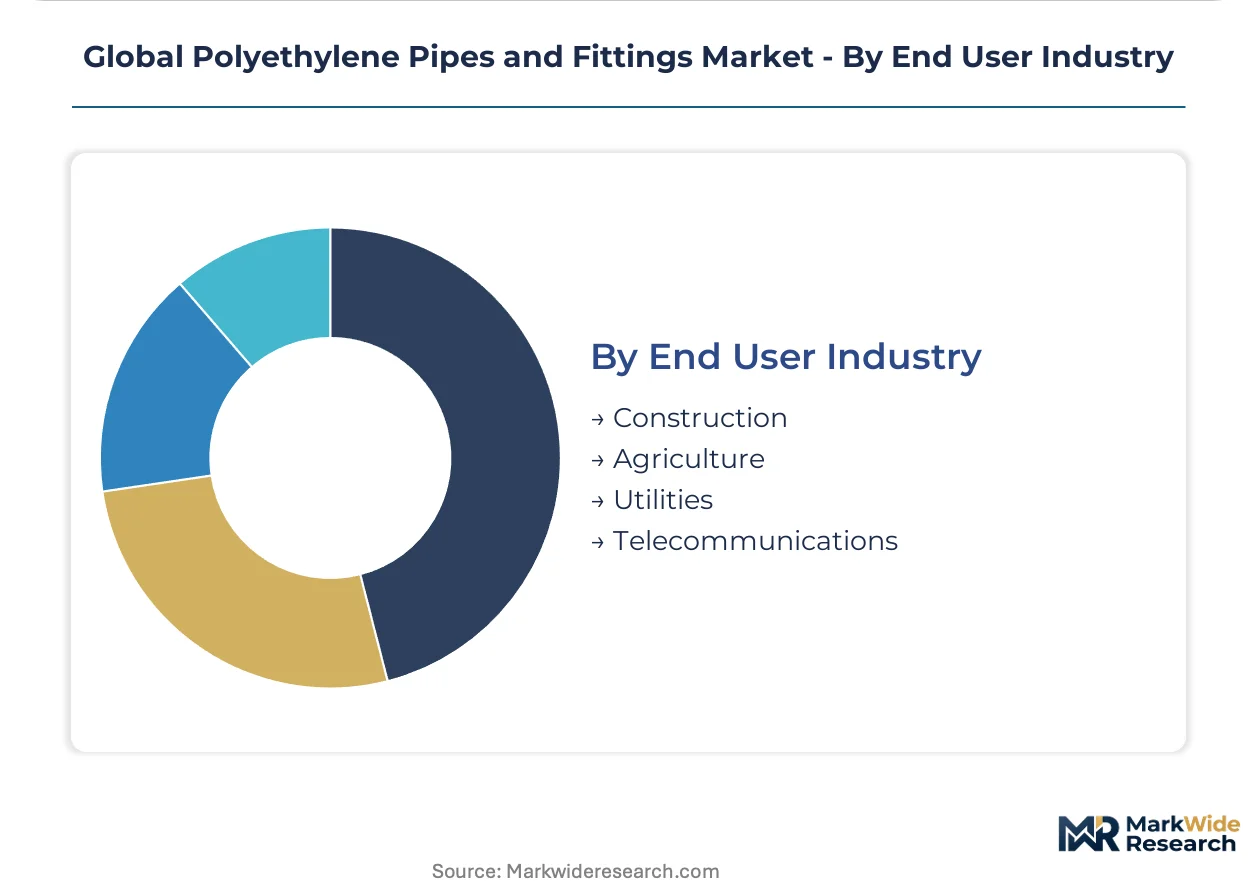
End User Industry:
Procurement patterns split between municipal utility specifications with extended compliance timelines and agricultural buyers prioritizing delivered cost.
- Utilities:Municipal water and gas operators specify certified fusion-welded systems with digital-as-built documentation. Australia's integrated service contracts bundle material supply with installation crews and joint integrity guarantees.
- Agriculture:Drip and sprinkler conversions in Vietnam and India specify LDPE and MDPE laterals where flexibility and cost minimization outweigh pressure ratings.
- Construction:Building services and temporary site infrastructure drive demand for above-ground and conduit applications.
- Telecommunications:Fiber-optic cable protection specifies HDPE ducts with pull-through capacity for network densification.
Utilities anchor the revenue base through multi-year infrastructure programs. Agriculture is expanding most quickly through government-funded irrigation modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian contractors command 15-20% pricing premiums over Vietnamese peers for equivalent HDPE specifications, reflecting tighter certified welder availability and BIS compliance overhead. German utilities absorb the highest installed costs in Europe due to REACH-mandated resin upgrades and trenchless installation requirements. Chinese manufacturers leverage captive ethylene supply and GB standard harmonization to undercut export benchmarks across Southeast Asian tenders.
United States
City Gas Distribution buildouts and EPA Lead and Copper Rule revisions are accelerating HDPE displacement of legacy ductile iron in municipal water renewals. AWS-certified fusion technician shortages stretch project timelines 12-18 months across Midwest and Southwest infrastructure bids. Houston and Dallas-Fort Worth anchor extrusion capacity serving Permian Basin oilfield gathering lines and urban gas distribution networks.
India
PM-Gati Shakti irrigation corridors and City Gas Distribution mandates under PNGRB are specifying PE100-RC resins for medium-pressure transmission networks. BIS IS 4984 third-party testing requirements are consolidating supply around organized manufacturers with in-house certification laboratories. Gujarat and Maharashtra industrial clusters concentrate extrusion capacity serving Delhi-Mumbai Industrial Corridor water transmission projects.
Germany
REACH Annex XVII restrictions on lead-stabilized PVC are redirecting potable water specifications toward PE100 resins across municipal procurement frameworks. Co-extruded multilayer HDPE with fiberglass reinforcement is miniaturizing wall thickness for directional drilling beneath Rhine-Ruhr urban corridors. The Netherlands and Belgium import German extrusion technology for their own trenchless renewal programs.
China
MEE mandates for corrosion-resistant buried utilities and dual carbon goals are favoring polyethylene over ductile iron in new municipal water specifications. Captive HDPE resin sourcing through integrated petrochemical complexes compresses extrusion margins versus import-dependent competitors. Guangdong and Guizhou manufacturing bases supply domestic City Gas Distribution buildouts and Belt and Road export tenders across Southeast Asia.
Vietnam
Mekong Delta irrigation modernization programs specify LDPE laterals and micro-tubes for rice-paddy water efficiency conversions funded by government rural development budgets. Lower labor costs and relaxed certification requirements attract Chinese extrusion investment for re-export to ASEAN markets. Ho Chi Minh City industrial zones concentrate pipe fabrication serving delta agricultural districts and emerging urban gas distribution pilots.
Global Polyethylene Pipes and Fittings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Resin compounders with captive ethylene supply anchor the cost vector, while electrofusion specialists command premium positioning through proprietary socket designs and joint integrity guarantees. The market fragments across three strategic archetypes: integrated petrochemical-to-pipe conglomerates, regional extrusion specialists with distributed manufacturing footprints, and installation-contracting bundlers accepting total-project liability. Dominant competitive moves include backward integration into resin compounding and geographic expansion through acquisition of regional extrusion assets.
Among North American infrastructure suppliers, JM Eagle exemplifies scale-driven vertical consolidation from resin through extrusion. European fitting specialists Aliaxis and Pipelife International occupy positions anchored by distributed manufacturing footprints that reduce dependence on single labor pools. China Lesso Group Holdings Limited represents the integrated conglomerate archetype with captive HDPE sourcing and massive extrusion scale across southern Chinese industrial bases. These three patterns illustrate how competitive positioning diverges across technology, cost, and geographic coverage vectors.
| Leading Market Players |
|---|
| JM Eagle |
| Aliaxis |
| China Lesso Group Holdings Limited |
| Chevron Phillips Chemical Company |
| WL Plastics |
| Advanced Drainage Systems |
| Wavin |
| Jain Irrigation Systems |
| Pipelife International |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month lead times for AWS-certified fusion technicians compress contractor bidding flexibility and amplify pricing power for organized manufacturers with captive welding crews. This scarcity dynamic concentrates margin capture among resin-integrated extruders while forcing project delays that inflate total installed costs across municipal infrastructure programs.
Pricing Analysis
Configured-to-order electrofusion fittings command 35-50% premiums over standard butt-fusion pipe segments due to embedded heating coil complexity and barcode traceability systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by PE100-RC resin grade, BIS IS 4984 certification tier, and bundled installation liability. Price differentiation intensifies as Indian PM-Gati Shakti deadlines compress contractor procurement timelines. Agricultural buyers in Vietnam's Mekong Delta exhibit highest price sensitivity, while European municipal utilities under REACH mandates absorb premium resin costs with limited negotiation leverage.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes ethylene feedstock flows from Middle Eastern naphtha crackers to Chinese Guangdong extrusion complexes. Manufacturing gravity centers on China, India, and Germany, with each node drawing from distinct ethylene supply configurations. Raw material dependencies encompass HDPE resin pellets, electrofusion coil assemblies, and PE100-RC compound additives. Single-source vulnerability concentrates in certified fusion-welding technician pools across North American infrastructure markets. Distribution runs through project-specific EPC contractors rather than stocked merchant distribution, tying inventory directly to municipal tender award cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified fusion-welding technician availability functions as the binding constraint across project execution timelines, privileging manufacturers with verticalized installation capabilities over pure-play extruders.
For Market Incumbents: Compound defensive positioning through backward integration into resin compounding and acquisition of regional extrusion assets with established BIS certification laboratories. PEX substitution in North American residential plumbing threatens LDPE demand, requiring capacity reallocation toward PE100-RC municipal specifications. Joint integrity guarantee capabilities represent the critical lever for urban gas distribution licensing. For New Entrants and Emerging Players: Digital-as-built documentation bundling presents a service-layer gap where incumbents under-serve Australian and Canadian infrastructure tenders. White-space targets concentrate in Vietnam's Mekong Delta irrigation modernization and India's secondary City Gas Distribution geographies outside Gujarat-Maharashtra clusters. A rental-model approach for electrofusion welding equipment penetrates price-sensitive agricultural segments without capital-intensive extrusion investment. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates seeking to monetize non-core pipe extrusion divisions amid ethylene margin volatility. Long-term viability favors integrated resin-to-installation platforms over commodity extrusion specialists exposed to naphtha-cracker operating rate swings. The inflection signal to monitor is BIS IS 4984 laboratory accreditation timelines, which determine qualification for government irrigation tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene supply buffers Middle Eastern naphtha price volatility for Chinese and Indian extruders. |
| Electrofusion Technology Licensing | Proprietary socket designs command margin premiums in India's PNGRB-mandated urban gas buildouts. |
| Certified Welder Training Program Scale-Up | AWS and ISO 21307 qualification pipelines determine project execution capacity across North American bids. |
| Trenchless Installation Equipment Partnerships | Co-extruded multilayer HDPE compatibility with directional drilling opens German and Dutch urban renewal markets. |
| RFID-Enabled Smart Pigging Integration | Embedded fiber-optic sensing during fusion welding supports real-time leak detection in European gas networks. |
Research Methodology
The analysis maps HDPE pipe extrusion, PE fitting fabrication, MDPE/LDPE commodity segments, and installation contracting services, each validated through plant managers at integrated petrochemical complexes, procurement leads at municipal water utilities, EPC contractors bidding cross-border transmission projects, and distribution channel partners across Southeast Asian markets. Primary interview insights triangulate against customs and trade data from Indian DGFT and Chinese customs authorities, SEC 10-K filings from listed manufacturers, BIS certification registries, and REACH Annex XVII substance restriction notifications. Bottom-up project pipeline enumeration cross-references top-down resin consumption estimates from petrochemical industry associations.
Consistency checks against external benchmarks validate volume and value outputs across the analysis window. The analytical framework models resin grade tier, pressure rating class, joint technology type, application end-use, and regional regulatory cluster dimensions. CAGRs derive from ethylene feedstock cost trajectories, municipal infrastructure budget appropriations, and City Gas Distribution pipeline kilometer targets. Industry-specific forecast inputs incorporate PM-Gati Shakti irrigation corridor timelines and PNGRB authorization tranches.
Material uncertainties — ethylene price volatility, fusion technician certification bottlenecks, ASTM-ISO protocol divergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement intensity and infrastructure budget continuity. Practitioners should keep alternative scenarios live as REACH substance evaluations and BIS laboratory accreditation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Copper Tube Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Global Fluoropolymer Tubing Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market