
 Tanktwo String Cell Battery Market | 2026-2036
Tanktwo String Cell Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Tanktwo String Cell Battery Market Analytics
Electric vehicle application demand is decoupling from traditional pack architectures as fleet operators seek modular replacement economics. TankTwo specializes in string cell configurations that enable single-element swap-out without full pack decommissioning. Panasonic Corporation leverages its cylindrical cell expertise to compete in adjacent modular formats. LG Energy Solution anchors its position through advanced chemistry portfolios that complement decentralized battery management.
The Tanktwo String Cell Battery employs electrochemical cells arranged in serial strings with individual fuse protection and contactless communication, enabling replacement of failed units without interrupting overall pack voltage. Its primary purpose centers on reducing total cost of ownership for high-utilization electric vehicle fleets through field-serviceable architectures. Solid-state chemistry segments attract premium positioning due to energy density advantages in weight-sensitive deployments. Electric vehicle applications dominate volume absorption while grid storage segments offer longer contract visibility. Modular design technology leads differentiation as manufacturers seek to separate hardware from software upgrade cycles.
The EPA enforces battery recycling standards that elevate end-of-life compliance costs for sealed pack designs. The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that favor serviceable architectures with traceable cell lineages. NHTSA safety protocols for propulsion battery systems influence crashworthiness testing requirements that string configurations must satisfy. Stakeholders should monitor regulatory divergence between jurisdictions as modular designs face divergent certification pathways across major automotive markets.
Market Dynamics
Modular battery architectures are decoupling hardware lifecycles from vehicle depreciation schedules, forcing a structural renegotiation of fleet asset management economics. This shift privileges field-serviceable electrochemical systems over sealed pack designs.
Growth Catalysts
- Fleet operator TCO pressure:High-utilization electric vehicle operators in Germany and the Netherlands are piloting string cell configurations to minimize downtime from single-cell failures.
- EU Battery Regulation traceability mandates:Carbon footprint disclosure requirements and recycled content thresholds favor architectures with documented cell lineage and replaceable elements.
- Contactless battery management communication:Inductive data transmission between serial string elements eliminates wiring harness complexity and enables hot-swappable module designs.
Market Restraints
- Lithium supply concentration:Cathode active material dependency on Chilean and Australian spodumene concentrates creates input cost volatility for cell manufacturers.
- NHTSA crashworthiness certification:String cell fuse protection systems must demonstrate thermal runaway containment under propulsion battery safety protocols, extending validation timelines.
- Solid-state chemistry substitution:Next-generation solid-state cells with embedded cell-level protection threaten to obsolete external fuse architectures in premium applications.
Strategic Opportunities
- Commercial transport electrification in Poland:Bus and delivery van fleet operators represent underpenetrated demand for modular replacement economics outside German automotive clusters.
- Grid storage second-life applications:Retired string cells from automotive fleets can redeploy into stationary energy storage with verified state-of-health data from original service records.
- Service contract unbundling:Battery-as-a-service models separate hardware ownership from energy provision, creating recurring revenue streams for modular system operators.
Industry Challenges
- Cell balancing algorithm expertise:Distributed battery management systems require firmware engineers with specialized knowledge of electrochemical state estimation at the string level.
- ISO 26262 functional safety certification:Automotive-grade ASIL-D compliance for contactless communication protocols demands substantial validation investment and third-party audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanktwo String Cell Battery Market |
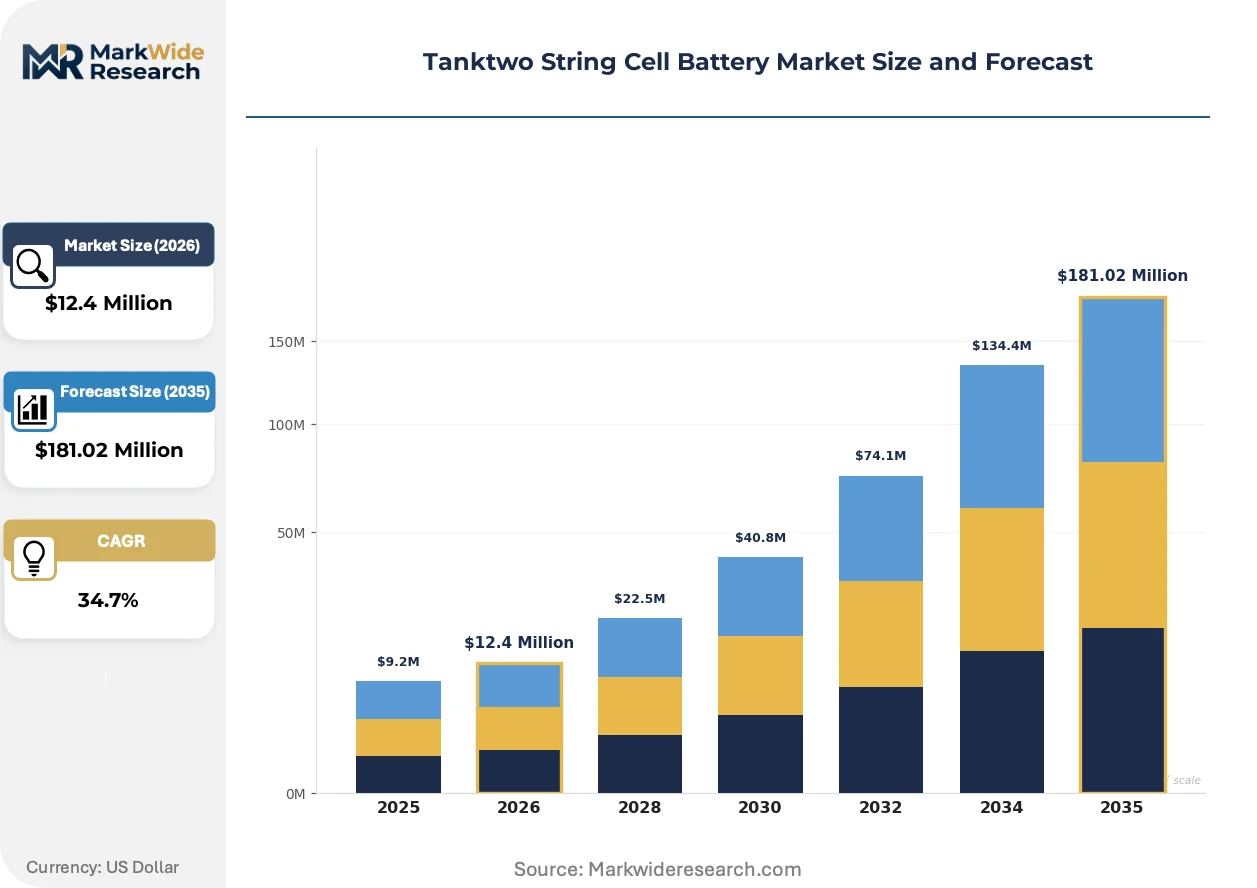
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $181.02 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Application: Electric Vehicles, Renewable Energy, Consumer Electronics, Grid Storage End User: Manufacturers, Retailers, Government, Utilities Technology: Advanced Chemistry, Modular Design, Smart Energy Management, Recycling Technologies |
| Companies Covered | TankTwo, Tesla, Inc., Panasonic Corporation, LG Energy Solution, Samsung SDI, BYD Company Ltd., CATL, QuantumScape Corporation, Solid Power Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanktwo String Cell Battery Market Evolving Landscape
Contactless power and data transmission is dissolving the mechanical constraints that historically locked battery cells into fixed pack geometries. This electromagnetic decoupling enables granular modularity without the wear-prone connectors that plague conventional architectures.
Solid-state cell formats with integrated protection electronics are electrifying the premium segment of electric vehicle battery design. BMW and Mercedes-Benz commercial transport divisions are evaluating these configurations for weight-sensitive long-haul applications. The technology is compressing the performance gap between modular string architectures and sealed high-density packs.
The EU Battery Regulation's carbon footprint disclosure mandate is forcing supply chain documentation investments across European cell assembly operations. Industrial consequence includes preferential procurement scoring for batteries with verified recycled content and traceable manufacturing energy sources. German commercial vehicle OEMs are responding by requiring cell-level provenance data from Tier 1 suppliers.
Fleet procurement departments are unbundling battery hardware from vehicle chassis purchases in favor of separate lease or service agreements. Traditional OEM captive finance structures face disruption from independent battery asset managers offering usage-based contracts. This pattern is most visible in Dutch and Belgian urban delivery fleets where vehicle utilization rates exceed 18 hours daily.
Tanktwo String Cell Battery Market Segmentation
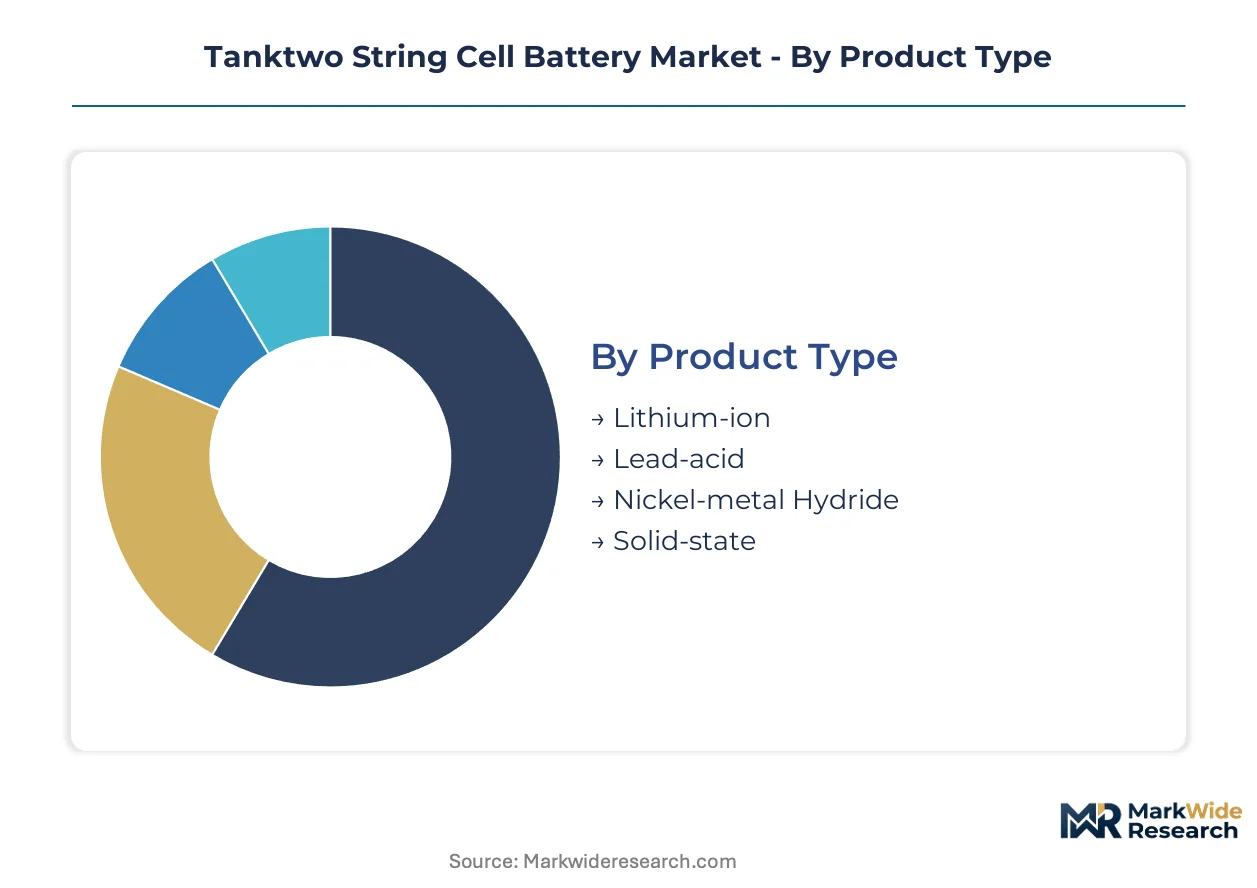
Segmentation in string cell batteries reveals how modular architectures reshape procurement patterns across electrochemical systems. Product chemistry and application context determine whether field-serviceability justifies premium positioning over sealed pack economics.
Product Type:
Standardized cell formats dominate volume manufacturing while solid-state variants command customization premiums in weight-sensitive deployments.
- Lithium-ion:Cylindrical and prismatic cells with liquid electrolyte formulations remain the workhorse chemistry for commercial transport electrification. German bus fleet operators specify these configurations for their established supply chains and replacement part availability.
- Solid-state:Ceramic or sulfide electrolyte architectures eliminate thermal runaway risks and enable thinner cell geometries. BMW's commercial transport division evaluates these for long-haul electric trucks where energy density directly translates to payload capacity.
- Lead-acid:Mature flooded and AGM formats persist in backup power and cost-constrained fleet conversions.
- Nickel-metal Hydride:Rare-earth hydride cathode systems occupy niche hybrid vehicle refurbishment markets.
Most installed capacity flows through lithium-ion formats. Expansion is steepest in solid-state as automotive OEMs validate manufacturing scalability.
Application:
Utilization intensity separates applications where modular replacement economics justify upfront premiums from those tolerating sealed pack obsolescence.
- Electric Vehicles:High-mileage commercial fleets in the Netherlands and Belgium deploy string cells to minimize downtime from single-cell degradation. Daily utilization exceeding 18 hours makes field-serviceability a decisive TCO factor.
- Grid Storage:Utility-scale installations prioritize contract visibility over hardware flexibility, though second-life automotive cell redeployment creates hybrid procurement models.
- Renewable Energy:Solar and wind pairing applications favor proven lithium-ion reliability over modular complexity.
- Consumer Electronics:Sealed pack integration and miniaturization requirements exclude string architectures from smartphones and laptops.
Electric vehicle applications absorb the majority of production volume. Grid storage contracts deliver the longest revenue visibility.
End User:
Procurement sophistication varies sharply between asset owners seeking lifecycle cost control and intermediaries prioritizing transaction velocity.
- Manufacturers:Automotive OEMs and Tier 1 suppliers integrate string cells into chassis designs with dedicated service bay configurations.
- Utilities:Grid operators specify modular formats for degradation-matched capacity augmentation without full system replacement.
- Government:Municipal transit authorities in Poland and the Czech Republic pilot string cell buses under EU Green Deal procurement guidelines.
- Retailers:Independent battery asset managers lease hardware to fleet operators under usage-based service contracts.
Manufacturers command the largest contract values. Retailers are expanding most quickly as battery-as-a-service models proliferate.
Technology:
Hardware-software separation determines whether upgrade cycles decouple from physical cell replacement.
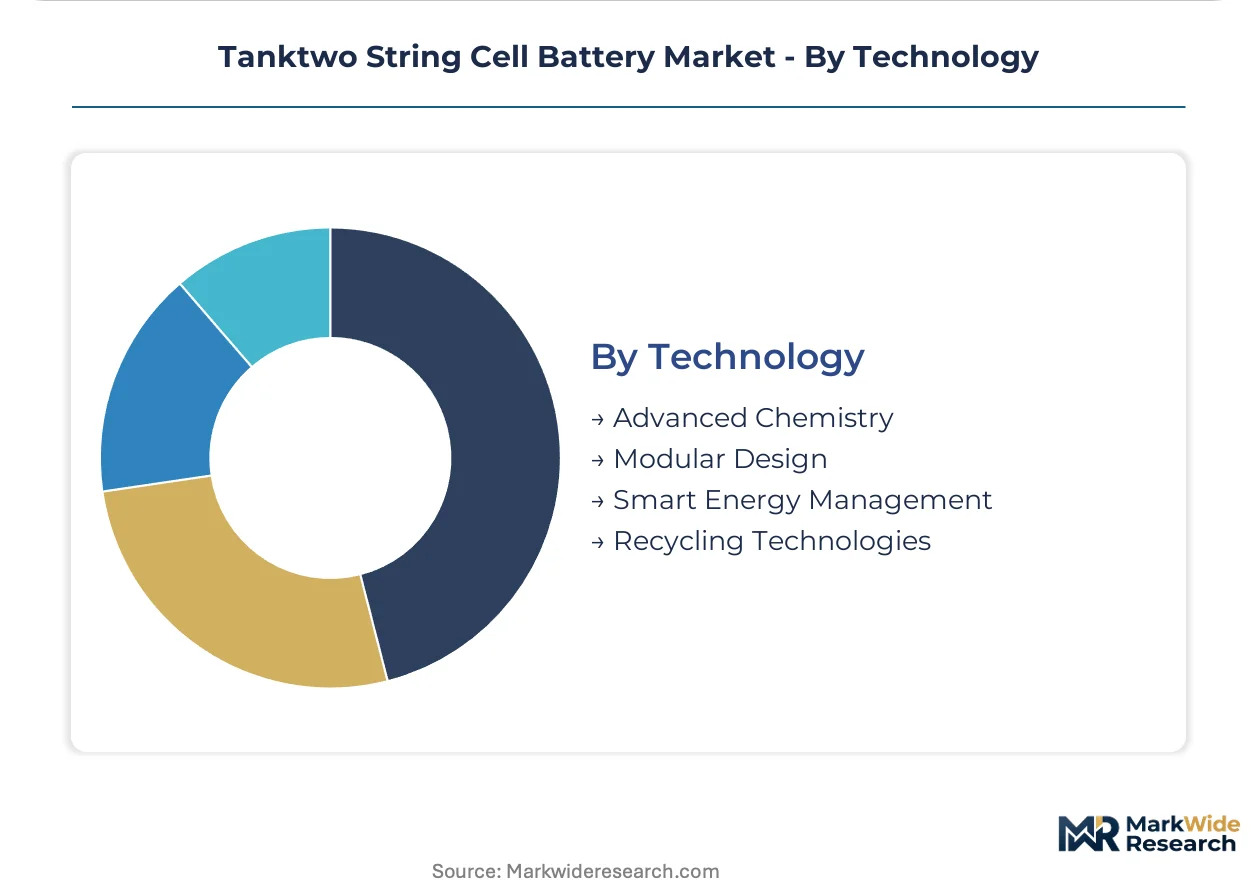
- Modular Design:Serial string configurations with individual fuse protection and contactless communication enable hot-swappable element replacement. TankTwo's architecture exemplifies this approach for high-availability fleet operations.
- Smart Energy Management:Distributed battery management systems with inductive data transmission between string elements eliminate wiring harness failure modes.
- Advanced Chemistry:Silicon-anode and high-nickel cathode formulations push energy density boundaries in premium applications.
- Recycling Technologies:Cell-level traceability systems support EU Battery Regulation compliance through documented provenance and state-of-health verification.
Modular design technology anchors current deployments. Smart energy management systems are gaining share fastest as firmware differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is steering cell assembly investments toward jurisdictions where EU Battery Regulation compliance costs less than the premium commanded by traceable architectures. German automotive clusters absorb the highest certification investment while Polish and Czech operations capture margin from delegated production.
Germany
Commercial transport electrification drives string cell pilot programs at Daimler Truck and MAN bus divisions. KBA crashworthiness protocols mandate extended thermal runaway containment validation for modular fuse architectures. The Stuttgart and Munich metropolitan corridors concentrate Tier 1 supplier engineering centers developing contactless battery management systems.
Netherlands
Urban delivery fleets operating 18-plus hour daily cycles prioritize field-serviceable configurations to minimize downtime degradation. The national environmental agency enforces carbon footprint disclosure thresholds that favor batteries with documented cell lineage. Rotterdam and Eindhoven logistics hubs host independent battery asset managers leasing modular hardware under usage-based contracts.
Poland
Municipal transit authorities pilot string cell bus deployments under EU Green Deal procurement guidelines with co-financing from the national environmental fund. The country's national automotive regulator adapts EU Battery Regulation traceability mandates to local inspection protocols. Silesian and Greater Poland voivodeships concentrate bus fleet operators seeking modular replacement economics outside German pricing structures.
Belgium
Cross-border fleet operators exploit regulatory harmonization to standardize modular battery configurations across Benelux routes. Federal environmental enforcement aligns with EU Battery Regulation recycled content thresholds and carbon footprint disclosure. Antwerp and Brussels logistics corridors attract battery-as-a-service providers targeting high-utilization last-mile delivery electrification.
United States
EPA battery recycling standards elevate end-of-life compliance costs for sealed pack designs, creating relative advantage for serviceable architectures. NHTSA propulsion battery safety protocols influence crashworthiness testing requirements that string configurations must satisfy. Michigan and California automotive clusters host validation laboratories assessing modular fuse protection under federal motor vehicle safety standards.
Tanktwo String Cell Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with modular architecture developers commanding premium positioning against sealed pack commodity suppliers. The vendor base concentrates among cylindrical cell incumbents extending into adjacent formats and dedicated modular system architects. Two strategic archetypes dominate: integrated automotive OEMs with captive battery divisions, and independent technology licensors specializing in contactless communication and fuse protection IP. Competitive moves center on strategic partnerships for cell supply security and technology licensing for battery management firmware differentiation.
Among dedicated modular architecture specialists, TankTwo exemplifies the field-serviceable configuration segment with its serial string cell approach. Panasonic Corporation anchors the cylindrical cell incumbent tier, leveraging established manufacturing scale to compete in adjacent modular formats. LG Energy Solution occupies a position bridging chemistry innovation and system integration, with advanced material portfolios that complement decentralized battery management architectures.
| Leading Market Players |
|---|
| TankTwo |
| Tesla, Inc. |
| Panasonic Corporation |
| LG Energy Solution |
| Samsung SDI |
| BYD Company Ltd. |
| CATL |
| QuantumScape Corporation |
| Solid Power Inc. |
| Others |
Value Network & Pricing Analysis
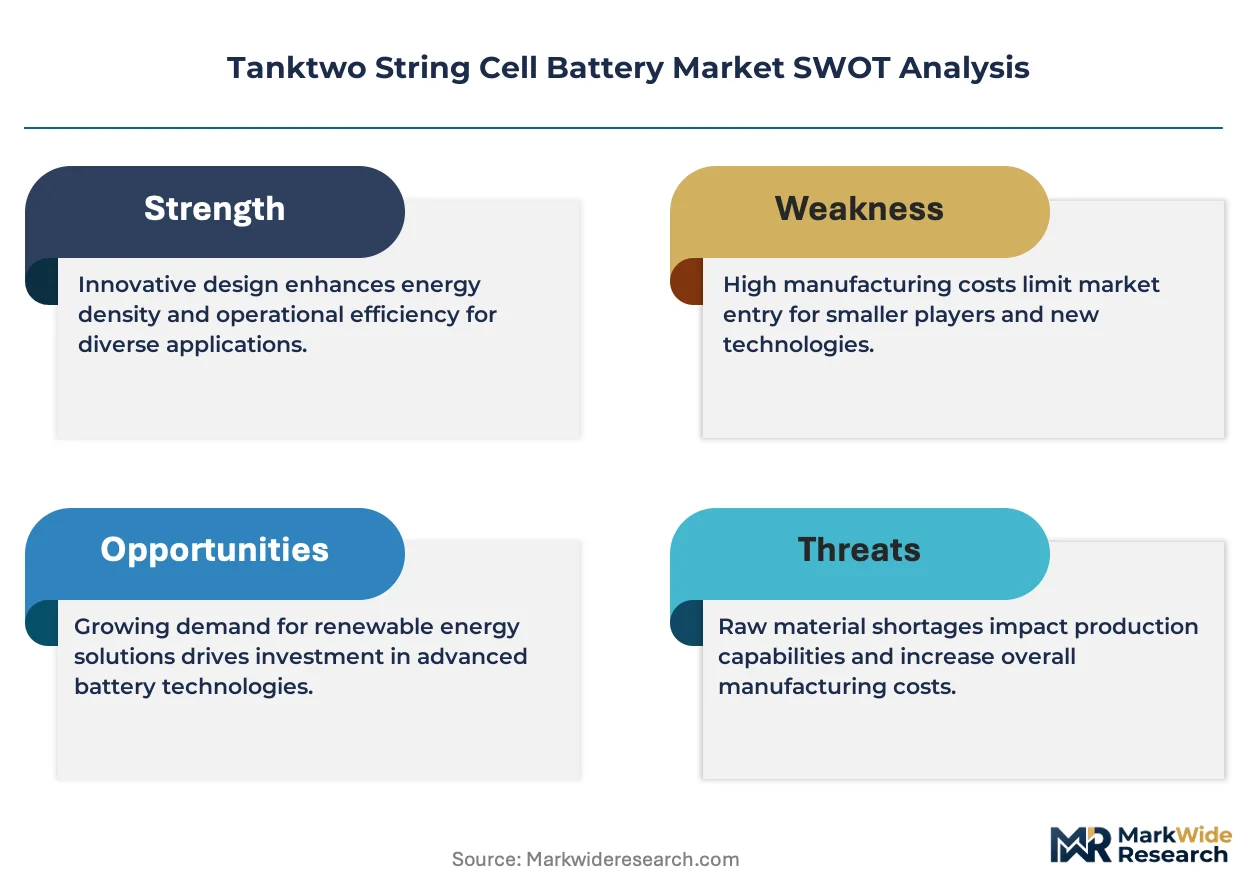
Captive cathode active material production in South Korea and Japan anchors pricing power for cell manufacturers serving modular string architectures. This upstream control insulates Tier 1 suppliers from lithium carbonate volatility while enabling premium positioning for field-serviceable configurations.
Pricing Analysis
Distributor margins for replacement string cells compress under direct-to-fleet contracting models that bypass traditional aftermarket channels. Three-tier pricing structure across premium solid-state, standard lithium-ion, and economy lead-acid levels reflects certification grade and volume scale differentials. Pricing pressure stems from solid-state chemistry substitution threats in premium electric vehicle applications. Municipal transit authorities exhibit highest price sensitivity due to fixed procurement budgets, while commercial logistics operators prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Dutch fleet operators, while independent battery asset managers source through specialized distributors. Cathode active materials draw from Chilean spodumene concentrates and Australian hard-rock lithium operations. Cell assembly concentrates in South Korea, China, and Poland. Single-source vulnerability in ceramic electrolyte substrates for solid-state formats creates supply chain risk. Distribution runs through Tier 1 automotive supplier networks with embedded service bay configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation functions as a regulatory compounder, with carbon footprint disclosure mandates and recycled content thresholds accelerating demand for traceable cell architectures.
For Market Incumbents: Lock in cell supply security through long-term offtake agreements with Chilean and Australian spodumene producers. Secure ASIL-D certification for contactless battery management protocols before NHTSA validation timelines extend competitive gaps. Vertical integration into fuse protection electronics manufacturing defends margin position against modular system commoditization.
For New Entrants and Emerging Players: Polish municipal transit authorities represent an underserved buyer archetype with EU Green Deal co-financing availability and limited incumbent penetration. Battery-as-a-service models for Benelux urban delivery fleets offer white-space expansion with usage-based contract structures. Target independent fleet operators outside German automotive clusters with modular replacement economics pitched against sealed pack downtime costs.
For Investors and Strategic Acquirers: Consolidation pressure builds where firmware differentiation outpaces hardware scale economies in distributed battery management systems. Mid-cap specialists with ISO 26262 certification completion and proven contactless communication IP present acquisition targets with defensive moats. Monitor solid-state chemistry manufacturing yield improvements as inflection indicator for modular architecture obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive lithium supply from Chilean operations insulates TankTwo and LG Energy Solution from spot price volatility. |
| ASIL-D Functional Safety Certification | Automotive-grade validation for contactless protocols accelerates OEM qualification at Daimler Truck and MAN. |
| Battery-as-a-Service Platform Launch | Usage-based contracts with Rotterdam logistics operators separate hardware ownership from energy provision. |
| Second-Life Grid Storage Partnership | Retired string cells from Dutch fleets redeploy into utility-scale installations with verified state-of-health data. |
| Solid-State Chemistry Licensing Agreement | Ceramic electrolyte IP from QuantumScape threatens to obsolete external fuse architectures in premium segments. |
Research Methodology
Direct dialogue with fleet operations directors, Tier 1 supplier procurement managers, battery management firmware engineers, and EU regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from KBA crashworthiness filings, EPA battery recycling enforcement actions, EU Battery Regulation implementation guidance, and IHS Markit commercial vehicle production databases. Bottom-up cell deployment estimates triangulated against top-down fleet electrification spending projections.
Segmented outputs across chemistry format, application intensity, end-user procurement sophistication, and technology architecture informed the analytical framework. Modeled dimensions included vehicle utilization tier, fleet size category, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to pilot deployment timelines and scaled adoption thresholds. Lithium carbonate price trajectories and solid-state manufacturing yield curves served as chemistry-specific forecast inputs.
Underlying measurement precision varies by segment; electric vehicle fleet applications carry tighter precision than grid storage second-life projections due to verified deployment data availability. Forecasts reflect assumptions regarding EU Battery Regulation enforcement consistency and NHTSA validation timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market