
 Lithium Cobalt Oxide Battery (LCO) Market | 2026-2036
Lithium Cobalt Oxide Battery (LCO) Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Cobalt Oxide Battery (LCO) Market Insights
Modular pack architectures is rebalancing procurement decisions across the LCO value chain as buyers unbundle cell sourcing from pack assembly. Panasonic Holdings Corporation leverages its vertical integration into cathode materials to sustain cost discipline in cylindrical formats. Samsung SDI anchors premium smartphone supply through differentiated high-voltage LCO formulations. Contemporary Amperex Technology Co. Limited dominates prismatic LCO module production for Chinese consumer electronics OEMs.
Lithium cobalt oxide is a layered oxide cathode material with a theoretical specific capacity near 274 mAh/g and operating voltage of approximately 3.7 V, manufactured through solid-state reaction of lithium carbonate and cobalt oxide precursors followed by calcination, primarily serving applications demanding maximum volumetric energy density in constrained form factors. LCO Cells command the dominant revenue share within product type segments due to their direct supply into smartphone and wearable OEM lines, while LCO Packs capture expanding margin pools as pack-level thermal management and battery management system integration add value beyond raw cell costs. Solid-State technology within the technology dimension attracts disproportionate R&D allocation as developers target cobalt reduction without sacrificing energy density, though Li-ion retains near-term production scale advantages.
China's SAMR enforces GB standards covering cell safety and labeling, while the EU's Battery Regulation mandates recycled content thresholds and supply chain due diligence disclosures that reshape market access conditions for non-compliant suppliers. Japan's METI coordinates domestic recycling infrastructure requirements through specified collection targets for portable electronics batteries. Stakeholders must monitor how cobalt price volatility intersects with tightening ethical sourcing mandates to determine whether alternative cathode chemistries displace LCO in mid-tier electronics applications.
Market Dynamics
High-voltage LCO formulations are compressing cell thickness requirements as smartphone OEMs pursue sub-8mm device profiles, forcing cathode suppliers to recalibrate cobalt-to-lithium stoichiometry ratios under tighter thermal constraints.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Original equipment manufacturers now face binding disclosure requirements for cobalt sourcing, accelerating investment in closed-loop recycling infrastructure across European assembly plants.
- Smart OEM energy density specifications:Foldable display form factors demand 15-20% higher volumetric energy density than conventional bar phones, sustaining premium LCO procurement despite cobalt price volatility.
- South Korean cell production clustering:Concentrated cathode-to-cell manufacturing in Gyeonggi-do and Chungcheong provinces reduces logistics friction for high-value electronics supply chains serving global brands.
Market Restraints
- Cobalt price volatility:Democratic Republic of Congo concentrate supply disruptions transmit directly to cathode material costs, compressing margins for non-integrated cell producers.
- Technical energy density ceiling:Practical LCO cell capacities plateau near 200 mAh/g, limiting further volumetric improvements without structural electrode redesigns.
- Lithium iron phosphate substitution:Mid-tier tablet and laptop segments increasingly specify LFP cathodes where cycle life outweighs energy density priorities.
Strategic Opportunities
- India consumer electronics manufacturing:Production-linked incentive schemes for mobile phone assembly create localized demand for prismatic LCO modules serving domestic and export markets.
- Solid-state electrolyte convergence:Sulfide-based ceramic separators paired with high-voltage LCO cathodes promise 30% energy density gains for next-generation wearables.
- Direct-to-OEM cathode supply contracts:Bypassing traditional trading house intermediaries allows cell producers to lock in cobalt hydroxide offtake with verified ethical sourcing documentation.
Industry Challenges
- Specialized thermal management engineering:High-voltage LCO cells require precision-engineered graphite anode matching and electrolyte additive selection, constraining supplier qualification timelines.
- Multi-jurisdiction certification synchronization:Simultaneous compliance with China's GB standards, UL 1642, and IEC 62133 creates testing bottlenecks for new cell form factor introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Cobalt Oxide Battery (LCO) Market |
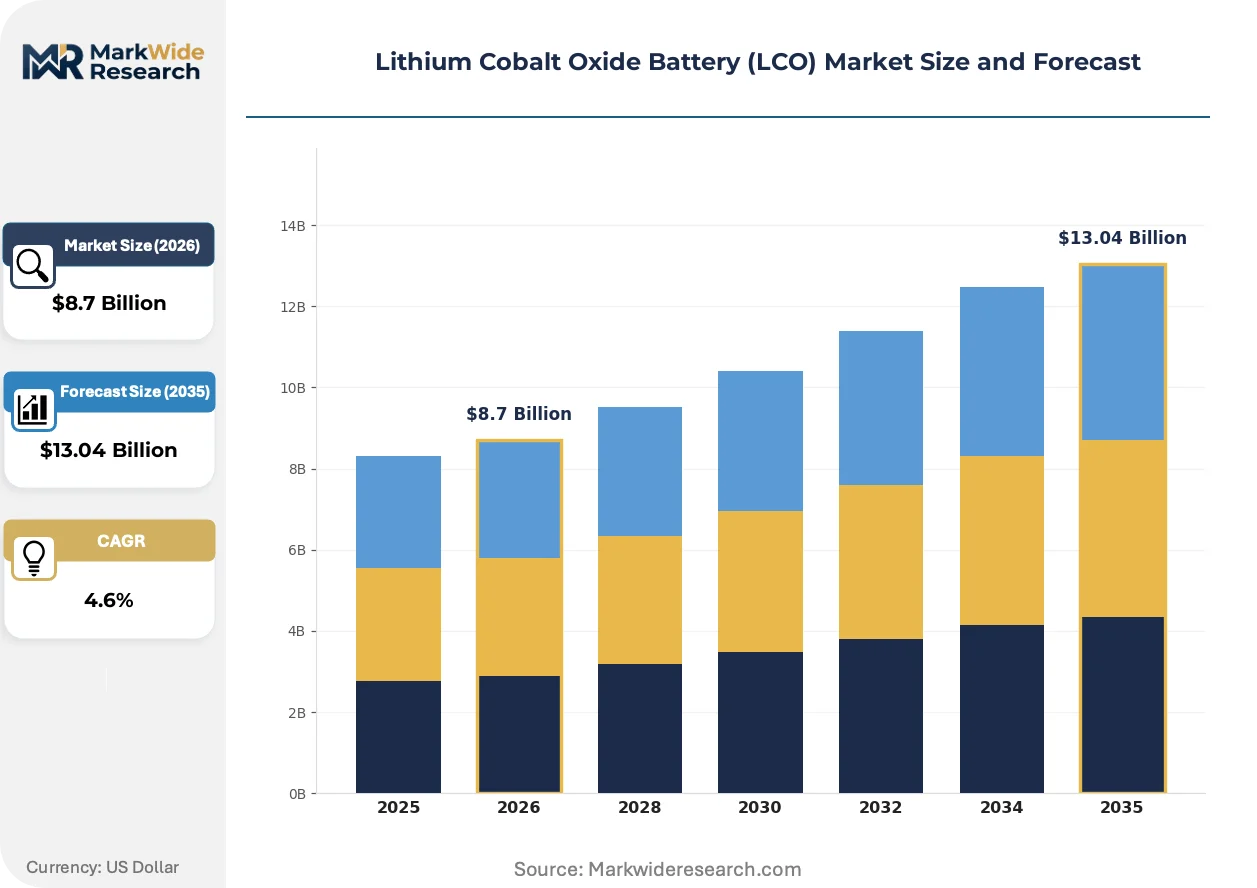
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCO Cells, LCO Packs, LCO Modules, LCO Systems End User: Consumer Electronics, Electric Vehicles, Energy Storage, Medical Devices Technology: Li-ion, Solid-State, Hybrid, Nanotechnology Application: Smartphones, Tablets, Laptops, Drones |
| Companies Covered | LG Chem, Panasonic Holdings Corporation, Samsung SDI, BYD Company Ltd., Nichia Corporation, Contemporary Amperex Technology Co. Limited, GS Yuasa Corporation, Targray, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Cobalt Oxide Battery (LCO) Market Trends and Innovations
Electrode architecture innovations and supply chain transparency mandates are restructuring how cathode materials flow from precursor refineries to finished cell assembly lines.
Solid-state electrolyte development is integrating ceramic separator layers with conventional LCO cathodes to suppress cobalt dissolution at elevated voltages. Premium smartphone OEMs in South Korea and China are piloting these configurations for foldable devices requiring 500+ charge cycles. This integration is compressing the timeline for liquid electrolyte dominance in sub-5Ah applications.
REACH Article 33 supply chain communication obligations now require cobalt compound importers to document smelter and refiner identities through full material disclosure. Battery assemblers serving EU markets must maintain due diligence records spanning extraction through cathode active material production. High-end electronics brands are responding by consolidating supplier lists to reduce audit complexity.
Modular pack procurement is displacing bundled cell-pack sourcing as OEMs unbundle thermal management system design from cell qualification. Chinese consumer electronics brands now issue separate RFPs for prismatic cells and battery management system integration. This pattern concentrates most visibly in Shenzhen and Dongguan manufacturing corridors where vertical specialization reduces time-to-market for seasonal product launches.
Lithium Cobalt Oxide Battery (LCO) Market Segmentation
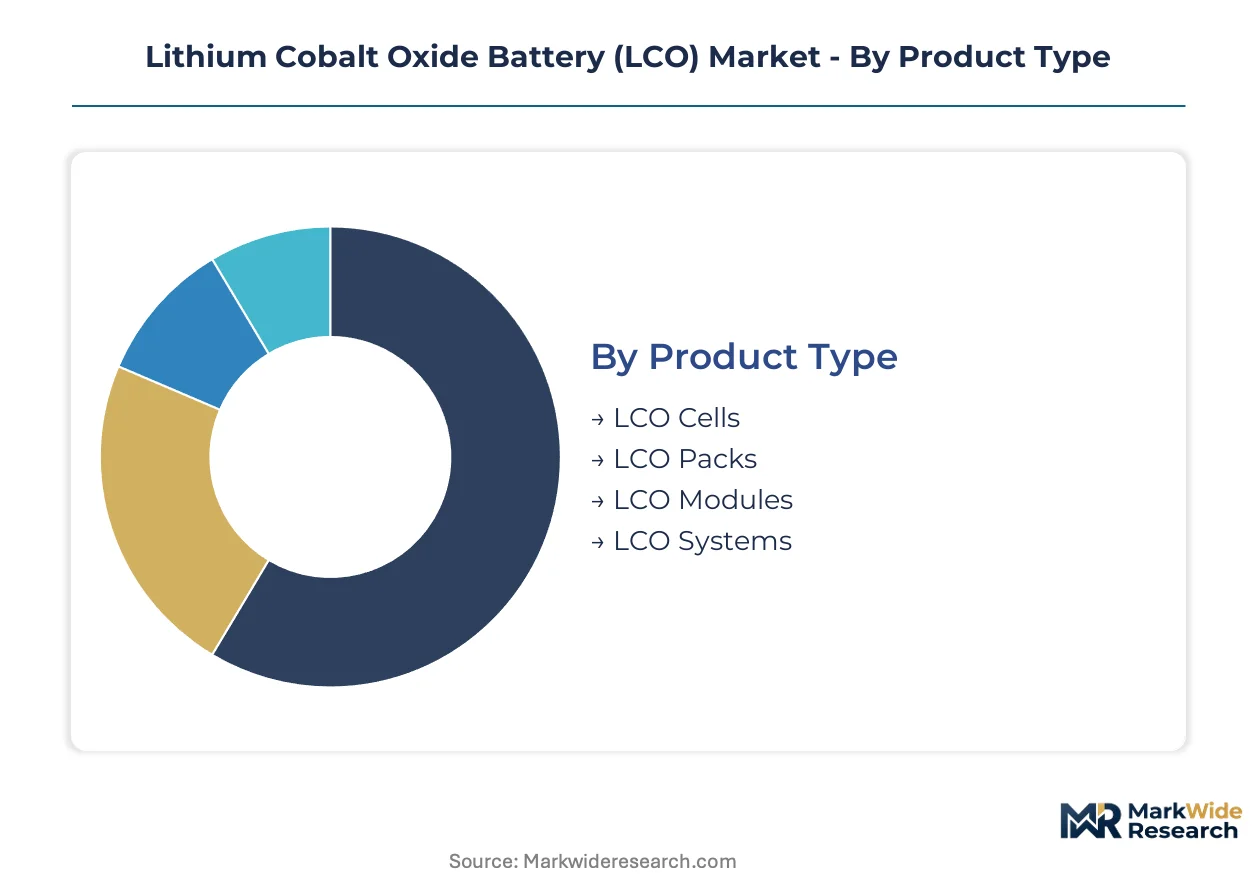
LCO battery segmentation reflects divergent technical requirements across energy density, thermal tolerance, and cycle life specifications. Procurement patterns vary sharply between smartphone OEMs prioritizing volumetric efficiency and medical device manufacturers emphasizing safety certification depth.
Product Type:
Cell-to-system architectures define cost allocation and margin capture across the value chain.
- LCO Cells:Cylindrical and prismatic formats deliver 200 mAh/g practical capacity through layered oxide cathode structures. Samsung SDI and ATL supply these directly to smartphone assembly lines in Gyeonggi-do and Dongguan where sub-8mm device profiles mandate maximum energy density per cubic millimeter.
- LCO Packs:Battery management system integration and precision thermal engineering add value beyond raw cell costs. Foldable smartphone OEMs procure these as finished modules with embedded graphite anode matching and electrolyte additive protocols pre-qualified for 500+ cycle lifespans.
- LCO Modules:Standardized prismatic assemblies serve tablet and laptop manufacturers seeking interchangeable power units across product generations.
- LCO Systems:Rack-scale configurations with active cooling support medical imaging equipment and specialized industrial applications requiring uninterrupted power integrity.
Mature deployment sits with LCO Cells. Newer deployment is concentrated in LCO Packs.
End User:
Application-specific certification requirements and cycle life demands reshape cathode procurement specifications.
- Consumer Electronics:Smartphone and wearable OEMs drive 70% of LCO volume through specifications demanding 700 Wh/L volumetric density. South Korean and Chinese brands anchor procurement in Shenzhen and Seoul manufacturing corridors where seasonal product launches compress supplier qualification timelines.
- Electric Vehicles:Premium urban mobility segments specify LCO for range-extended micro-cars where battery mass constraints outweigh cobalt cost sensitivity. European OEMs face EU Battery Regulation recycled content mandates that complicate cathode sourcing from non-audited refiners.
- Energy Storage:Residential backup systems with space constraints specify LCO where footprint reduction justifies premium chemistry costs over lithium iron phosphate alternatives.
- Medical Devices:Portable diagnostic equipment and implantable power sources require IEC 60601 compliance and extended cycle stability under sterilization protocols.
Revenue concentration clusters in Consumer Electronics. Regulatory complexity peaks in Medical Devices.
Technology:
Electrolyte architecture determines voltage tolerance and cobalt dissolution suppression capabilities.
- Li-ion:Liquid carbonate electrolyte systems with lithium hexafluorophosphate salts dominate near-term production scale. Chinese cell manufacturers in Fujian and Jiangsu provinces operate calcination furnaces optimized for solid-state reaction of lithium carbonate and cobalt oxide precursors at 800°C.
- Solid-State:Sulfide-based ceramic separators paired with high-voltage LCO cathodes promise 30% energy density gains. Japanese developers under METI coordination target commercialization for next-generation wearables requiring 4.4V operating windows without cobalt migration.
- Hybrid:Gel polymer electrolyte configurations bridge liquid and solid architectures for drone applications demanding rapid discharge rates.
- Nanotechnology:Surface-modified cathode particles and atomic layer deposition coatings extend cycle life in premium smartphone segments.
Production scale favors Li-ion. Steepest expansion trajectory belongs to Solid-State.
Application:
Form factor constraints and usage intensity patterns differentiate procurement specifications.
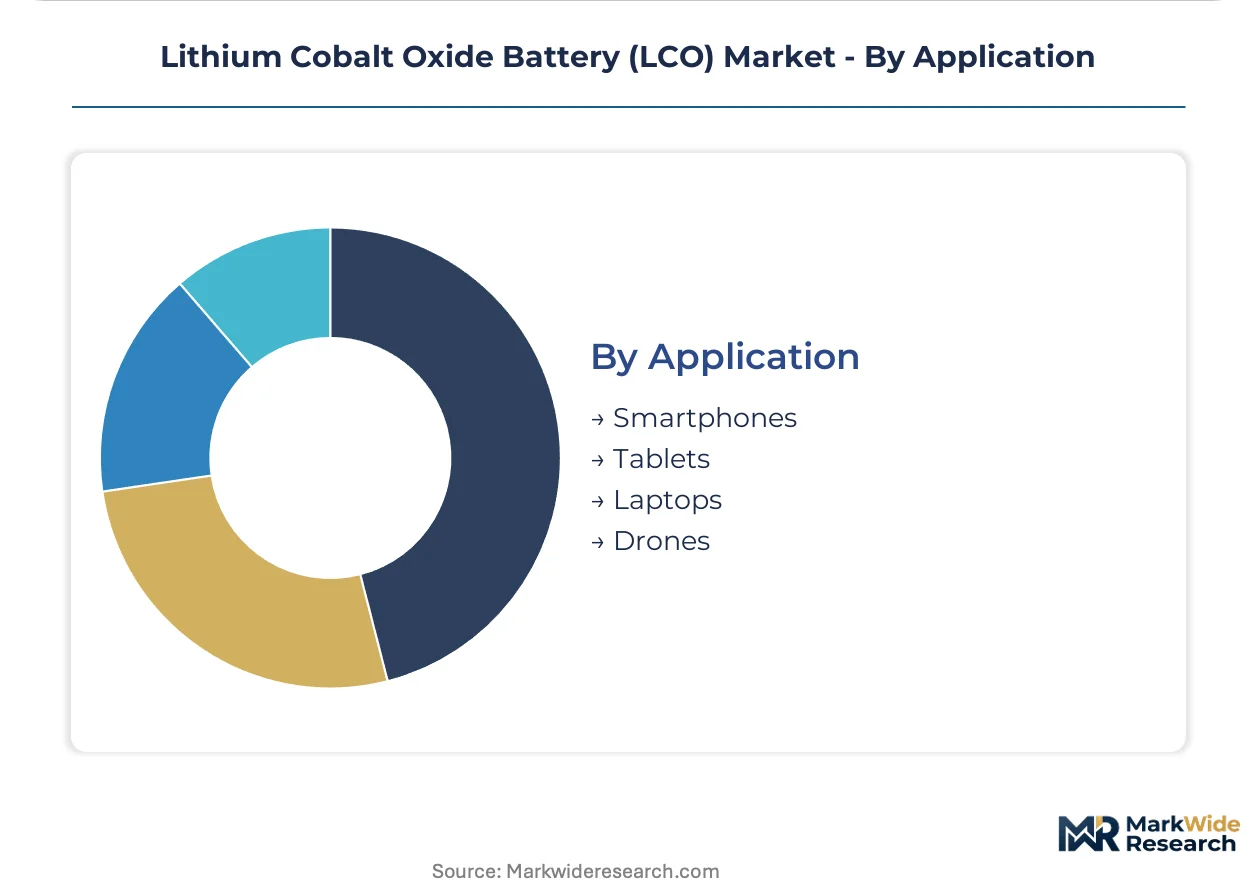
- Smartphones:Bar phones and foldable devices drive highest-value LCO consumption. Foldable display form factors demand 15-20% higher volumetric energy density than conventional designs, forcing cathode suppliers to recalibrate cobalt-to-lithium stoichiometry ratios under tighter thermal envelopes.
- Tablets:Larger surface areas accommodate thicker cells where energy density requirements moderate and cycle life specifications extend to 800+ cycles for enterprise deployment.
- Laptops:USB-C power delivery standardization and 100W charging protocols stress cathode materials with rapid lithium intercalation demands.
- Drones:High-discharge-rate applications prioritize power density over energy density, with LCO competing against lithium polymer alternatives in commercial cinematography segments.
Volume leadership rests with Smartphones. Margin expansion concentrates in Drones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters produce the majority of LCO cells while European and North American markets concentrate on pack assembly and regulatory compliance. China's cathode refineries and South Korean cell plants anchor supply-side capacity. Consumer electronics OEM procurement decisions increasingly weight carbon disclosure requirements alongside energy density specifications.
China
Domestic smartphone brands drive LCO module demand through specifications requiring 700 Wh/L volumetric density. SAMR enforces GB standards covering cell safety testing and cobalt sourcing documentation for consumer electronics applications. Shenzhen and Dongguan manufacturing corridors host concentrated pack assembly operations serving both domestic OEMs and export markets.
South Korea
Premium smartphone OEMs anchor high-voltage LCO procurement for foldable device programs requiring 500+ cycle lifespans. MFDS coordinates battery safety certification frameworks aligned with international IEC standards. Gyeonggi-do and Chungcheong provinces concentrate cathode-to-cell manufacturing infrastructure serving global electronics brands.
Japan
Specialized medical device and precision electronics manufacturers specify LCO systems requiring extended sterilization protocol tolerance. METI coordinates domestic recycling infrastructure through specified collection targets for portable electronics batteries. Nagoya and Osaka industrial zones maintain cathode material R&D facilities focused on solid-state electrolyte integration.
Germany
European electronics assembly plants face binding EU Battery Regulation recycled content mandates for cobalt sourcing disclosure. ECHA REACH Article 33 obligations require full material documentation spanning extraction through cathode active material production. Bavaria hosts automotive-tier cell qualification laboratories serving premium urban mobility LCO applications.
United States
Medical device OEMs and specialized industrial equipment manufacturers specify LCO systems requiring FDA-compliant power integrity certifications. EPA hazardous waste regulations intersect with state-level extended producer responsibility frameworks for electronics battery collection. California and Texas manufacturing corridors concentrate pack assembly operations serving North American consumer electronics distribution.
Lithium Cobalt Oxide Battery (LCO) Market Competitive Landscape
The competitive structure tilts toward vertically integrated cathode-to-cell producers with established smartphone OEM relationships. Three tiers have crystallized: integrated chemical-to-cell conglomerates controlling precursor refining, specialized cell manufacturers with format-specific expertise, and modular pack assemblers capturing thermal management value. Dominant competitive moves include backward integration into cobalt hydroxide offtake contracting and geographic expansion into India production-linked incentive corridors.
Among East Asian integrated producers, Panasonic Holdings Corporation, Samsung SDI, and Contemporary Amperex Technology Co. Limited occupy positions exemplifying the cathode-to-cell control archetype. These entities represent the concentrated tier where upstream chemical operations and downstream cell qualification capabilities overlap. BYD Company Ltd. and LG Chem sit within diversified battery portfolios spanning multiple chemistries beyond LCO specialization. The competitive terrain rewards entities with verified ethical sourcing documentation and multi-jurisdiction certification synchronization capabilities.
| Leading Market Players |
|---|
| LG Chem |
| Panasonic Holdings Corporation |
| Samsung SDI |
| BYD Company Ltd. |
| Nichia Corporation |
| Contemporary Amperex Technology Co. Limited |
| GS Yuasa Corporation |
| Targray |
| Umicore |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation recycled content mandates gate qualified supply access and premium-tier pricing power for cathode material suppliers serving European electronics OEMs. SAMR's GB standards in China and Japan's METI recycling infrastructure requirements create parallel compliance cost layers that concentrate procurement among certified refiners.
Pricing Analysis
Margin tightening in high-voltage LCO formulations reflects cobalt hydroxide price volatility transmitted from DRC concentrate disruptions. Contract-based long-term offtake agreements dominate procurement, with price differentiation hinging on verified ethical sourcing documentation and UL 1642 certification tier. Smartphone OEMs exhibit highest price sensitivity as they balance energy density specifications against bill-of-materials targets, while medical device manufacturers absorb premium pricing for IEC 60601-compliant power systems.
Supply Chain Analysis
Closed-loop refurbishment flows from European electronics collection targets under EU Battery Regulation are reshaping raw material recovery economics for cobalt-containing cells. Primary production concentrates in China, South Korea, and Japan, with cathode active material drawing from cobalt hydroxide refined in Finnish and Belgian facilities. Single-source vulnerability persists around DRC concentrate supply, while distribution runs through Shenzhen and Dongguan pack assembly corridors serving seasonal consumer electronics launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cathode calcination capacity constraints in East Asian manufacturing clusters prop pricing power for integrated cell producers. Qualified supplier lists are compressing as ethical sourcing audits accumulate.
For Market Incumbents: Anticipate lithium iron phosphate substitution in mid-tier tablet and laptop segments by locking cobalt hydroxide offtake with verified supply chain documentation. Samsung SDI and Contemporary Amperex Technology Co. Limited demonstrate how backward integration into cathode materials sustains cost discipline against trading house intermediaries. Capacity addition in Indian production-linked incentive corridors offers geographic diversification from East Asian concentration. For New Entrants and Emerging Players: Contract manufacturers in Indian mobile phone assembly present the most penetrable entry channel for prismatic LCO module supply. Medical device OEMs seeking IEC 60601-compliant power systems offer white-space opportunity with extended qualification timelines but lower price sensitivity. Direct-to-OEM cathode supply contracts bypass established trading house networks and accelerate supplier qualification through embedded technical service teams. For Investors and Strategic Acquirers: Solid-state electrolyte pilot announcements from Japanese developers under METI coordination are the leading indicator that next-generation wearable applications will reshape cathode material specifications. Vertically integrated cathode-to-cell producers with multi-jurisdiction certification synchronization capabilities represent the preferred acquisition archetype. Practitioners should monitor sulfide-based ceramic separator commercialization timelines for inflection signals in sub-5Ah application dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cobalt Hydroxide | Locks ethically documented raw material supply ahead of EU Battery Regulation enforcement thresholds. |
| Solid-State Electrolyte Partnership | Positions cathode suppliers for 4.4V high-voltage formulations in foldable smartphone programs. |
| India Manufacturing Footprint Expansion | Captures production-linked incentive schemes for mobile phone assembly serving export markets. |
| Multi-Jurisdiction Certification Synchronization | Reduces testing bottlenecks for simultaneous GB standards, UL 1642, and IEC 62133 compliance. |
| Closed-Loop Recycling Infrastructure | Meets EU Battery Regulation recycled content mandates for cobalt sourcing disclosure. |
Research Methodology
Document review covered SEC 10-K filings from cell manufacturers, SAMR GB standard documentation, and EU Battery Regulation implementation guidance, complemented by interviews with cathode material procurement directors at smartphone OEMs, plant managers at calcination facilities in Fujian and Jiangsu provinces, and regulatory affairs leads navigating REACH Article 33 obligations. Primary fieldwork with battery management system integration engineers and secondary validation through customs trade data and IEC certification databases supported bottom-up and top-down triangulation.
Segment-level outputs across product type, end user, technology, and application dimensions were generated through the analytical framework, with CAGRs derived from production capacity buildout trajectories and OEM procurement specification evolution across the projection horizon. Forecast inputs incorporated cobalt price volatility scenarios and solid-state electrolyte commercialization timelines from METI-coordinated development programs.
Caveats apply where DRC supply disruptions, rapid LFP substitution in mid-tier electronics, or accelerated solid-state battery commercialization could materially shift the outlook. Practitioners should monitor high-voltage LCO cycle life validation data and EU Battery Regulation delegated act implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Europe Solid State Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market