
 Asia-Pacific Lithium-Ion Battery Market | 2026-2036
Asia-Pacific Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lithium-Ion Battery Market Outlook
China's dual carbon goals under MIIT supervision is expanding the compliance baseline for cell manufacturers serving domestic EV makers. CATL leverages its integrated cathode-to-pack footprint across Ningde and Yibin to sustain cost leadership in LFP supply. Samsung SDI competes on premium NMC chemistry for export-bound Korean and European automakers. BYD Company Ltd. anchors vertical control over blade cell architecture, spanning mines through module assembly.
Asia-Pacific lithium-ion batteries electrochemically store and discharge energy through lithium-ion shuttling between graphite anodes and metal-oxide cathodes, typically achieving 150-250 Wh/kg at cell level for automotive-grade NMC formulations; this electrochemical architecture enables the propulsion, grid stabilization, and portable power functions that electrification mandates require. LFP technology dominates volume in Chinese bus and entry EV platforms where cost-per-cycle metrics outweigh energy density priorities. NMC chemistry leads in Korean and Japanese supply chains targeting premium automotive OEMs demanding higher specific energy. Energy Storage Systems represent the fastest-expanding application dimension as utility-scale solar pairing accelerates across Australia, India, and Southeast Asian markets.
Japan's METI enforces JIS standards and supply chain security protocols that shape cell qualification timelines for domestic automotive integration. South Korea's MFDS and KATS coordinate with industry on NCM9½½ cathode safety thresholds as nickel content rises. China's SAMR and GB standards mandate thermal runaway propagation resistance in passenger vehicle packs. Stakeholders must monitor how divergent national certification regimes affect cross-border module interchangeability and plant location decisions.
Market Dynamics
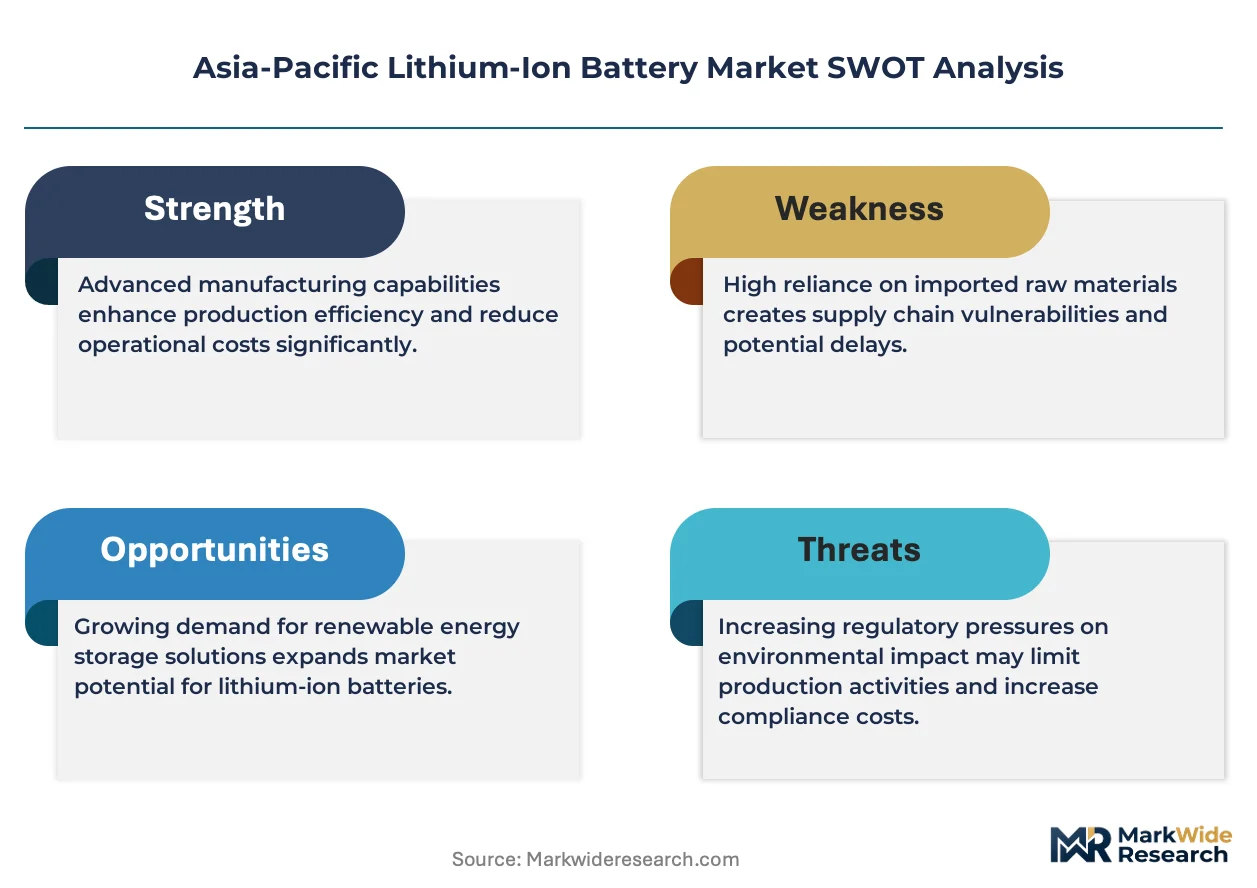
China's MIIT dual carbon mandates and Japan's METI supply chain security protocols are compressing qualification timelines while expanding compliance baselines for cell manufacturers across the region.
Growth Catalysts
- MIIT Dual Carbon Goals:China's tightening GB standards for thermal runaway propagation resistance are mandating pack-level redesigns that favor integrated cathode-to-pack producers serving domestic EV makers.
- Energy Storage Systems:Utility-scale solar pairing across Australia, India, and Southeast Asian markets is pulling lithium iron phosphate chemistry into grid stabilization contracts at accelerating volumes.
- NCM9½½ Cathode Chemistry:South Korea's MFDS and KATS coordination on elevated nickel content thresholds is enabling higher specific energy cells for premium automotive OEMs targeting export markets.
Market Restraints
- Lithium Carbonate Volatility:Raw material input costs for cathode precursors swing with South American brine and Australian spodumene concentrate availability, compressing margin visibility for non-integrated producers.
- Geographic Supply Concentration:China's Jiangsu and Fujian manufacturing corridors host adjacent cathode, cell, and EV assembly clusters that concentrate geopolitical and logistics risk for buyers seeking supply diversification.
- Electrolyte Formulation Limits:High-voltage NMC cells above 4.3V face electrolyte oxidation stability barriers that constrain cycle life in fast-charging automotive applications.
Strategic Opportunities
- India Grid-Scale Storage:Underpenetrated utility markets in Maharashtra and Gujarat offer first-mover positioning for LFP suppliers as CEA mandates accelerate renewable pairing requirements.
- Second-Life Battery Applications:Retired automotive packs are converging with stationary energy storage needs, creating circular economy revenue streams for module refurbishers serving commercial and industrial segments.
- Japan METI Battery Supply Chain Initiative:Domestic content incentives and JIS qualification fast-tracks are opening qualification pathways for regional producers serving Toyota, Nissan, and Honda integration programs.
Industry Challenges
- Electrochemical Engineering Talent:Cell design and solid-state electrolyte R&D functions face acute shortages across Korean and Japanese manufacturing bases, elongating product development cycles.
- Multi-Jurisdiction Certification:Divergent SAMR, METI, and MFDS safety protocols force parallel testing tracks that extend pack qualification timelines by twelve to eighteen months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lithium-Ion Battery Market |
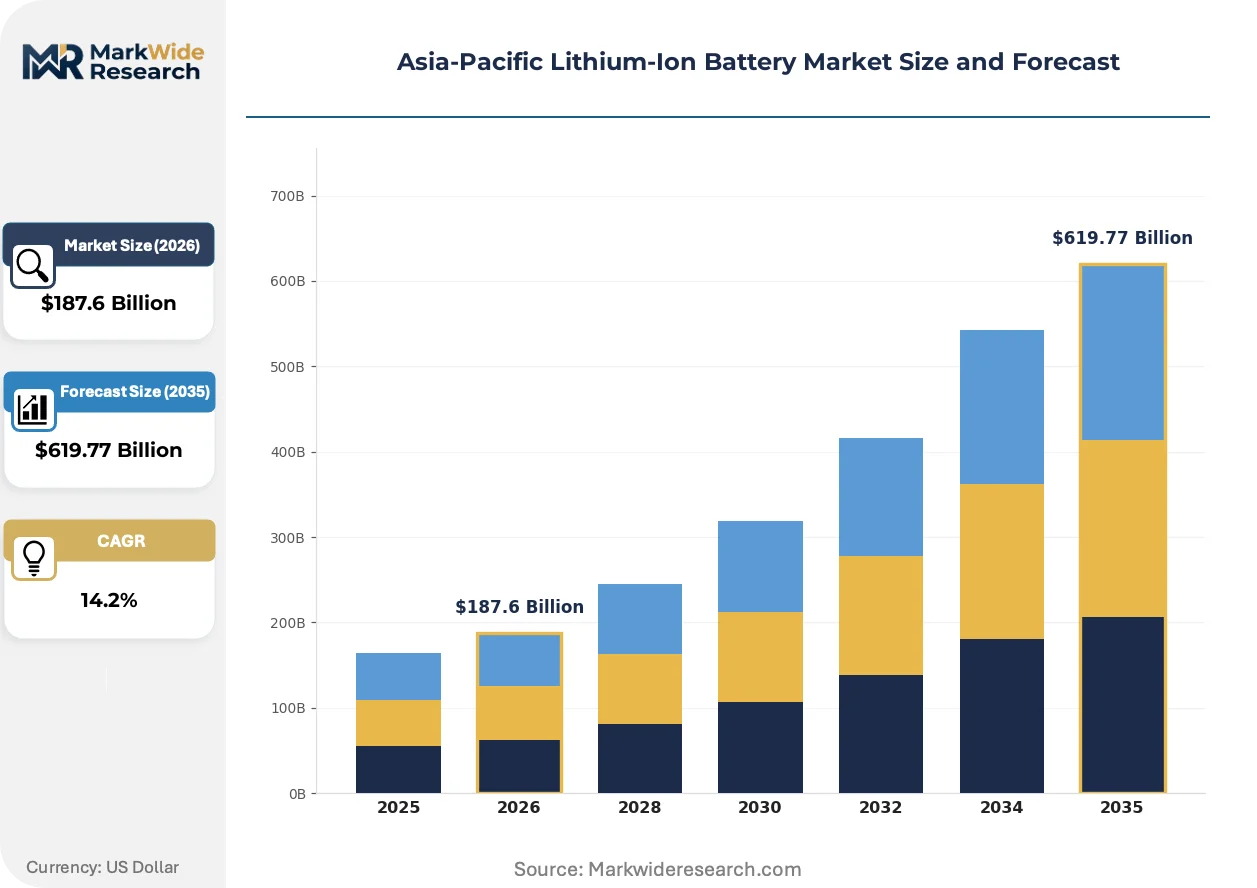
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Equipment Application: Automotive, Consumer Goods, Renewable Energy, Power Tools Technology: LFP, NMC, NCA, LiCoO2 End User: Manufacturers, Retailers, Utilities, OEMs |
| Companies Covered | Samsung SDI Co., Ltd., GS Yuasa Corporation, Contemporary Amperex Technology Co., Limited (CATL), Hitachi, Ltd., Toshiba Corporation, Panasonic Corporation, BYD Company Ltd., Automotive Energy Supply Corporation (AESC), LG Chem, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lithium-Ion Battery Market Strategic Shifts
Electrochemical architecture decisions are locking in competitive positioning as cathode chemistry choices bifurcate between cost-optimized LFP and energy-dense NMC supply chains.
Lithium iron phosphate cathode technology is consolidating its position in Chinese bus and entry-level EV platforms where cost-per-cycle metrics dominate procurement specifications. Domestic automakers in the Jiangsu corridor are standardizing on blade cell architectures that eliminate module housings. This chemistry is consolidating market share in price-sensitive segments while compressing nickel-cobalt-manganese demand growth in volume applications.
Japan's METI enforcement of JIS C 8715-2 safety standards and supply chain security protocols is tightening cell qualification timelines for domestic automotive integration. The industrial consequence is a preference for qualified regional suppliers over new cross-border entrants in Toyota and Nissan procurement decisions. Premium NMC chemistry suppliers serving Korean and Japanese export markets are responding with dedicated Japan-certified production lines.
Fleet operators and utility buyers are compressing supplier qualification cycles from multi-year frameworks to eighteen-month pilot-to-scale contracts. Direct procurement teams at energy majors are displacing traditional distributor networks in Australia and Indian grid-scale tenders. This pattern is most visible in Southeast Asian markets where state-owned utilities are consolidating vendor panels around three to four qualified cell suppliers.
Asia-Pacific Lithium-Ion Battery Market Segmentation
Segmentation in Asia-Pacific lithium-ion batteries reveals how certification requirements, chemistry choices, and end-use specifications fragment procurement strategies across national regulatory regimes. Manufacturers must align product architectures with MIIT thermal runaway standards, METI JIS protocols, and MFDS safety thresholds to secure qualification in target markets.
Product Type:
MIIT GB standards for thermal runaway propagation resistance apply most stringently to passenger vehicle packs, while industrial equipment faces lighter SAMR certification burdens.
- Consumer Electronics:Compact cylindrical and prismatic cells dominate smartphone, laptop, and wearable applications. Demand concentrates in China's Guangdong manufacturing belt where Dongguan and Shenzhen assembly clusters source standardized 18650 and 21700 formats from adjacent cell plants. MIIT certification timelines for consumer-grade cells run shorter than automotive equivalents.
- Electric Vehicles:Automotive-grade cells achieve 150-250 Wh/kg through NMC or LFP chemistries, with pack-level integration requiring SAMR-mandated nail penetration and overcharge abuse testing. Jiangsu and Fujian corridors host cathode-to-pack producers serving BYD, NIO, and Xpeng assembly lines under compressed qualification cycles.
- Energy Storage Systems:Grid-scale installations across Australia's National Electricity Market and India's CEA-mandated renewable pairing projects favor LFP chemistry for cycle life economics. Containerized battery units require IEC 62619 certification alongside national electrical safety approvals.
- Industrial Equipment:Forklift, mining vehicle, and material handling applications source heavy-format prismatic cells with lower energy density thresholds. Japanese industrial OEMs impose JIS C 8715-2 supplementary testing for factory floor deployment.
Leading the category by volume: Electric Vehicles. Growing fastest: Energy Storage Systems.
Application:
Cost tier differentiation separates premium automotive NMC supply chains from price-sensitive renewable energy LFP procurement.
- Automotive:OEM qualification protocols from Toyota, Hyundai, and BYD demand 18-24 month validation cycles including cell-to-pack thermal management verification. Korean and Japanese export-bound production lines carry additional MFDS and METI documentation burdens.
- Consumer Goods:Portable power banks, e-bikes, and personal electronics drive high-volume cylindrical cell demand through Southeast Asian distributor networks. BIS certification gates Indian market entry for China-origin cells.
- Renewable Energy:Utility-scale solar and wind pairing projects across Maharashtra, Gujarat, and Queensland specify 4-hour duration LFP systems. CEA mandates and Australian AEMO grid connection standards shape technical procurement specifications.
- Power Tools:Professional-grade cordless equipment requires high-discharge-rate 18650 cells with enhanced cycle life under repetitive load conditions. Japanese power tool manufacturers source through METI-qualified regional suppliers.
Highest margin concentration: Automotive. Steepest expansion trajectory: Renewable Energy.
Technology:
Cathode chemistry selection locks manufacturers into distinct supply chain configurations and regulatory compliance pathways.
- LFP:Lithium iron phosphate chemistry eliminates cobalt content, achieving cost-per-cycle advantages in Chinese bus fleets and entry-level EV platforms. CATL's integrated Ningde and Yibin production bases supply blade cell architectures to domestic automakers under MIIT dual carbon alignment.
- NMC:Nickel-manganese-cobalt formulations deliver higher specific energy for premium automotive export markets. South Korean producers coordinate with MFDS on NCM9½½ cathode safety thresholds as nickel content rises above 90%.
- NCA:Nickel-cobalt-aluminum chemistry serves high-performance applications requiring maximum gravimetric energy density. Japanese cell makers maintain NCA production for domestic luxury EV integration under METI supply chain security protocols.
- LiCoO2:Lithium cobalt oxide dominates consumer electronics for volumetric energy density in compact formats. Cobalt price volatility and ethical sourcing concerns constrain expansion beyond established smartphone and laptop supply chains.
Widest deployment: LFP. Most stringent certification requirements: NMC.
End User:
Customer type determines contract structure, with direct utility procurement displacing traditional distributor networks in grid-scale segments.
- Manufacturers:Cell producers and pack integrators source cathode precursors, electrolytes, and separator materials through long-term offtake agreements. Chinese vertical integration from mine to module compresses input cost variability for Jiangsu-based producers.
- Retailers:Consumer electronics distributors and aftermarket automotive channels stock standardized cell formats with minimal technical differentiation. Price competition intensifies in Southeast Asian markets with thin certification barriers.
- Utilities:State-owned power companies in India, Thailand, and Australia consolidate vendor panels around three to four qualified LFP suppliers. Direct procurement teams displace intermediaries in 100MWh-plus tender processes.
- OEMs:Automotive original equipment manufacturers impose proprietary cell specifications requiring dedicated production line qualification. Toyota, Nissan, and Honda integration programs favor METI-fast-tracked regional suppliers over new cross-border entrants.
Contract value concentration: Utilities. Fastest procurement cycle compression: OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of Asia-Pacific cell output while Japan and South Korea consume premium formulations for export-bound automotive programs. Domestic demand across Southeast Asia and India remains import-dependent. National regulatory regimes fragment procurement pathways.
China
Domestic EV procurement absorbs over half of regional LFP cell volume under MIIT dual carbon enforcement. SAMR mandates thermal runaway propagation resistance testing for all passenger vehicle packs. The Jiangsu and Fujian manufacturing corridors host cathode-to-pack producers serving BYD, NIO, and Xpeng assembly lines.
Japan
Automotive OEMs source premium NMC chemistry for hybrid and luxury EV platforms targeting European and North American export markets. METI enforces JIS C 8715-2 standards and supply chain security protocols that compress qualification timelines. The Kanto region around Tokyo anchors qualified cell production for Toyota, Nissan, and Honda integration programs.
South Korea
Battery producers coordinate with MFDS on NCM9½½ cathode safety thresholds as nickel content rises above 90% for high-specific-energy cells. KATS alignment with industry shapes export certification for premium automotive OEMs. The Seoul Capital Area and Busan-Ulsan corridor concentrate cathode precursor and cell manufacturing for global automaker supply.
India
CEA mandates accelerate utility-scale solar pairing requirements in Maharashtra and Gujarat, pulling LFP chemistry into grid stabilization tenders. BIS certification gates market entry for China-origin cells in consumer and industrial segments. State-owned utilities consolidate vendor panels around three to four qualified suppliers for 100MWh-plus contracts.
Australia
The National Electricity Market drives utility-scale storage procurement alongside rooftop solar saturation in Queensland and Victoria. AEMO grid connection standards shape technical specifications for containerized battery units. Direct procurement teams at energy majors displace traditional distributor networks in large-scale tender processes.
Asia-Pacific Lithium-Ion Battery Market Competitive Environment
The competitive structure tilts toward integrated cathode-to-pack producers with captive raw material access. Tier-one suppliers dominate automotive qualification pathways while second-tier players compete on price in consumer electronics and industrial segments. Three archetypes define positioning: vertically integrated mining-to-module operators, premium chemistry specialists serving export markets, and cost-optimized LFP fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves across the region.
Among integrated producers, Contemporary Amperex Technology Co., Limited exemplifies the cathode-to-pack archetype through its Ningde and Yibin production bases. Samsung SDI Co., Ltd. occupies a position within the premium chemistry tier serving Korean and European automakers. BYD Company Ltd. anchors the vertical control archetype spanning mines through module assembly for domestic EV platforms.
| Leading Market Players |
|---|
| Samsung SDI Co., Ltd. |
| GS Yuasa Corporation |
| Contemporary Amperex Technology Co., Limited (CATL) |
| Hitachi, Ltd. |
| Toshiba Corporation |
| Panasonic Corporation |
| BYD Company Ltd. |
| Automotive Energy Supply Corporation (AESC) |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China's Jiangsu and Fujian corridors anchor supply-side discipline, translating captive cathode-to-pack integration into pricing power that resists raw material volatility. MIIT dual carbon enforcement compresses margin tolerance for non-integrated competitors while reinforcing contract-based long-term offtake structures among qualified suppliers.
Pricing Analysis
Cost-down pressure on automotive-grade cells accelerates because SAMR-mandated thermal runaway testing extends pack redesign cycles, forcing qualification investments that non-integrated producers cannot absorb. Three-tier pricing structure across premium NMC, standard LFP, and economy industrial formats separates certification-grade automotive supply from price-sensitive grid storage procurement. Premium chemistry suppliers serving Korean and Japanese export markets command margin buffers through METI and MFDS documentation, while entry-level LFP fabricators face acute buyer price sensitivity from Chinese domestic EV makers.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Ningde and Yibin production bases to domestic automaker assembly plants, compressing logistics costs for blade cell architectures. Raw material dependencies on Australian spodumene concentrate and South American brine feed cathode precursor output across China, South Korea, and Japan. Single-source vulnerability concentrates in China's Fujian corridor, where adjacent cathode, cell, and EV assembly clusters create geopolitical exposure for buyers seeking supply diversification. Distribution runs through direct procurement channels at energy majors in Australia and India, displacing traditional distributor networks in grid-scale tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT GB standards for thermal runaway propagation resistance construct a cost-of-compliance moat that favors integrated producers with in-house testing capabilities, elevating barriers for cross-border entrants lacking SAMR-qualification infrastructure.
For Market Incumbents: Lock in cathode-to-pack integration across Ningde and Yibin production bases to defend margin position against lithium carbonate volatility. Expand METI-fast-tracked qualification pathways for Toyota and Nissan integration programs before emerging LFP specialists achieve JIS certification. Prioritize capacity addition in Jiangsu corridor adjacent to BYD and NIO assembly lines. For New Entrants and Emerging Players: The premium-to-economy price gap in India's Maharashtra and Gujarat grid-scale storage markets offers first-mover positioning as CEA mandates accelerate renewable pairing requirements. Target underqualified utility vendor panels where state-owned power companies consolidate around three to four LFP suppliers. Pursue second-life battery refurbishment partnerships with commercial and industrial segments as a low-capital go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap cathode precursor specialists in South Korea's Busan-Ulsan corridor as nickel content thresholds strain NCM9½½ safety compliance costs. Long-term viability hinges on backward integration into Australian spodumene offtake or South American brine positions. Monitor MFDS coordination with industry on elevated nickel content thresholds as the inflection signal for premium chemistry margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode-to-Pack Integration | CATL's Ningde and Yibin bases compress input cost variability under MIIT dual carbon alignment. |
| METI Fast-Track Qualification | JIS C 8715-2 certification opens Toyota and Nissan procurement pathways for regional suppliers. |
| Australian Spodumene Offtake | Long-term supply agreements with Western Australian concentrate producers hedge lithium carbonate volatility. |
| India Grid-Scale LFP Deployment | CEA-mandated renewable pairing in Maharashtra pulls containerized battery units into 100MWh-plus tenders. |
| Second-Life Battery Refurbishment | Retired automotive packs converge with stationary storage needs, creating circular economy revenue streams. |
Study Parameters
SEC filings, customs and trade databases, and MIIT production disclosures formed the secondary backbone, cross-referenced with primary interviews across cell design engineers, SAMR certification specialists, utility procurement officers, and cathode precursor plant managers. Bottom-up triangulation against top-down production capacity estimates validated volume assumptions across the analysis window.
Historical trendline analysis of LFP and NMC chemistry deployment patterns informed segmentation modeling by product type, application, technology, and end user, with additional dimensioning by national regulatory cluster. CAGRs were derived from installed capacity trajectories and EV penetration assumptions, incorporating AEMO grid connection standards and CEA mandate timelines as industry-specific forecast inputs.
Inputs from SAMR production registries and METI supply chain security protocols were available through the study window; gaps in real-time lithium carbonate spot pricing introduce uncertainty bands around margin forecasts. Periodic stress-testing of base assumptions is recommended as MFDS coordination on NCM9½½ thresholds and MIIT dual carbon enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Global Lithium-Ion Battery Energy Storage System Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market