
 Silicon Anode Lithium-Ion Battery Market | 2026-2036
Silicon Anode Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Anode Lithium-Ion Battery Market Analytics
The EU Battery Regulation is repositioning the cost-of-entry calculus for silicon-anode suppliers by imposing strict carbon footprint thresholds and recycled lithium recovery mandates. Group14 Technologies leverages its commercial-scale silicon-carbon composite production in Washington state to anchor early supply contracts with European automakers. Sila Nanotechnologies sustains R&D intensity through partnerships with Mercedes-Benz, while Amprius Technologies dominates the aviation sub-segment with its ultra-high energy density cells for unmanned aerial systems.
Silicon anode lithium-ion batteries replace conventional graphite anodes with silicon-dominant active materials that theoretically accommodate ten times more lithium ions per unit volume, though practical implementations typically blend silicon with carbon binders to manage volumetric expansion during cycling. The primary commercial purpose centers on delivering higher gravimetric energy density for electric vehicles and weight-sensitive aerospace applications. Pouch battery formats currently occupy the leading volume position due to their packaging efficiency and thermal management advantages in automotive modules, while cylindrical designs are accelerating fastest as Tesla's 4680 format validates larger-diameter silicon-anode architectures. Within applications, electric vehicles concentrate the dominant margin pool, yet aerospace represents the highest value-per-kilogram segment where Enovix and Amprius compete.
Europe's EMA and ECHA frameworks govern chemical safety disclosures for silicon nanoparticle processing, while the EU Battery Regulation's due diligence requirements are forcing anode suppliers to document cobalt-free and conflict-mineral-free supply chains. The US EPA and OSHA jointly regulate silicon dust exposure limits in electrode manufacturing facilities, raising capital requirements for domestic gigafactory entrants. Stakeholders must monitor how China's GB standards for battery cell safety testing evolve, as NMPA certification decisions will determine market access for imported silicon-anode cells into the world's largest electric vehicle market.
Market Dynamics
The central structural force reshaping silicon anode lithium-ion batteries is the EU Battery Regulation's carbon footprint declaration mandate, which forces anode suppliers to reconfigure supply chains around verified low-carbon silicon processing and documented recycled lithium recovery rates.
Growth Catalysts
- Aviation electrification mandates:Unmanned aerial systems and regional electric aircraft operators are procuring ultra-high energy density cells to extend flight endurance while meeting weight constraints.
- South Korean pilot line expansion:Dedicated silicon-anode manufacturing facilities in South Korea are concentrating technical talent and equipment supply chains, accelerating cell qualification timelines for automotive OEMs.
- REACH compliance frameworks:ECHA chemical safety disclosures for silicon nanoparticle processing are standardizing material specifications across European cell manufacturers, reducing qualification friction between suppliers and buyers.
Market Restraints
- Silicon feedstock cost volatility:Metallurgical-grade silicon prices fluctuate with solar panel manufacturing demand, compressing anode material margins during polysilicon shortage cycles.
- Volumetric expansion physics:Silicon particles swell 300% during lithiation, requiring carbon binder architectures that dilute theoretical energy density advantages and extend R&D timelines.
- China GB standard uncertainty:Pending NMPA certification revisions for imported silicon-anode cells create market access risk for non-Chinese suppliers serving the world's largest electric vehicle fleet.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentive structures for advanced cell chemistry manufacturing offer capital cost offsets for silicon-anode gigafactory entrants targeting the subcontinent's emerging electric two-wheeler and three-wheeler segments.
- Pre-lithiation technology convergence:Integration of stabilized lithium metal powders with silicon-carbon composites promises first-cycle efficiency gains that could unlock aviation and marine applications currently blocked by formation loss constraints.
- Direct OEM contracting channels:Automotive manufacturers are bypassing traditional tier-one battery pack assemblers to negotiate silicon-anode cell supply agreements directly with material innovators, compressing margin capture for intermediate distributors.
Industry Challenges
- Electrode coating talent scarcity:Silicon-anode slurry formulation and slot-die coating require process engineers with rare cross-training in nanoparticle dispersion rheology and high-speed manufacturing, creating recruitment bottlenecks for gigafactory scale-up.
- Formation protocol standardization delays:Absence of unified IEC testing methodologies for silicon-anode cycle life measurement forces suppliers to duplicate qualification campaigns across customer-specific test matrices, extending commercialization timelines.
- Dry electrode integration complexity:Emerging solvent-free electrode manufacturing processes require complete reconfiguration of calendaring and slitting equipment, straining capital allocation decisions for incumbent graphite-anode producers pivoting to silicon.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Anode Lithium-Ion Battery Market |
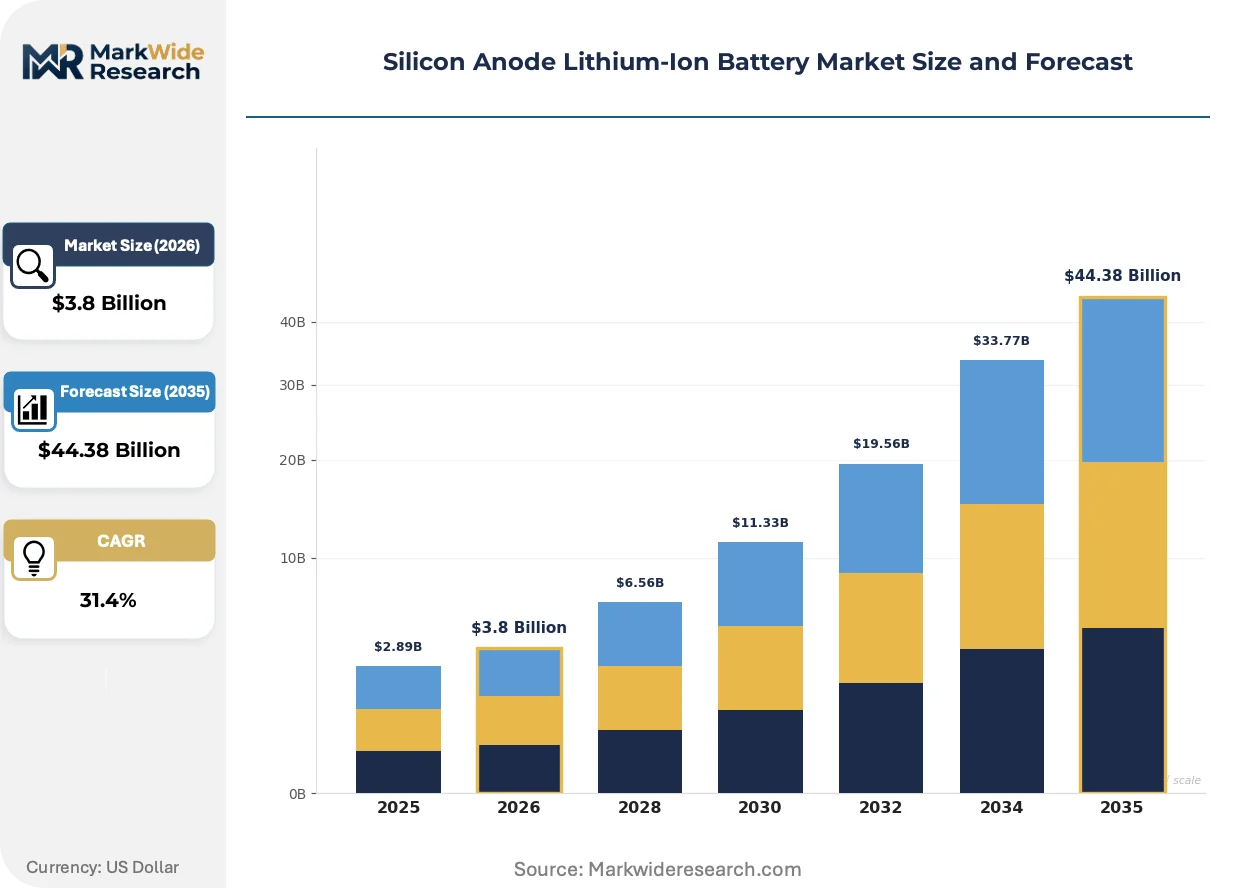
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Battery, Cylindrical Battery, Prismatic Battery, Pouch Battery Application: Electric Vehicle, Consumer Electronics, Energy Storage System, Aerospace Component: Electrolyte, Separator, Current Collector, Anode Material End User: Automotive, Electronics Manufacturers, Renewable Energy Providers, Aviation Industry |
| Companies Covered | Group14 Technologies, Samsung, Sila Nanotechnologies, Nexeon, Enovix, Amprius Technologies, LeydenJar, StoreDot, Enevate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Anode Lithium-Ion Battery Market Evolving Landscape
Silicon anode technology is fragmenting manufacturing geography as regional cell producers seek supply chain autonomy from East Asian graphite anode concentration, while regulatory pressure accelerates material disclosure requirements and performance certification standards.
Silicon-carbon composite architectures are decentralizing cell production location decisions by enabling smaller-format gigafactories to achieve energy density parity with legacy graphite-anode megaplants. Regional battery producers in Germany and the United States are adopting these materials to justify domestic manufacturing investments despite higher labor costs. The technology is decentralizing capacity planning away from volume-maximizing single sites toward distributed networks serving regional automotive assembly clusters.
REACH registration requirements for silicon nanoparticles are forcing anode suppliers to submit granular toxicology and exposure data before commercial shipments to European cell manufacturers. ECHA's extended safety data sheet mandates have extended material qualification timelines by six to twelve months for non-EU suppliers. Small and mid-sized anode innovators are responding by establishing European toll processing partnerships to localize chemical transformation steps and simplify regulatory compliance.
Automotive OEMs are consolidating silicon-anode cell procurement through multi-year offtake agreements that transfer formation yield risk from suppliers to vehicle manufacturers. Tier-one battery pack assemblers are losing their traditional intermediary role as direct material specification authority shifts to OEM cell engineering teams. This pattern is most visible in Germany, where Mercedes-Benz and BMW have established dedicated silicon-anode sourcing offices in Washington state and South Korea to manage supplier relationships previously handled by Asian cell integrators.
Silicon Anode Lithium-Ion Battery Market Segmentation
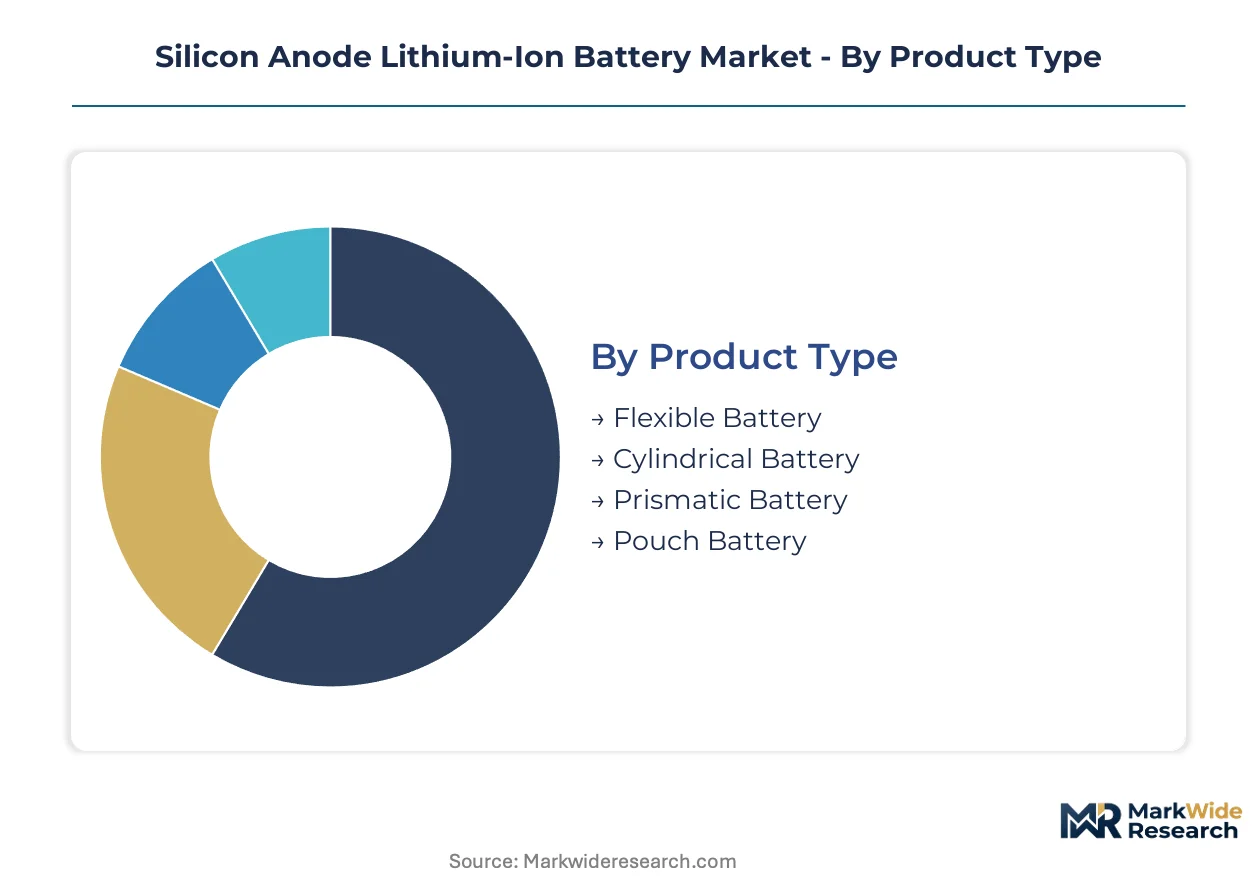
Silicon anode battery architectures diverge sharply across form factor, end-use thermal requirements, and supply chain maturity. Each segment category carries distinct qualification timelines and margin structures that determine competitive positioning for material suppliers and cell manufacturers.
Product Type:
Standardization dominates at the cell level while customization concentrates in module integration and thermal management systems.
- Pouch Battery:Laminated aluminum-polymer packaging maximizes volumetric energy density and enables flexible form factors for automotive floor pans. Demand clusters with European premium EV manufacturers seeking packaging efficiency for extended-range sedans, constrained by swelling management requirements during silicon lithiation cycles.
- Cylindrical Battery:Steel-can architectures with tabless electrode designs accommodate radial expansion stress from silicon particle swelling more effectively than prismatic alternatives. Tesla's 4680 format validation is accelerating procurement from South Korean and Japanese equipment suppliers for larger-diameter silicon-anode production lines.
- Prismatic Battery:Aluminum-housed rectangular cells dominate Chinese EV platforms where cell-to-pack integration reduces module overhead. CATL and BYD specifications are setting de facto dimensional standards for Asian automotive adoption.
- Flexible Battery:Ultra-thin printed and thin-film architectures serve wearable electronics and conformable medical devices requiring mechanical compliance. Energy density trade-offs limit automotive relevance to specialized sensor applications.
Leading the category by volume: Pouch Battery. Growing fastest: Cylindrical Battery.
Application:
Cost tiers stratify sharply between mass-market automotive and certified aerospace procurement.
- Electric Vehicle:Battery electric and plug-in hybrid platforms account for the dominant revenue pool, with OEMs specifying silicon-anode cells for 800V architectures and premium driving range segments. German and South Korean automakers are bypassing tier-one integrators to negotiate direct material supply agreements with anode innovators.
- Aerospace:Unmanned aerial systems and regional electric aircraft impose the most stringent gravimetric energy density requirements, accepting 3-5x cell cost premiums versus automotive. FAA certification pathways for silicon-anode propulsion batteries remain under development, creating qualification bottlenecks for US air taxi developers.
- Consumer Electronics:Smartphone and laptop manufacturers are selectively adopting silicon-carbon composite anodes for flagship product lines where battery life differentiation commands retail premiums.
- Energy Storage System:Grid-scale and residential battery installations prioritize cycle life and capital cost over energy density, limiting silicon-anode penetration to demonstration projects and frequency regulation applications requiring rapid discharge.
Highest margin concentration: Aerospace. Expanding most quickly: Electric Vehicle.
Component:
Supply concentration varies from commoditized separators to specialized anode materials with limited qualified suppliers.
- Anode Material:Silicon-carbon composite slurries and pre-lithiated powders constitute the primary technology differentiation layer, with Group14 Technologies and Sila Nanotechnologies controlling distinct intellectual property approaches to particle architecture and binder systems.
- Electrolyte:Fluorinated carbonate formulations and localized high-concentration salts are being co-developed with anode suppliers to stabilize solid-electrolyte interphase formation on silicon surfaces during initial cycles.
- Separator:Ceramic-coated polyolefin membranes face performance trade-offs as silicon expansion generates mechanical stress on pore structures; aramid and PI alternatives are emerging for high-silicon-content cells.
- Current Collector:Ultra-thin copper foils with engineered surface roughness improve silicon adhesion but require tension-controlled winding equipment to prevent electrode cracking during high-speed manufacturing.
Tightest supply: Anode Material. Fastest qualification timeline: Electrolyte.
End User:
Procurement sophistication ranges from automotive OEM technical specifications to renewable energy provider price-per-kWh tenders.
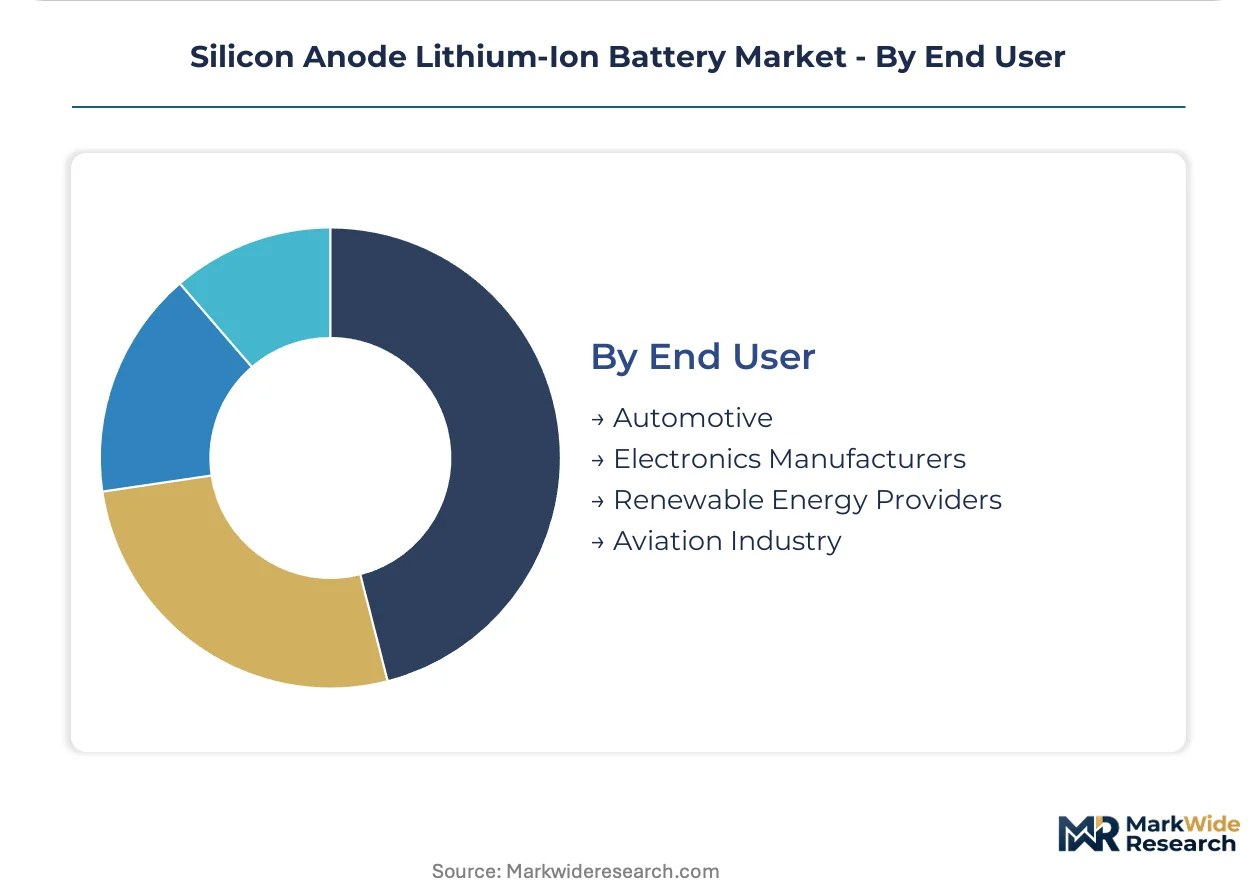
- Automotive:Vehicle manufacturers are consolidating silicon-anode sourcing through dedicated cell engineering teams in Washington state and South Korea, displacing traditional tier-one battery pack assembler intermediaries. Mercedes-Benz and BMW have established regional procurement offices to manage direct supplier relationships.
- Aviation Industry:Electric aircraft developers and unmanned system operators specify cells against mission endurance requirements rather than standardized cycle life metrics, creating bespoke qualification protocols that extend commercialization timelines.
- Electronics Manufacturers:Consumer device assemblers prioritize supply security and form factor flexibility over absolute energy density, maintaining dual sourcing across silicon-anode and advanced graphite-anode suppliers.
- Renewable Energy Providers:Utility and independent power producers evaluate silicon-anode storage against lithium iron phosphate benchmarks on levelized cost of storage, with silicon penetration limited to applications where footprint constraints outweigh capital cost sensitivity.
Dominant procurement volume: Automotive. Steepest expansion trajectory: Aviation Industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for silicon anode lithium-ion batteries concentrates in three national markets where automotive electrification and aerospace procurement intersect with domestic manufacturing policy. Each geography shapes supplier access through distinct regulatory frameworks and industrial cluster development.
United States
Aviation electrification programs at FAA-certified test ranges and Department of Defense unmanned system procurements drive ultra-high energy density cell demand. The Inflation Reduction Act's advanced manufacturing production credits reduce capital costs for domestic anode material facilities. Washington state hosts commercial-scale silicon-carbon composite production serving direct OEM contracting channels.
Germany
Mercedes-Benz and BMW specifications for 800V premium EV architectures anchor European silicon-anode procurement volume. The EU Battery Regulation's carbon footprint declaration mandate and recycled content thresholds reconfigure supplier qualification requirements. Bavaria-based cell engineering teams now manage direct supplier relationships previously routed through Asian integrators.
South Korea
Samsung SDI and SK On pilot line expansions concentrate technical talent and equipment supply chains for automotive qualification campaigns. MFDS chemical safety frameworks and KBA vehicle-type approval processes standardize material specifications. Gyeonggi-do manufacturing corridors host dedicated silicon-anode production facilities accelerating cell qualification timelines.
China
CATL and BYD prismatic cell specifications set de facto dimensional standards for mass-market EV platforms consuming silicon-anode materials. Pending NMPA certification revisions for imported cells create market access uncertainty for non-Chinese suppliers. Yangtze River Delta battery industrial zones integrate silicon-anode research with graphite-anode legacy capacity.
Japan
Meti-funded solid-state battery programs and silicon-anode hybrid architectures target next-generation automotive applications. JIS standards for cell safety testing and METI supply chain resilience initiatives promote domestic anode material development. Nagoya-area automotive supplier networks coordinate silicon-anode qualification with Toyota and Honda electrification roadmaps.
Silicon Anode Lithium-Ion Battery Market Competitive Landscape
US-based material innovators anchor one tier; South Korean and Japanese cell manufacturers hold integrated production scale. The vendor base splits between specialized anode material suppliers and diversified battery producers with captive silicon-anode programs. Three archetypes dominate: silicon-carbon composite specialists, pre-lithiation technology developers, and aviation-focused ultra-high density cell manufacturers. Competitive moves concentrate on direct OEM contracting channel establishment and pilot line capacity expansion ahead of gigafactory qualification.
Within the material innovation tier, Group14 Technologies and Sila Nanotechnologies exemplify divergent intellectual property approaches to particle architecture and binder systems. Amprius Technologies occupies a position in the aviation-specialist segment where gravimetric energy density specifications command substantial cost premiums. Samsung represents the integrated manufacturer archetype with silicon-anode pilot lines feeding broader cell production networks.
| Leading Market Players |
|---|
| Group14 Technologies |
| Samsung |
| Sila Nanotechnologies |
| Nexeon |
| Enovix |
| Amprius Technologies |
| LeydenJar |
| StoreDot |
| Enevate |
| Others |
Value Network & Pricing Analysis
Automotive OEM direct procurement offices in Washington state and South Korea anchor pricing power for silicon-anode cells, compressing margin capture for traditional tier-one battery pack assemblers and shifting contract structures toward long-term offtake agreements with formation yield risk transfer.
Pricing Analysis
Short lead-time premiums for aviation-qualified cells command substantial markups over automotive volumes, while spot inventory discounts emerge for metallurgical-grade silicon feedstock during solar panel demand troughs. Three-tier pricing structure across aviation-certified, automotive-qualified, and development-grade volumes reflects certification investment recovery timelines. Pricing pressure stems from polysilicon shortage cycles that compress anode material margins when solar manufacturing demand spikes. Aviation procurement teams exhibit lowest price sensitivity, accepting cost premiums for gravimetric energy density, while renewable energy providers benchmark silicon-anode storage against lithium iron phosphate on levelized cost thresholds.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and the US Inflation Reduction Act's advanced manufacturing credits are reshaping sourcing geography toward localized toll processing partnerships. Supply concentrates in China for prismatic cell manufacturing, South Korea for cylindrical pilot lines, and the United States for silicon-carbon composite production. The chain draws from metallurgical-grade silicon feedstock, fluorinated carbonate electrolytes, and ceramic-coated polyolefin separators. Single-source vulnerability in silicon nanoparticle processing equipment creates qualification bottlenecks for gigafactory scale-up. Distribution runs through direct OEM contracting channels that displace traditional tier-one battery pack assembler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon-anode cell supply remains constrained by electrode coating talent scarcity and formation protocol standardization delays, propping pricing power for qualified suppliers while extending commercialization timelines for aspirant entrants.
For Market Incumbents: Acquire specialized slot-die coating equipment manufacturers to secure process engineering talent pools and lock in nanoparticle dispersion rheology capabilities. Secure backward integration into metallurgical-grade silicon processing to hedge polysilicon price volatility exposure. Defensive positioning requires pre-lithiation technology patents to block formation loss improvement pathways for substitute anode material developers. For New Entrants and Emerging Players: Digital-channel qualification platforms offering remote cell testing data dashboards provide the lowest-friction route to aviation OEM technical evaluations. White-space concentrates in regional electric aircraft propulsion batteries where FAA certification pathways remain under development. Target India's electric two-wheeler and three-wheeler segments through PLI-aligned domestic manufacturing partnerships. Direct contracting with German automotive OEM cell engineering teams bypasses entrenched Asian integrator relationships. For Investors and Strategic Acquirers: The window for entry favors pre-revenue silicon-carbon composite specialists with validated pilot-scale production and locked electrolyte co-development partnerships. Long-term viability hinges on securing multi-year offtake agreements before gigafactory qualification campaigns saturate available procurement bandwidth. Acquisition targets should demonstrate ECHA REACH registration progress for silicon nanoparticle toxicology disclosure. The signal to watch is NMPA certification revision timing for imported cells into China, which would reset competitive access assumptions for non-Chinese suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Pilot Line Capacity Expansion | Samsung SDI and SK On dedicated facilities accelerate automotive qualification timelines for 800V architectures. |
| Direct OEM Contracting Channel | Mercedes-Benz and BMW sourcing offices in Washington state displace traditional tier-one battery pack assembler intermediaries. |
| Pre-Lithiation Technology Development | Stabilized lithium metal powder integration promises first-cycle efficiency gains for aviation formation loss constraints. |
| REACH Compliance Localization | European toll processing partnerships simplify ECHA extended safety data sheet mandates for non-EU anode suppliers. |
| Aviation Certification Pathway Investment | FAA propulsion battery standards development creates qualification moat for early silicon-anode cell submissions. |
Research Methodology
SEC filings, customs and trade data, and IEA battery supply chain reports formed the secondary backbone, cross-referenced with primary interviews involving electrode coating process engineers, automotive OEM cell procurement directors, aviation battery system integrators, and ECHA regulatory compliance specialists. Bottom-up cell production capacity modeling and top-down electric vehicle platform penetration analysis enabled triangulation across data sources.
Bottom-up volume estimates aggregated named pilot line capacities and equipment supplier order backlogs, while top-down projections applied content-per-vehicle assumptions across electric vehicle, aviation, and consumer electronics segments. The analytical framework modeled form factor adoption, application tier margin structures, and component supply concentration throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market value expansion. Industry-specific inputs included polysilicon price cycle correlations and NMPA certification timeline assumptions.
The model holds under stable EU Battery Regulation implementation timelines and continued South Korean pilot line investment trajectories; deviation in China's GB standard revision timing or India's PLI scheme allocation would shift regional supply concentration assumptions. Forecasts incorporate documented assumptions regarding formation yield improvement rates and electrolyte co-development partnership success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market