
 Lead Stearate Market | 2026-2036
Lead Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Stearate Market Outlook
Specialty chemical distribution networks serving PVC compounders is reconfiguring around regional hub strategies that cut lead times for heat stabilizer inputs. Peter Greven GmbH & Co. KG leverages its European manufacturing footprint to sustain just-in-time contracts with German automotive cable producers. Valtris Specialty Chemicals anchors North American supply through vertically integrated stearic acid sourcing. Baerlocher GmbH competes on technical service intensity, embedding formulation chemists directly at customer compounding sites.
Lead stearate functions as a metallic soap salt produced via direct fusion of stearic acid with litharge, yielding a product with melting points typically between 105°C and 112°C that serves primarily as a heat stabilizer and lubricant in halogenated polymer processing. The powder form dominates current shipments due to its ease of dispersion in dry-blend PVC operations, though granules are gaining traction where dust containment regulations have tightened. Plastics applications, specifically rigid PVC pipe and profile extrusion, occupy the largest margin pool, while coatings for corrosion-resistant primers represent a faster-growing niche where lead replacement remains technically challenging.
EPA oversight under the Toxic Substances Control Act constrains new lead compound introductions in the United States, while REACH registration requirements in Europe mandate extensive toxicological dossiers that filter out smaller importers. China's GB standards for plastic products set maximum lead migration limits that directly determine which stabilizer grades qualify for food-contact and potable-water applications. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments made for one market may not transfer cleanly to another.
Market Dynamics
Regulatory fragmentation across major chemical jurisdictions is fragmenting supplier qualification pathways, forcing lead stearate producers to maintain parallel compliance dossiers for EPA, ECHA, and China's MEE while PVC processors consolidate purchase volumes around fewer qualified vendors.
Growth Catalysts
- REACH registration thresholds:ECHA's data requirements for lead compounds above one tonne annually filter out marginal importers, concentrating volume with established European manufacturers who can absorb toxicological testing costs.
- PVC pipe demand in China's water infrastructure:Provincial utilities expanding potable-water networks under the 14th Five-Year Plan specify heat-stabilized formulations for buried distribution lines, directly lifting technical-grade lead stearate offtake.
- Granulation technology adoption:Dust suppression mandates in German compounding facilities accelerate granular lead stearate substitution for powder forms, rewarding suppliers with dedicated extrusion capabilities.
Market Restraints
- Stearic acid feedstock volatility:Tallow and palm oil price swings transmit directly to lead stearate production economics, compressing margin predictability for non-integrated compounders.
- Substitution by calcium-zinc systems:Wire and cable manufacturers serving Scandinavian markets face customer-driven reformulation pressure away from lead-based stabilizers toward mixed-metal alternatives.
- EPA new chemical review timelines:Toxic Substances Control Act Section 5 premanufacture notices for modified lead stearate grades extend 180+ days, freezing product line extensions for US-focused suppliers.
Strategic Opportunities
- Corrosion-resistant coatings for offshore wind:Marine primer formulations requiring lead soap compatibility with epoxy-amine systems represent an underserved specification niche as North Sea turbine installation accelerates.
- India's BIS certification pathway:Domestic PVC profile extruders seeking ISI mark compliance for window frames create first-mover advantage for lead stearate suppliers willing to complete Bureau of Indian Standards factory audits.
- Battery separator lubrication demand:Lithium-ion cell manufacturing expansion in South Korea and Japan consumes metallic soap lubricants for polyolefin membrane processing, opening technical-grade volume outside traditional plastics channels.
Industry Challenges
- Formulation chemist scarcity:PVC stabilizer technical service requires hybrid expertise in polymer degradation mechanisms and heavy metal toxicology, a skill intersection with limited training pipeline output.
- Legacy ERP integration with batch traceability:REACH and TSCA audit demands for lot-level lead content documentation collide with decades-old manufacturing execution systems at mid-scale European producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Stearate Market |
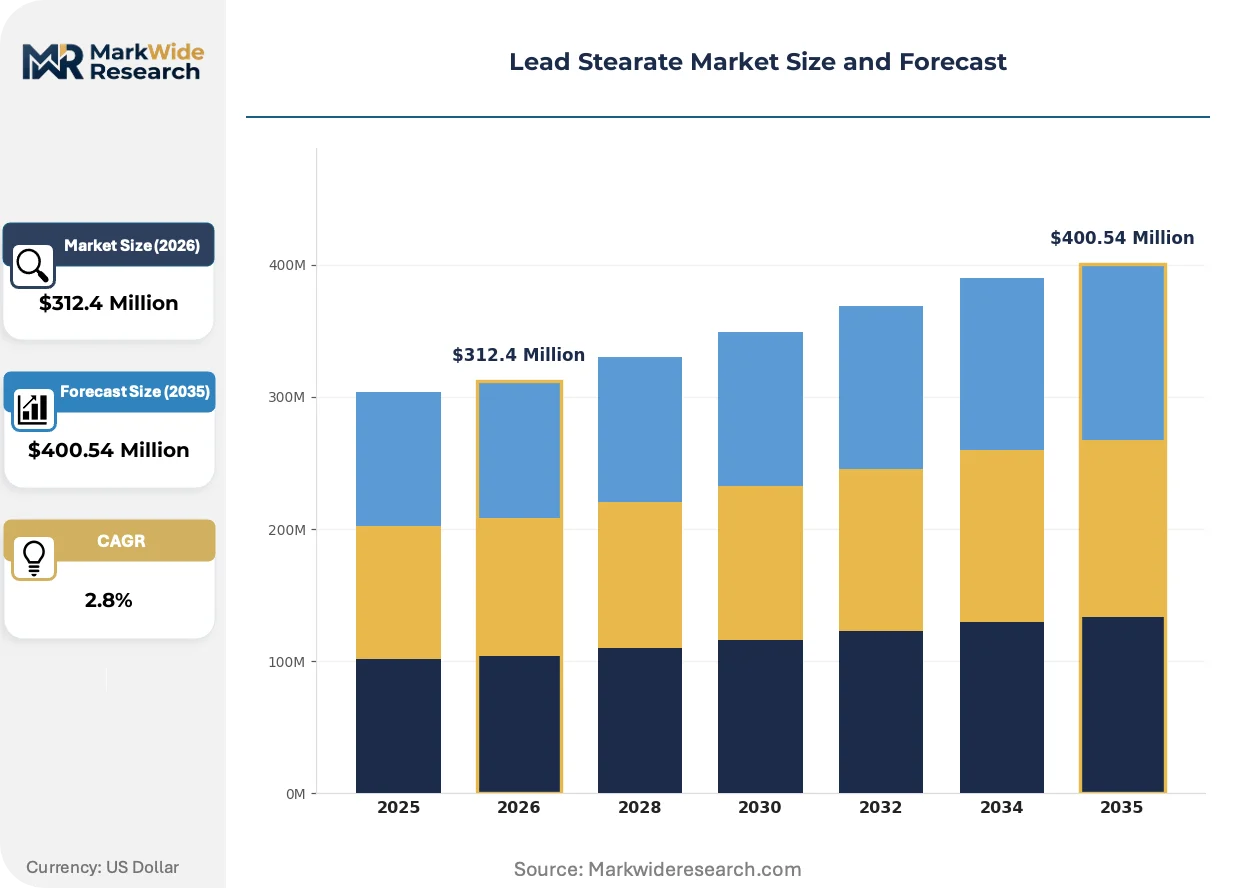
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $400.54 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Pellets, Flakes Application: Plastics, Coatings, Rubber, Adhesives End User: Construction, Automotive, Packaging, Electronics Form: Solid, Liquid, Compound, Mixture |
| Companies Covered | Peter Greven GmbH & Co. KG, Pratham Stearchem, Valtris Specialty Chemicals, American Elements, POCL Enterprises, Baerlocher GmbH, PMC Group, AIVIT Group, Faci S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Stearate Market Strategic Shifts
Lead stearate production and application methods are pivoting toward dust-containment compliance and specification-grade differentiation as regulatory scrutiny intensifies and end-users demand documented purity thresholds.
Granular lead stearate is migrating from specialty niche to mainstream specification in German and Benelux compounding operations. Automotive cable producers at Leoni and Prysmian facilities specify granules to satisfy workplace exposure limits under Germany's TRGS 900 technical rule. The format shift compresses powder-form margins while rewarding capital-intensive extrusion investments.
ECHA's 2023 update to REACH Annex XVII lead restrictions tightened migration limits for articles in prolonged skin contact, directly affecting PVC synthetic leather applications. Italian furniture manufacturers serving contract interiors now demand certified sub-90 ppm migration grades, forcing stabilizer formulators to segregate production lines by purity tier. The coating segment faces parallel pressure as toy and childcare article specifications cascade down supply chains.
Specification-driven procurement now dominates large PVC pipe contracts in China's municipal water sector. Provincial SOEs bundle heat stabilizer qualification with compounder certification, collapsing previously separate vendor relationships. Sinopec's pipe resin customers now source lead stearate through approved distributor hierarchies rather than direct mill relationships, compressing spot-market liquidity and elongating payment cycles for non-preferred suppliers.
Lead Stearate Market Segmentation
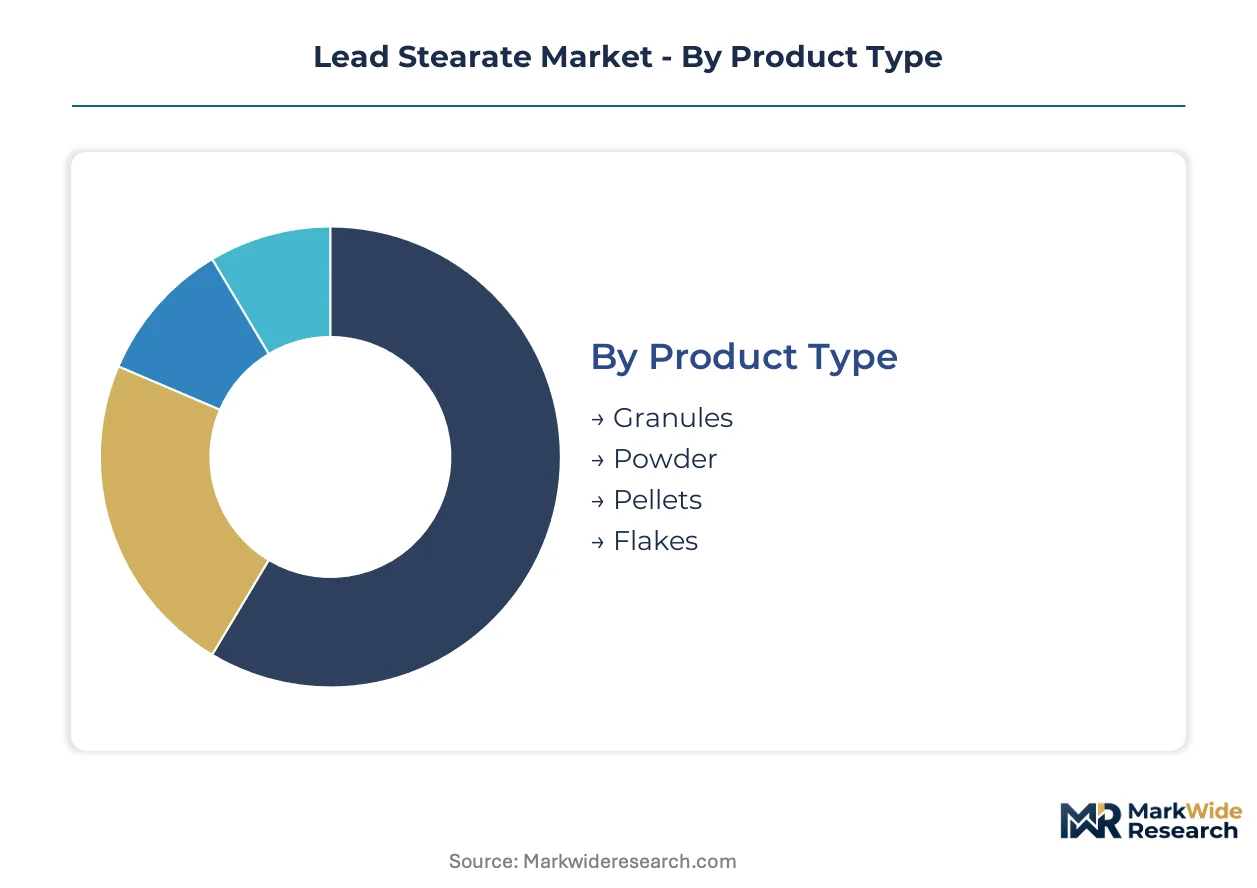
Lead stearate procurement patterns diverge sharply across physical formats and downstream specifications, with inventory velocity varying from continuous-flow powder operations to project-based coating contracts. Understanding these turnover differentials enables suppliers to align production scheduling with working capital constraints.
Product Type:
Powder formats turn inventory fastest in high-volume PVC compounding, while granules and specialized shapes tie up working capital longer due to dedicated extrusion runs and customer-specific qualification protocols.
- Granules:Extruded spherical or cylindrical particles manufactured through melt-compounding processes yield dust-free handling characteristics. German automotive cable producers at Leoni and Prysmian facilities specify this format to satisfy TRGS 900 workplace exposure limits, compressing powder-form margins while rewarding capital-intensive extrusion investments.
- Powder:Micronized particles produced via direct fusion and milling dominate dry-blend PVC operations for rigid pipe and profile extrusion. Chinese provincial utilities expanding potable-water networks under infrastructure plans specify this grade for heat-stabilized formulations in buried distribution lines.
- Pellets:Compressed cylindrical forms serve niche applications requiring controlled dissolution rates in solvent-based systems.
- Flakes:Thin compressed sheets find limited use in specialty coating formulations where gradual dispersion is preferred.
Powder anchors the volume base while granules gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity-grade stabilizer applications from specification-driven coating segments where purity premiums justify dedicated production lines.
- Plastics:PVC heat stabilization consumes the largest share, with rigid pipe and profile extrusion representing the core margin pool. REACH Annex XVII lead restrictions and China's GB standards for plastic products set maximum migration limits that directly determine qualification for food-contact and potable-water specifications.
- Coatings:Corrosion-resistant primers for marine and industrial applications command technical premiums due to lead soap compatibility requirements with epoxy-amine systems. North Sea offshore wind installation accelerates demand for this specification-grade niche where lead replacement remains technically challenging.
- Rubber:Processing aids and mold release applications in tire and industrial rubber manufacturing.
- Adhesives:Specialized formulations requiring metallic soap lubrication in high-temperature bonding operations.
Plastics commands the largest revenue pool while coatings expands most quickly on marine infrastructure investment.
End User:
Customer type concentration shapes technical service intensity, with construction sector procurement consolidating around fewer qualified vendors while automotive demands embedded formulation support.
- Construction:Municipal water infrastructure and building profiles drive bulk consumption. Sinopec's pipe resin customers in China now source through approved distributor hierarchies rather than direct mill relationships, compressing spot-market liquidity.
- Automotive:Wire and cable manufacturers face customer-driven reformulation pressure away from lead-based stabilizers toward mixed-metal alternatives in Scandinavian markets.
- Packaging:Limited food-contact applications constrained by migration limit regulations across jurisdictions.
- Electronics:Battery separator manufacturing in South Korea and Japan consumes metallic soap lubricants for polyolefin membrane processing.
Construction provides the demand foundation while electronics applications climb fastest on lithium-ion cell manufacturing expansion.
Form:
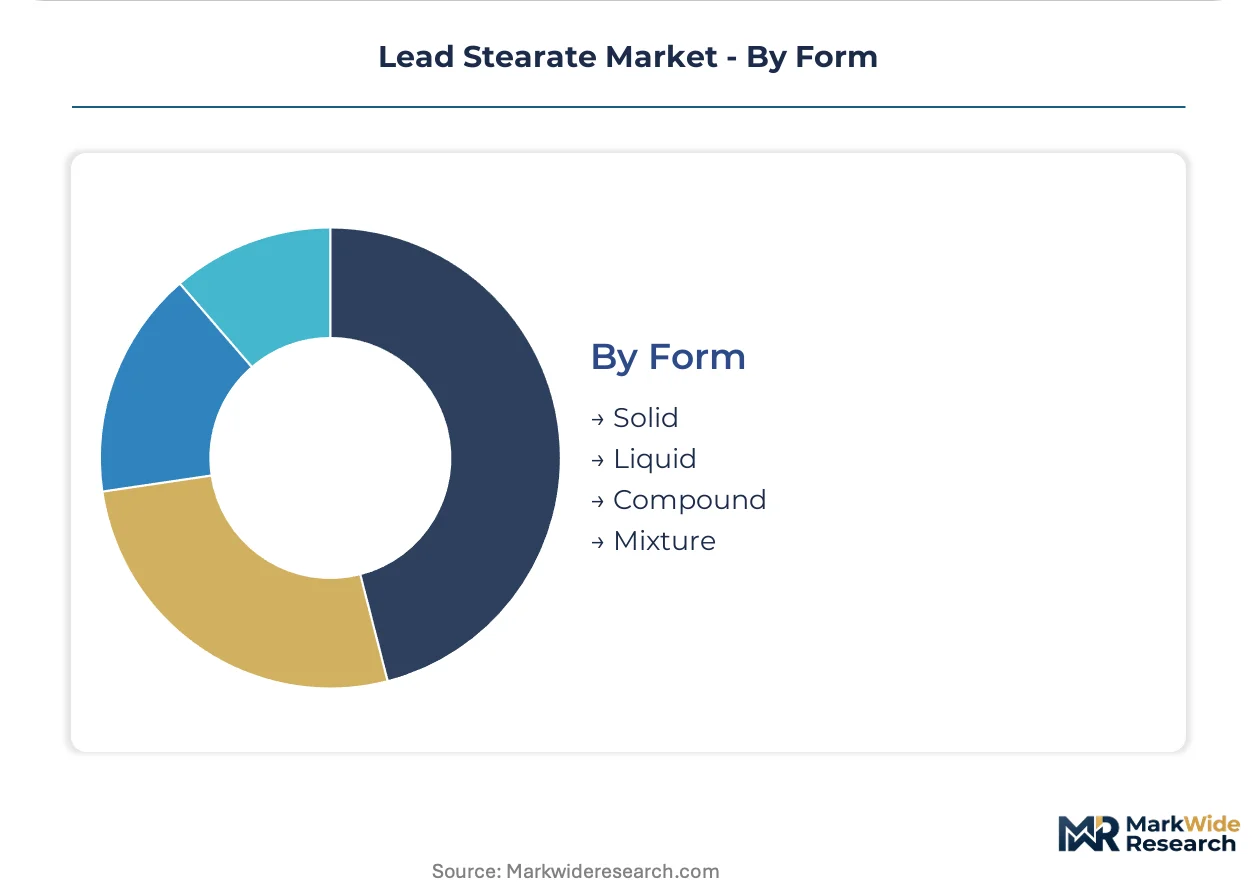
Supply concentration in solid formats reflects manufacturing scale economies, while liquid and compounded alternatives serve specialized dispersion requirements.
- Solid:Crystalline or amorphous metallic soap salts with melting points between 105°C and 112°C serve as the standard reference form for heat stabilizer specifications.
- Liquid:Dispersions in plasticizers or solvents enable direct metering in continuous compounding operations.
- Compound:Pre-blended stabilizer packages containing lead stearate with co-stabilizers and lubricants for single-additive convenience.
- Mixture:Custom formulations tailored to specific PVC resin grades or processing equipment.
Solid forms dominate shipment volumes while compound formats expand fastest on processor consolidation around simplified procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward European compounders who absorb REACH toxicology costs, while Chinese processors extract volume discounts through consolidated provincial procurement. This asymmetry reshapes supplier qualification pathways across jurisdictions.
China
Provincial utilities expanding potable-water networks under the 14th Five-Year Plan specify heat-stabilized PVC formulations for buried distribution lines. GB standards for plastic products set maximum lead migration limits that determine stabilizer grade qualification. Sinopec's pipe resin customers in Jiangsu and Shandong now source through approved distributor hierarchies rather than direct mill relationships.
Germany
Automotive cable producers at Leoni and Prysmian facilities specify granular lead stearate to satisfy TRGS 900 workplace exposure limits. ECHA's 2023 update to REACH Annex XVII tightened migration limits for articles in prolonged skin contact. Dust suppression mandates in North Rhine-Westphalia compounding facilities accelerate granular substitution for powder forms.
United States
Wire and cable manufacturers face customer-driven reformulation pressure toward calcium-zinc alternatives in coastal markets. EPA oversight under the Toxic Substances Control Act constrains new lead compound introductions with Section 5 premanufacture notices extending 180+ days. Valtris Specialty Chemicals anchors supply through captive stearic acid sourcing in the Ohio River Valley.
India
Domestic PVC profile extruders seeking ISI mark compliance for window frames create first-mover advantage for suppliers completing Bureau of Indian Standards factory audits. BIS certification pathways filter out smaller importers who cannot sustain audit costs. Maharashtra and Gujarat house the densest concentrations of compounders upgrading formulations for building code compliance.
South Korea
Lithium-ion cell manufacturing expansion consumes metallic soap lubricants for polyolefin membrane processing in battery separator applications. MFDS oversight of industrial chemical imports shapes supplier qualification timelines. Busan-Ulsan chemical complexes anchor technical-grade demand outside traditional plastics channels.
Lead Stearate Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on specification-grade differentiation. The supplier base concentrates around three tiers: European manufacturers absorbing REACH toxicology costs, North American producers with captive feedstock integration, and Asian compounders competing on volume scale. Two strategic archetypes dominate: technical-service-intensive formulators embedding chemists at customer sites, and scale-driven producers extracting margin through backward integration into stearic acid. Competitive moves center on granular extrusion capacity additions and regional hub strategies that cut lead times for qualified customers.
Among European manufacturers, Peter Greven GmbH & Co. KG and Baerlocher GmbH occupy positions defined by technical service intensity and REACH registration depth. Valtris Specialty Chemicals represents the North American integrated archetype. These three names illustrate how geographic regulatory exposure shapes competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Peter Greven GmbH & Co. KG |
| Pratham Stearchem |
| Valtris Specialty Chemicals |
| American Elements |
| POCL Enterprises |
| Baerlocher GmbH |
| PMC Group |
| AIVIT Group |
| Faci S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European granular extrusion lines is compressing spot availability for automotive cable specifications while Chinese powder producers absorb volume discounts through provincial utility procurement consolidation. This utilization asymmetry rewards backward-integrated stearic acid producers with pricing power in specification-grade tiers while commoditizing standard powder grades.
Pricing Analysis
Configured-to-order granular grades for German automotive cable producers command 15-25% premiums over standard powder quotations due to TRGS 900 compliance documentation and dedicated extrusion runs. Three-tier pricing structure across REACH-certified premium, technical-grade standard, and economy powder levels reflects certification depth and migration-limit testing. Cost compression in standard powder tiers is intensifying because Chinese provincial SOEs bundle stabilizer qualification with compounder certification, collapsing spot-market liquidity. Municipal water infrastructure buyers in China exhibit highest price sensitivity, while marine coating specifiers in the North Sea show lowest sensitivity due to lead-replacement technical barriers.
Supply Chain Analysis
Export-control regimes on lead compound processing equipment limit technology transfer to emerging producers, concentrating advanced granular capacity in Germany, the Netherlands, and Belgium. Raw material flows draw from Malaysian and Indonesian palm oil stearic acid, Chinese litharge, and European tallow derivatives. Single-source vulnerability runs through Malaysian oleochemical clusters exposed to El Niño rainfall disruption. Distribution runs through approved distributor hierarchies in China and direct mill relationships in European automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Granulation technology adoption represents a high-growth disruption as dust-suppression mandates cascade from German TRGS 900 workplace rules into broader EU enforcement, compressing powder-form margins while rewarding capital-intensive extrusion investments.
For Market Incumbents: Entrench specification-grade positioning by embedding formulation chemists at customer compounding sites and completing Bureau of Indian Standards factory audits ahead of domestic PVC profile extruder consolidation. Backward integration into stearic acid insulates margin from palm oil volatility while calcium-zinc substitution pressure in Scandinavian wire and cable markets demands technical service intensity to defend qualified supplier status.
For New Entrants and Emerging Players: Build out corrosion-resistant coating capabilities for North Sea offshore wind marine primer specifications where lead soap compatibility with epoxy-amine systems creates technical moats. India's BIS certification pathway offers the most penetrable entry point among major PVC markets, with Maharashtra and Gujarat compounders upgrading formulations for building code compliance. A go-to-market angle anchored in battery separator lubrication for South Korean lithium-ion cell manufacturing sidesteps entrenched plastics channel competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical-service-intensive formulators with embedded customer-site chemists and REACH registration depth, as PVC processor consolidation around fewer qualified vendors elongates contract durations. Long-term viability across the analysis window favors producers with captive stearic acid sourcing and granular extrusion capacity. The acquisition target archetype combines backward-integrated feedstock control with specification-grade certification infrastructure. The signal to watch as inflection indicator is ECHA migration-limit tightening for articles in prolonged skin contact, which would accelerate purity-tier segregation and reward pre-qualified premium-grade capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Granular Extrusion Capacity Addition | Dust-suppression mandates in German compounding facilities accelerate format substitution and reward capital deployment. |
| Backward Integration into Stearic Acid | Captive oleochemical sourcing insulates margin from Malaysian palm oil price volatility and El Niño disruption. |
| REACH Annex XVII Registration Depth | Toxicological dossier completeness filters marginal importers and concentrates volume with established European manufacturers. |
| Bureau of Indian Standards Certification | Factory audit completion creates first-mover advantage as domestic PVC profile extruders seek ISI mark compliance. |
| Battery Separator Lubricant Qualification | Technical-grade volume outside traditional plastics channels opens on South Korean and Japanese lithium-ion expansion. |
Study Parameters
A standing panel of PVC compounding plant managers, automotive cable procurement leads, marine coating formulators, and distribution channel partners provided ongoing calibration against customs data, SEC chemical sector filings, and ECHA registration databases. Primary interviews with technical service directors and regulatory affairs specialists at stabilizer formulators were cross-checked against secondary sources including trade flow records, Cefic industry reports, and Chinese GB standard updates. Bottom-up volume estimates from end-use application sizing were reconciled with top-down producer capacity assessments.
Scenario bracketing around REACH enforcement intensity, Chinese infrastructure spending cadence, and calcium-zinc substitution velocity established forecast bounds across the projection horizon. Segmentation dimensions modeled include physical format tier, application purity specification, end-use industry concentration, and regional regulatory cluster. CAGRs were derived from application-level demand elasticity analysis and producer capacity utilization trajectories. Forecast inputs incorporated stearic acid feedstock price correlation structures and granular extrusion adoption curves.
Stress conditions across palm oil supply disruption, ECHA migration-limit acceleration, and Chinese provincial procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement timelines and substitution technology performance. Material shifts in EPA TSCA Section 5 review timelines or BIS certification pathway stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tris Nonylphenyl Phosphite Market
Additives
Texture Modifier Market
Additives
1,4 Butanediol Derivatives Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Sodium Diacetate Market
Additives
Tricalcium Citrate Market
Additives
Global Coalescing Agent Market
Additives
Citric Acid Anhydrous Market
Additives
Refinery Fuel Additives Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Europe Choline Chloride Market
Additives
Europe Anti-Caking Market
Additives
Metallic Stearate Market
Additives
Calcium Acetate Market