
 Tallow Amine Market | 2026-2036
Tallow Amine Market Size, Share, and Industry Trends Forecast 2026-2036
Tallow Amine Market Outlook
North America is tilting toward expanded tertiary amine capacity as domestic chemical manufacturers respond to agrochemical formulator demand. AkzoNobel N.V. leverages its integrated alkoxylation network to secure feedstock access across the value chain. Kao Corporation anchors its position through specialized tertiary amine production for personal care applications. Evonik Industries AG competes on R&D intensity in amine derivative development.
Tallow amine denotes fatty amines derived from tallow fatty acids, typically containing C16-C18 alkyl chains with nitrogen functionality introduced through ammonia reaction at 150-200°C; these surfactants function primarily as emulsifiers, corrosion inhibitors, and flotation agents in industrial processes. Primary amines retain mature volume leadership in mining flotation applications where established supply contracts lock in procurement patterns. Tertiary amines capture expanding margin pools in personal care formulations as brand owners prioritize milder conditioning chemistry. Amine blends gain traction in agrochemical adjuvants where multi-functional performance reduces formulation complexity.
EPA registration requirements under FIFRA govern tallow amine use in pesticide formulations, while REACH restricts certain impurity profiles in European imports, compelling suppliers to invest in refined distillation capabilities. India's BIS certification mandates and CDSCO oversight of chemical intermediates create additional compliance layers for market entrants. Stakeholders must monitor regulatory divergence between jurisdictions to optimize product slate and manufacturing location decisions.
Market Dynamics
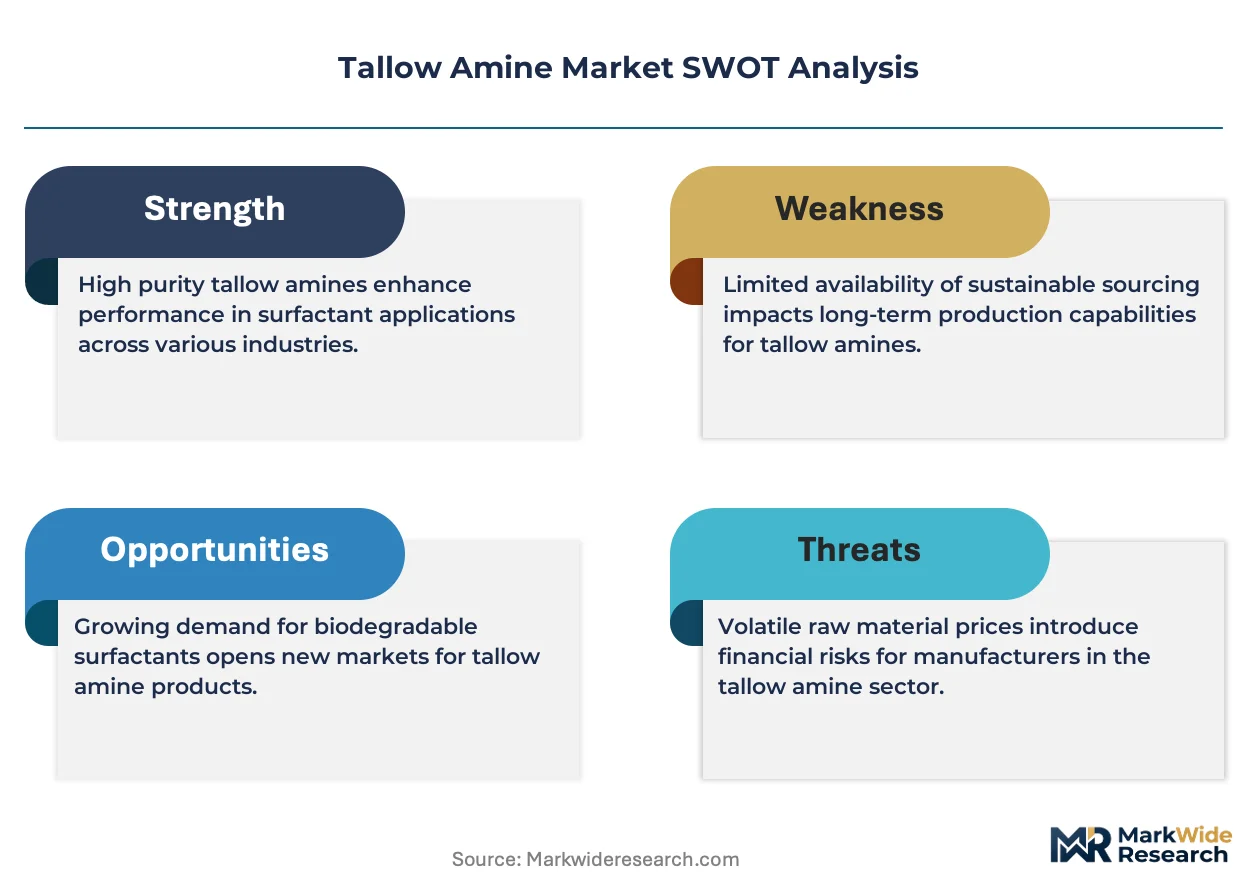
REACH compliance in Europe and EPA registration requirements under FIFRA are compressing supplier margins while simultaneously creating competitive moats for producers with refined distillation capabilities and documented purity profiles.
Growth Catalysts
- Agrochemical Adjuvant Demand:Farmers in India are expanding surfactant use in pesticide formulations as domestic agrochemical production scales rapidly, driving volume pull for amine blends.
- REACH Impurity Restrictions:European import standards are compelling suppliers to invest in higher-purity production, locking in premium positioning for compliant producers.
- Textile Processing Expansion:India's textile processing capacity growth is generating sustained demand for emulsifiers and softening agents derived from tallow amines.
Market Restraints
- Tallow Fatty Acid Volatility:Feedstock costs fluctuate with livestock supply cycles and rendering industry consolidation, squeezing margin predictability for amine producers.
- Substitution by Synthetic Quaternaries:Palm-derived and petrochemical-based amines offer pricing advantages in cost-sensitive personal care applications.
- Regulatory Divergence Friction:Differing purity requirements between EPA FIFRA, REACH, and India's BIS certification create compliance cost stacking for multi-jurisdiction suppliers.
Strategic Opportunities
- India Domestic Manufacturing:CDSCO oversight of chemical intermediates and BIS certification mandates favor local production investments over import-dependent models.
- Personal Care Conditioning Chemistry:Brand owners are prioritizing milder tertiary amine formulations, opening margin pools in premium hair and skin care segments.
- Digital Formulation Platforms:AI-driven surfactant selection tools are enabling faster customer co-development cycles and reducing technical service costs.
Industry Challenges
- Specialized Chemical Engineering Talent:Fatty amine synthesis requires expertise in high-pressure ammonia reactions and distillation optimization that remains scarce in emerging production regions.
- Legacy Equipment Retrofit Costs:Existing primary amine capacity requires significant capital expenditure to pivot toward higher-margin tertiary amine production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tallow Amine Market |
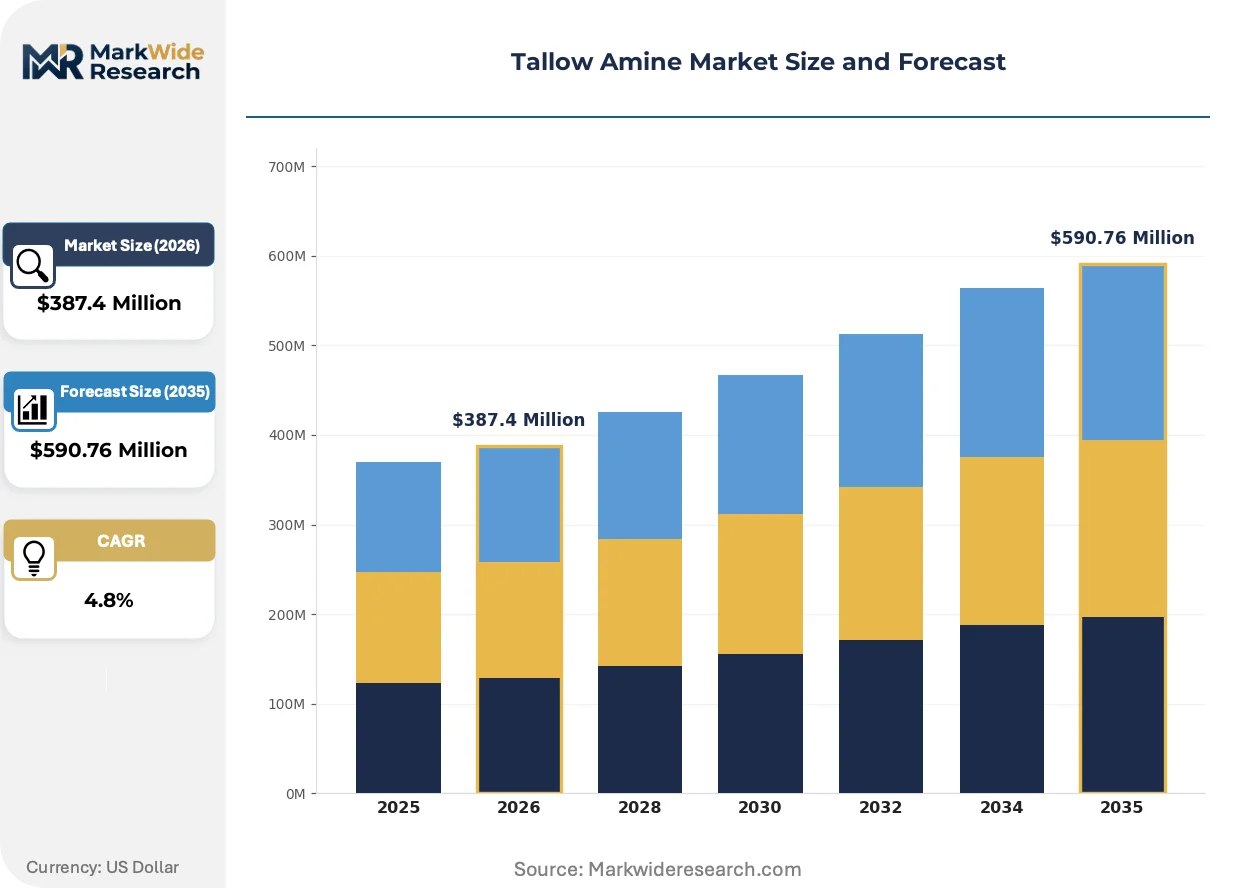
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $590.76 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Amines, Secondary Amines, Tertiary Amines, Amine Blends Application: Textile Industry, Agrochemicals, Paints & Coatings, Personal Care End User: Agriculture, Chemical Manufacturing, Textile Producers, Consumer Goods Form: Liquid, Solid, Gel, Emulsion |
| Companies Covered | AkzoNobel N.V., Kao Corporation, Clariant AG, Evonik Industries AG, Solvay S.A., Huntsman Corporation, Stepan Company, Lonza Group, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tallow Amine Market Strategic Shifts
Digitalization of formulation development and tightening purity mandates are reshaping how tallow amine suppliers engage technical buyers and structure their product portfolios.
Process analytical technology (PAT) is virtualizing quality control workflows in fatty amine production. Agrochemical formulators in the United States are adopting PAT-enabled supplier qualification protocols to accelerate EPA registration timelines. This capability compression is virtualizing the traditional technical service relationship between producers and formulators.
REACH restrictions on certain impurity profiles are tightening specification windows for European imports. Suppliers must now document distillation cut points and residual solvent levels with greater granularity. Agrochemical adjuvant applications face the steepest compliance burden, driving consolidation toward integrated producers with captive analytical capabilities.
Specification-driven procurement is compressing supplier qualification cycles as agrochemical and personal care formulators centralize surfactant buying. Technical data packages and regulatory pre-submission documentation are replacing relationship-based vendor selection in North America and Western Europe. This pattern is most pronounced among multinational agrochemical companies with centralized global procurement functions.
Tallow Amine Market Segmentation
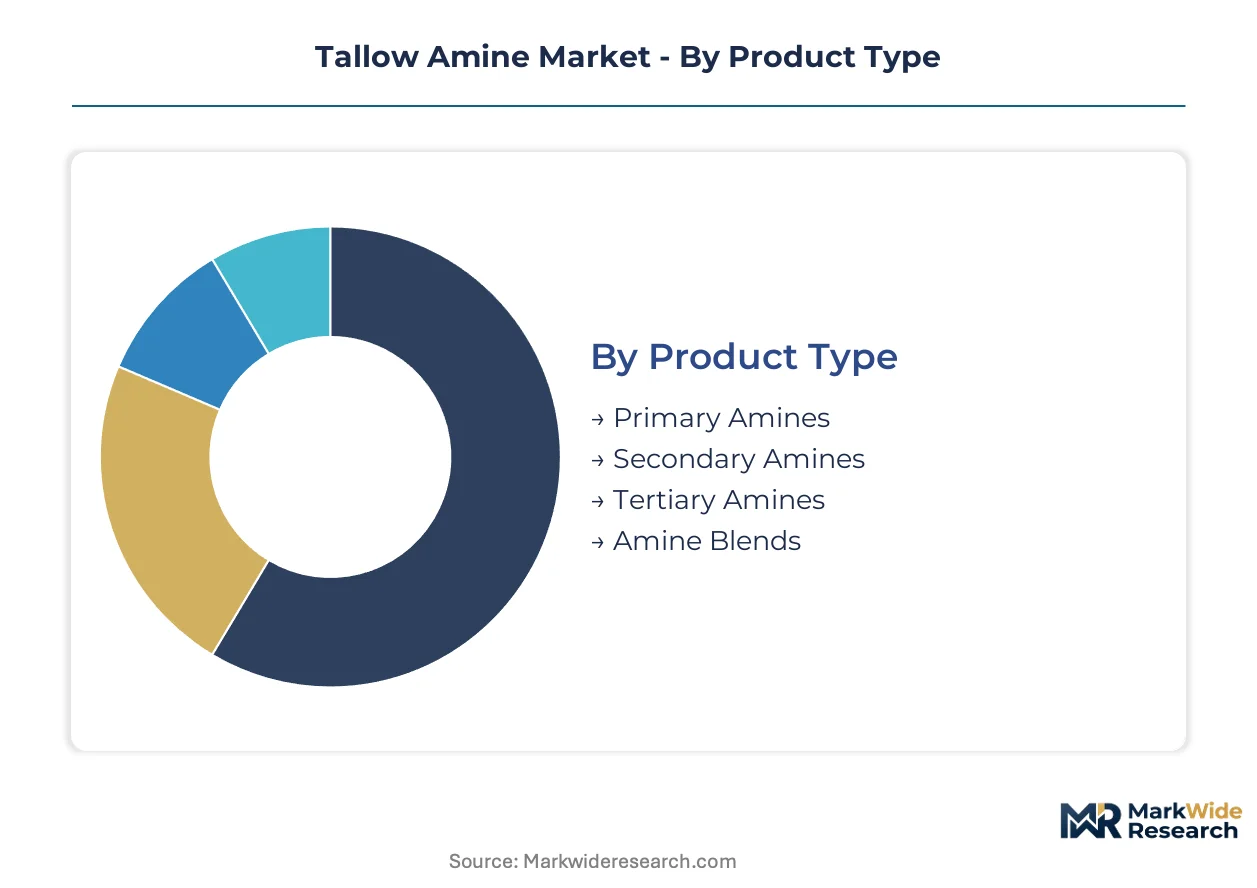
Technical buyers in the tallow amine market require granular segmentation to match nitrogen functionality with specific formulation requirements. Procurement teams prioritize specification alignment over brand loyalty, making segment clarity essential for supplier qualification.
Product Type:
After-sales technical service intensity varies sharply across amine classes, with tertiary amines demanding formulation support while primary amines rely on established specification sheets.
- Primary Amines:These retain free amino hydrogen groups after fatty acid amidation, delivering strong cationic charge density for mineral flotation. Mining operations in Australia specify primary amines for established ore separation contracts where technical service needs remain minimal.
- Tertiary Amines:Fully substituted nitrogen centers enable milder conditioning profiles in personal care. Kao Corporation anchors capacity for this segment as brand owners in Japan prioritize tertiary amine derivatives for premium hair conditioning formulations.
- Secondary Amines:Single hydrogen substitution creates intermediate reactivity for specialized corrosion inhibitor synthesis.
- Amine Blends:Multi-component systems reduce formulation complexity for agrochemical adjuvant producers seeking single-source surfactant solutions.
Primary amines hold the largest share; momentum sits with tertiary amines.
Application:
Cost tier stratification separates commodity agrochemical uses from premium personal care positioning, with purity grades determining pricing bandwidth.
- Agrochemicals:Adjuvant formulations leverage tallow amine surfactants to enhance pesticide droplet spread and leaf penetration. Farmers in India are expanding surfactant loading as domestic pesticide production scales, driving volume pull for standard-grade amine blends.
- Personal Care:Conditioning agents require low-color, low-odor tertiary amine specifications for cosmetic acceptance. Brand owners in Germany enforce REACH-compliant impurity profiles that lock in premium positioning for refined producers.
- Textile Industry:Softening and antistatic applications consume amine quaternaries for fabric finishing processes.
- Paints & Coatings:Dispersant and adhesion promoter functions exploit amine functionality for pigment wetting and substrate bonding.
Agrochemicals dominate volume; personal care commands the steepest margin expansion trajectory.
End User:
Customer type fragmentation concentrates procurement power among multinational agrochemical formulators while textile producers remain geographically dispersed.
- Agriculture:Pesticide manufacturers specify amine adjuvants for glyphosate and dicamba formulations. EPA registration requirements under FIFRA govern surfactant selection, with documented purity profiles accelerating supplier qualification timelines.
- Consumer Goods:Personal care formulators prioritize milder tertiary amine chemistry for conditioning applications. BIS certification mandates in India favor domestic producers with established CDSCO documentation for chemical intermediate imports.
- Chemical Manufacturing:Intermediate producers consume amines for downstream quaternary ammonium compound synthesis.
- Textile Producers:Fabric finishers source emulsifiers and softening agents for garment processing operations.
Agriculture represents the largest demand pool; consumer goods is climbing the fastest.
Form:
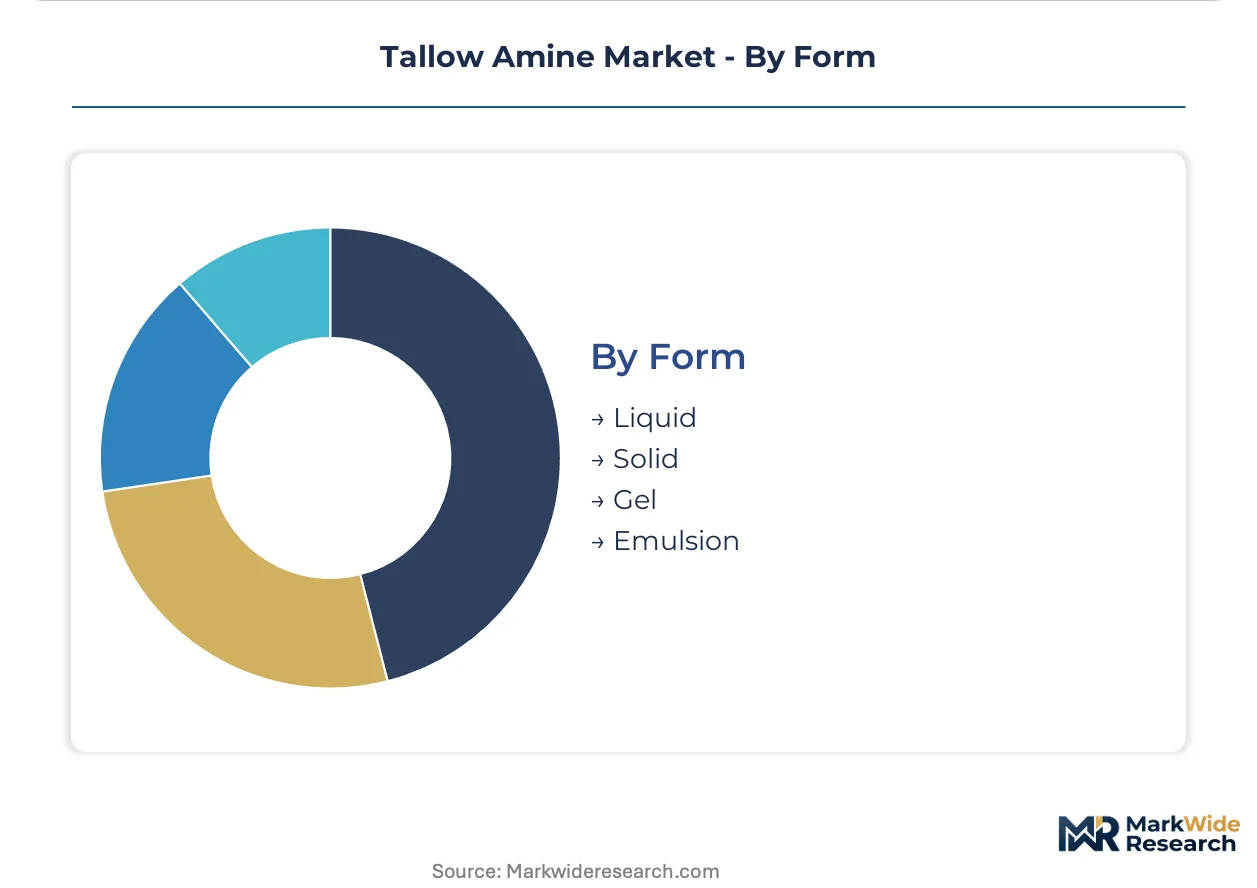
Supply concentration favors liquid handling infrastructure, while solid and gel forms serve niche applications requiring transport stability or controlled release.
- Liquid:Standard bulk delivery format enables efficient metering in continuous agrochemical formulation. Tank farm infrastructure at Indian ports supports import-dependent supply chains for domestic pesticide producers.
- Solid:Flake or pellet forms reduce transportation costs for remote mining flotation operations where on-site dissolution is preferred.
- Gel:Thickened systems enable precise dosing in personal care conditioning products.
- Emulsion:Pre-dispersed formats simplify incorporation into water-based coating formulations.
Liquid holds the largest share; solid forms gain traction in cost-sensitive bulk applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized distillation capacity clusters in Germany, the United States, India, Japan, and Brazil, with each jurisdiction imposing distinct purity mandates that reshape local production economics.
United States
Domestic agrochemical formulators drive tertiary amine consumption for pesticide adjuvant applications. EPA registration requirements under FIFRA compress supplier qualification timelines for surfactant producers. The Gulf Coast chemical corridor hosts expanded alkoxylation infrastructure serving Midwest agricultural markets.
Germany
Personal care brand owners enforce REACH-compliant impurity profiles for conditioning chemistry imports. ECHA oversight of fatty amine derivatives mandates documented distillation cut points and residual solvent thresholds. The Rhine-Ruhr industrial basin concentrates refined amine production for European cosmetic and coating applications.
India
Domestic pesticide manufacturing scales rapidly, pulling volume demand for standard-grade amine blends. BIS certification mandates and CDSCO oversight of chemical intermediates favor local production investments over import-dependent supply chains. Gujarat's chemical manufacturing belt anchors expanded fatty amine capacity serving domestic agrochemical and textile processing clusters.
Japan
Premium hair care formulators prioritize milder tertiary amine specifications for conditioning applications. METI industrial chemical standards govern purity benchmarks for cosmetic-grade imports. The Kansai region around Osaka maintains specialized production infrastructure for personal care surfactant derivatives.
Brazil
Agricultural surfactant demand tracks expansion of glyphosate and dicamba formulation capacity for soybean and corn protection. ANVISA pharmaceutical and chemical intermediate regulations create compliance layers for imported amine raw materials. São Paulo state's agrochemical manufacturing corridor concentrates formulation activity driving adjuvant consumption.
Tallow Amine Market Competitive Environment
Integrated chemical conglomerates and specialized surfactant producers split the market into distinct capability tiers. The vendor base concentrates around producers with captive fatty acid supply and in-house alkoxylation networks. Three archetypes dominate: diversified multinational chemical groups with global distribution infrastructure, regional specialists with formulation technical service depth, and integrated tallow processors with backward control over rendering feedstocks. Competitive moves center on distillation capacity expansion for higher-purity grades and strategic partnerships with agrochemical formulators seeking documented regulatory compliance packages.
Among European-based chemical groups, AkzoNobel N.V. and Evonik Industries AG exemplify the integrated multinational archetype with established alkoxylation and amine derivative capabilities. Kao Corporation represents the Asia-Pacific specialist positioning, anchoring premium personal care surfactant supply. These three occupy positions spanning the value chain from feedstock access through formulated derivative delivery.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Kao Corporation |
| Clariant AG |
| Evonik Industries AG |
| Solvay S.A. |
| Huntsman Corporation |
| Stepan Company |
| Lonza Group |
| Arkema Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European tertiary amine distillation is compressing supplier margins while simultaneously amplifying pricing power for integrated producers with captive alkoxylation networks. This utilization squeeze is redirecting procurement volumes toward India and the United States, where capacity expansions are reshaping regional price benchmarks.
Pricing Analysis
REACH impurity restrictions dictate the pricing tier structure across European imports, separating pharmaceutical-grade specifications from standard agrochemical grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: documented distillation cut points command substantial premiums for personal care formulators in Germany. Cost compression in standard-grade amine blends is intensifying because Indian domestic production is scaling rapidly. Agrochemical adjuvant buyers exhibit highest price sensitivity, while cosmetic brand owners absorb premium positioning for REACH-compliant tertiary amines.
Supply Chain Analysis
Integrated chemical conglomerates in Germany, the United States, and India hold concentrated fatty amine manufacturing capacity, with backward integration into tallow rendering feedstocks determining cost competitiveness. Raw material dependencies center on tallow fatty acid supply from livestock rendering, ammonia for nitrogen functionality, and specialized catalysts for high-pressure amidation reactions. Single-source vulnerability runs through European distillation equipment suppliers, where specialized column engineering expertise remains geographically concentrated. Distribution runs through bulk liquid tank farm infrastructure at port locations, with drum and tote formats serving smaller agrochemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tallow amine market rewards producers with rare expertise in high-pressure ammonia reaction engineering and refined distillation optimization, creating durable barriers for competitors lacking specialized chemical engineering talent pools.
For Market Incumbents: Harden regulatory documentation capabilities to accelerate EPA FIFRA and REACH qualification timelines for agrochemical formulators. Deepen backward integration into tallow rendering feedstocks to insulate margin structures from livestock supply cycle volatility. Prioritize capacity additions in Gujarat's chemical belt to capture India domestic manufacturing incentives under BIS and CDSCO frameworks. For New Entrants and Emerging Players: Pursue contract manufacturing arrangements with established alkoxylation networks rather than greenfield capacity investments. India's agrochemical adjuvant segment offers the most penetrable white-space opportunity, with domestic pesticide production scaling faster than local amine supply. Lead with technical service intensity for tertiary amine formulations to differentiate from commodity primary amine suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated producers with captive fatty acid supply and documented regulatory compliance packages across multiple jurisdictions. Long-term viability hinges on positioning for sustained REACH and EPA specification tightening rather than commodity volume plays. Watch for consolidation signals among mid-tier Indian producers as BIS certification mandates raise compliance barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tallow Rendering | Captive feedstock access insulates margin structures from livestock supply volatility in Argentina and Australia. |
| Distillation Capacity Expansion | Refined cut-point documentation accelerates REACH qualification for German personal care formulators. |
| Long-term Supply Agreement | Contracted offtake with Indian agrochemical producers locks in volume amid domestic capacity scaling. |
| Joint Venture with Alkoxylation Specialist | Partnership with Gulf Coast infrastructure operators secures backward integration without capital-heavy greenfield investment. |
| Green Manufacturing Transition | Process analytical technology deployment reduces solvent residuals for ECHA-compliant impurity profiles. |
Study Parameters
Operator-level perspectives from plant managers at fatty amine production facilities, procurement leads at agrochemical formulators, distribution channel partners in specialty chemical logistics, and technical R&D directors in surfactant applications anchored the qualitative base. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated chemical conglomerates, ECHA substance registration databases, and BIS certification records. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down capacity assessments across major production clusters.
Scenario bracketing around regulatory compliance timelines and feedstock cost volatility shaped the analytical framework across the analysis window. Segmentation dimensions modeled include amine functionality class, end-use industry application, purity grade tier, and regional production hub configuration. CAGRs were derived from slope analysis of normalized consumption intensity trends, with inputs from EPA registration pipeline data for agrochemical adjuvants and METI cosmetic ingredient disclosure patterns for personal care applications.
Sensitivities concentrate around REACH specification tightening timelines, Indian domestic capacity ramp schedules, and tallow fatty acid supply disruptions from livestock disease outbreaks. Forecasts reflect assumptions regarding regulatory divergence persistence and substitution elasticity for palm-derived amine alternatives. Quarterly review of ECHA substance evaluation progress, CDSCO intermediate import licensing volumes, and rendering industry consolidation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Cetyl Esters Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Glycerine Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Estolides Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Synthetic Wax Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Fatty Acid Ester Market