
 Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market | 2026-2036
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market Foresight
Buyer concentration among European industrial bakeries is decoupling from traditional dairy-centric procurement patterns as confectionery and sauce manufacturers diversify their emulsifier supplier rosters. Cargill Inc. leverages its integrated oilseed processing infrastructure to secure backward control over fatty acid feedstocks. Evonik Industries differentiates through synthetic process expertise that tightens esterification yield tolerances. KLK Oleo anchors its position via Malaysian palm oil derivatives that feed tartaric acid ester production lines.
Mixed acetic and tartaric acid esters of mono and diglycerides of fatty acids comprise glycerol-based molecules where one or two fatty acid chains undergo partial esterification with acetic and tartaric acid moieties, yielding hydrophilic-lipophilic balance values between 8 and 12 that stabilize oil-water interfaces in aerated food matrices. Their primary commercial purpose centers on dough conditioning, volume expansion, and shelf-life extension in yeast-leavened and chemically leavened baked goods. Emulsifiers command the largest product type position due to entrenched use in continuous bread production, while stabilizers represent the fastest-expanding category as plant-based dairy analogues proliferate. The liquid form dominates industrial-scale dosing systems, though powder formats are gaining traction in artisan bakery segments where dry-blend convenience reduces handling complexity.
The European Food Safety Authority maintains maximum permissible residue thresholds for tartaric acid derivatives in finished foods, while REACH registration dossiers govern the ecological toxicity profiling of glycerol ester manufacturing intermediates. FDA food additive regulations under 21 CFR 172.830 codify usage limits for acetylated tartaric acid esters in US commerce, creating divergent compliance burdens for exporters serving both Atlantic markets. Stakeholders must monitor evolving purity specifications from EFSA and FDA as clean-label pressures intensify scrutiny of synthetic emulsifier alternatives.
Market Dynamics
Clean-label pressures from European retail chains are compressing synthetic emulsifier tolerance thresholds while simultaneously elevating demand for modified glycerol esters that bridge performance and label transparency. This tension forces reformulation cycles across industrial baking and plant-based dairy analogues.
Growth Catalysts
- EU F-Gas Regulation:Tightened purity benchmarks for food-grade additives accelerate substitution toward bio-derived emulsifiers with documented carbon footprints.
- Industrial confectionery expansion:Aerated chocolate and mousse production lines require HLB-optimized stabilizers that mixed acetic-tartaric esters deliver at scale.
- Malaysian palm oil derivative clusters:Concentrated fatty acid feedstock supply enables integrated esterification economics for tartaric acid ester manufacturers.
Market Restraints
- Glycerol price volatility:Biodiesel co-product supply fluctuations create input cost instability for mono and diglyceride producers.
- REACH registration burdens:ECHA dossier requirements for glycerol ester intermediates impose fixed compliance costs that disadvantage smaller compounders.
- Enzymatic emulsifier substitution:Lipase-modified lecithin variants encroach on volume expansion applications in artisan bread segments.
Strategic Opportunities
- Plant-based dairy analogue proliferation:Oat and almond milk whipping applications generate stabilizer demand that mixed esters capture through aeration control.
- EFSA clean-label incentives:Maximum residue threshold clarity for tartaric acid derivatives rewards early compliance investments with retail shelf access.
- Continuous bread production automation:Liquid dosing system integration creates formulation lock-in with industrial bakery chains seeking operational consistency.
Industry Challenges
- Esterification yield optimization:Tightening acetic-to-tartaric acid ratios requires process engineering talent scarce outside specialty chemical hubs.
- Dual-market compliance synchronization:FDA 21 CFR 172.830 specifications diverge from EFSA thresholds, forcing separate validation batches for trans-Atlantic exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market |
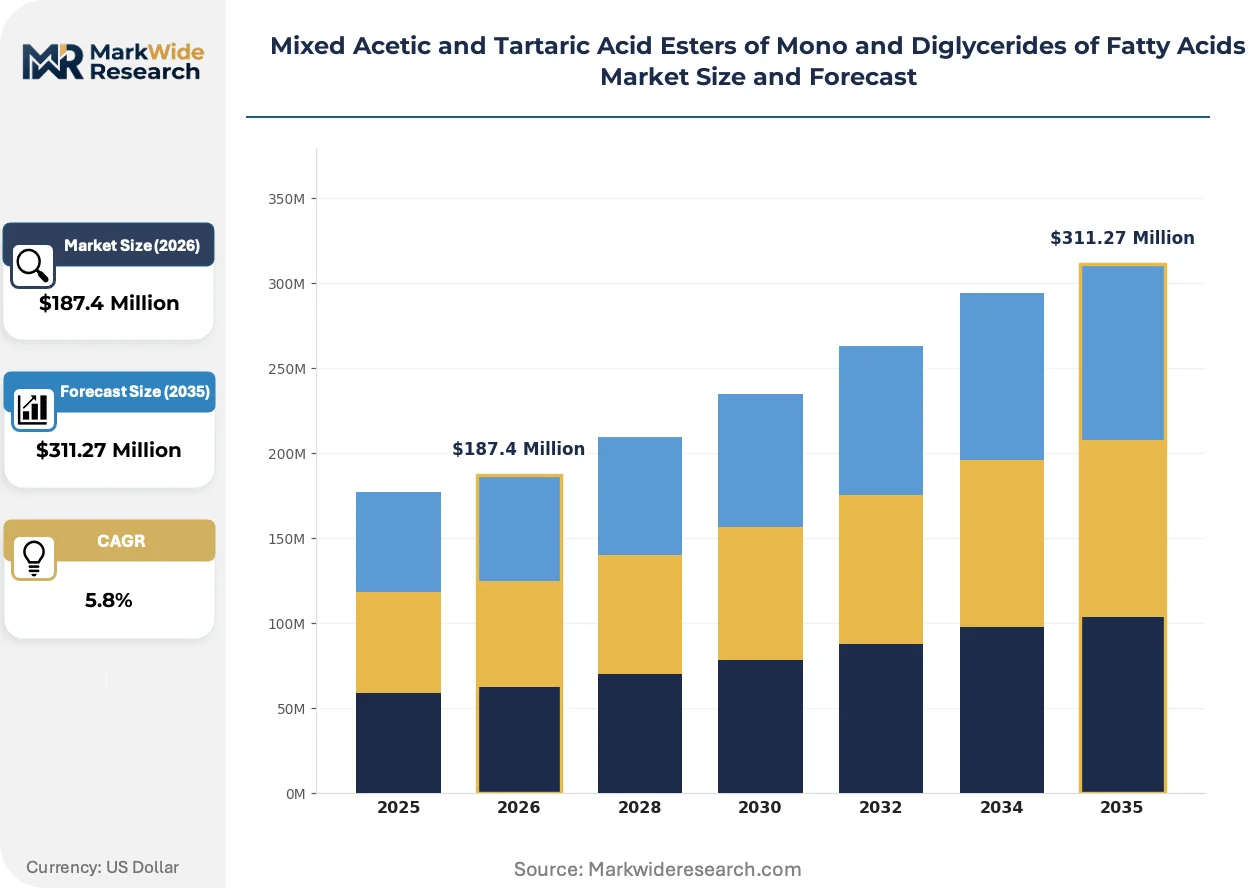
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Stabilizers, Thickening Agents, Preservatives End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Cosmetics Form: Liquid, Powder, Granular, Paste Application: Baking, Confectionery, Dairy Products, Sauces |
| Companies Covered | Fine Organics, Oleon N.V., Cargill Inc., Faci Asia Pacific Pte. Ltd., Estelle Chemicals Pvt. Ltd., DuPont, KLK Oleo, Metroshen International Corporation, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market Shifts & Advancements
Enzymatic synthesis routes are displacing chemical esterification in premium emulsifier tiers, while digital formulation tools compress development cycles. These shifts redistribute value toward bioprocess specialists and away from conventional oleochemical processors.
Membrane filtration technology is integrating into glycerol purification stages, stripping color bodies and odor compounds before esterification. German industrial bakeries adopting this upstream processing report reduced downstream quality variation. The technology is integrating acetic-tartaric ester production into broader oleochemical sustainability certifications.
REACH registration dossiers now mandate expanded ecological toxicity profiling for glycerol ester manufacturing intermediates. Compounders face extended data generation timelines for substances above one tonne annual volume. French and Italian additive distributors are consolidating supplier rosters to limit exposure to registration gaps.
Direct procurement relationships between industrial bakery chains and emulsifier compounders are compressing traditional distributor margins. Specialty ingredient distributors in the Benelux region report volume attrition as buyers seek formulation technical support directly from manufacturers. This pattern concentrates most visibly in Germany's continuous bread production corridor.
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market Segmentation
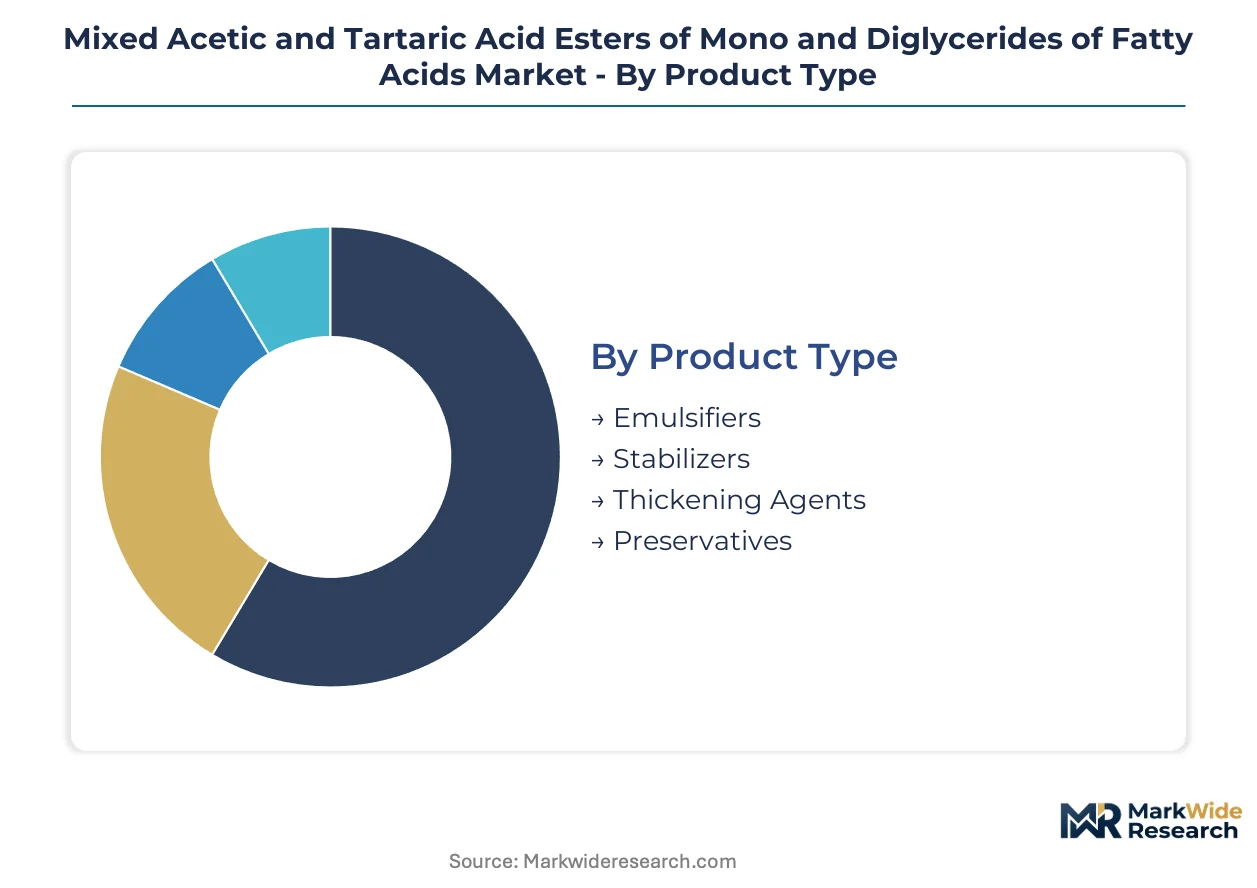
Segmentation in this market tracks how industrial buyers prioritize performance specifications against handling logistics and regulatory compliance. Procurement committees at European bakery chains weight HLB values and dosing system compatibility differently than artisan operators or pharmaceutical formulators.
Product Type:
Buyers select functional categories based on processing temperature thresholds and finished product shelf-life targets.
- Emulsifiers:These acetic-tartaric esters deliver HLB values of 8-12 for oil-water interface stabilization in continuous bread production. Demand concentrates in Germany's industrial baking corridor where dough conditioning specifications are tightening under EFSA scrutiny.
- Stabilizers:Formulations optimized for aerated matrices control bubble structure in plant-based whipped toppings. French and Italian confectionery manufacturers are expanding procurement for mousse and aerated chocolate applications.
- Thickening Agents:Viscosity-modifying variants serve sauce and dressing manufacturers requiring freeze-thaw stability.
- Preservatives:Antimicrobial-functional esters extend shelf life in clean-label bakery products with reduced synthetic additive loads.
Volume sits with Emulsifiers; growth tilts toward Stabilizers.
End Use Industry:
Application environments dictate purity grades and documentation requirements.
- Food & Beverage:Yeast-leavened and chemically leavened baked goods dominate consumption, with clean-label pressures from European retail chains compressing synthetic emulsifier tolerance thresholds. REACH registration dossiers for glycerol ester intermediates impose compliance costs that favor larger compounders serving this segment.
- Pharmaceuticals:Excipient-grade specifications require enhanced purity documentation for tablet and capsule formulations.
- Personal Care:Emollient and surfactant applications in lotions and creams utilize lower-purity grades with broader specification tolerances.
- Cosmetics:Color cosmetic formulations employ these esters for pigment dispersion and texture modification.
Revenue concentrates in Food & Beverage; Pharmaceuticals shows the steepest expansion trajectory.
Form:
Material handling infrastructure and batch size determine format selection.
- Liquid:Pumpable concentrates integrate with automated dosing systems in high-throughput industrial bakeries. German continuous bread producers favor this format for operational consistency.
- Powder:Dry-blend convenience reduces handling complexity for artisan bakeries in France and Italy where smaller batch sizes predominate.
- Granular:Free-flowing particles suit intermediate-scale operations requiring measured dispensing without liquid handling equipment.
- Paste:High-viscosity formulations serve niche applications requiring precise manual incorporation or cold-process compatibility.
Industrial adoption favors Liquid; artisan segments are driving Powder uptake.
Application:
Processing conditions and finished product matrices define functional requirements.
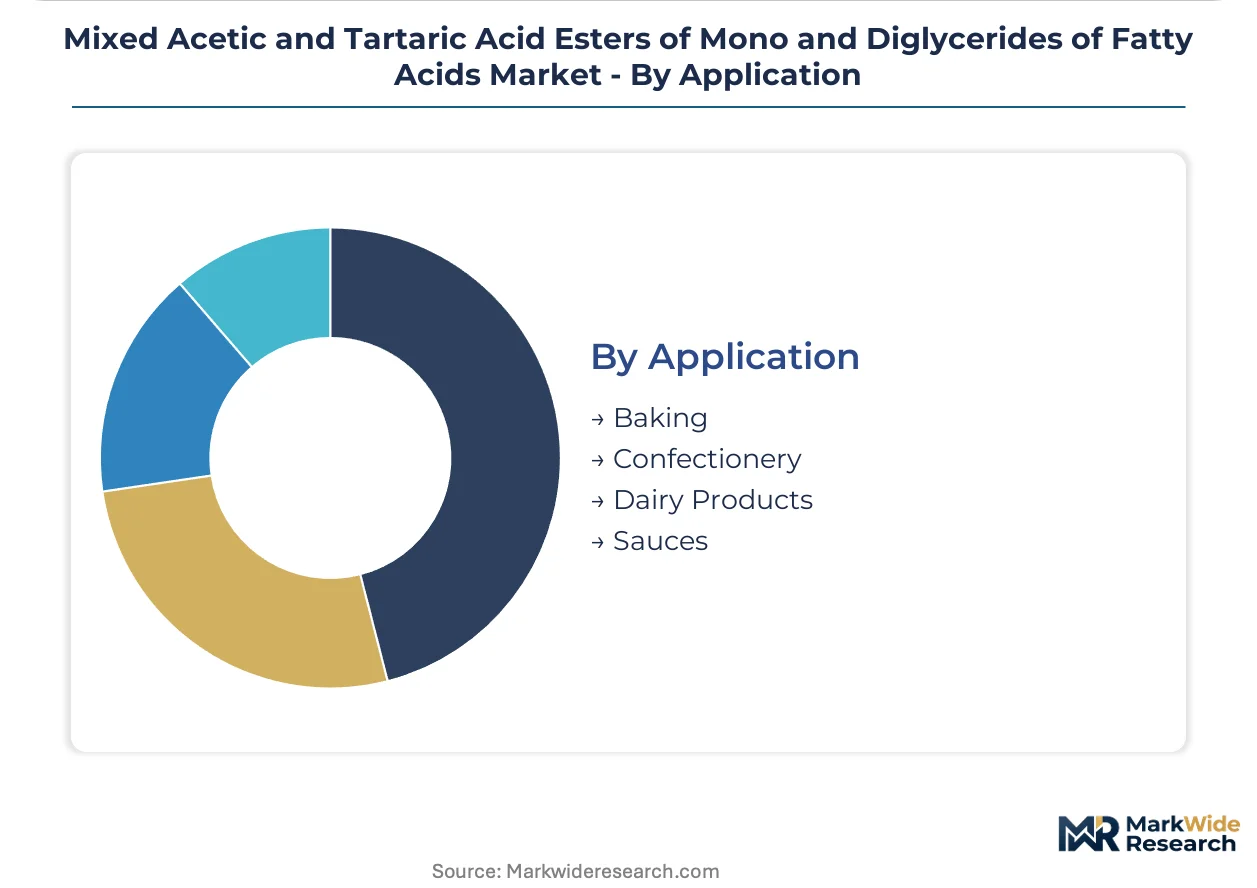
- Baking:Dough conditioning and volume expansion in yeast-leavened systems represent the foundational use case. Industrial chains across Germany, France, and Italy specify these esters for standardized crumb structure.
- Confectionery:Aerated chocolate and mousse production requires precise aeration control that HLB-optimized stabilizers deliver at scale.
- Dairy Products:Plant-based milk analogues utilize these esters for whipping performance and fat globule stabilization.
- Sauces:Emulsion stability in cold-process dressings and heat-processed condiments depends on acetic-tartaric ratio optimization.
Procurement volume centers on Baking; Dairy Products is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakery chains in Germany, France, and Italy concentrate procurement for mixed acetic-tartaric acid esters, while Malaysia and the United States anchor feedstock supply and regulatory divergence challenges for exporters.
Germany
Continuous bread production corridors in North Rhine-Westphalia and Bavaria specify liquid-format emulsifiers for automated dosing systems. EFSA purity thresholds for tartaric acid derivatives tighten formulation requirements for industrial bakers. The country's oleochemical processing clusters around Hamburg and Cologne integrate membrane filtration for glycerol purification.
France
Artisan bakeries in Île-de-France and Auvergne-Rhône-Alpes drive powder-format demand for dry-blend convenience in smaller batch operations. ANSM monitors food additive compliance alongside EFSA frameworks. Lyon-based confectionery manufacturers expand stabilizer procurement for aerated chocolate and mousse production lines.
Italy
Coexistence of industrial and artisan baking in Lombardy and Emilia-Romagna creates bifurcated demand for liquid and powder formats. REACH registration dossiers for glycerol ester intermediates impose compliance costs favoring larger compounders. Bologna's food technology corridor hosts formulation technical support centers serving Mediterranean markets.
Malaysia
KLK Oleo and palm oil derivative clusters in Selangor and Johor enable integrated esterification economics for tartaric acid ester production. The country's national standards body aligns with ASEAN harmonization initiatives for food-grade additives. Penang's oleochemical processing zones feed fatty acid feedstock supply to European compounders.
United States
FDA 21 CFR 172.830 specifications for acetylated tartaric acid esters create divergent compliance burdens for exporters serving Atlantic markets. Industrial bakeries in the Midwest and Southeast specify HLB-optimized emulsifiers for standardized crumb structure. Chicago and Atlanta distribution hubs manage separate validation batches for dual-market synchronization.
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market Competitive Landscape
European producers anchor the premium formulation tier; Asian specialists hold feedstock-integrated positions. The vendor base distributes across integrated oleochemical conglomerates, synthetic process specialists, and regional compounders. Three archetypes dominate: backward-integrated oilseed processors, synthetic esterification experts, and palm-oil-derivative specialists. Competitive moves center on capacity expansion in Malaysian feedstock zones and formulation technical support partnerships with industrial bakery chains.
Within the integrated conglomerate tier, Cargill Inc. and KLK Oleo exemplify backward integration into fatty acid feedstocks. Evonik Industries occupies a position among synthetic process specialists with tightened esterification yield capabilities. Fine Organics and Oleon N.V. represent regional compounders with distribution density across European bakery corridors.
| Leading Market Players |
|---|
| Fine Organics |
| Oleon N.V. |
| Cargill Inc. |
| Faci Asia Pacific Pte. Ltd. |
| Estelle Chemicals Pvt. Ltd. |
| DuPont |
| KLK Oleo |
| Metroshen International Corporation |
| Evonik Industries |
| Others |
Supply & Pricing Matrix
Industrial bakery chains in Germany's continuous bread production corridor wield disproportionate pricing leverage through consolidated liquid-format procurement contracts that compress compounder margins while rewarding scale-compliant suppliers with formulation lock-in.
Pricing Analysis
High-volume liquid contracts for automated dosing systems trade margin for throughput security, while powder formats for artisan segments in France and Italy capture premium spreads through dry-blend convenience. Price differentiation hinges on EFSA purity certification tiers and REACH dossier completeness, with compounders bearing registration costs passing through to smaller buyers. Pricing pressure stems from glycerol price volatility as biodiesel co-product supply fluctuates, forcing reformulation cost absorption. Artisan bakeries exhibit highest price sensitivity due to batch-scale constraints, whereas industrial chains prioritize operational consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam anchor hub-and-spoke patterns serving European bakery corridors, with secondary nodes in Lyon and Bologna handling Mediterranean demand. Feedstock supply concentrates in Malaysia, Indonesia, and Germany—Malaysian palm oil derivatives enable integrated esterification economics, while German oleochemical clusters refine glycerol through membrane filtration. Raw material dependencies rest on fatty acid distillates, tartaric acid, and acetic anhydride. Single-source vulnerability in Malaysian palm oil derivative supply creates tariff exposure risk under evolving EU-ASEAN trade frameworks. Distribution runs through specialty ingredient distributors consolidating supplier rosters to limit REACH registration gap exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over fatty acid feedstocks and glycerol purification infrastructure determines compounder survival as EFSA purity thresholds tighten.
For Market Incumbents: Cement formulation lock-in with German industrial bakery chains through technical support partnerships that embed liquid dosing system integration. Deepen backward integration into oilseed processing or captive glycerol supply to offset biodiesel co-product volatility. Invest in enzymatic synthesis capabilities before lipase-modified lecithin variants capture artisan bread volume expansion applications.
For New Entrants and Emerging Players: Enter via plant-based dairy analogue stabilizers in France and Italy, where aerated oat and almond milk applications lack entrenched supplier relationships. Target confectionery manufacturers in Lyon and Bologna seeking HLB-optimized stabilizers for mousse production. Lead with membrane filtration-equipped glycerol purification as a sustainability credential that commands retail shelf access.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale compounders with incomplete REACH dossiers in Italy and France, where registration cost burdens force consolidation. Long-term viability hinges on feedstock-integrated positions or synthetic process expertise tightening esterification yields. Watch EFSA maximum residue threshold revisions as the inflection signal rewarding early compliance investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's captive fatty acid supply secures margin control against glycerol volatility. |
| Enzymatic Synthesis Route Development | Bioprocess specialists capture premium tiers as chemical esterification faces clean-label pressure. |
| Membrane Filtration Technology Adoption | German industrial bakeries report reduced quality variation through upstream glycerol purification. |
| REACH Dossier Completion Investment | Early ECHA compliance rewards compounders with distributor consolidation tailwinds. |
| Plant-Based Dairy Analogue Formulation Partnerships | French and Italian oat milk manufacturers generate stabilizer demand through aeration control. |
Research Methodology
Document review covered EFSA scientific opinions, REACH registration dossiers, FDA 21 CFR 172.830 specifications, and EU F-Gas Regulation implementation guidance, complemented by interviews with compounder R&D directors, industrial bakery procurement managers, specialty ingredient distributors, and oleochemical plant engineers. Secondary validation drew from customs trade data, SEC filings of integrated oilseed processors, and ASEAN harmonization initiative progress reports. Bottom-up volume estimates from end-use application modeling were cross-referenced against top-down market sizing through glycerol ester production capacity analysis.
Historical capacity utilization trends informed baseline assumptions, then stress-tested against panel input from formulation technical support centers in Bologna and Lyon. Segmentation modeling tracked product type, end-use industry, form, and application dimensions across the projection horizon, with regional regulatory cluster overlays for EFSA, FDA, and ASEAN frameworks. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label substitution rates and enzymatic emulsifier penetration scenarios.
Revisions become necessary when EFSA maximum residue thresholds shift, REACH registration timelines extend, or Malaysian palm oil derivative export policies tighten. Forecasts reflect assumptions about biodiesel co-product supply stability and industrial bakery automation adoption rates. Periodic stress-testing of base assumptions against enzymatic synthesis cost curves and distributor consolidation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
1-Decene Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Europe Wax Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Paraffin Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Octylphenol Ethoxylate Market