
 Oily Waste Cans Market | 2026-2036
Oily Waste Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Oily Waste Cans Market Analytics
North American steel production is shifting toward specialized fabrication for hazardous material containment, tightening supply availability for fire-rated waste receptacles. Justrite Mfg. Co., LLC leverages its vertical integration in metal forming to sustain consistent output of OSHA-compliant oily waste cans. Eagle Manufacturing Company anchors its position through broad distribution across industrial supply channels. Sysbel Corporation competes on certified safety ratings for marine and chemical applications.
Oily waste cans are sealed, self-closing containers constructed from galvanized steel or chemically resistant polyethylene, designed to isolate oil-soaked rags and combustible debris from ignition sources in workshops and factories. Metal cans dominate the product type landscape due to thermal durability and regulatory acceptance, while plastic cans gain traction in corrosive chemical environments where rust resistance matters. Within applications, automotive services and manufacturing facilities represent the mature core, whereas marine operations emerge as a faster-growing niche driven by port authority fire codes and vessel safety mandates.
OSHA standards for flammable liquids storage directly shape product design requirements and certification thresholds for oily waste cans sold in the United States. EPA hazardous waste handling protocols and NFPA fire codes further constrain material choices and venting specifications, elevating compliance costs for non-certified imports. Stakeholders must monitor evolving state-level fire marshal rulings and potential harmonization with international maritime safety standards to anticipate certification burdens and sourcing adjustments.
Market Dynamics
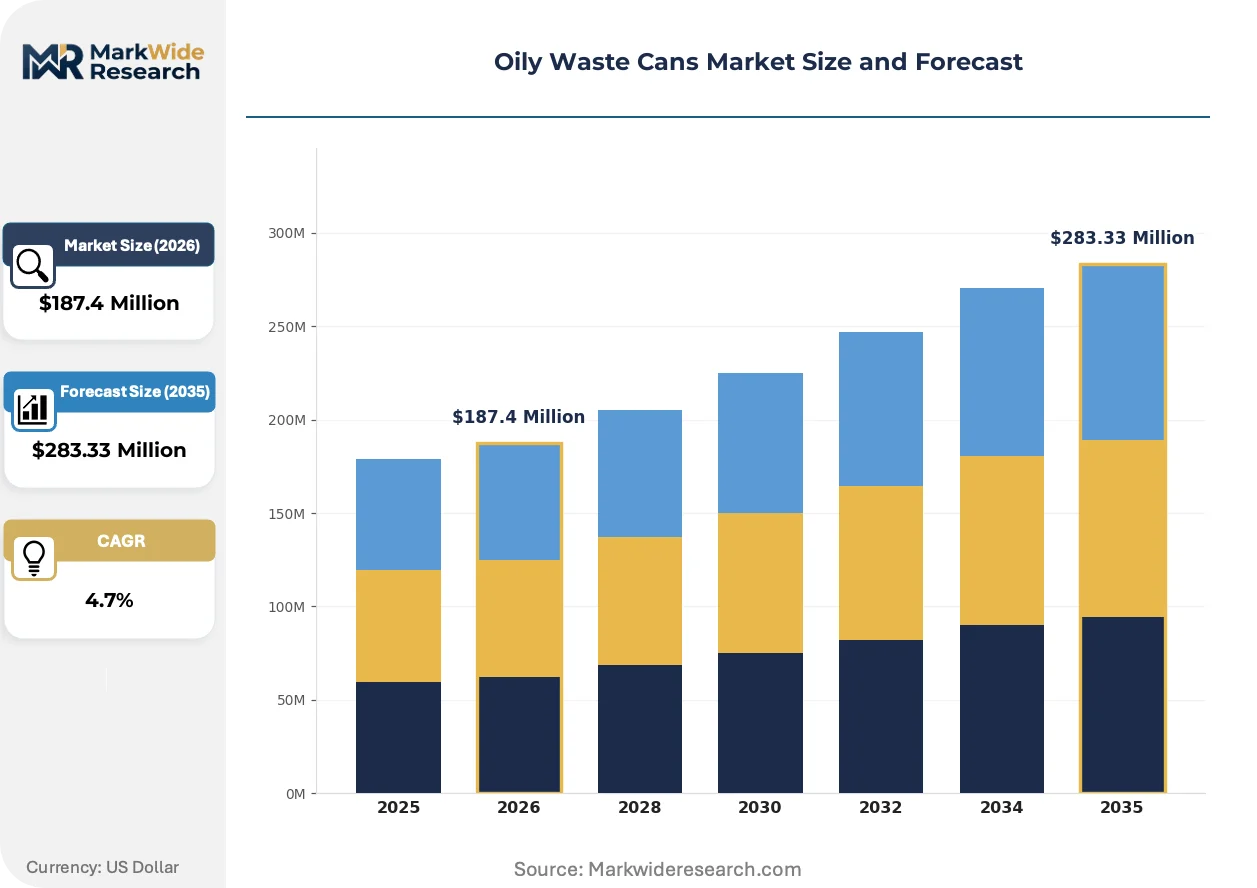
OSHA's flammable waste containment mandates are compressing procurement cycles for certified oily waste cans as industrial facilities accelerate compliance investments ahead of enforcement audits. Steel supply constraints from North American mills are simultaneously tightening availability of fire-rated metal receptacles.
Growth Catalysts
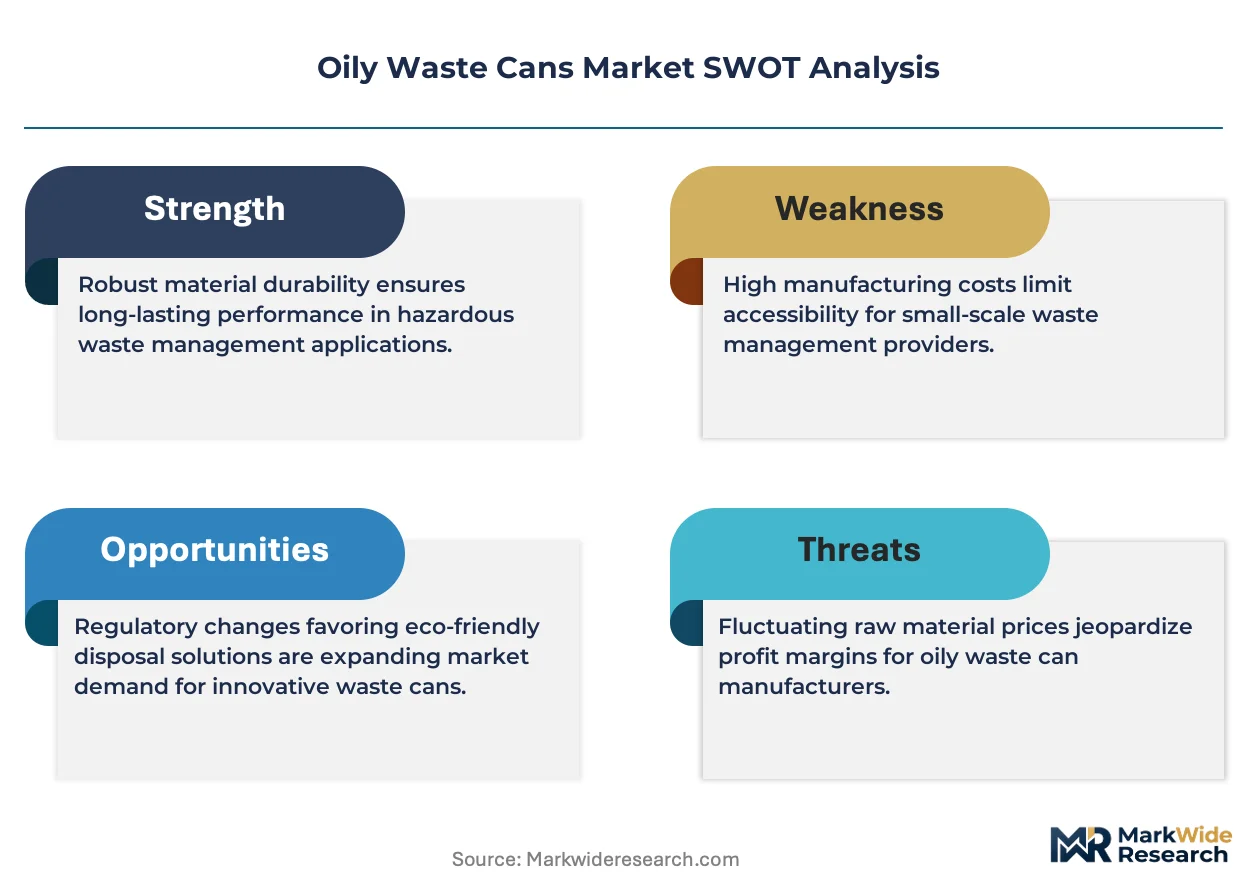
- OSHA 29 CFR 1910.106:The standard mandates self-closing lids and flame arrestors for flammable liquid waste storage, forcing automotive service centers to replace non-compliant containers.
- Marine port authorities:Vessel safety codes in coastal jurisdictions are expanding certified waste can requirements to shipboard maintenance operations.
- Galvanized steel thermal durability:Metal forming advances are extending service life in high-temperature workshop environments versus polyethylene alternatives.
Market Restraints
- Steel input volatility:Hot-rolled coil price swings from North American mills are compressing margins for fabricated receptacle producers.
- Single-source supply risk:Fire-rated steel gauge availability concentrates among specialty rolling mills in the Great Lakes region.
- Polyethylene substitution ceiling:Plastic cans face NFPA thermal performance limits that prevent adoption in high-heat metalworking applications.
Strategic Opportunities
- Underpenetrated chemical processing:Corrosive solvent handling facilities in Texas and Louisiana represent untapped demand for chemically resistant waste containment.
- NFPA 30 harmonization:Alignment between fire codes and international maritime standards would unlock export certification pathways.
- E-commerce industrial distribution:Direct procurement platforms are bypassing traditional supply house intermediaries for mid-volume buyers.
Industry Challenges
- Certification timeline compression:Third-party testing backlog at NRTL facilities is extending product launch cycles.
- Skilled welder scarcity:Precision seam welding for leak-proof construction faces labor pipeline constraints in metal fabrication hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oily Waste Cans Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Cans, Plastic Cans, Drum Containers, Composite Cans Application: Automotive Services, Manufacturing Facilities, Oil Change Shops, Marine Operations Capacity: 5 Gallons, 20 Gallons, 30 Gallons, 55 Gallons Distribution Channel: Direct Sales, Online Retailers, Industrial Suppliers, Wholesale Distributors |
| Companies Covered | Justrite Mfg. Co., LLC, Eagle Manufacturing Company, Sysbel Corporation, DENIOS, Inc., TENAQUIP Limited, VWR International, LLC, P. Henkel GmbH, Hazero Company, Rototec SPA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oily Waste Cans Market Evolving Landscape
Smart sensing capabilities and material science advances are redefining performance benchmarks for hazardous waste containment. Regulatory stringency is accelerating product refresh cycles.
Corrosion-resistant alloy coatings are converging with IoT-enabled fill-level monitoring to enable predictive maintenance scheduling in high-throughput manufacturing environments. Automotive OEMs are piloting these integrated systems at assembly plant maintenance bays. The technology convergence is compressing replacement intervals while elevating compliance documentation capabilities.
EPA hazardous waste generator improvements are tightening manifest documentation requirements for oil-soaked debris tracking. Industrial facilities must now maintain chain-of-custody records linking waste cans to disposal endpoints. Chemical processing plants in the Gulf Coast region are responding by specifying serialized receptacles with integrated tracking labels.
Consolidated procurement through integrated supply contracts is displacing spot purchasing at multi-site manufacturing networks. National distributors are bundling waste containment with absorbents and spill response equipment under single-source agreements. This pattern is most visible among aerospace contractors with dispersed MRO operations across California and Washington state.
Oily Waste Cans Market Segmentation
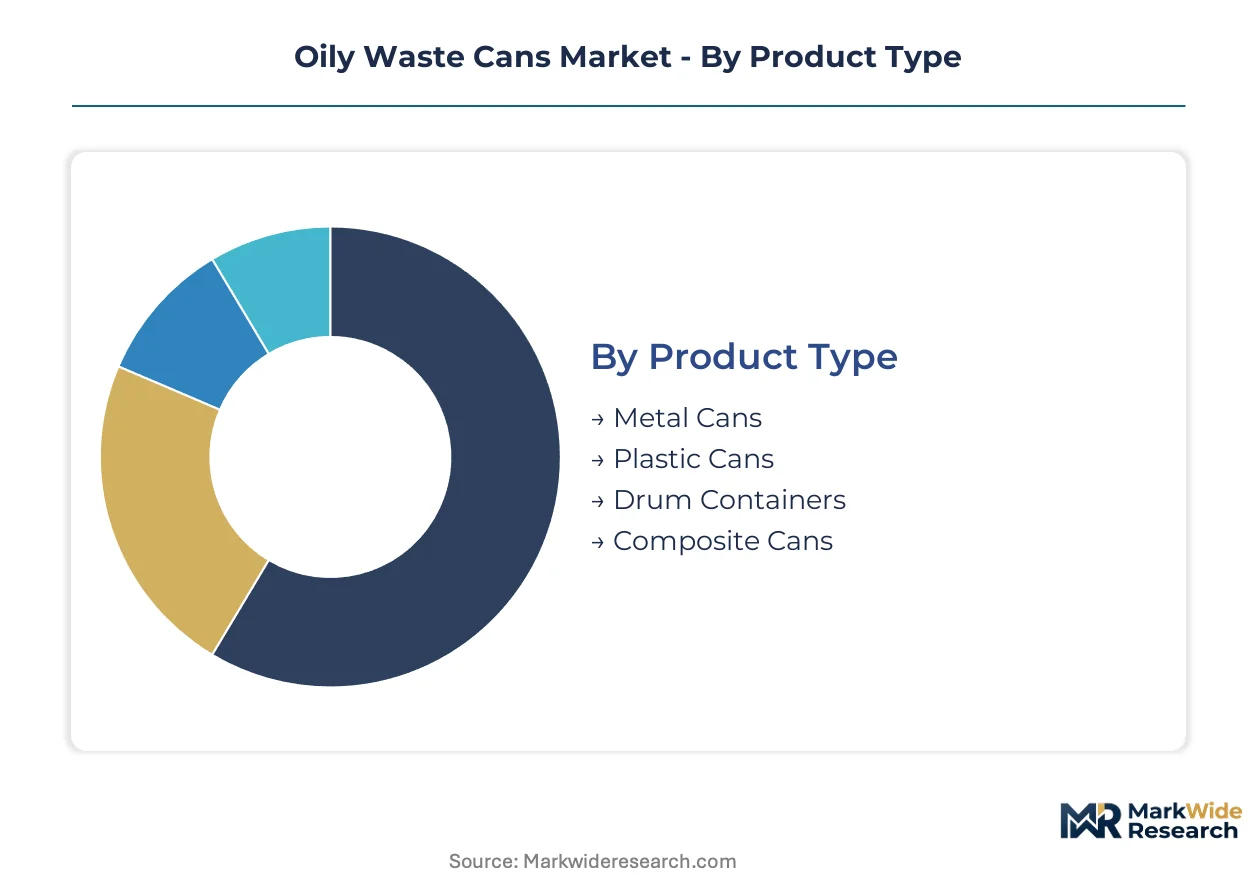
Material specifications and regulatory compliance thresholds drive purchase decisions across the Oily Waste Cans Market. Buyers evaluate thermal performance, chemical resistance, and certification alignment against specific workplace hazards.
Product Type:
Workplace fire codes and thermal exposure profiles determine material selection above cost considerations.
- Metal Cans:Fabricated from galvanized steel with self-closing lids and flame arrestor vents, these containers withstand temperatures exceeding polyethylene limits. Demand concentrates in automotive service centers across the United States where OSHA mandates thermal durability for flammable waste containment.
- Plastic Cans:Molded from chemically resistant polyethylene, these units resist corrosion from solvent-soaked debris in chemical processing environments. Adoption is expanding in Gulf Coast petrochemical facilities where rust prevention outweighs thermal performance requirements.
- Drum Containers:High-volume cylindrical receptacles serve centralized waste collection points at manufacturing campuses.
- Composite Cans:Hybrid constructions combine metal structural elements with polymer liners for specialized chemical resistance.
Volume sits with Metal Cans; growth tilts toward Plastic Cans.
Application:
Regulatory inspection frequency and penalty severity shape procurement urgency by end-use environment.
- Automotive Services:Service bays and quick-lube operations generate continuous streams of oil-soaked rags requiring immediate containment. OSHA enforcement audits at dealerships and independent shops across California and Texas sustain replacement demand for certified receptacles.
- Manufacturing Facilities:Metalworking and assembly plants produce combustible debris at scale, necessitating distributed waste collection points. Procurement concentrates in Midwest industrial corridors where fire marshal inspections drive compliance upgrades.
- Oil Change Shops:High-throughput lubrication services require frequent container rotation and documented disposal chains.
- Marine Operations:Shipboard maintenance and port facility operations face expanding vessel safety code requirements. Port authorities in coastal jurisdictions are mandating certified containment for bilge maintenance and engine room waste, representing the steepest expansion trajectory among application segments.
Procurement scale favors Manufacturing Facilities; compliance pressure peaks in Marine Operations.
Capacity:
Footprint constraints and waste generation rates determine sizing decisions across facility types.
- 5 Gallons:Compact receptacles fit individual workstations and mobile maintenance carts. Deployment concentrates in aerospace MRO operations across Washington state where space optimization and frequent container rotation reduce fire exposure duration.
- 20 Gallons:Mid-size units balance collection interval and handling ergonomics for departmental use. Adoption is climbing fastest in multi-bay automotive service centers seeking to reduce labor costs from excessive container changes.
- 30 Gallons:Intermediate capacity serves centralized collection in medium-scale manufacturing.
- 55 Gallons:Drum-equivalent volumes support high-waste production lines and bulk disposal logistics.
Unit shipments concentrate at 5 Gallons; revenue expansion tracks toward 20 Gallons.
Distribution Channel:
Procurement sophistication and volume scale determine channel selection across buyer segments.
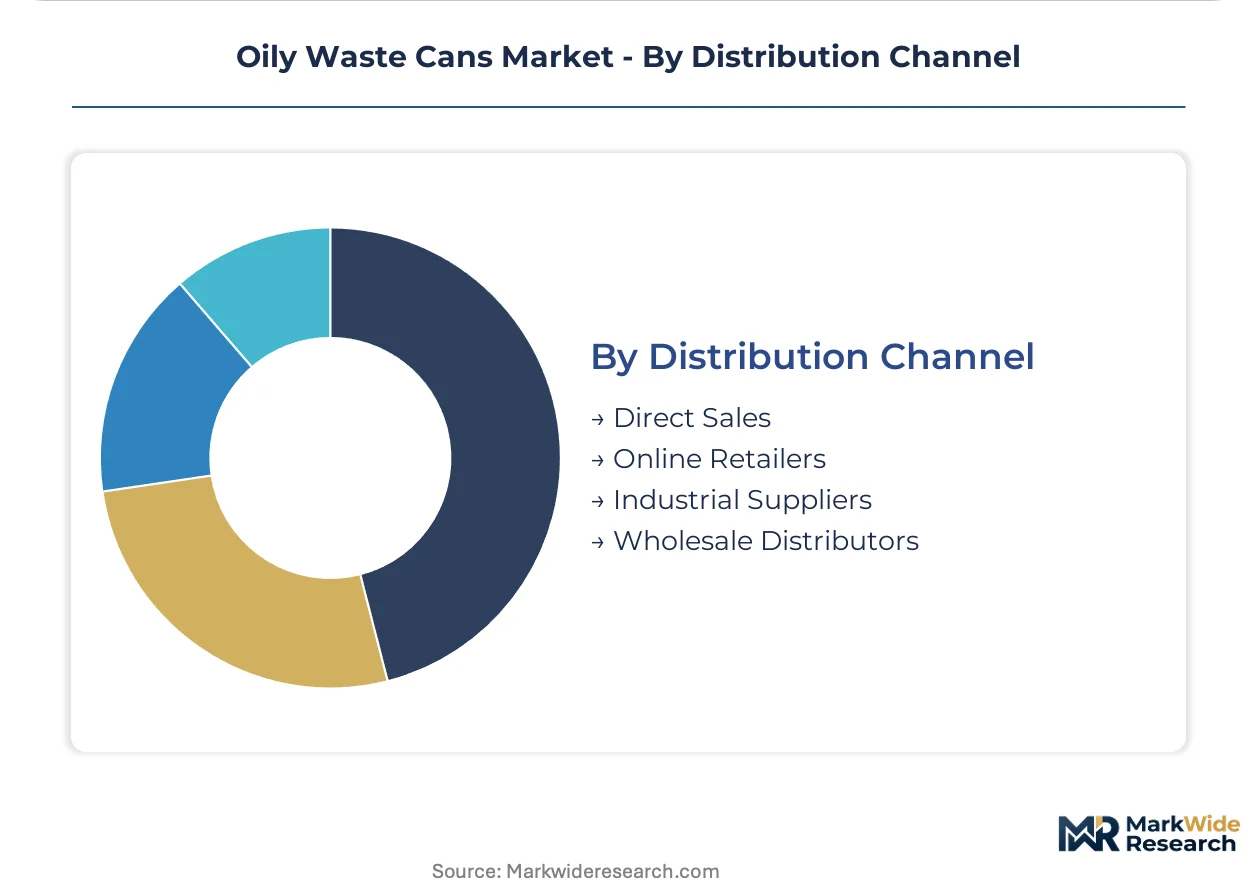
- Direct Sales:Manufacturer-direct relationships serve national accounts with multi-site standardization requirements. Contract penetration is deepest among aerospace contractors with dispersed MRO networks seeking serialized tracking and consolidated billing.
- Industrial Suppliers:Traditional supply houses maintain local inventory and technical specification support. Volume concentrates in Midwest manufacturing belts where established distributor relationships and same-day availability drive purchase loyalty.
- Online Retailers:E-commerce platforms capture mid-volume buyers with transparent pricing and rapid fulfillment.
- Wholesale Distributors:Bulk procurement channels serve regional dealer networks and independent service operators.
Transaction volume flows through Industrial Suppliers; platform growth accelerates at Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Great Lakes steel mills supply the specialized gauge stock that fabricators across North America convert into fire-rated waste receptacles. This feedstock concentration shapes procurement geography for certified containment solutions.
United States
Automotive service centers in California and Texas drive replacement cycles for OSHA-compliant containers ahead of enforcement audits. EPA hazardous waste generator improvements tighten manifest documentation for oil-soaked debris tracking. Gulf Coast petrochemical facilities in Louisiana and Texas specify chemically resistant receptacles for corrosive solvent handling.
Germany
Industrial machinery manufacturers in Baden-Württemberg and North Rhine-Westphalia maintain distributed waste collection points under strict fire marshal inspection regimes. REACH chemical safety protocols constrain material choices for waste containment in chemical processing environments. The Ruhr industrial corridor sustains demand for high-capacity drum containers at manufacturing campuses.
China
Port authorities in Shanghai and Shenzhen are expanding vessel safety code requirements to shipboard maintenance operations. GB standards for hazardous material handling shape certification thresholds for domestic and export-bound containment products. Yangtze River Delta shipyards pilot integrated waste tracking systems for maritime compliance documentation.
Japan
Automotive OEM assembly plants in Aichi Prefecture deploy predictive maintenance scheduling for high-throughput waste containment. METI industrial safety guidelines mandate thermal performance specifications for flammable waste storage in metalworking environments. Kansai region chemical processors specify corrosion-resistant alloy coatings for solvent-soaked debris handling.
Canada
Aerospace MRO operations in British Columbia and Quebec seek serialized receptacles with integrated tracking labels for disposal chain documentation. Health Canada environmental protocols align with EPA hazardous waste handling frameworks for cross-border facility standardization. Ontario manufacturing belts consolidate procurement through integrated supply contracts bundling containment with spill response equipment.
Oily Waste Cans Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized alloy formulations and IoT-enabled monitoring integrations. The vendor base clusters around three archetypes: vertically integrated metal fabricators with captive steel supply, regional specialists in chemically resistant polymer molding, and diversified industrial safety distributors leveraging broad channel reach. Consolidation pressure favors scale players with NRTL certification relationships, while niche openings persist for corrosion-resistant composite innovators. Dominant competitive moves include backward integration into specialty steel gauge sourcing and geographic expansion through distributor acquisition.
Among North American fabricators, Justrite Mfg. Co., LLC and Eagle Manufacturing Company exemplify the integrated-production archetype with in-house metal forming capabilities. Sysbel Corporation occupies a position representing certified safety rating specialization for marine and chemical applications. These three anchors illustrate how competitive positioning stratifies across thermal durability expertise, chemical resistance certification, and distribution network density.
| Leading Market Players |
|---|
| Justrite Mfg. Co., LLC |
| Eagle Manufacturing Company |
| Sysbel Corporation |
| DENIOS, Inc. |
| TENAQUIP Limited |
| VWR International, LLC |
| P. Henkel GmbH |
| Hazero Company |
| Rototec SPA |
| Others |
Value Network & Pricing Analysis
OSHA-mandated self-closing lid specifications and flame arrestor venting requirements are forcing automotive service centers to trade up from economy-grade imports, compelling North American fabricators to source fire-rated steel gauge at premium terms and compressing margins on standard-tier offerings.
Pricing Analysis
Warranty-backed NRTL certification and serialized tracking documentation bundle into premium-tier quotations, while standard offerings ship bare. Three-tier pricing structure across premium, standard, and economy levels separates UL-listed metal fabrication with captive steel supply from distributor-branded imports. Price differentiation hinges on certification tier and volume scale, with national accounts commanding 15-20 point spreads over spot buyers. Cost compression in the economy tier is intensifying because Gulf Coast petrochemical facilities are substituting chemically resistant polyethylene for metal in corrosive environments. Independent quick-lube operators exhibit highest price sensitivity; aerospace contractors with multi-site MRO networks show lowest.
Supply Chain Analysis
Freight absorption for galvanized steel coil from Great Lakes mills to Midwest fabrication hubs adds 8-12 points to landed cost, disadvantaging coastal distributors against regional metal formers. Supply concentrates in the United States, Canada, and Germany, with fire-rated gauge availability tethered to specialty rolling capacity in the Great Lakes region. Raw material dependencies center on hot-rolled steel coil, zinc coating inputs, and chemically resistant polyethylene resin. Single-source vulnerability at NRTL testing facilities creates certification bottlenecks extending product launch cycles. Distribution runs through industrial supply houses with local inventory and same-day availability, though e-commerce platforms are capturing mid-volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty steel gauge scarcity at Great Lakes mills is propping pricing power for certified fabricators with captive supply relationships, creating durable margin structures for incumbents while constraining expansion capacity for aspirants.
For Market Incumbents: Extend backward integration into zinc coating and precision seam welding capabilities to defend against polyethylene substitution in corrosive chemical environments. Lock long-term offtake agreements with automotive dealership networks before NFPA 30 harmonization opens import pathways. Prioritize NRTL certification pipeline investment to compress testing backlog disadvantages. For New Entrants and Emerging Players: Capture underpenetrated chemical processing demand in Texas and Louisiana by specifying corrosion-resistant alloy coatings that incumbent metal fabricators have deferred. Marine port authority mandates for vessel safety codes represent the most penetrable application segment, with shipboard maintenance operations requiring certified containment ahead of enforcement deadlines. Lead through direct e-commerce procurement platforms targeting mid-volume buyers bypassing traditional supply house intermediaries. For Investors and Strategic Acquirers: The window for entry favors vertically integrated metal fabricators with captive steel supply and established NRTL relationships, as certification barriers compound over the projection horizon. Acquisition targets should display fire-rated gauge sourcing security and aerospace MRO contract penetration. Monitor state-level fire marshal ruling harmonization with international maritime standards as the inflection signal for export certification pathway opening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Gauge | Captive supply from Great Lakes mills secures fire-rated coil availability against rolling capacity constraints. |
| NRTL Certification Pipeline Expansion | Reduced third-party testing backlog accelerates product launch cycles ahead of OSHA enforcement audit waves. |
| Corrosion-Resistant Alloy Coating Development | Enables penetration of Gulf Coast petrochemical facilities where polyethylene substitution threatens metal share. |
| Serialized Tracking System Integration | Supports EPA hazardous waste generator documentation requirements for oil-soaked debris chain-of-custody. |
| E-Commerce Platform Launch | Captures mid-volume automotive service centers seeking transparent pricing and rapid fulfillment outside supply houses. |
Research Methodology
Multi-period observation of OSHA enforcement audit frequency, NRTL certification backlog duration, and steel coil price volatility anchored the trend analysis, supplemented by interviews with plant engineers at automotive service centers, procurement leads at aerospace MRO networks, distribution channel partners in industrial supply houses, technical directors at metal fabrication facilities, and compliance officers at marine port authorities. Secondary validation drew from EPA hazardous waste generator reports, OSHA injury and inspection databases, SEC 10-K filings of listed industrial safety distributors, customs trade data for steel and polyethylene imports, and NFPA code revision dockets. Bottom-up shipment estimates by product type and capacity tier triangulated against top-down spending projections by end-use sector.
Segment-weighting across material type, application environment, capacity tier, and distribution channel shaped the analytical framework, with growth rates derived from elasticity modeling against regulatory enforcement intensity and steel input cost trajectories. Industry-specific forecast inputs incorporated fire marshal inspection scheduling patterns at the state level and vessel safety code adoption timelines at coastal port authorities. Volume and value outputs reflect convergence of demand-side procurement cycle analysis and supply-side capacity utilization assessment across the modeling period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel mill capacity expansion decisions, NFPA-international maritime harmonization timing, and polyethylene thermal performance standard revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Glycerine Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
US Esters Market
Oleochemicals
Petrolatum Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Global Palm Wax Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Octylphenol Ethoxylate Market