
 Undecanoyl Chloride Market | 2026-2036
Undecanoyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Undecanoyl Chloride Market Analytics
Buyer concentration in pharmaceutical intermediates is recalibrating as specialty chemical houses consolidate long-term supply agreements with acyl chloride producers. BASF SE leverages its integrated Ludwigshafen complex to sustain captive production of high-purity undecanoyl chloride for internal peptide chemistry programs. Merck KGaA anchors its position through pharmaceutical-grade certification protocols that dominate European research laboratory procurement. Evonik Industries AG competes via specialized packaging and cold-chain logistics for moisture-sensitive acyl chloride shipments.
Undecanoyl chloride is an eleven-carbon acyl chloride (C11H21ClO) synthesized from undecanoic acid via thionyl chloride or phosphorus pentachloride conversion, functioning primarily as an acylation reagent in organic synthesis and pharmaceutical intermediate production. The reagent grade segment occupies stable volume positions across academic institutions and contract research organizations, while pharmaceutical grade commands premium positioning due to stringent residual solvent and heavy metal specifications under pharmacopeial standards. Application demand in chemical synthesis leads absolute volume, though pharmaceutical intermediates represents the fastest-expanding margin pool as peptide therapeutics pipelines broaden.
EPA oversight under the Toxic Substances Control Act shapes domestic manufacturing compliance burdens for acyl chloride emissions and worker exposure limits, while REACH registration requirements in Europe mandate comprehensive safety dossiers for undecanoyl chloride importers. FDA current good manufacturing practice guidelines for pharmaceutical excipients and intermediates further constrain supplier qualification pathways for U.S.-bound material. Stakeholders must monitor evolving biocide regulation overlap and carbon border adjustment mechanisms that could reroute Asia-Pacific supply into alternative purification investments.
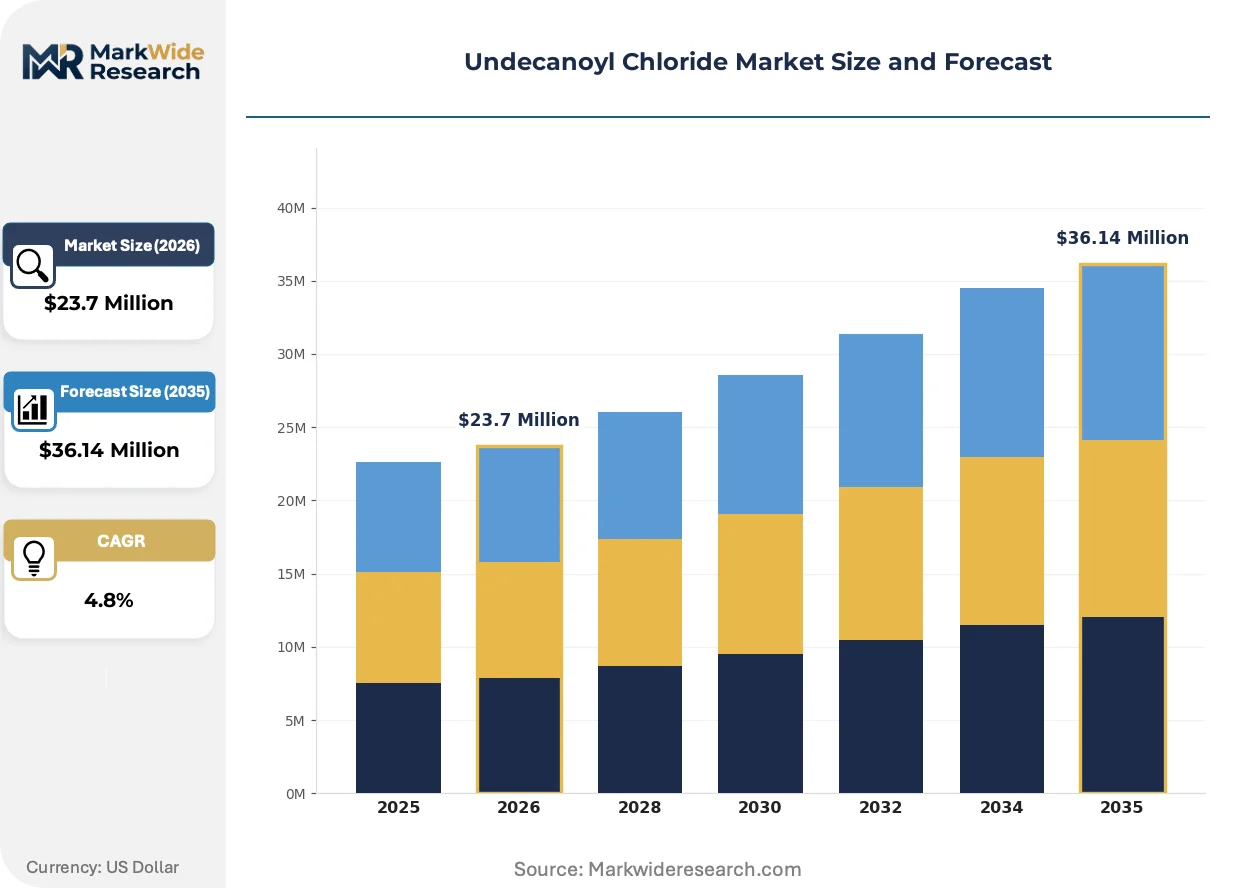
Market Dynamics
Peptide therapeutic pipelines are compressing development timelines and forcing acyl chloride suppliers to certify pharmaceutical-grade purity ahead of traditional qualification cycles, restructuring procurement relationships across the specialty chemical value chain.
Growth Catalysts
- Peptide synthesis expansion:Contract development and manufacturing organizations in the United States specialty chemical corridor are scaling acylation reagent volumes for GLP-1 analog production, pulling undecanoyl chloride into long-term supply agreements.
- REACH registration completion:ECHA dossier acceptance for undecanoyl chloride has unlocked formal import channels into European pharmaceutical intermediates markets, replacing informal trader networks with qualified supplier relationships.
- Thionyl chloride process optimization:Continuous flow reactor adoption at German and U.S. production sites is lowering residual sulfur specifications below pharmacopeial thresholds, expanding addressable market for high-purity grades.
Market Restraints
- Phosphorus pentachloride feedstock volatility:Agricultural phosphate demand fluctuations and energy input costs at Chinese phosphorus processors create raw material price instability that compresses undecanoyl chloride margin structures.
- Moisture sensitivity logistics burden:Cold-chain and inert-atmosphere packaging requirements for acyl chloride shipments impose freight cost premiums that disadvantage smaller volume buyers in fragmented research laboratory segments.
- Substitution by activated esters:N-hydroxysuccinimide ester alternatives in solid-phase peptide synthesis are displacing acyl chloride reagents in certain coupling protocols, particularly at contract research organizations prioritizing handling safety.
Strategic Opportunities
- Indian pharmaceutical intermediates corridor:CDSCO export-oriented unit certification pathways and PLI scheme incentives for active pharmaceutical ingredient manufacturing are attracting acyl chloride suppliers to establish local technical representation.
- Bioconjugation chemistry expansion:Antibody-drug conjugate payload-linker synthesis protocols are incorporating undecanoyl chloride for lipidation modifications, opening oncology therapeutic development as a new demand vertical.
- Carbon border adjustment mechanism preparation:EU importers are qualifying low-carbon-footprint undecanoyl chloride production routes ahead of 2026 CBAM phase-in, creating first-mover advantage for suppliers with verified Scope 3 emissions data.
Industry Challenges
- Pharmaceutical-grade certification timeline:FDA current good manufacturing practice audits and ICH Q3D elemental impurity method validation for acyl chloride suppliers require 18-24 month qualification periods that delay revenue recognition.
- Analytical chemist scarcity:Specialized expertise in gas chromatography-mass spectrometry residual solvent analysis and inductively coupled plasma heavy metal detection for acyl chloride release testing is concentrating at established pharmaceutical houses, constraining new entrant technical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Undecanoyl Chloride Market |
| Market Size in 2026 | $23.7 Million |
| Market Size in 2035 | $36.14 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Grade, Analytical Grade, Industrial Grade, Pharmaceutical Grade Application: Chemical Synthesis, Pharmaceutical Intermediates, Agrochemicals, Specialty Chemicals End User: Pharmaceutical Companies, Chemical Manufacturers, Research Laboratories, Academic Institutions Packaging Type: Drums, Bags, Bottles, Cylinders |
| Companies Covered | BASF SE, Merck KGaA, Dow Chemical Company, Evonik Industries AG, Clariant AG, Arkema Group, Solvay S.A., Eastman Chemical Company, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Undecanoyl Chloride Market Evolving Landscape
Flow chemistry platforms and digital batch records are compressing quality assurance cycles while regulatory data integrity requirements are hardening documentation standards across undecanoyl chloride supply chains.
Continuous flow thionyl chloride conversion systems are decentralizing production scale economics by enabling modular capacity expansion without centralized batch reactor capital commitments. Mid-sized pharmaceutical intermediate suppliers in the United States and Germany are adopting skid-mounted flow units at twice the pace of traditional batch investments. This technology is decentralizing geographic production concentration away from legacy petrochemical corridors toward customer-proximate synthesis hubs.
EMA's updated guideline on elemental impurities in pharmaceutical excipients is tightening arsenic and lead specifications for acyl chloride intermediates entering European medicinal product supply chains. Suppliers must now demonstrate ICP-MS trace analysis capabilities and implement supplier qualification programs for thionyl chloride raw material sources. Pharmaceutical-grade undecanoyl chloride destined for European peptide manufacturers faces the most intensive documentation burden, with some suppliers withdrawing from the specification tier rather than upgrading analytical infrastructure.
Direct sourcing agreements between peptide therapeutic developers and acyl chloride manufacturers are collapsing traditional distributor layers in research chemical procurement. Large contract manufacturing organizations are negotiating multi-year offtake contracts that specify residual solvent limits and heavy metal thresholds exceeding standard reagent grade catalogs. This channel consolidation is most visible in the Boston-Cambridge biotech cluster, where preferred supplier programs now lock in 70 percent of undecanoyl chloride volume through qualified single-source relationships.
Undecanoyl Chloride Market Segmentation
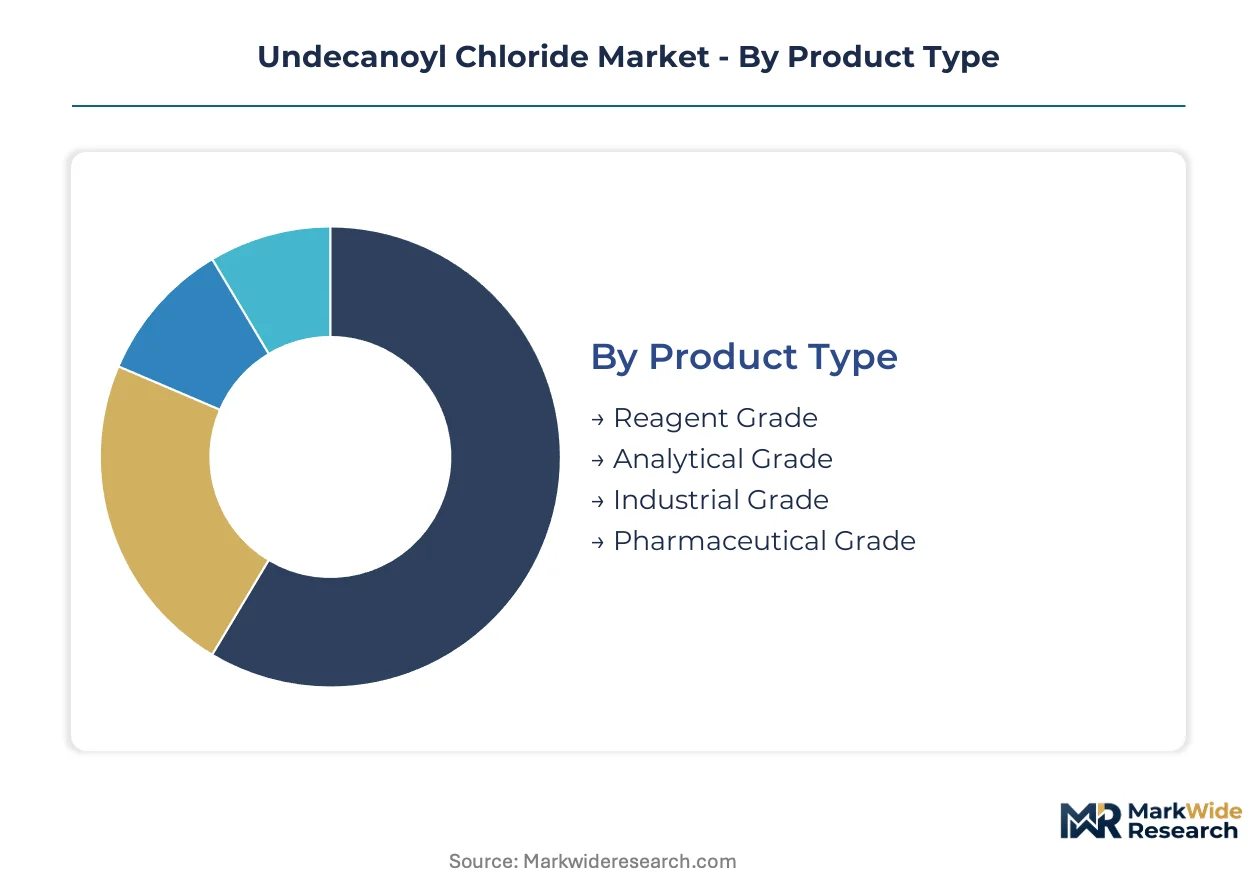
Undecanoyl chloride procurement splits sharply across purity grades and handling requirements, with pharmaceutical certification costs creating tiered supply relationships that reshape competitive positioning. Segmentation discipline reveals where margin pools concentrate and which customer types absorb regulatory compliance burdens.
Product Type:
Supply concentration in pharmaceutical-grade material is tightening as REACH registration and FDA audit requirements eliminate smaller synthesis houses from high-purity tiers.
- Pharmaceutical Grade:Residual solvent specifications under ICH Q3C and elemental impurity thresholds per ICH Q3D dominate release testing protocols. Demand concentrates at CDMOs in the United States specialty chemical corridor and German peptide synthesis clusters, where GLP-1 analog production pulls long-term offtake agreements.
- Reagent Grade:Standard acylation reagent for academic and contract research settings with basic purity verification. Procurement volumes stabilize across research laboratories in Boston-Cambridge and Heidelberg, though moisture sensitivity logistics constrain smaller buyer economics.
- Analytical Grade:Certified reference material for chromatographic method development and validation studies. Gas chromatography-mass spectrometry laboratories at Merck KGaA and BASF SE anchor demand.
- Industrial Grade:Bulk acylation reagent for non-pharmaceutical chemical synthesis with relaxed purity tolerances. Cost-driven procurement from commodity chemical manufacturers in China and India dominates this tier.
Today's leader: Pharmaceutical Grade. Tomorrow's challenger: Reagent Grade as bioconjugation chemistry expands.
Application:
Application demand diverges between volume-led chemical synthesis and margin-led pharmaceutical intermediates, with peptide therapeutic pipelines restructuring procurement relationships.
- Pharmaceutical Intermediates:Acylation reagent for peptide bond formation in solid-phase and solution-phase synthesis. Contract development organizations in Massachusetts and Baden-Württemberg are scaling volumes for incretin analog manufacturing, compressing supplier qualification timelines.
- Chemical Synthesis:General organic acylation for fragrance precursors, polymer modifiers, and specialty ester production. Volume concentration at German and Chinese commodity chemical houses sustains baseline demand.
- Agrochemicals:Intermediate for pesticide active ingredient synthesis, particularly lipid-modified bioactive compounds. Regulatory scrutiny under EPA FIFRA and REACH biocide overlap constrains supplier pathways.
- Specialty Chemicals:Niche acylation applications in cosmetics, flavors, and advanced materials. Fragmented demand across European and North American formulators limits scale economies.
Pharmaceutical intermediates capture the steepest expansion trajectory. Chemical synthesis defends absolute volume position.
End User:
Customer type determines packaging, documentation, and technical service intensity, with pharmaceutical companies extracting the most stringent supplier commitments.
- Pharmaceutical Companies:Integrated drug manufacturers and virtual developers requiring GMP-compliant material with complete regulatory dossiers. FDA pre-approval inspection readiness and EMA variation management dominate supplier selection.
- Chemical Manufacturers:Commodity and specialty chemical producers purchasing industrial and reagent grades for captive synthesis programs. Price-sensitive procurement with limited documentation requirements.
- Research Laboratories:Contract research organizations and discovery chemistry units prioritizing handling safety and rapid delivery. N-hydroxysuccinimide ester substitution threatens acyl chloride share in this segment.
- Academic Institutions:University chemistry departments with irregular, small-volume procurement patterns. Budget constraints and safety officer oversight favor pre-packaged, dilute solutions over neat acyl chloride.
Pharmaceutical companies lock in multi-year supply security. Research laboratories face displacement pressure from activated ester alternatives.
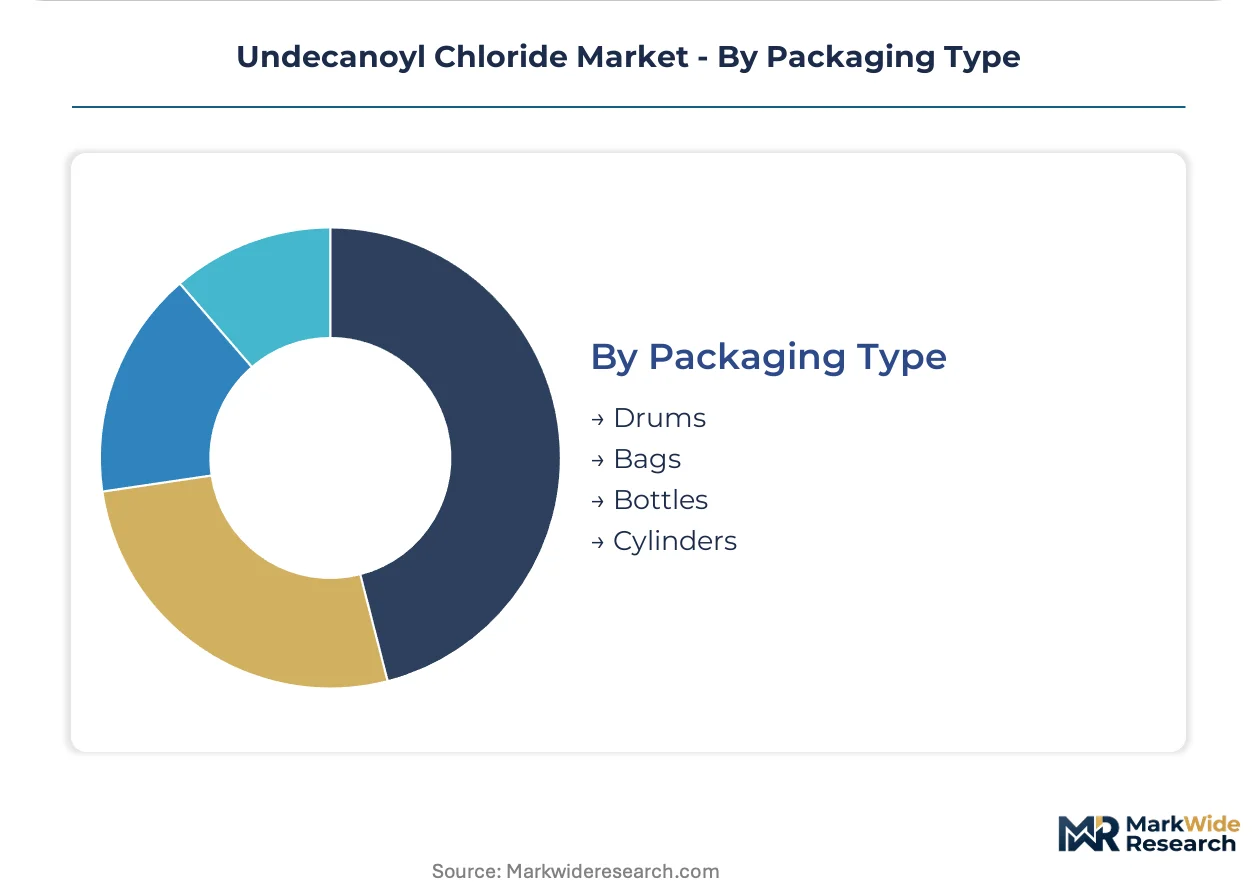
Packaging Type:
Moisture sensitivity and vapor pressure dictate packaging engineering, with inert-atmosphere requirements creating freight cost premiums that segment buyer economics.
- Drums:Standard bulk containment for industrial and reagent grade shipments, typically 200-liter capacity with nitrogen blanket. German and United States specialty chemical distributors dominate drum repackaging.
- Cylinders:Pressurized or sealed vessels for pharmaceutical-grade material with rigorous leak testing and pressure rating certification. Cold-chain logistics integration at Evonik Industries and Merck KGaA anchors this tier.
- Bottles:Laboratory-scale packaging for research and analytical grades, often amber glass with PTFE-lined closures. Breakage risk and shipping weight constraints limit international distribution.
- Bags:Flexible intermediate bulk containers for low-moisture-sensitivity industrial applications, primarily in Asian commodity chemical supply chains.
Cylinders command premium positioning for pharmaceutical security. Drums sustain volume leadership across chemical synthesis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States dominate pharmaceutical-grade undecanoyl chloride procurement, while India and China compete on industrial-grade volume with divergent regulatory compliance trajectories.
United States
GLP-1 analog manufacturing at Massachusetts CDMOs and Texas specialty chemical corridors drives pharmaceutical-grade demand. EPA Toxic Substances Control Act enforcement tightens acyl chloride emissions monitoring at production facilities. The Boston-Cambridge biotech cluster anchors preferred supplier programs locking in multi-year undecanoyl chloride offtake agreements.
Germany
Peptide synthesis scale-up at Baden-Württemberg pharmaceutical houses and Ludwigshafen integrated chemical complexes sustains premium-grade consumption. REACH registration completion through ECHA unlocks formal import channels replacing informal trader networks. Evonik Industries AG at Marl and Merck KGaA at Darmstadt dominate cold-chain logistics for moisture-sensitive shipments.
China
Industrial-grade acylation reagent production concentrates at Zhejiang and Jiangsu commodity chemical processors serving fragrance and polymer modifier markets. Phosphorus pentachloride feedstock volatility from agricultural phosphate demand fluctuations compresses margin structures. NMPA oversight of acyl chloride manufacturing intensifies as pharmaceutical intermediate exports face stricter impurity documentation.
India
CDSCO export-oriented unit certification pathways and PLI scheme incentives for active pharmaceutical ingredient manufacturing attract acyl chloride technical representation. Hyderabad and Ahmedabad pharmaceutical corridors expand peptide therapeutic intermediate production. DGFT export documentation requirements for acyl chlorides tighten ahead of EU carbon border adjustment mechanism phase-in.
Switzerland
Swissmedic pharmaceutical-grade certification protocols dominate European research laboratory procurement for high-purity acyl chlorides. Basel-based bioconjugation chemistry specialists incorporate undecanoyl chloride into antibody-drug conjugate payload-linker synthesis. The country's precision chemical manufacturing tradition supports niche analytical-grade reference material production.
Undecanoyl Chloride Market Competitive Landscape
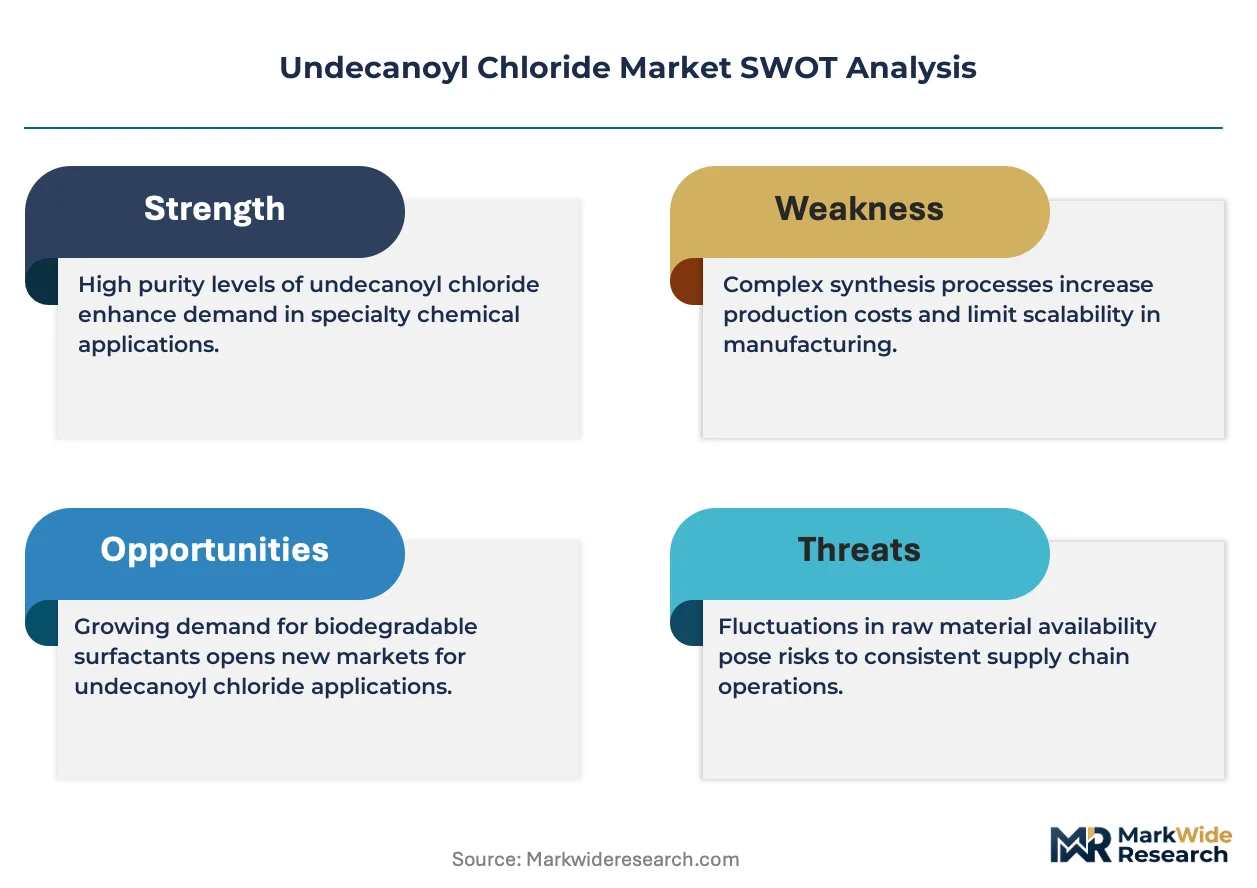
Diversified conglomerates compete with focused pure-play specialists across tiered purity grades, with pharmaceutical certification costs eliminating smaller synthesis houses from premium tiers. The vendor base concentrates around integrated chemical complexes capable of captive thionyl chloride conversion and modular flow reactor adoption. Three archetypes dominate: multinational diversified chemicals with internal peptide programs, pharmaceutical-grade specialists with EMA/FDA audit readiness, and regional commodity producers serving industrial acylation demand. Competitive moves center on backward integration into phosphorus pentachloride or thionyl chloride feedstocks and multi-year offtake contracting with CDMO peptide manufacturers.
Within the diversified chemicals tier, BASF SE anchors European pharmaceutical-grade supply through its Ludwigshafen integrated complex, while Merck KGaA exemplifies audit-ready specialization for research laboratory procurement. Evonik Industries AG occupies a position at the logistics-intensive end, with specialized packaging and cold-chain capabilities for moisture-sensitive acyl chloride shipments distinguishing its service architecture.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Dow Chemical Company |
| Evonik Industries AG |
| Clariant AG |
| Arkema Group |
| Solvay S.A. |
| Eastman Chemical Company |
| Akzo Nobel N.V. |
| Others |
Value Network & Pricing Analysis
Thionyl chloride feedstock costs cascade through undecanoyl chloride pricing tiers, with German and United States pharmaceutical-grade producers absorbing sulfur specification upgrades while Chinese industrial-grade suppliers pass through phosphorus pentachloride volatility from agricultural phosphate markets.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for pharmaceutical-grade material as continuous flow reactor adoption lowers residual sulfur thresholds. Three-tier pricing structure across pharmaceutical, reagent, and industrial grades separates FDA-audit-ready suppliers from commodity acylation reagent producers. Cost compression in industrial-grade tiers intensifies because phosphorus pentachloride feedstock volatility from Chinese agricultural phosphate demand squeezes margin structures. Research laboratories demonstrate highest price sensitivity due to moisture-sensitive logistics premiums, while GLP-1 analog manufacturers at Massachusetts CDMOs absorb certification costs for supply security.
Supply Chain Analysis
Specialized analytical chemist scarcity in Baden-Württemberg and Massachusetts constrains quality assurance throughput at pharmaceutical-grade production sites. Supply concentrates in Germany, the United States, and China, with thionyl chloride and phosphorus pentachloride feedstocks drawing from Ludwigshafen integrated complexes and Zhejiang commodity processors. Single-source vulnerability runs through ECHA-registered European importers dependent on qualified supplier relationships. Distribution runs through specialty chemical distributors for drum repackaging and cold-chain logistics providers for cylinder shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory certification barriers, with EMA's updated elemental impurity guidelines and FDA pre-approval inspection readiness creating tiered supplier lock-in that rewards early compliance investment.
For Market Incumbents: Anchor pharmaceutical-grade positioning through captive thionyl chloride conversion at Ludwigshafen-scale integrated complexes. Deepen backward integration into phosphorus pentachloride feedstocks to defend against Chinese agricultural phosphate volatility. Prioritize ICP-MS analytical infrastructure to meet EMA arsenic and lead specification tightening rather than withdrawing from premium tiers. For New Entrants and Emerging Players: Begin with CDSCO export-oriented unit certification pathways in Hyderabad and Ahmedabad pharmaceutical corridors where PLI scheme incentives reduce capital barriers. Target reagent-grade supply to Boston-Cambridge CROs facing displacement pressure from N-hydroxysuccinimide ester substitutes. Deploy skid-mounted flow reactor units to bypass centralized batch reactor capital requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade certification timelines stretch 18-24 months and analytical chemist scarcity concentrates technical capabilities at established houses. Mid-cap specialists with verified Scope 3 emissions data capture first-mover advantage ahead of EU carbon border adjustment mechanism phase-in. Watch for withdrawal signals from specification tiers as EMA documentation burdens intensify.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Adoption | Modular capacity expansion at German and United States sites lowers residual sulfur below pharmacopeial thresholds. |
| Backward Integration into Feedstocks | Captive thionyl chloride production insulates margin structures from agricultural phosphate demand fluctuations. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA audit readiness locks in multi-year offtake agreements with GLP-1 analog manufacturers. |
| Carbon Border Adjustment Preparation | Verified Scope 3 emissions data qualifies low-carbon production routes for EU import preference. |
| Cold-Chain Logistics Specialization | Inert-atmosphere cylinder packaging secures moisture-sensitive shipments for peptide synthesis applications. |
Research Methodology
Bottom-up peptide therapeutic pipeline modeling reconciled against top-down acyl chloride production tracking forms the analytical core of this study. Primary interviews with peptide synthesis directors at Massachusetts CDMOs, procurement leads at German pharmaceutical houses, regulatory affairs specialists at ECHA-registered importers, and plant managers at Zhejiang commodity processors combined with secondary validation from FDA 483 observation databases, ECHA registration dossiers, SEC 10-K chemical segment disclosures, and German chemical industry association reports. Top-down and bottom-up triangulation reconciles demand-side therapeutic development timelines with supply-side capacity utilization and feedstock cost structures.
Input-output matrices model undecanoyl chloride demand across pharmaceutical intermediates, chemical synthesis, and bioconjugation chemistry applications, segmented by grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from regression analysis of historical volume trajectories against peptide therapeutic pipeline expansion rates and regulatory registration completion timelines across the analysis window. Forecast inputs incorporate thionyl chloride process yield improvements, REACH registration acceptance rates, and CDSCO export-oriented unit certification velocity.
Several conditions sit outside the modeled scope, including unannounced peptide therapeutic clinical trial failures, abrupt phosphorus pentachloride export restrictions from Chinese processors, and accelerated N-hydroxysuccinimide ester substitution in solid-phase synthesis protocols. Forecasts reflect assumptions about regulatory timeline stability and feedstock cost pass-through mechanisms. Material deviation in FDA inspection backlog clearance or EMA elemental impurity guideline enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Esters Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
1-Decene Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Oleophilic Materials Market