
 Cetyl Esters Market | 2026-2036
Cetyl Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Cetyl Esters Market Outlook
Specialized esterification chemist availability is collapsing across European and North American manufacturing hubs, constraining batch consistency for high-purity cetyl esters. Croda International plc leverages backward integration into vegetable feedstocks to sustain margin stability. Koster Keunen anchors its position through beeswax-derived cetyl ester specialization. KLK OLEO competes on palm-oil-based scale from Southeast Asian oleochemical complexes.
Cetyl esters comprise fatty acid esters of cetyl alcohol (hexadecanol), typically produced via acid-catalyzed esterification or transesterification at 120–180°C, functioning primarily as emollients, viscosity builders, and opacifiers in topical formulations. Cetyl palmitate dominates product type volume due to its prevalence in premium cosmetic creams, while cetyl stearate captures faster growth from pharmaceutical ointment demand. Cosmetics and personal care applications concentrate margin pools, whereas food industry usage remains nascent and specification-constrained.
REACH registration through ECHA governs cetyl ester import and formulation thresholds across Europe, while FDA cosmetic ingredient review shapes U.S. market access pathways. BIS purity standards in India and evolving ASEAN cosmetic directives in Southeast Asia add compliance layers for multi-territory suppliers. Stakeholders must monitor feedstock volatility between palm, coconut, and synthetic alcohol routes while tracking regulator shifts on natural-origin certification claims.
Market Dynamics
Specialized esterification chemist availability is collapsing across European and North American manufacturing hubs, constraining batch consistency for high-purity cetyl esters and forcing formulators to consolidate supplier relationships around backward-integrated producers with captive technical talent.
Growth Catalysts
- REACH purity thresholds:ECHA registration requirements for cetyl ester imports into Europe are filtering out low-grade suppliers and concentrating demand among certified manufacturers capable of documenting vegetable-origin chain of custody.
- Clean-label cosmetic reformulation:Branded personal care manufacturers in Germany, France, and the United States are systematically replacing petrolatum-derived emollients with cetyl palmitate and cetyl stearate in premium skin creams.
- Pharmaceutical ointment specifications:Cetyl stearate demand from topical drug formulators is accelerating as USP-grade requirements tighten for dermatological applications requiring stable viscosity profiles.
Market Restraints
- Palm oil price volatility:Feedstock cost swings in Malaysian and Indonesian oleochemical complexes transmit directly to cetyl ester margins, compressing profitability for non-integrated compounders.
- Beeswax supply concentration:Koster Keunen's dominance in beeswax-derived cetyl ester specialization creates single-source risk for formulators requiring halal or vegan certification pathways.
- Transesterification yield ceilings:Acid-catalyzed processes at 120–180°C face thermodynamic limits that prevent cost-efficient scale-up beyond current commercial batch sizes.
Strategic Opportunities
- ASEAN cosmetic directive alignment:Emerging harmonization across Southeast Asian regulatory frameworks is opening consolidated market access for suppliers holding multi-territory compliance dossiers.
- Food-grade specification development:BIS purity standards in India and evolving FSSAI emulsifier approvals are creating first-mover advantage for ester producers capable of meeting ingestible-grade thresholds.
- Enzymatic esterification convergence:Lipase-catalyzed processes combined with membrane separation technology are enabling cold-process cetyl ester production with superior color and odor profiles for fragrance-sensitive formulations.
Industry Challenges
- Esterification chemist scarcity:European technical universities have shuttered specialized oleochemistry programs, shrinking the talent pipeline for process optimization and scale-up troubleshooting.
- Multi-jurisdiction certification timelines:Parallel REACH, FDA cosmetic ingredient review, and BIS registration processes extend product launch cycles by 18–24 months for new cetyl ester variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetyl Esters Market |
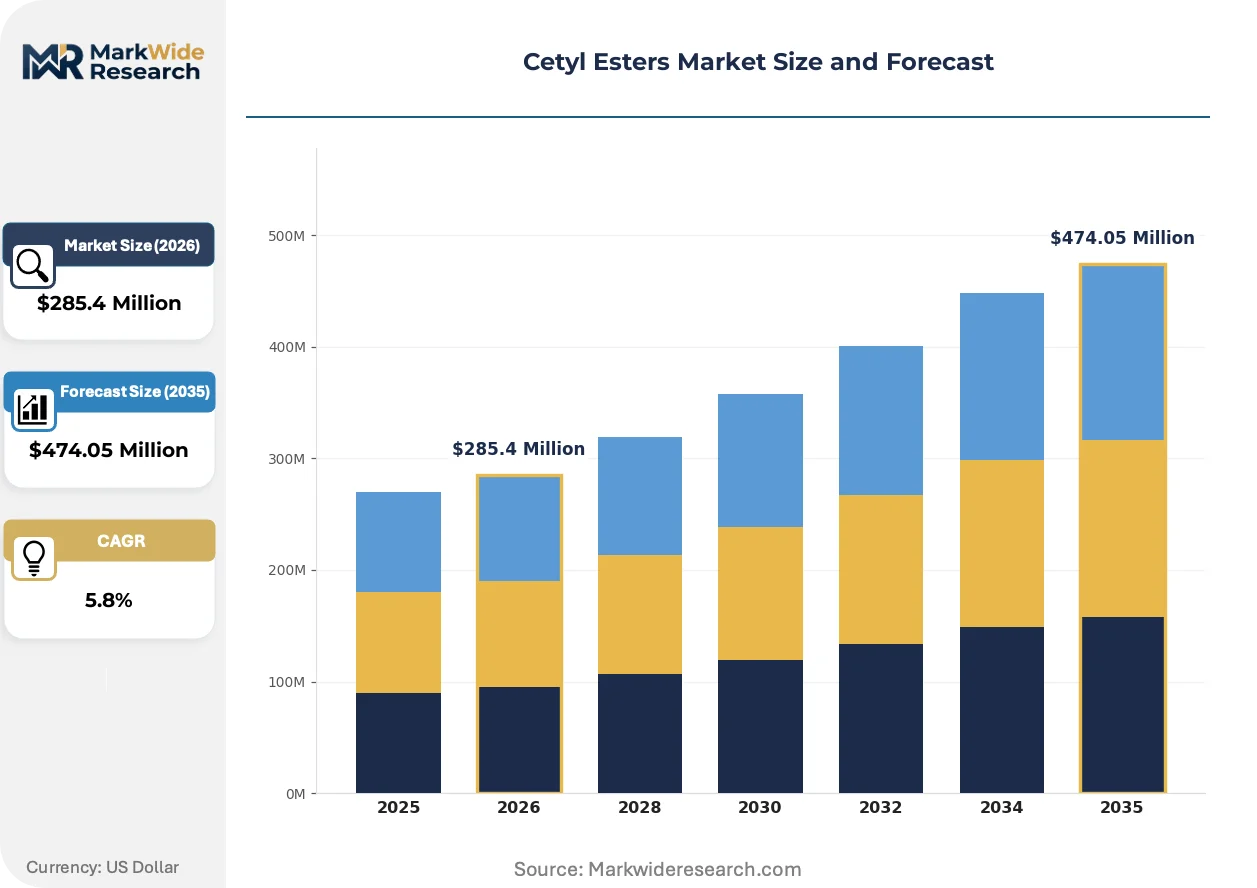
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cetyl Alcohol, Cetyl Palmitate, Cetyl Stearate, Cetyl Myristate Application: Cosmetics, Pharmaceuticals, Food Industry, Personal Care End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Liquid, Cream, Powder, Gel |
| Companies Covered | R.I.T.A, AQIA, Koster Keunen, Jeen International, Protameen Chemicals, Croda International plc, Strahl & Pitch, KLK OLEO, Vantage Specialty Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetyl Esters Market Strategic Shifts
Enzymatic process technology is decomposing traditional acid-catalyzed production economics, while regulatory fragmentation across REACH, FDA, and ASEAN frameworks is reshaping competitive access patterns. Formulator procurement criteria are hardening around documented vegetable-origin chain of custody.
Enzymatic esterification using immobilized lipase biocatalysts is decomposing the cost advantage of conventional sulfuric acid-catalyzed processes. Premium cosmetic formulators in France and Switzerland are adopting cold-process cetyl palmitate at 3–5% price premiums for superior color stability. This technology is decomposing batch-to-batch variability tolerance among mid-tier suppliers unable to fund biocatalyst capital expenditure.
REACH registration through ECHA now requires updated safety dossiers for cetyl ester imports above 100 tonnes annually. The industrial consequence is supplier consolidation as smaller compounders withdraw from European formulation supply chains. Pharmaceutical-grade cetyl stearate for topical ointments faces the steepest compliance cost escalation, driving German and Dutch formulators toward pre-registered supply contracts with backward-integrated producers.
Buyer concentration among branded personal care manufacturers is compressing supplier negotiation leverage. Direct procurement from oleochemical complexes in Malaysia and Indonesia is displacing layered distributor networks for volume cosmetic accounts. This pattern is most visible in the United States, where Sephora and Ulta Beauty clean-label mandates are forcing contract manufacturers to document single-source vegetable feedstock origins.
Cetyl Esters Market Segmentation
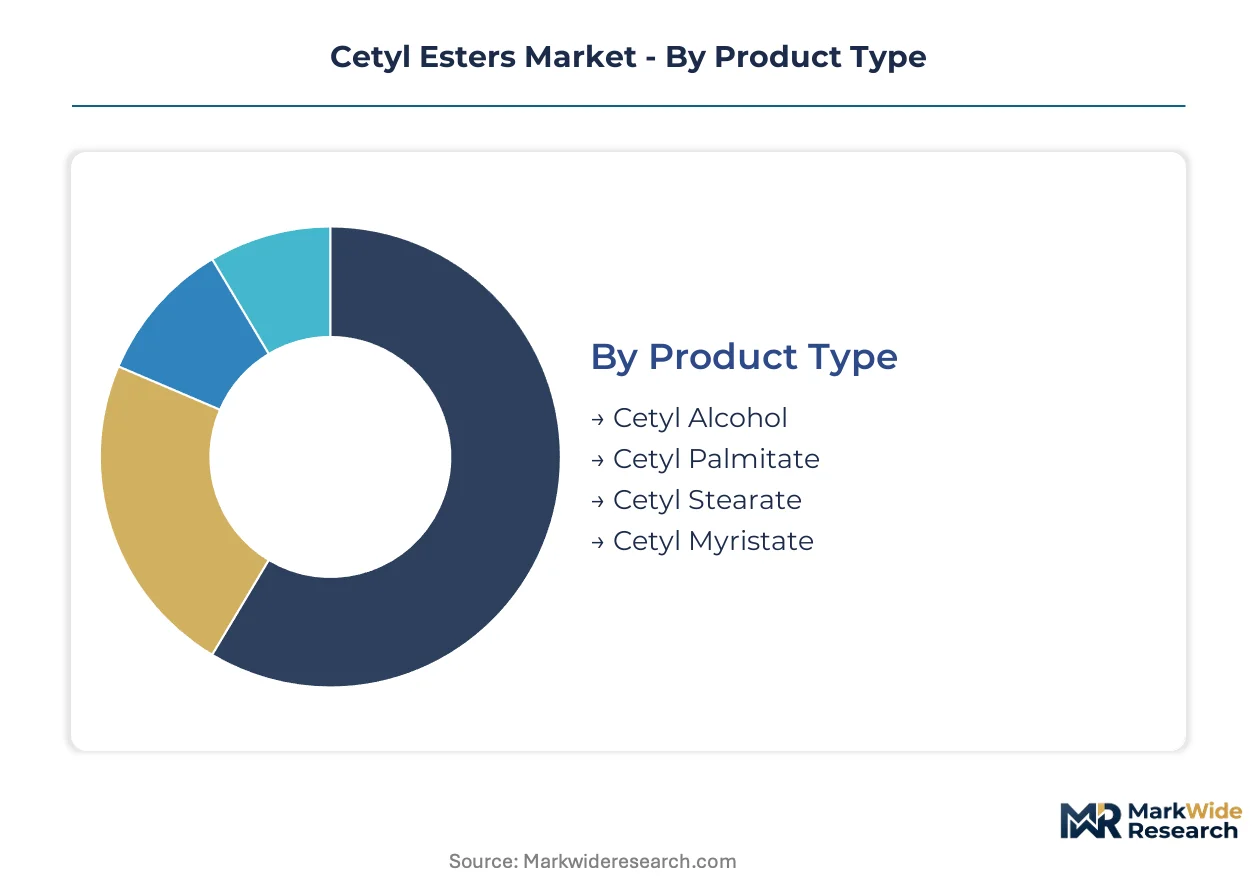
Segmentation in cetyl esters reveals how product specifications, application requirements, and supply chain configurations fragment procurement patterns across cosmetic, pharmaceutical, and food-grade channels. Understanding these divides exposes where margin pools concentrate and where compliance burdens shift buyer-seller power dynamics.
Product Type:
Channel mix varies sharply by ester chemistry: cetyl palmitate and cetyl stearate flow predominantly through direct procurement contracts with backward-integrated oleochemical producers, while cetyl alcohol and cetyl myristate move through layered distributor networks serving smaller compounders.
- Cetyl Palmitate:A saturated fatty acid ester combining cetyl alcohol with palmitic acid, prized for its crystalline structure and skin-feel properties in premium emollient systems. Demand concentrates in German and French cosmetic formulators replacing petrolatum-derived bases under clean-label mandates from Sephora and Ulta Beauty.
- Cetyl Stearate:The stearic acid ester variant delivering superior viscosity stability across temperature ranges critical for pharmaceutical ointment specifications. USP-grade requirements from topical drug manufacturers in the United States and Switzerland are accelerating procurement of documented vegetable-origin batches with full REACH dossiers.
- Cetyl Alcohol:The foundational fatty alcohol feedstock for downstream esterification, also sold directly as emollient and emulsion stabilizer.
- Cetyl Myristate:The myristic acid ester offering lighter skin-feel profiles for fluid cosmetic formulations and sprayable applications.
By volume, cetyl palmitate leads. By growth pace, cetyl stearate is expanding most quickly.
Application:
Cost tier stratification separates these segments: cosmetics and personal care command premium pricing for certified vegetable-origin grades, while food industry applications face specification-constrained, lower-margin procurement with extended BIS and FSSAI approval timelines.
- Cosmetics:Skin creams, lotions, and color cosmetics requiring emollient, opacifying, and viscosity-building functions with documented chain-of-custody for natural-origin claims.
- Personal Care:Hair conditioners, sun care, and baby care products where cetyl esters provide detangling and conditioning benefits alongside label-friendly ingredient positioning.
- Pharmaceuticals:Topical ointments and dermatological preparations demanding USP-grade cetyl stearate with validated viscosity profiles and impurity thresholds.
- Food Industry:Emerging applications as emulsifiers and coating agents, currently nascent due to stringent ingestible-grade purity requirements and multi-jurisdiction approval barriers.
Cosmetics generates the deepest margin pools. Pharmaceuticals shows the steepest compliance cost escalation.
End User:
Customer type determines contract structure and technical service intensity: manufacturers demand captive supply agreements with process optimization support, while distributors and wholesalers absorb inventory risk for standardized grades.
- Manufacturers:Branded personal care and pharmaceutical companies with direct procurement teams negotiating backward-integrated supply contracts and technical collaboration on formulation integration.
- Retailers:Clean-label mandates from specialty beauty retailers are forcing contract manufacturers to document single-source vegetable feedstock origins with full regulatory dossiers.
- Distributors:Regional chemical distributors holding inventory for mid-tier compounders unable to meet minimum order quantities for direct mill supply.
- Wholesalers:Volume aggregators serving smaller formulators with standardized cetyl alcohol and generic ester grades.
Manufacturers capture the greatest supply security. Distributors face the most margin compression from direct procurement displacement.
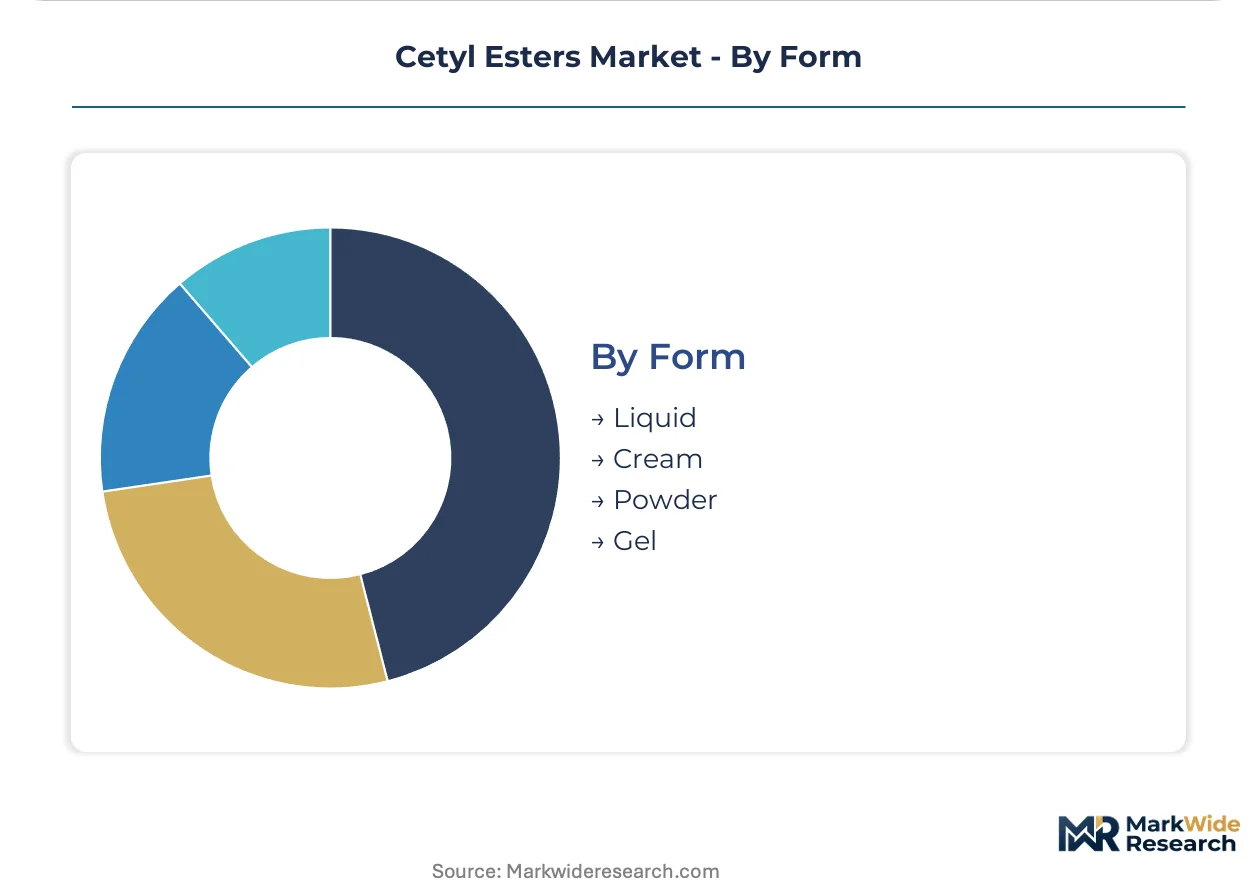
Form:
Supply concentration clusters around semi-solid and solid formats where Southeast Asian oleochemical complexes exploit scale economies, while liquid and gel forms require specialized processing equipment that fragments producer bases.
- Cream:Semi-solid emulsion base incorporating cetyl esters as primary structuring agents and emollients in jar-packaged skin care.
- Powder:Micronized cetyl ester grades for dry shampoo, powder foundations, and anhydrous formulations requiring flow and lubricity control.
- Liquid:Fluid ester preparations and diluted alcohol forms for sprayable and pump-dispensed product systems.
- Gel:Structured aqueous systems where cetyl esters contribute to rheology modification and sensory modulation.
Powder commands the highest processing premiums. Cream maintains the broadest application base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration through ECHA governs cetyl ester import thresholds across Europe, filtering out low-grade suppliers and concentrating demand among certified manufacturers with documented vegetable-origin chain of custody.
United States
Clean-label mandates from Sephora and Ulta Beauty are forcing contract manufacturers to document single-source vegetable feedstock origins. FDA cosmetic ingredient review shapes market access pathways for cetyl palmitate and cetyl stearate. New Jersey and California host the densest clusters of premium cosmetic formulators reformulating around petrolatum replacements.
Germany
Branded personal care manufacturers in Germany are systematically replacing mineral oil-derived emollients with vegetable-based cetyl esters. ECHA registration requirements filter out uncertified suppliers from European formulation supply chains. The Rhine-Ruhr industrial corridor anchors backward-integrated oleochemical production serving cosmetic compounders.
France
Premium cosmetic formulators in France are adopting cold-process cetyl palmitate at price premiums for superior color stability. REACH dossier updates for imports above 100 tonnes annually compress supplier margins. The Île-de-France region concentrates demand from luxury skincare houses reformulating around natural-origin claims.
Malaysia
Palm-oil-based cetyl ester production from Southeast Asian oleochemical complexes competes on scale for volume cosmetic accounts. Feedstock cost swings in Malaysian complexes transmit directly to cetyl ester margins. The Klang Valley industrial zone hosts integrated oleochemical facilities supplying direct procurement contracts with North American and European formulators.
India
BIS purity standards and evolving FSSAI emulsifier approvals are creating first-mover advantage for ester producers meeting ingestible-grade thresholds. Central Drug Standard Control Organization oversight shapes pharmaceutical-grade specifications. Maharashtra and Gujarat industrial corridors are developing food-grade cetyl ester capacity for domestic and export markets.
Cetyl Esters Market Competitive Environment
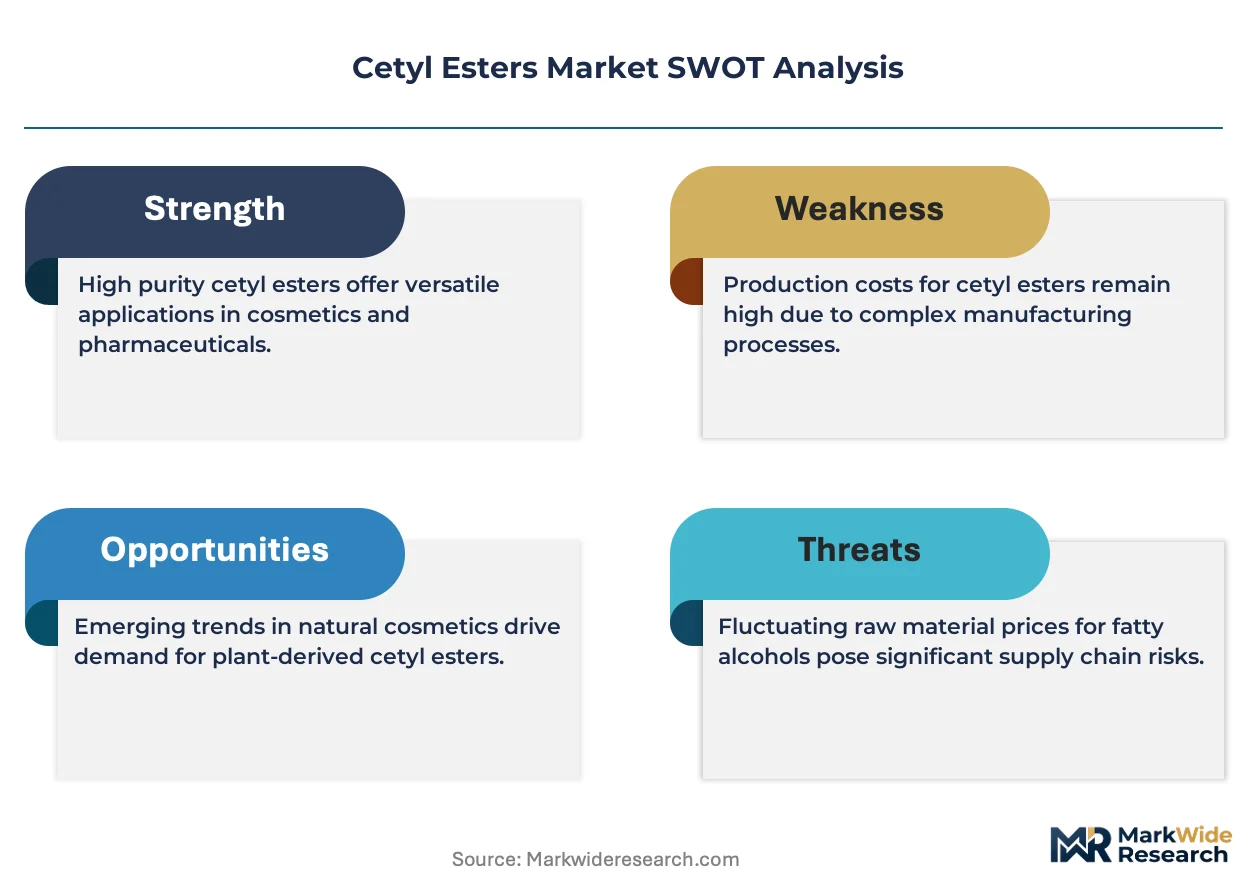
A small set of integrated leaders sits above a broader specialist tier, with backward-integrated oleochemical producers commanding supply security advantages over compounder-only operations. The market structure concentrates procurement leverage among formulators with direct mill relationships, while mid-tier distributors face margin compression from disintermediation. Two strategic archetypes dominate: Southeast Asian palm-oil-based scale producers and European vegetable-feedstock specialists with REACH pre-registration. Competitive moves center on captive feedstock control and multi-jurisdiction compliance dossier accumulation.
Among the named participants, Croda International plc exemplifies the integrated specialist archetype with European regulatory positioning, while Koster Keunen occupies a defined position in beeswax-derived cetyl ester segments. KLK OLEO represents the Southeast Asian scale-driven tier with Malaysian oleochemical complex access. These three anchors illustrate how geographic feedstock advantages and regulatory pre-certification are separating sustainable suppliers from compounders facing compliance cost escalation.
| Leading Market Players |
|---|
| R.I.T.A |
| AQIA |
| Koster Keunen |
| Jeen International |
| Protameen Chemicals |
| Croda International plc |
| Strahl & Pitch |
| KLK OLEO |
| Vantage Specialty Ingredients |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Malaysian oleochemical complexes and European cosmetic formulators lock in feedstock access and price visibility across volatile palm oil cycles. These contracts insulate backward-integrated producers from spot market swings while exposing non-integrated compounders to margin compression when Indonesian feedstock costs spike.
Pricing Analysis
Price spreads between REACH-certified European grades and standard Southeast Asian material run 15-25% depending on documentation depth. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with USP-grade cetyl stearate commanding the widest premiums. Cost compression in mid-tier cosmetic grades is intensifying because direct procurement from Klang Valley mills is displacing distributor markups. Small compounders in India show the highest price sensitivity, while luxury skincare houses in France absorb premiums for cold-process material with superior color stability.
Supply Chain Analysis
Strategic stockpiling of palm-derived feedstocks dominates Southeast Asian producer behavior, while European formulators run lean just-in-time inventories to minimize working capital. Supply concentrates in Malaysia, Indonesia, and Germany, with the Klang Valley and Rhine-Ruhr corridors anchoring integrated production. Raw material dependencies center on crude palm oil, coconut fatty alcohol, and sulfuric acid catalysts. Single-source vulnerability in beeswax-derived cetyl esters creates concentration risk for halal-certified supply chains. Distribution runs through direct mill relationships for volume accounts, with regional distributors serving smaller compounders unable to meet minimum order thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. REACH dossier accumulation and ECHA pre-registration create switching costs that compound over multi-year compliance cycles.
For Market Incumbents: Compound backward integration into vegetable feedstocks to defend margin stability against palm oil volatility. Extend captive technical talent pools through specialized oleochemistry apprenticeship programs to counter esterification chemist scarcity. Lock in multi-year offtake contracts with German and French cosmetic formulators before enzymatic process technology disrupts acid-catalyzed economics. For New Entrants and Emerging Players: Technical service gaps in formulation integration support present white-space opportunities for agile specialists. Target mid-tier Indian compounders seeking BIS-certified food-grade cetyl esters with shortened approval timelines. Enter through enzymatic cold-process technology partnerships with Swiss and French premium cosmetic houses willing to pay for superior color and odor profiles. For Investors and Strategic Acquirers: European vegetable-feedstock specialists with REACH pre-registration and documented chain-of-custody systems represent the most defensible acquisition archetype. Long-term viability hinges on regulatory dossier depth rather than scale alone. Watch for enzymatic esterification yield breakthroughs as the inflection signal that reshapes cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Feedstocks | Croda International plc's captive palm and coconut sourcing insulates margins from Malaysian price volatility. |
| Enzymatic Process Technology Investment | Immobilized lipase biocatalysts enable cold-process production with superior color stability for fragrance-sensitive formulations. |
| Multi-Jurisdiction Compliance Dossier Accumulation | REACH, FDA, and BIS registration coverage opens consolidated access to German, US, and Indian formulation supply chains. |
| Long-term Supply Agreement with Retailer Mandates | Sephora and Ulta Beauty clean-label requirements force contract manufacturers toward single-source vegetable documentation. |
| Food-Grade Specification Development | FSSAI and BIS ingestible-grade approvals create first-mover advantage in India's emerging emulsifier applications. |
Study Parameters
Cross-validation between primary interviews with plant managers at Southeast Asian oleochemical complexes and secondary customs/trade data anchors the qualitative findings. Conversations with procurement leads at German cosmetic formulators, technical R&D directors in Swiss fragrance houses, and distribution channel partners in India were triangulated against SEC filings, Cefic reports, and ECHA registration databases. Bottom-up volume estimates from individual production facilities were reconciled with top-down demand aggregation across cosmetics, pharmaceutical, and food-grade applications.
Sensitivity analysis around palm oil price trajectories and enzymatic technology adoption curves tests forecast robustness across the projection horizon. Segmentation modeling incorporates grade tier, end-use industry, regional production hub, and certification pathway dimensions. CAGRs were derived from trend extrapolation of historical volume flows adjusted for regulatory compliance cost escalation and feedstock substitution patterns. Industry-specific inputs include REACH dossier renewal timelines and USP-grade specification penetration rates in topical drug formulations.
Underlying assumptions cover sustained clean-label reformulation momentum in premium cosmetics, with deviation risk concentrated in palm oil supply disruptions or accelerated enzymatic process cost parity. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when enzymatic esterification yield economics cross threshold viability against acid-catalyzed batch processes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
1-Decene Market
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Global Hexyl Cinnamal Market