
 Trimethyl Pentanediol Monoisobutyrate Market | 2026-2036
Trimethyl Pentanediol Monoisobutyrate Market Size, Share, and Industry Trends Forecast 2026-2036
Trimethyl Pentanediol Monoisobutyrate Market Intelligence
Industrial-grade specification tiers for high-purity trimethyl pentanediol monoisobutyrate is collapsing into fewer, broader bands as downstream formulators consolidate vendor lists and demand consistent batch-to-batch performance. Eastman Chemical Company leverages backward integration into oxo-alcohol feedstocks to control cost volatility across its specialty esters portfolio. BASF SE anchors European supply through its Ludwigshafen manufacturing complex, while OQ Chemicals GmbH competes on customized esterification capabilities for regional coatings customers.
Trimethyl pentanediol monoisobutyrate is a branched C-12 ester alcohol manufactured via catalytic esterification of trimethyl pentanediol with isobutyric acid, yielding a colorless liquid with low viscosity, high boiling point, and excellent coalescing efficiency in waterborne systems. Its primary industrial purpose centers on film formation in latex paints and viscosity modification in personal care formulations. Coatings applications dominate volume consumption as architectural and automotive waterborne formulations displace solvent-based alternatives, while personal care applications sustain premium margin pools due to stringent purity requirements from cosmetic brands. Direct sales channels capture the largest value share by serving chemical manufacturers with contracted volume commitments, though distributors occupy a critical intermediary role for mid-tier construction and printing customers.
EPA regulations under the National Volatile Organic Compound Emission Standards for Consumer and Commercial Products constrain permissible solvent content in architectural coatings, directly elevating demand for exempt compounds including trimethyl pentanediol monoisobutyrate. REACH registration requirements and the EU Green Deal's chemical sustainability targets impose full toxicological dossiers on importers, favoring established producers with existing substance registrations over new market entrants. Stakeholders must monitor evolving state-level VOC rules in California and New York alongside China's GB standards for architectural coatings, as regulatory divergence threatens to fragment formulation specifications and complicate multinational product registration strategies.
Market Dynamics
Waterborne coating formulations are displacing solvent-based systems across automotive and architectural end-uses, concentrating purchasing power among formulators with integrated R&D capabilities and forcing specialty ester suppliers to consolidate specification tiers.
Growth Catalysts
- EPA VOC Exemptions:The National Volatile Organic Compound Emission Standards for Consumer and Commercial Products classifies trimethyl pentanediol monoisobutyrate as a VOC-exempt compound, accelerating its substitution for regulated solvents in architectural coatings.
- Automotive OEM Consolidation:Integrated supply relationships between coatings formulators and vehicle manufacturers in Germany, China, and the United States are locking in multi-year volume commitments for low-VOC raw materials.
- Oxo-Alcohol Feedstock Control:Backward integration into propylene-derived intermediates is stabilizing input cost volatility for established ester producers, insulating contracted customers from spot market fluctuations.
Market Restraints
- Propylene Price Volatility:Crude oil-linked feedstock costs for oxo-alcohol production transmit directly to trimethyl pentanediol pricing, compressing margins for non-integrated formulators.
- REACH Registration Barriers:Full toxicological dossier requirements under EU chemicals regulation favor incumbent registrants and block new market entrants lacking existing substance registrations.
- Glycol Ether Substitution:Propylene glycol monomethyl ether and dipropylene glycol monomethyl ether compete directly in waterborne coalescing applications, limiting pricing power in cost-sensitive construction segments.
Strategic Opportunities
- Personal Care Premiumization:Cosmetic brands in South Korea and Japan are sourcing high-purity ester alcohols for skin-conditioning formulations, commanding margin premiums above industrial coatings grades.
- China GB Standard Alignment:Implementation of national VOC limits for architectural coatings under GB 38508 is redirecting domestic formulators toward exempt oxygenated solvents with favorable toxicological profiles.
- Biobased Esterification Pathways:Catalytic processes utilizing renewable isobutyric acid from fermentation are converging with conventional petrochemical routes, opening sustainability-positioned product lines for brand-conscious coatings customers.
Industry Challenges
- Batch-to-Batch Consistency:Downstream formulators consolidating vendor lists are demanding tighter color, acid value, and moisture specifications, forcing capital investment in automated process control systems.
- Regulatory Divergence Management:State-level VOC rules in California and New York are fragmenting formulation specifications, complicating multinational product registration strategies and inventory pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trimethyl Pentanediol Monoisobutyrate Market |
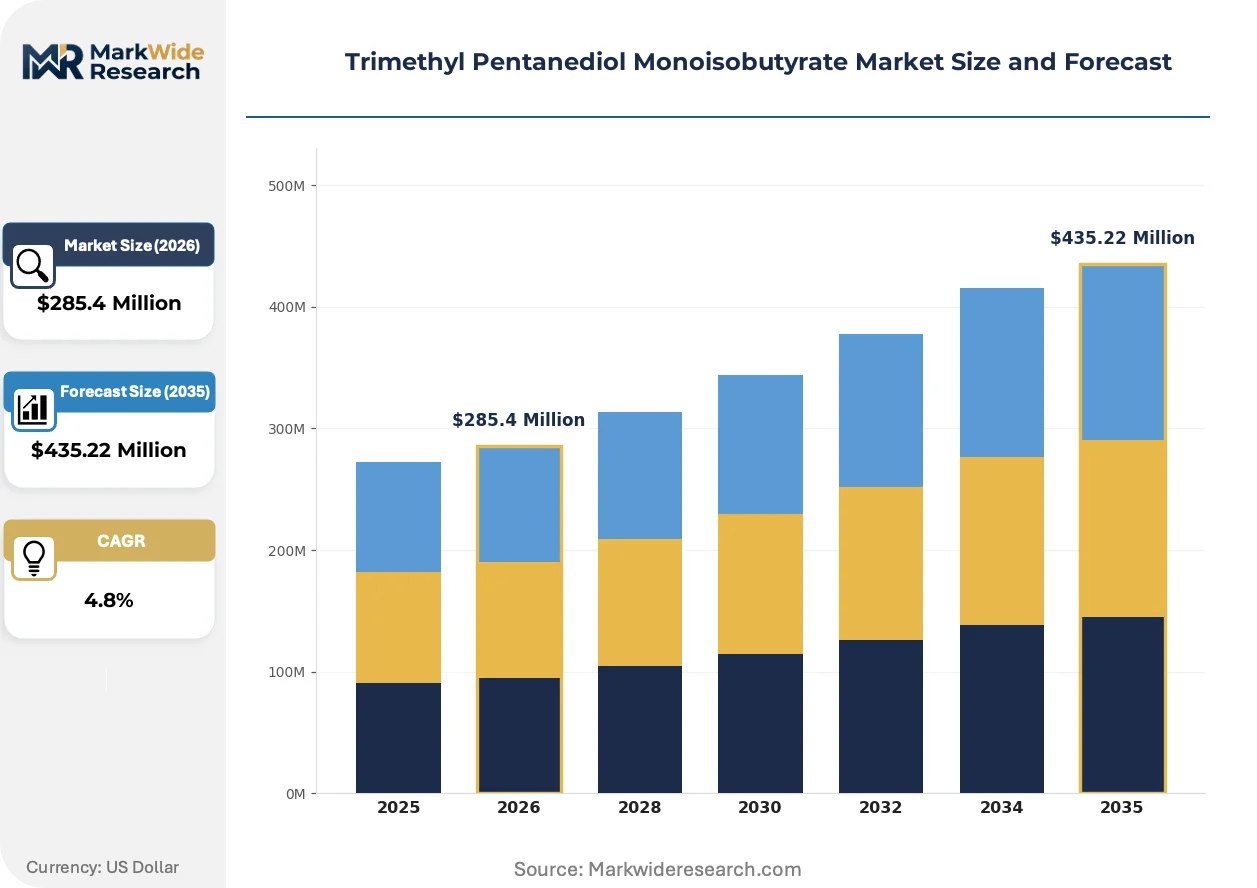
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Coatings, Adhesives, Inks Application: Personal Care, Paints, Sealants, Printing End User: Chemical Manufacturers, Cosmetic Brands, Automotive, Construction Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Eastman Chemical Company, Hallstar, OXEA, Univar Solutions, Honeywell International, BASF SE, Evonik Industries AG, OQ Chemicals GmbH, Shijiazhuang Xinlongwei Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trimethyl Pentanediol Monoisobutyrate Market Strategic Shifts & Innovations
Catalytic esterification processes and purification technologies are reshaping competitive positioning among specialty ester producers, separating integrated manufacturers from toll-processing operators.
Membrane-based purification of trimethyl pentanediol monoisobutyrate is bifurcating the supply base between high-purity cosmetic-grade producers and industrial coatings-focused manufacturers. Personal care formulators in Japan and South Korea are adopting ultrapure specifications with sub-50 ppm acid values and near-zero color. This technology is compressing margins for conventional distillation-based producers unable to meet pharmaceutical-adjacent purity thresholds.
REACH registration requirements and the EU Green Deal's chemical sustainability targets are imposing full substance dossiers on importers into European markets. Industrial consequence includes preferential sourcing from established registrants with existing compliance infrastructure. Automotive coatings producers in Germany are responding by locking in multi-year supply agreements with Ludwigshafen-based manufacturing complexes to secure registration continuity.
Specification consolidation among downstream formulators is eliminating mid-tier purity grades, compressing the market toward premium cosmetic specifications and economy industrial grades. Distributors serving mid-tier construction and printing customers are losing volume to direct sales channels with contracted R&D support. This pattern is most visible in the United States, where architectural coatings producers have reduced qualified supplier lists from twelve to four over the past five years.
Trimethyl Pentanediol Monoisobutyrate Market Segmentation
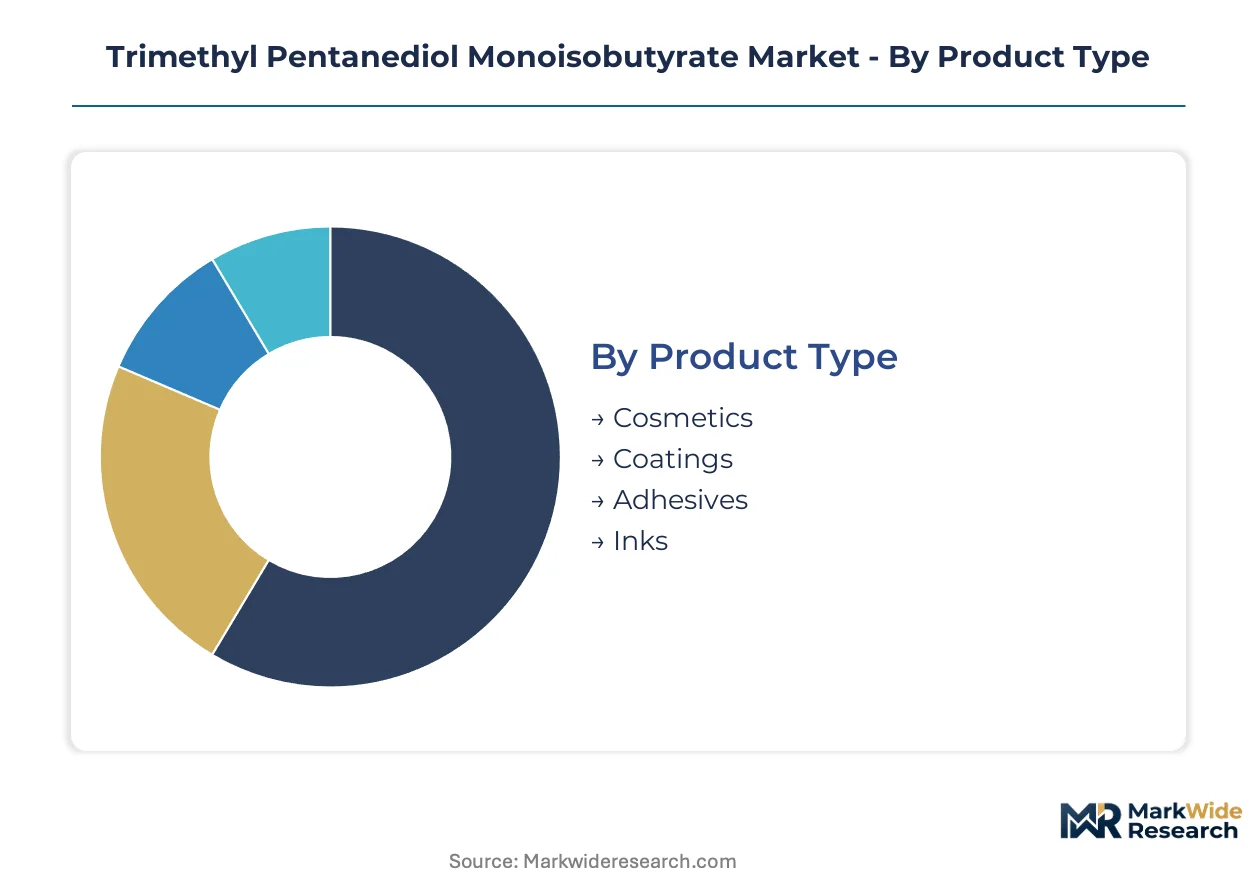
Segmentation in the trimethyl pentanediol monoisobutyrate market reveals how purity specifications and channel economics fragment margin capture. Formulators with integrated R&D capabilities concentrate purchasing power, while regulatory compliance costs reshape viable customer profiles across end-use categories.
Product Type:
Margin pools concentrate in cosmetics-grade specifications where pharmaceutical-adjacent purity thresholds command substantial premiums over industrial formulations.
- Cosmetics:Ultrapure grades with sub-50 ppm acid values and near-zero color serve skin-conditioning formulations in South Korea and Japan. Cosmetic brands impose batch-to-batch consistency requirements that membrane-based purification systems satisfy, insulating qualified suppliers from price competition.
- Coatings:Waterborne architectural and automotive formulations consume the largest volumes as EPA VOC exemptions accelerate substitution for regulated solvents. German automotive OEMs and U.S. architectural coatings producers lock in multi-year volume commitments with backward-integrated suppliers.
- Adhesives:Industrial bonding applications favor economy-grade specifications with broader batch tolerance, serving mid-tier construction customers through distributor channels.
- Inks:Printing applications require moderate purity grades balancing coalescing efficiency with cost constraints, particularly in commercial packaging segments.
The dominant share belongs to Coatings, while Cosmetics is closing the gap fastest through premiumization in Asian personal care markets.
Application:
Volume concentration tracks regulatory pressure intensity, with jurisdictions enforcing strict VOC limits redirecting formulation chemistry toward exempt oxygenated solvents.
- Personal Care:High-purity ester alcohols function as skin-conditioning agents and viscosity modifiers in premium cosmetic formulations. Japanese and South Korean brands source through direct sales channels with contracted R&D support, bypassing traditional distributors.
- Paints:Architectural waterborne systems dominate consumption as EPA National Volatile Organic Compound Emission Standards and China GB 38508 alignment constrain permissible solvent content. California and New York state-level rules fragment formulation specifications for multinational producers.
- Sealants:Construction-grade applications sustain steady demand through distributor networks serving mid-tier contractors with standardized industrial grades.
- Printing:Commercial printing inks utilize moderate-purity specifications, with procurement patterns shifting toward consolidated vendor lists among large-format operators.
Paints commands the largest volume position, though Personal Care exhibits the steepest expansion trajectory as cosmetic brands elevate formulation standards.
End User:
Customer scale and technical integration determine channel economics, with large formulators extracting price advantages through contracted volume commitments.
- Chemical Manufacturers:Integrated coatings formulators with captive R&D capabilities source directly from oxo-alcohol producers, securing registration continuity under REACH and EPA guidelines. Eastman Chemical Company and BASF SE anchor supply relationships through backward integration into propylene-derived feedstocks.
- Cosmetic Brands:Premium personal care marketers in Japan and South Korea impose pharmaceutical-adjacent purity specifications, sourcing through qualified suppliers with membrane purification capabilities.
- Automotive:OEMs in Germany, China, and the United States consolidate purchasing through integrated supply relationships with specialty ester producers, locking in multi-year commitments for low-VOC raw materials.
- Construction:Mid-tier architectural coatings and sealant producers rely on distributor intermediaries, facing margin compression from specification consolidation among larger competitors.
Chemical Manufacturers hold the dominant procurement position, while Cosmetic Brands are gaining purchasing influence fastest through purity premiumization.
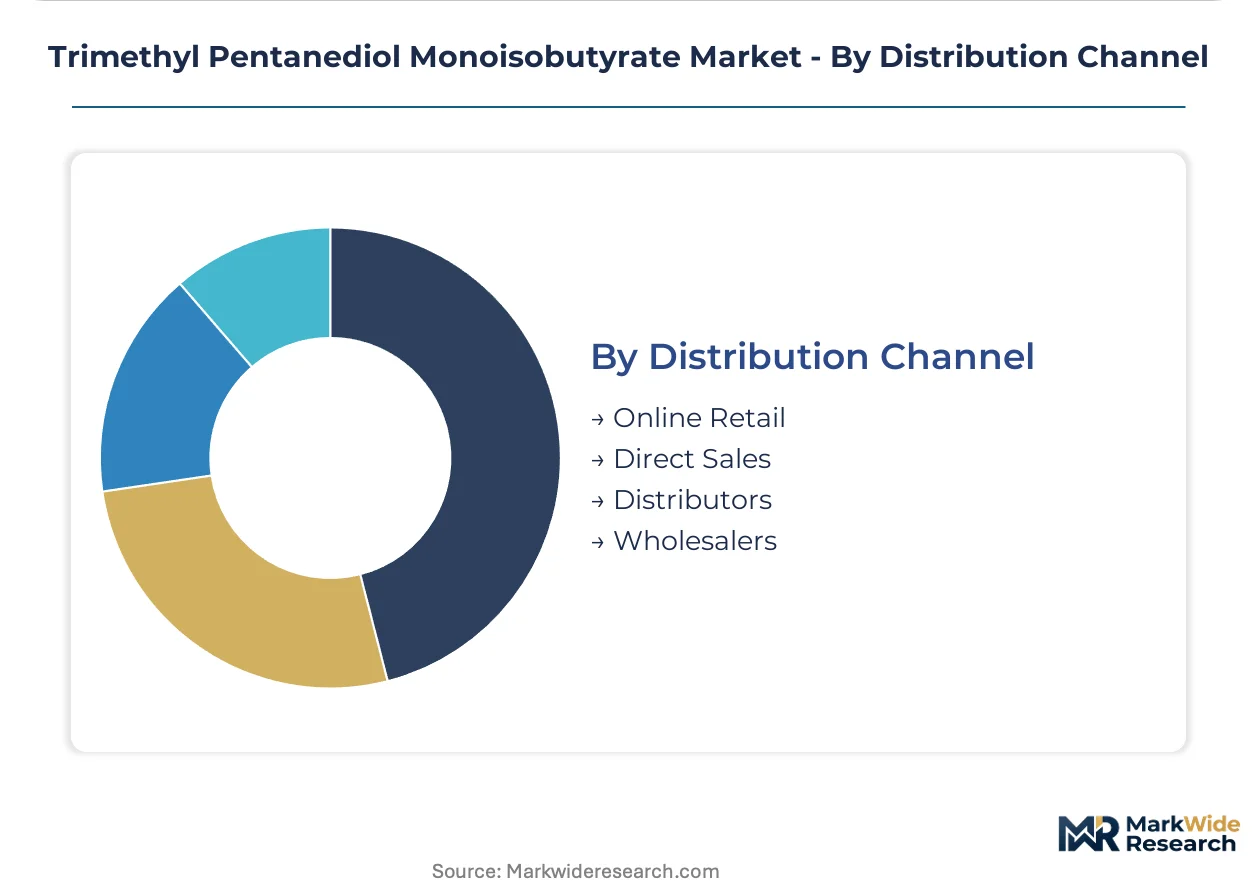
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with direct relationships capturing value from integrated formulators.
- Direct Sales:Large chemical manufacturers and automotive coatings formulators contract directly with specialty ester producers for volume commitments and R&D collaboration. This channel captures the largest value share through multi-year agreements.
- Distributors:Mid-tier construction and printing customers depend on distributor intermediaries for inventory pooling and technical support, though specification consolidation is eroding this channel's volume position.
- Online Retail:Small-batch cosmetic and specialty coatings customers utilize digital procurement for standardized grades, particularly in personal care ingredient marketplaces.
- Wholesalers:Commodity-grade industrial applications source through wholesale channels with limited technical service, serving price-sensitive construction segments.
Direct Sales maintains the dominant value position, while Online Retail is expanding most quickly through personal care ingredient platform growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States exhibit low price elasticity as automotive OEMs lock in multi-year supply agreements, while Chinese construction coatings formulators remain highly sensitive to spot market fluctuations in oxo-alcohol feedstocks.
United States
Architectural coatings producers in California and New York face divergent state-level VOC regulations that fragment formulation specifications. EPA National Volatile Organic Compound Emission Standards classify trimethyl pentanediol monoisobutyrate as VOC-exempt, accelerating substitution for regulated solvents. Integrated supply relationships between Midwest-based coatings formulators and Gulf Coast oxo-alcohol producers stabilize procurement costs through backward integration.
Germany
Automotive OEMs in Stuttgart and Munich consolidate purchasing power through multi-year volume commitments for low-VOC raw materials. REACH registration requirements and EU Green Deal chemical sustainability targets impose full toxicological dossiers, favoring established producers with existing compliance infrastructure. The Ludwigshafen manufacturing complex anchors European supply through captive production of propylene-derived intermediates.
China
GB 38508 national VOC limits for architectural coatings redirect domestic formulators toward exempt oxygenated solvents. Construction coatings producers in the Yangtze River Delta and Pearl River Delta exhibit high price sensitivity to propylene feedstock volatility. Shandong-based specialty ester manufacturers compete on customized esterification capabilities for regional automotive customers.
Japan
Cosmetic brands in Tokyo and Osaka impose pharmaceutical-adjacent purity specifications with sub-50 ppm acid values and near-zero color. METI chemical management policies align with REACH-equivalent substance registration requirements, elevating compliance costs for imported materials. Personal care formulators source ultrapure grades through direct channels with contracted R&D support.
South Korea
Premium skincare marketers in Seoul drive demand for high-purity ester alcohols in skin-conditioning formulations. MFDS cosmetic safety regulations parallel EU purity standards, creating regulatory convergence with Japanese procurement patterns. Membrane-based purification capabilities differentiate qualified suppliers serving the K-beauty export sector.
Trimethyl Pentanediol Monoisobutyrate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with membrane-purification specialists commanding premium margins in personal care while backward-integrated oxo-alcohol producers dominate industrial coatings volume. The market structure consolidates around three tiers: integrated petrochemical majors with captive feedstock supply, regional esterification specialists with customized capabilities, and toll-processing operators serving spot market demand. Strategic moves center on specification consolidation through automated process control investment and registration continuity locking under REACH and EPA frameworks.
Among integrated petrochemical majors, Eastman Chemical Company and BASF SE exemplify archetypes combining upstream oxo-alcohol production with downstream specialty ester manufacturing. OQ Chemicals GmbH occupies a position within the regional specialist tier, leveraging customized esterification capabilities for coatings customers. These three entities represent the dominant competitive anchors shaping procurement relationships with automotive OEMs and architectural coatings formulators across Germany, the United States, and China.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Hallstar |
| OXEA |
| Univar Solutions |
| Honeywell International |
| BASF SE |
| Evonik Industries AG |
| OQ Chemicals GmbH |
| Shijiazhuang Xinlongwei Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
REACH registration requirements and EPA VOC exemption status simultaneously gate supplier qualification and stratify price realization across purity tiers. Buyers in Germany and the United States absorb substantial premiums for registration-continuous supply, while Chinese formulators arbitrage spot-market oxo-alcohol volatility through shorter-term contracting.
Pricing Analysis
After-sales technical service and formulation support contracts capture lifetime value exceeding base chemical transactions. Three-tier pricing structure across premium cosmetic, standard coatings, and economy industrial levels reflects membrane purification investment and batch certification rigor. Cost compression in economy grades is intensifying because propylene feedstock volatility transmits directly to non-integrated producers. Mid-tier construction coatings customers exhibit highest price sensitivity, while Japanese cosmetic brands demonstrate near-zero elasticity for ultrapure specifications.
Supply Chain Analysis
Germany and the United States anchor integrated oxo-alcohol production, while China concentrates regional esterification capacity for Asia-Pacific coatings demand. Propylene-derived intermediates, isobutyric acid, and catalytic hydrogenation catalysts constitute critical input dependencies. Single-source vulnerability concentrates around Ludwigshafen-based propylene oxide supply for European automotive coatings customers. Distribution runs through direct sales channels for large formulators, with distributor intermediaries serving fragmented construction and printing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coating displacement of solvent-based systems constitutes a high-growth disruption accelerated by EPA VOC exemption status and tightening GB standards in China. Formulators with integrated R&D capabilities are consolidating vendor lists, compressing viable supplier positions.
For Market Incumbents: Compound registration continuity advantages under REACH and EPA frameworks through multi-year supply agreements with German automotive OEMs. Lock in propylene feedstock supply via backward integration or long-term offtake contracts to insulate against spot market volatility. Invest in automated process control systems to satisfy batch-to-batch consistency requirements from consolidating downstream formulators. For New Entrants and Emerging Players: Cosmetic-grade certification fast-tracks through MFDS alignment in South Korea and METI equivalency in Japan open white-space penetration. Target personal care ingredient platforms serving K-beauty export markets where pharmaceutical-adjacent purity specifications command substantial premiums. Pursue biobased isobutyric acid pathways to differentiate on sustainability positioning for brand-conscious coatings customers. For Investors and Strategic Acquirers: REACH registration deadlines reshaping the acquisition landscape favor targets with existing substance dossiers over greenfield registration plays. Five-to-ten year viability hinges on membrane purification capabilities and captive oxo-alcohol supply. Monitor China GB 38508 enforcement intensity as inflection indicator for regional demand redirection toward exempt oxygenated solvents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstocks | Eastman Chemical and BASF SE stabilize margin volatility through captive oxo-alcohol supply. |
| Membrane Purification Capacity Addition | Ultrafiltration systems enable cosmetic-grade certification for Japanese and South Korean personal care markets. |
| Long-term Supply Agreement with Automotive OEMs | Multi-year volume commitments from Stuttgart and Munich manufacturers secure registration continuity. |
| Biobased Esterification Pathway Development | Fermentation-derived isobutyric acid opens sustainability-positioned product lines for coatings customers. |
| Automated Process Control Investment | Real-time monitoring systems satisfy tightening acid value and color specifications from consolidating formulators. |
Research Approach
Initial hypotheses were tested against primary input from coatings formulators, cosmetic brand procurement leads, oxo-alcohol plant managers, and specialty ester distribution partners and refined through secondary validation. Customs and trade data, ACC and Cefic industry reports, EPA regulatory filings, and SEC 10-K disclosures provided quantitative anchors. Bottom-up demand modeling across end-use segments triangulated against top-down production capacity assessments.
Variance decomposition across the projection horizon isolates feedstock cost volatility, regulatory enforcement intensity, and substitution dynamics as primary uncertainty sources. Segmentation dimensions span purity grade tier, end-use industry concentration, regional production hub configuration, and channel structure. CAGRs derive from segment-level volume trajectory analysis incorporating propylene price correlation and coatings formulation shift elasticity.
Underlying assumptions cover REACH registration continuity, EPA VOC exemption durability, and China GB standard enforcement cadence, with deviation risk concentrated in propylene feedstock spike magnitude and automotive OEM sourcing consolidation pace. Recalibration cycles align with material shifts in regulatory enforcement thresholds and membrane purification technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Synthetic Wax Market
Oleochemicals
Esters Market
Oleochemicals
Europe Wax Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Oleochemicals Market