
 Narrow Range Ethoxylates Market | 2026-2036
Narrow Range Ethoxylates Market Size, Share, and Industry Trends Forecast 2026-2036
Narrow Range Ethoxylates Market Intelligence
The EU F-Gas Regulation and downstream buyer sustainability mandates is realigning procurement criteria for surfactant feedstocks across European personal care and agrochemical supply chains. BASF SE leverages its integrated C2-C4 value chain to secure narrow-cut ethylene oxide supply for controlled ethoxylation. Nouryon sustains long-term offtake agreements with specialty formulators seeking batch-to-batch consistency in hydrophobe-ethylene oxide ratios. Clariant AG differentiates through catalyst technology that tightens ethoxylate distribution profiles below conventional Poisson spreads.
Narrow range ethoxylates are specialty nonionic surfactants manufactured through advanced ethoxylation processes yielding ethylene oxide adduct distributions with polydispersity indices below 1.1, as opposed to the broader spreads typical of conventional base-catalyzed reactions. Their narrow molecular weight distribution delivers superior surface tension reduction, lower aqueous gel-phase viscosity, and predictable performance in temperature-sensitive formulations across cosmetics, agrochemicals, and pharmaceutical applications. Nonionic surfactants and emulsifiers together anchor the product portfolio, with emulsifiers capturing concentrated margin pools in high-purity pharmaceutical and dermal formulations where batch consistency commands specification premiums. Solubilizers represent the fastest-growing product category as micellar delivery systems expand across water-miscible active formulations in personal care and crop protection adjuvants.
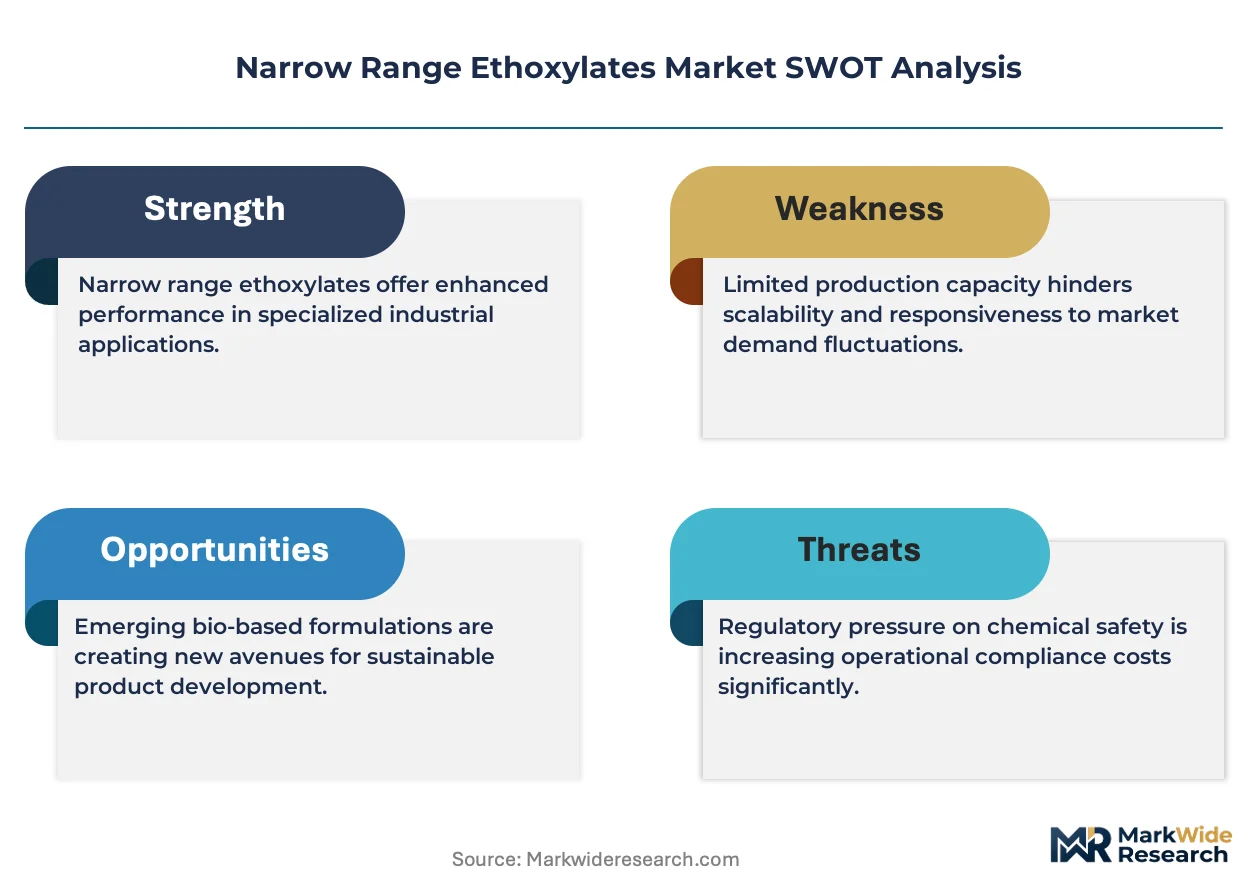
REACH restrictions on ethoxylates with uncontrolled ethylene oxide distribution, coupled with ECHA classification updates on residual 1,4-dioxane content, are tightening product standards and forcing reformulation investments across EU-based formulators. FDA and EPA parallel scrutiny of ethoxylate impurities in U.S. pharmaceutical and agrochemical applications is creating divergent compliance pathways that favor producers with multi-jurisdictional certification capabilities. Stakeholders must monitor regulatory harmonization pressure between EU and U.S. impurity thresholds while positioning narrow-range capacity to capture specification-driven substitution demand.
Market Dynamics
REACH restrictions on conventional ethoxylates with uncontrolled ethylene oxide distribution are forcing specialty chemical producers to reconfigure ethoxylation capacity toward narrow-cut specifications, compressing product development cycles and raising barriers for non-integrated suppliers.
Growth Catalysts
- EU biodegradability mandates:Personal care brands reformulate around tighter environmental standards, creating specification-driven substitution demand for narrow range ethoxylates with superior aquatic toxicity profiles.
- Agrochemical adjuvant precision:Crop protection formulators require batch-to-batch consistency in hydrophobe-ethylene oxide ratios to maintain spray droplet stability across variable field conditions.
- Pharmaceutical solubilizer expansion:Micellar delivery systems for water-miscible actives drive demand for low-polydispersity surfactants with predictable temperature-performance curves.
Market Restraints
- Ethylene oxide feedstock concentration:Narrow-cut ethoxylation requires captive C2 value chain access or long-term offtake agreements with integrated petrochemical producers, limiting new entrant participation.
- Specialized catalyst cost structure:Advanced ethoxylation catalysts with narrow distribution control command 40-60% premiums over conventional base-catalyzed systems, compressing margin pools for non-specialized producers.
- Residual 1,4-dioxane thresholds:ECHA classification updates and FDA parallel scrutiny impose additional purification steps and analytical certification burdens on ethoxylate manufacturers.
Strategic Opportunities
- India personal care penetration:CDSCO alignment with international impurity standards and BIS adoption of narrow-range specifications create first-mover advantages for certified suppliers.
- Biobased hydrophobe integration:Convergence of narrow-range ethoxylation with renewable fatty alcohol feedstocks enables premium positioning in EU Green Deal-aligned procurement frameworks.
- Direct pharmaceutical supply relationships:Bypassing distributor channels to contract directly with dermal formulation specialists captures specification premiums and locks in multi-year volume commitments.
Industry Challenges
- Specialized process engineering talent:Narrow-range ethoxylation requires expertise in continuous reactor design and real-time polydispersity monitoring that outstrips current technical training pipeline output.
- Multi-jurisdictional certification timelines:Harmonizing EU REACH dossiers with FDA drug master files and EPA pesticide inert listings extends product registration cycles by 18-24 months.
- Legacy equipment retrofit complexity:Converting conventional batch ethoxylation assets to narrow-range specifications demands reactor redesign and distributed control system upgrades that disrupt production continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narrow Range Ethoxylates Market |
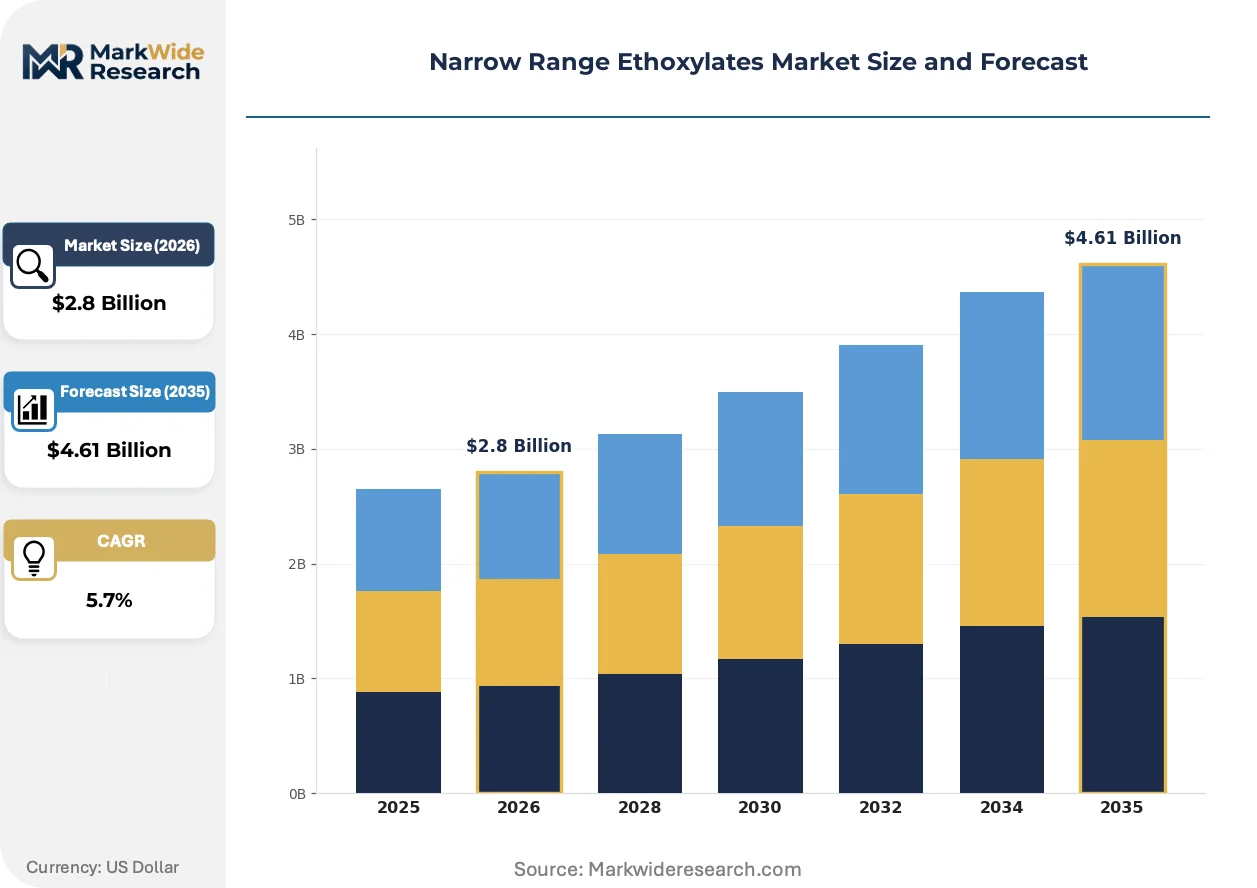
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonionic Surfactants, Emulsifiers, Solubilizers, Thickening Agents Application: Cosmetics, Personal Care, Agrochemicals, Pharmaceuticals End User: Manufacturers, Formulators, Chemical Distributors, Retailers Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Clariant AG, Nouryon, BASF SE, Stepan Company, Croda International Plc, Dow Chemical Company, Sasol Limited, Huntsman Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narrow Range Ethoxylates Market Strategic Shifts & Innovations
Process intensification and real-time analytical integration are compressing the gap between laboratory-scale polydispersity control and commercial production economics, enabling broader adoption of narrow-range specifications beyond premium pharmaceutical applications.
Continuous flow ethoxylation reactors with inline near-infrared spectroscopy are automating polydispersity monitoring and catalyst dosing adjustments that previously required offline chromatographic verification. Specialty chemical producers in Germany and the Netherlands deploy these systems to achieve sub-1.05 polydispersity indices at throughputs matching conventional batch operations. This automation is compressing batch release timelines from days to hours and reducing off-specification product volumes that previously eroded narrow-range margin premiums.
REACH restrictions on ethoxylates with uncontrolled ethylene oxide distribution are tightening product standards across EU-based formulators, with ECHA guidance documents clarifying acceptable polydispersity thresholds for cosmetic and agrochemical registrations. The regulatory consequence is a bifurcation of the European surfactant supply base into narrow-range certified suppliers and conventional producers facing registration non-renewal risks. Personal care and pharmaceutical segments are responding fastest, with procurement specifications now routinely requiring polydispersity certificates and residual 1,4-dioxane analytical reports.
Formulator procurement models are consolidating supplier relationships around fewer narrow-range certified partners capable of multi-jurisdictional regulatory documentation. Large personal care multinationals are displacing fragmented regional surfactant sourcing with global framework agreements that bundle specification consistency, regulatory compliance, and volume flexibility. This consolidation is most visible in Germany and France, where headquarters procurement functions centralize surfactant buying decisions and demand integrated REACH-FDA-EPA certification packages from single-source suppliers.
Narrow Range Ethoxylates Market Segmentation
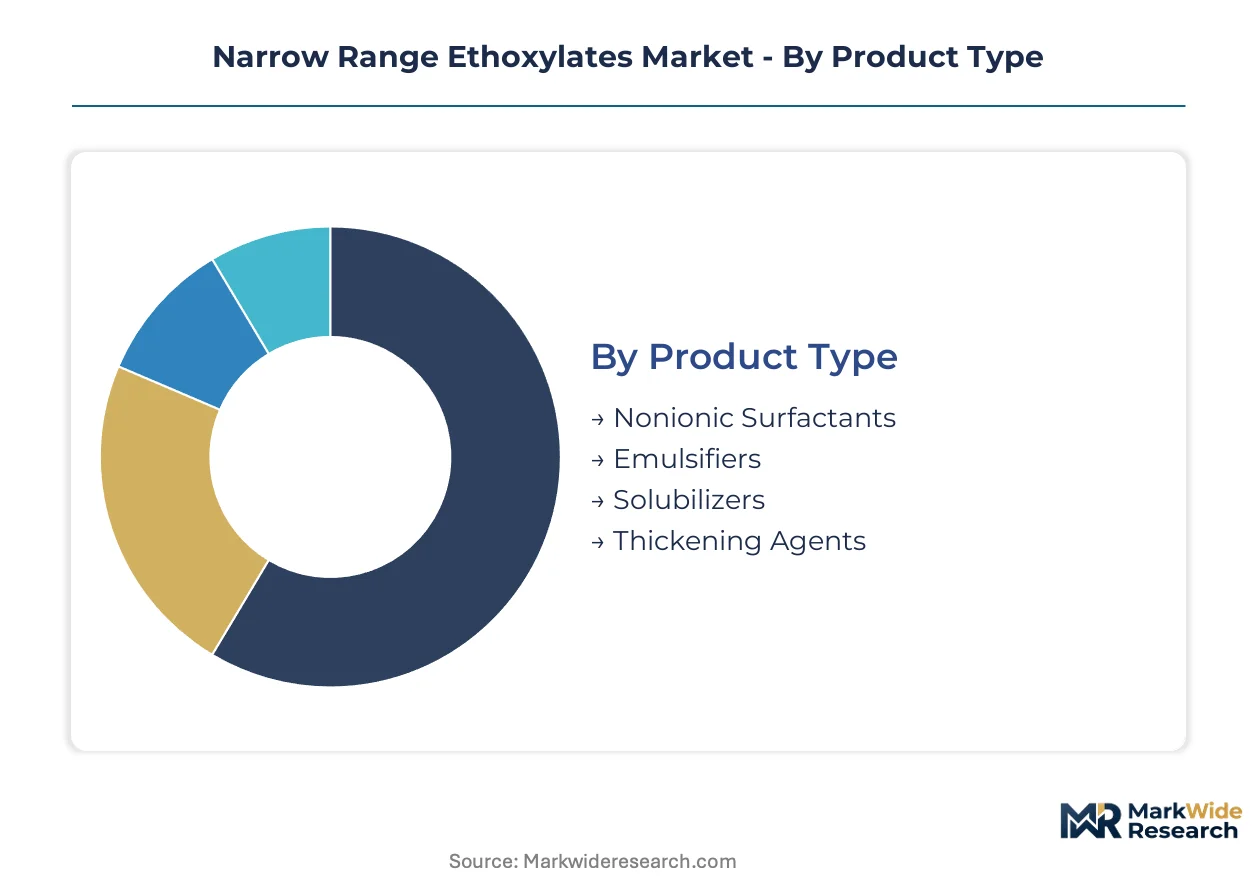
Narrow range ethoxylates command specification premiums that vary dramatically across product grades and end-use certifications. Segmentation reveals where REACH dossier burdens, FDA drug master file requirements, and ECHA impurity thresholds concentrate margin capture.
Product Type:
REACH cosmetic-grade registration demands polydispersity certificates below 1.1 for three of four product categories, while pharmaceutical applications impose additional residual 1,4-dioxane analytical burdens.
- Nonionic Surfactants:Base-grade narrow-cut ethoxylates with polydispersity indices of 1.05-1.10 serve as workhorse surface tension reducers. Demand concentrates in German agrochemical formulators seeking batch-to-batch consistency for spray adjuvant stability under variable field moisture conditions.
- Emulsifiers:High-purity grades with sub-1.05 polydispersity and enhanced temperature-performance predictability anchor pharmaceutical and dermal formulation specifications. Margin pools concentrate where batch consistency commands certification premiums from EU-based cosmetics multinationals reformulating around biodegradability mandates.
- Solubilizers:Micellar delivery systems for water-miscible actives in personal care and crop protection adjuvants.
- Thickening Agents:Specialized rheology modifiers with controlled ethylene oxide distribution for temperature-sensitive gel formulations.
Leading the category by volume: Nonionic Surfactants. Growing fastest: Solubilizers.
Application:
Cost tiers separate premium pharmaceutical grades from standard personal care and economy agrochemical specifications.
- Cosmetics:EU Green Deal procurement frameworks and CDSCO alignment pressures in India drive specification upgrades. Formulators pay premiums for integrated REACH-FDA certification packages from single-source suppliers.
- Personal Care:Biodegradability mandates from downstream brand sustainability commitments force reformulation toward narrow-cut specifications with superior aquatic toxicity profiles.
- Agrochemicals:Crop protection adjuvants requiring hydrophobe-ethylene oxide ratio precision for spray droplet stability across humidity extremes.
- Pharmaceuticals:Micellar delivery systems for water-miscible actives impose the strictest polydispersity and residual impurity thresholds.
Pharmaceuticals capture the steepest margin premiums. Personal Care shows the steepest specification upgrade trajectory.
End User:
Customer type determines whether procurement flows through distributor markups or direct contractual relationships with certification bundling.
- Manufacturers:Integrated chemical producers with captive C2 value chain access and in-house narrow-cut ethoxylation capacity.
- Formulators:Specialty compounders requiring batch-to-batch consistency certificates and multi-jurisdictional regulatory documentation for cosmetics and pharmaceutical clients.
- Chemical Distributors:Regional intermediaries facing margin compression as large personal care multinationals consolidate supplier relationships around certified narrow-range partners.
- Retailers:Downstream channels with limited specification influence but growing sustainability-driven procurement criteria.
Formulators command the most demanding certification requirements. Manufacturers retain the tightest feedstock integration advantages.
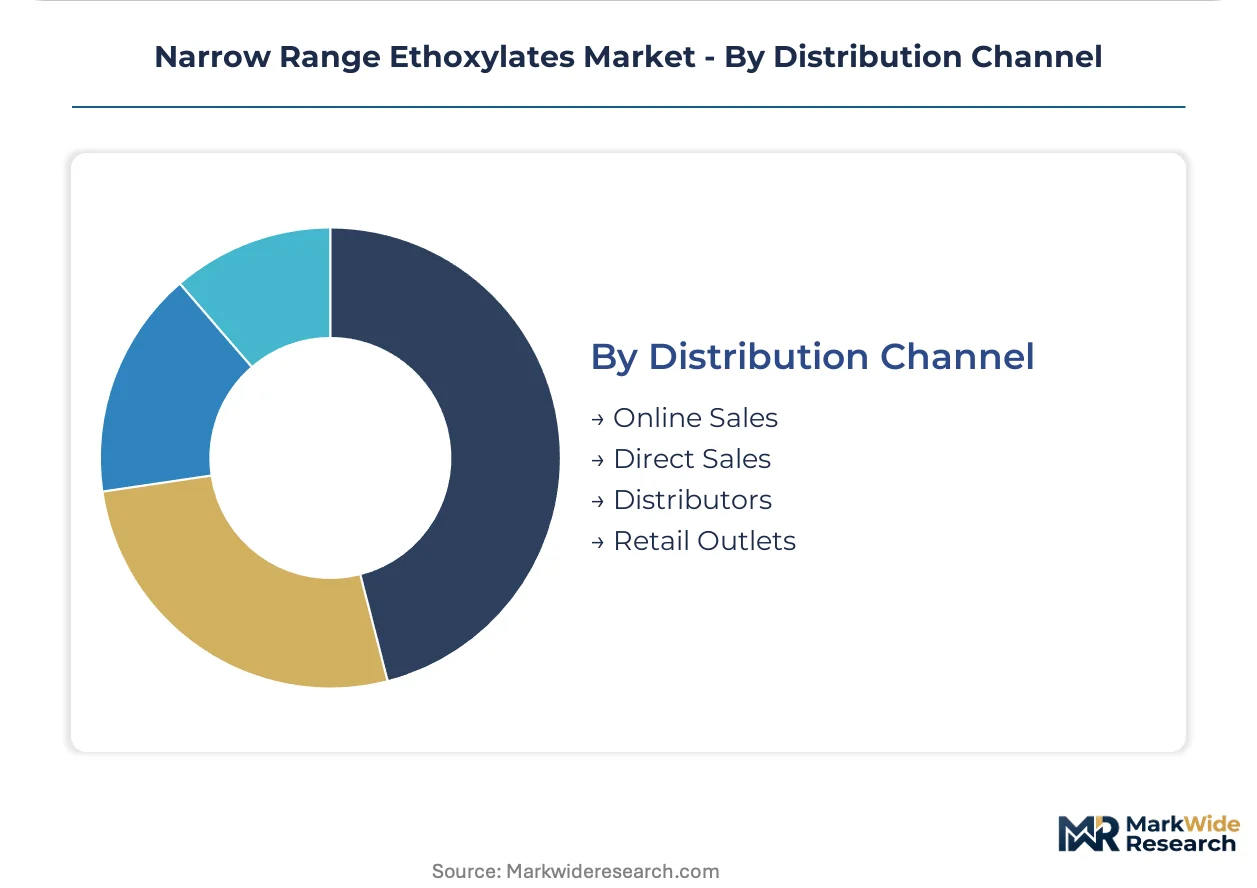
Distribution Channel:
Volume concentration favors direct sales for pharmaceutical and large cosmetics accounts, while fragmented regional demand sustains distributor relevance.
- Direct Sales:Global framework agreements bundle specification consistency, regulatory compliance, and volume flexibility for headquarters procurement functions in Germany and France.
- Distributors:Regional chemical distributors serving mid-tier formulators without scale for direct supplier contracts.
- Online Sales:Emerging channel for standardized narrow-cut grades with established certification documentation.
- Retail Outlets:Limited penetration given technical specification requirements and certificate-of-analysis needs.
Direct Sales leads by value capture. Online Sales expands most quickly for standardized grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the Netherlands, where integrated petrochemical complexes feed narrow-cut ethoxylation units. Consumption spreads across personal care formulators in France, agrochemical compounders in Brazil, and pharmaceutical manufacturers in the United States. Regulatory divergence between REACH and FDA timelines shapes regional procurement strategies.
Germany
Specialty chemical producers scale narrow-cut capacity to serve regulated European personal care and agrochemical markets. ECHA classification updates on residual 1,4-dioxane content tighten purification requirements for Ludwigshafen and Marl industrial clusters. BASF SE leverages its integrated C2-C4 value chain to secure captive ethylene oxide supply for controlled ethoxylation.
United States
Pharmaceutical solubilizer demand from micellar delivery system manufacturers drives specification upgrades. FDA parallel scrutiny of ethoxylate impurities creates compliance pathways favoring producers with multi-jurisdictional certification capabilities. Houston and New Jersey chemical corridors host reformulation investments from dermal formulation specialists.
France
Cosmetics multinationals headquartered in Paris and Lyon consolidate supplier relationships around global framework agreements. EU Green Deal procurement frameworks mandate biodegradability credentials that narrow-range ethoxylates satisfy. Procurement functions centralize surfactant buying decisions and demand integrated REACH-FDA-EPA certification packages.
Brazil
Agrochemical adjuvant formulators seek batch-to-batch consistency for spray droplet stability across variable field humidity conditions. ANVISA alignment with international impurity standards pressures local compounders toward certified narrow-cut sourcing. São Paulo industrial parks attract distributor investments linking European producers to Latin American crop protection markets.
India
Personal care penetration accelerates as CDSCO alignment with international impurity standards and BIS adoption of narrow-range specifications create first-mover advantages. Maharashtra and Gujarat chemical corridors host investments from specialty formulators seeking batch consistency certificates. Domestic producers retrofit conventional ethoxylation assets to capture specification-driven substitution demand.
Narrow Range Ethoxylates Market Key Industry Players
The competitive structure tilts toward integrated petrochemical majors with captive ethylene oxide supply. Three archetypes dominate: integrated C2-C4 value chain operators, specialty catalyst technology licensors, and regional formulator-facing compounders. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers seeking to lock in long-term offtake agreements with sustainability-mandated personal care brands.
Within the integrated tier, BASF SE and Nouryon exemplify archetypes combining captive feedstock access with multi-jurisdictional regulatory documentation capabilities. Clariant AG represents the catalyst technology vector, differentiating through narrow distribution profile control. These three anchors illustrate how REACH dossier burdens and FDA drug master file requirements concentrate competitive advantage around producers capable of bundling specification consistency with compliance certification.
| Leading Market Players |
|---|
| Clariant AG |
| Nouryon |
| BASF SE |
| Stepan Company |
| Croda International Plc |
| Dow Chemical Company |
| Sasol Limited |
| Huntsman Corporation |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Continuous flow ethoxylation reactor deployment in German and Dutch industrial clusters compresses batch release timelines while concentrating supply around integrated producers with captive ethylene oxide access. This technological transition simultaneously elevates cost barriers for non-specialized manufacturers and tightens pricing power among narrow-range certified suppliers serving REACH-regulated formulators.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects ECHA residual 1,4-dioxane thresholds and FDA parallel impurity scrutiny. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified pharmaceutical grades from personal care specifications and agrochemical base grades. Cost-down pressure on nonionic surfactants accelerates because specialized catalyst premiums compress margin pools for non-integrated producers. Formulators in cosmetics and pharmaceuticals exhibit lowest price sensitivity given specification-driven substitution mandates, while agrochemical compounders face highest price sensitivity amid volume procurement cycles.
Supply Chain Analysis
Multi-jurisdictional certification gating extends product registration cycles and consolidates supplier relationships around integrated producers with REACH-FDA-EPA documentation capabilities. Supply concentrates in Germany, the Netherlands, and the United States, where petrochemical complexes feed narrow-cut ethoxylation units. Feedstock dependencies draw from ethylene oxide, fatty alcohol hydrophobes, and advanced ethoxylation catalysts. Single-source vulnerability around specialized catalyst technology with narrow distribution control commands 40-60% premiums over conventional systems. Distribution runs through direct sales for pharmaceutical and large cosmetics accounts, with regional distributors serving mid-tier formulators lacking scale for framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH restrictions on conventional ethoxylates with uncontrolled ethylene oxide distribution erect a cost-of-compliance barrier that rewards producers with multi-jurisdictional certification capabilities and integrated C2 value chain access.
For Market Incumbents: Deploy backward integration into captive ethylene oxide supply to secure feedstock access against non-integrated entrant competition. Add narrow-cut capacity in Ludwigshafen and Marl industrial clusters to capture specification-driven substitution demand from EU-based cosmetics multinationals. Reinforce long-term offtake agreements with sustainability-mandated personal care brands to lock in volume commitments against catalyst technology licensors. For New Entrants and Emerging Players: Launch via distributor partnerships in São Paulo industrial parks linking European producers to Latin American crop protection markets. Target agrochemical adjuvant formulators in Brazil seeking batch-to-batch consistency certificates under ANVISA alignment pressures. Penetrate India's Maharashtra and Gujarat chemical corridors by retrofitting conventional ethoxylation assets to BIS narrow-range specifications ahead of domestic producer capacity additions. For Investors and Strategic Acquirers: Re-rating potential sits with integrated C2-C4 value chain operators given REACH dossier burdens and FDA drug master file requirements concentrating competitive advantage. Long-term viability favors producers with multi-jurisdictional certification capabilities and continuous flow reactor technology achieving sub-1.05 polydispersity indices. Monitor ECHA classification updates on residual 1,4-dioxane content as inflection indicator for purification investment cycles and margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Supply | Captive C2 feedstock access secures narrow-cut ethoxylation capacity against supply concentration risks in German industrial clusters. |
| Continuous Flow Reactor Technology Deployment | Inline near-infrared spectroscopy automation compresses batch release timelines from days to hours in Dutch production facilities. |
| Multi-Jurisdictional Certification Investment | Integrated REACH-FDA-EPA documentation packages capture specification premiums from Paris and Lyon cosmetics headquarters procurement. |
| Long-Term Offtake Agreements with Formulators | Volume commitments from sustainability-mandated personal care brands lock in narrow-range capacity utilization against demand volatility. |
| Specialized Catalyst Technology Licensing | Sub-1.05 polydispersity control capabilities differentiate supply relationships with dermal formulation specialists in New Jersey chemical corridors. |
Research Approach
Multi-period observation of ethoxylation capacity additions, regulatory filing timelines, and procurement specification changes anchored the trend analysis, supplemented by interviews with specialty chemical plant managers, downstream cosmetics procurement leads, agrochemical formulation directors, and pharmaceutical regulatory affairs specialists. Secondary validation drew from ECHA REACH dossiers, FDA drug master file submissions, SEC 10-K disclosures from integrated petrochemical producers, and Cefic surfactant production surveys. Bottom-up volume modeling triangulated against top-down value chain analysis across the projection horizon.
Segment-weighting applied product type, application, and end-use dimensions with polydispersity index thresholds as industry-specific stratification variable. CAGRs derived from regression analysis of historical capacity utilization against REACH regulatory phase-in schedules and downstream reformulation investment cycles. Forecast inputs incorporated catalyst technology adoption curves and biobased hydrophobe integration rates without year-specific assumptions.
Regulatory harmonization delays between EU and U.S. impurity thresholds, feedstock price volatility in ethylene oxide markets, and specialized process engineering talent scarcity are the dominant revision risks. Forecasts reflect documented assumptions on certification timeline compression and continuous reactor deployment rates. A model refresh is warranted upon material change in ECHA classification guidance or FDA parallel scrutiny intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Synthetic Wax Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Europe Wax Market
Oleochemicals
Lauryl Betaine Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Estolides Market
Oleochemicals
Oleochemicals Market