
 Estolides Market | 2026-2036
Estolides Market Size, Share, and Industry Trends Forecast 2026-2036
Estolides Market Foresight
Buyer concentration among personal care and lubricant formulators is restructuring procurement patterns across the estolides value chain. Biosynthetic Technologies leverages its biobased process platform to supply renewable estolide feedstocks. Croda International anchors European supply through its oleochemical expertise and sustainability certifications. Kao Corporation dominates Asian personal care channels with specialized emollient formulations.
Estolides are oligomeric esters synthesized from hydroxy fatty acids through condensation reactions, yielding viscous liquids with pour points below negative forty degrees Celsius and oxidative stability superior to conventional vegetable oils. Their primary commercial purpose centers on lubricant base stocks and cosmetic emollients where biobased content and thermal performance prove critical. Biobased Estolides command premium positioning as formulators seek renewable carbon content for Scope 3 reporting, while the Lubricants application segment sustains volume leadership through automotive and industrial fluid demand. Modified Estolides represent the fastest-growing product category as manufacturers tailor molecular architecture for specific viscosity and solubility requirements.
EPA biobased procurement guidelines and USDA BioPreferred program standards shape North American market access by mandating minimum renewable content thresholds for federal purchasing. REACH registration requirements under ECHA jurisdiction impose substance evaluation and safety data obligations on European estolide importers and manufacturers. Stakeholders must monitor evolving biobased certification schemes and lubricant performance specifications to align product development with procurement criteria that increasingly tie contract awards to verified sustainability metrics.
Market Dynamics
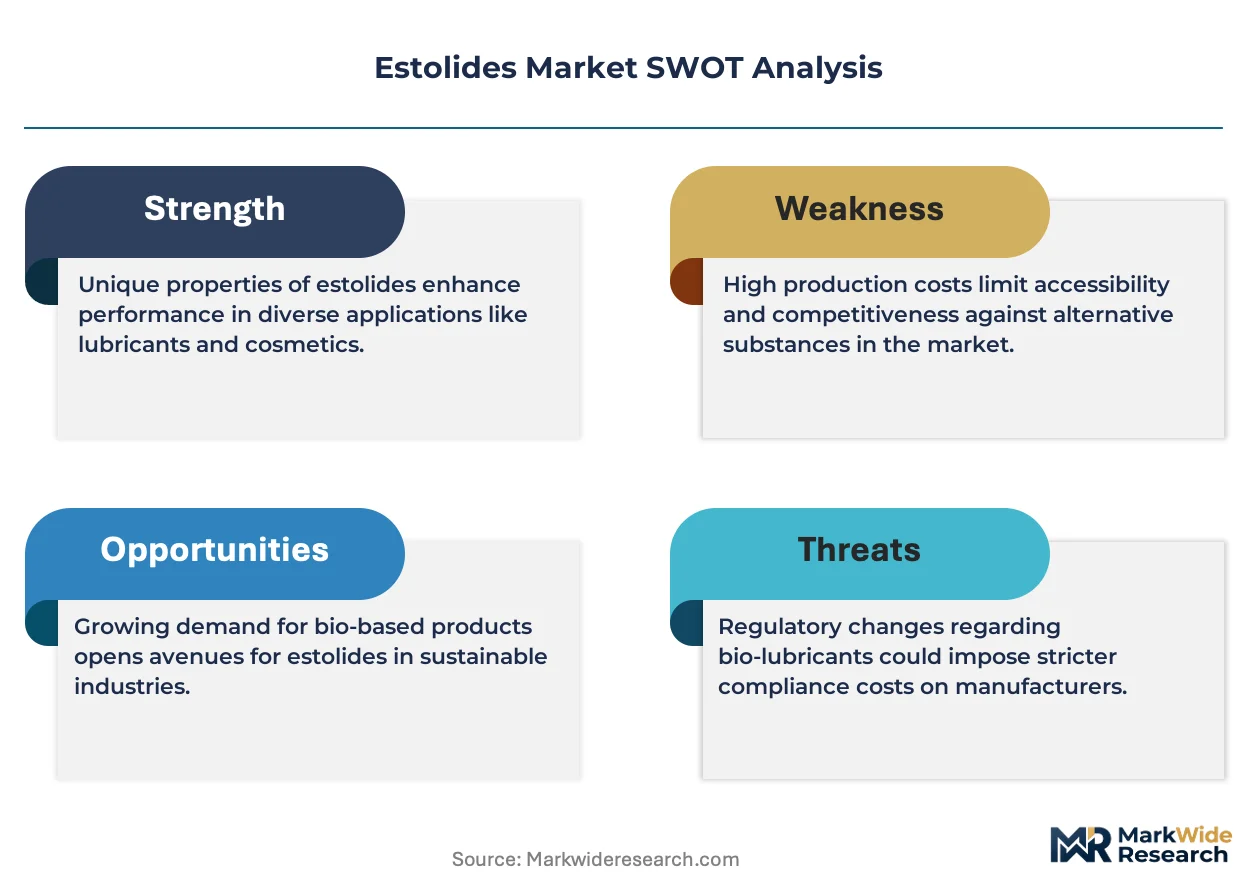
REACH registration requirements under ECHA jurisdiction are compressing formulation timelines as European personal care brands demand pre-certified biobased feedstocks with full safety dossiers already on file.
Growth Catalysts
- USDA BioPreferred Program:Federal procurement mandates in the United States require minimum renewable content thresholds for lubricant and personal care products, pulling estolide volumes into institutional supply chains.
- Automotive OEM fluid specifications:Extended drain intervals and lower viscosity grades in powertrain engineering are favoring estolide base stocks with superior oxidative stability.
- Cosmetic formulator consolidation:Large personal care houses in Germany and Japan are standardizing emollient portfolios around biobased esters to simplify Scope 3 carbon accounting.
Market Restraints
- Oleochemical feedstock volatility:Castor and meadowfoam oil prices fluctuate with agricultural yield cycles, compressing estolide producer margins during poor harvest seasons.
- Specialty chemical infrastructure concentration:Commercial-scale estolide production clusters in the United States, Germany, and Japan, exposing buyers to geographic supply risk.
- Polyalphaolefin substitution:Synthetic base stocks with established performance databases continue to dominate high-volume automotive lubricant formulations.
Strategic Opportunities
- Indian personal care market expansion:BIS biobased labeling schemes and rising middle-class consumption are creating entry points for estolide emollient suppliers.
- Aviation turbine oil applications:Thermal stability requirements in next-generation jet engines align with estolide pour point and oxidative performance profiles.
- EU Green Deal chemical sector targets:Mandatory renewable carbon quotas for industrial feedstocks will expand estolide eligibility in European manufacturing procurement.
Industry Challenges
- REACH data gap closure:ECHA substance evaluation timelines for novel estolide chemistries extend commercialization cycles by 18-24 months.
- Specialized condensation reactor engineering:Capital equipment for controlled oligomerization requires process expertise concentrated among a limited supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estolides Market |
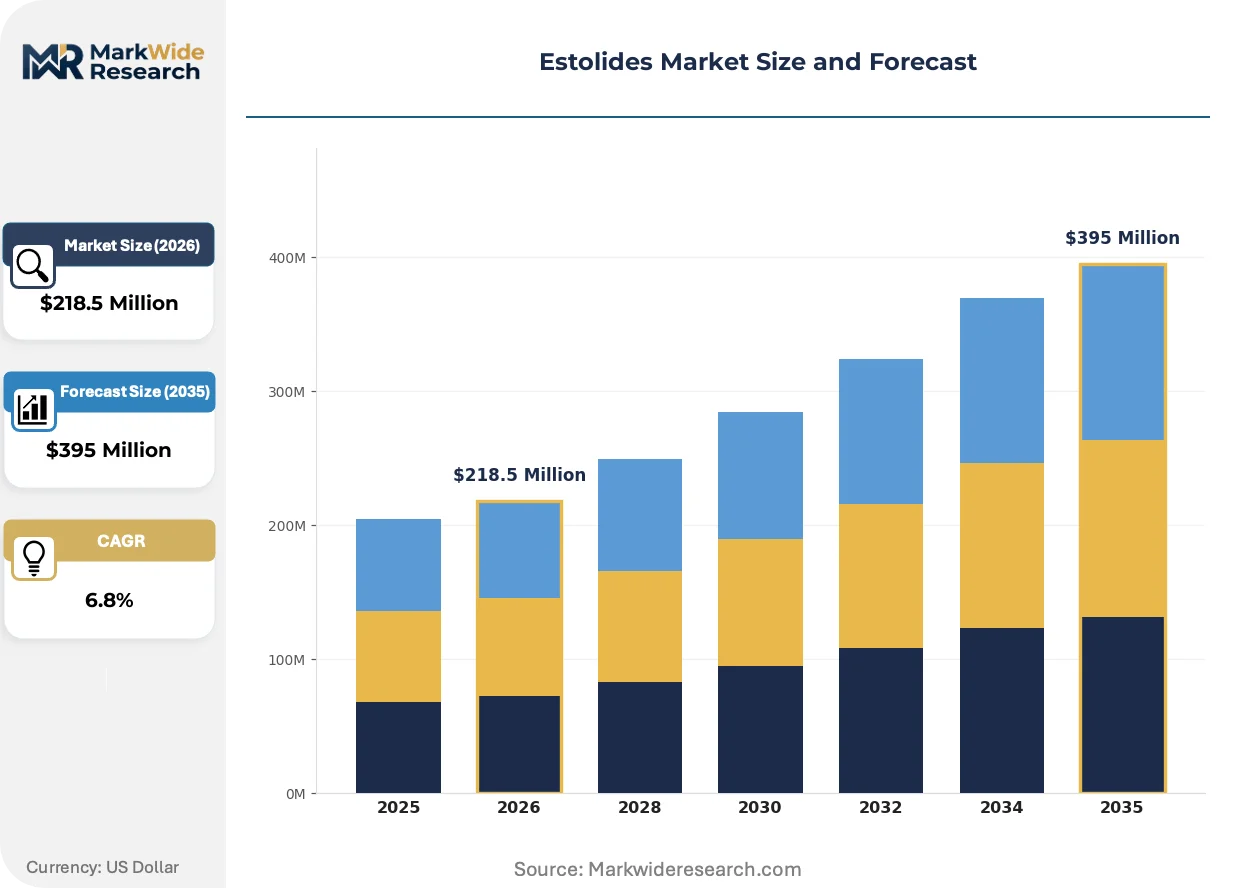
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $395 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Estolides, Synthetic Estolides, Biobased Estolides, Modified Estolides Application: Cosmetics, Lubricants, Coatings, Adhesives End User: Chemical Manufacturing, Automotive, Personal Care, Agriculture Form: Liquid, Solid, Powder, Emulsion |
| Companies Covered | Evonik, Clariant, Elementis, Kao Corporation, Croda International, Biosynthetic Technologies, STEPAN Company, Ashland, Calumet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estolides Market Shifts & Advancements
Process intensification and molecular architecture control are compressing development cycles as manufacturers seek to tailor estolide viscosity and solubility for specific end-use performance windows.
Enzymatic esterification pathways are modularizing production economics by enabling room-temperature condensation with reduced energy input. Specialty chemical producers in Germany and Japan are piloting these biocatalytic routes for cosmetic-grade estolide output. The technology is modularizing capital deployment decisions, allowing smaller batch facilities to serve regional formulator demand without scale-dependent unit cost penalties.
REACH authorization list expansion is tightening substitution obligations for persistent substances in lubricant formulations. European formulators must document safer alternatives for legacy base stock chemistries by 2026-2028 deadlines. Biobased estolide portfolios with pre-registered dossiers are capturing share in EU automotive and industrial fluid procurement.
Personal care ingredient buyers are consolidating supplier panels around vertically integrated oleochemical houses with captive estolide production. Large cosmetic brands in Japan and Germany now require direct feedstock traceability to plantation or fermentation origin. This concentration is compressing toll-manufacturer margins and favoring producers with backward integration into hydroxy fatty acid supply.
Estolides Market Segmentation
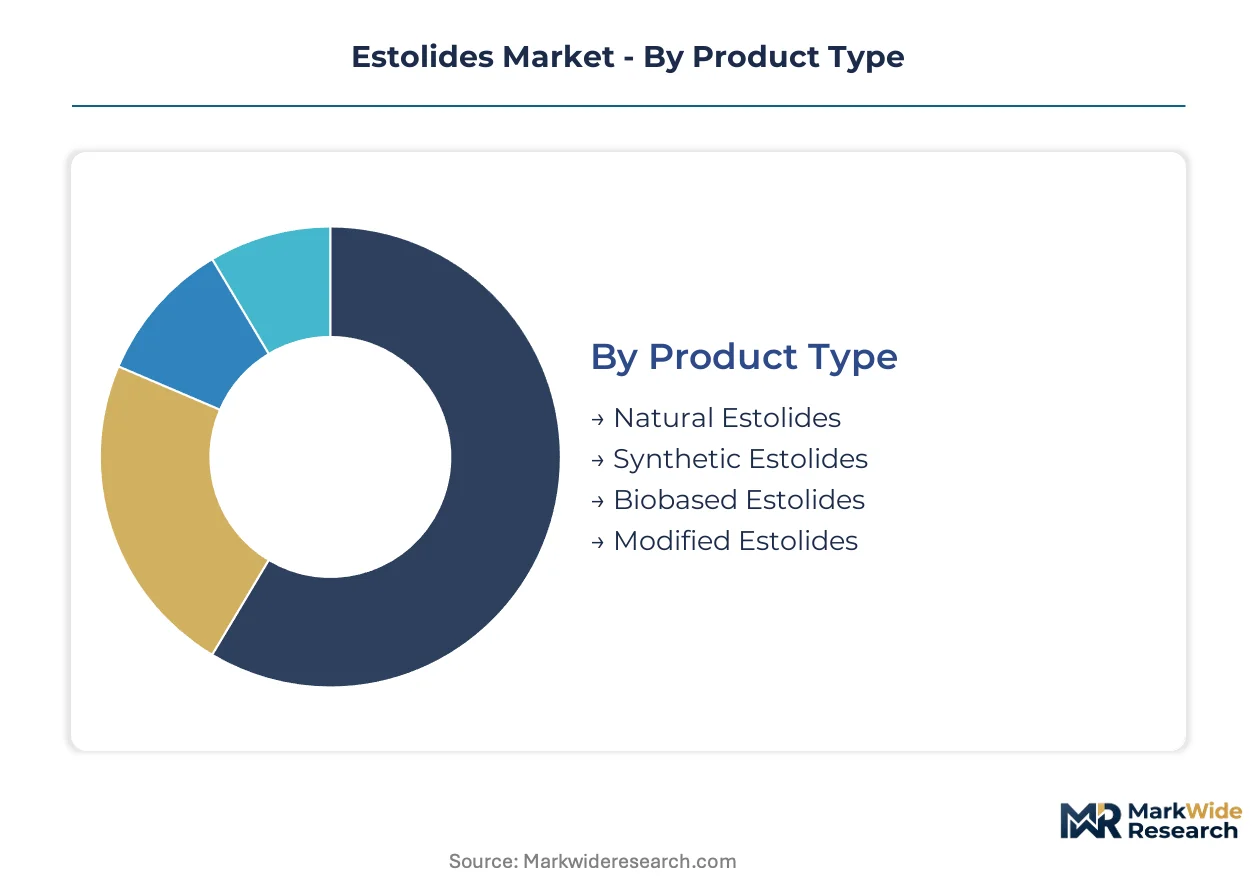
Estolide producers must navigate four distinct segmentation axes where technical specifications, regulatory positioning, and end-use performance requirements intersect. Each dimension carries unique margin implications and certification burdens that shape competitive strategy.
Product Type:
Volume leadership sits with established estolide chemistries, while premium positioning clusters around certified biobased variants with verified renewable carbon content.
- Natural Estolides:Derived directly from hydroxy fatty acid feedstocks such as castor and meadowfoam oils without synthetic modification. Demand concentrates in German and Japanese personal care formulators seeking ECHA-registered, plant-origin emollients with full traceability documentation.
- Biobased Estolides:Engineered for maximum renewable carbon content exceeding USDA BioPreferred thresholds. Procurement from United States federal contractors and automotive OEMs drives volume, as Scope 3 reporting requirements harden around verified biogenic content.
- Synthetic Estolides:Manufactured from petrochemical hydroxy acid precursors offering batch-to-batch consistency.
- Modified Estolides:Molecular architecture tailored for specific viscosity windows and solubility profiles.
Today's leader: Biobased Estolides. Tomorrow's challenger: Modified Estolides.
Application:
Application mix reflects divergent performance specifications between thermal-stability-critical industrial fluids and skin-contact cosmetic formulations.
- Lubricants:Base stock applications in automotive and industrial fluids leverage estolide pour points below negative forty degrees Celsius and oxidative stability superior to conventional vegetable oils. Extended drain intervals in powertrain engineering favor these properties.
- Cosmetics:Emollient applications demand cosmetic-grade purity with full REACH dossier compliance. German and Japanese personal care houses standardize procurement around biobased esters to streamline carbon accounting.
- Coatings:Film-forming and flow-control properties in protective surface treatments.
- Adhesives:Tack and flexibility modulation in pressure-sensitive formulations.
Volume dominance: Lubricants. Steepest expansion trajectory: Cosmetics.
End User:
Customer concentration varies sharply between consolidated automotive OEMs and fragmented agricultural formulators.
- Automotive:OEM fluid specifications mandate estolide base stocks for next-generation lower-viscosity powertrain designs. Procurement panels in the United States and Germany require pre-certified biobased content with full performance databases.
- Personal Care:Large cosmetic brands consolidate supplier panels around vertically integrated oleochemical houses with captive estolide production and direct plantation traceability.
- Chemical Manufacturing:Intermediate applications in specialty ester synthesis.
- Agriculture:Crop oil and adjuvant formulations with seasonal demand patterns.
Current procurement concentration: Automotive. Emerging demand center: Personal Care.
Form:
Physical state determines handling infrastructure requirements and formulation integration complexity.
- Liquid:Standard viscous estolide delivery form compatible with existing lubricant blending and cosmetic compounding equipment. Dominates commercial volumes due to processing efficiency.
- Emulsion:Aqueous dispersion systems enabling water-based cosmetic and coating formulations.
- Solid:Higher-melting point variants for controlled-release and wax applications.
- Powder:Spray-dried formats for dry blend compatibility.
Processing standard: Liquid. Fastest-gaining alternative: Emulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement volumes exceed German demand, yet Japanese formulators command tighter specifications for cosmetic-grade purity. Each geography imposes distinct regulatory entry barriers that reshape local competitive positioning.
United States
Automotive OEMs and federal contractors anchor demand through USDA BioPreferred program mandates for lubricant base stocks. EPA procurement guidelines require minimum renewable content thresholds for institutional supply contracts. Houston-Gulf Coast petrochemical corridors host specialty ester producers serving both automotive and personal care channels with integrated hydroxy fatty acid supply.
Germany
REACH-registered biobased emollients dominate procurement from consolidated cosmetic houses seeking streamlined Scope 3 carbon accounting. ECHA substance evaluation timelines compress commercialization cycles for novel estolide chemistries. Cologne-Düsseldorf oleochemical clusters concentrate vertically integrated production with captive castor oil processing and direct plantation traceability systems.
Japan
Personal care ingredient buyers consolidate supplier panels around producers with fermentation-origin feedstock documentation. METI biobased labeling schemes shape premium positioning for cosmetic applications. Osaka-Kobe chemical manufacturing belts sustain specialized emollient formulation capabilities serving domestic and export cosmetic brands.
India
Rising middle-class consumption and BIS biobased certification schemes create entry points for estolide emollient suppliers in skin-care and hair-care formulations. CDSCO cosmetic ingredient registration requirements impose safety data obligations on imported specialty esters. Maharashtra-Gujarat industrial corridors attract toll-manufacturing investments from global oleochemical houses seeking regional production presence.
China
Dual carbon policy targets and NMPA cosmetic ingredient filing requirements reshape import substitution dynamics for biobased esters. MIIT industrial feedstock guidelines favor renewable carbon quotas in lubricant and coating applications. Yangtze River Delta specialty chemical parks incubate domestic estolide production aimed at displacing imported cosmetic-grade volumes.
Estolides Market Competitive Landscape
United States producers anchor one tier with biobased process platforms; European specialists hold certification advantages through REACH-registered dossiers. Market structure fragments across three strategic tiers: multinational oleochemical houses with captive feedstock supply, mid-scale ester specialists serving regional formulator demand, and toll-manufacturers dependent on external hydroxy fatty acid procurement. Dominant competitive moves include backward integration into castor and meadowfoam oil supply, and strategic partnerships with cosmetic brands seeking direct plantation traceability.
Among Germany-based fabricators, Evonik and Clariant exemplify the multinational tier with integrated sustainability certifications and ECHA-registered portfolios. Kao Corporation represents Asian market anchoring through specialized emollient formulation capabilities. Croda International occupies a position bridging European supply security with global cosmetic channel access. Biosynthetic Technologies exemplifies the biobased process platform archetype with renewable feedstock engineering.
| Leading Market Players |
|---|
| Evonik |
| Clariant |
| Elementis |
| Kao Corporation |
| Croda International |
| Biosynthetic Technologies |
| STEPAN Company |
| Ashland |
| Calumet |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-registered biobased estolides and commodity synthetic variants manifests in both pricing premiums and supply chain configurations. USDA BioPreferred compliance and ECHA dossier completeness command valuation multiples that reflect captive hydroxy fatty acid supply and dedicated condensation reactor investments, while unregistered volumes compete on spot oleochemical input costs.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for cosmetic-grade estolides as enzymatic esterification routes reduce energy-intensive oligomerization costs. Three-tier pricing structure across premium, standard, and economy levels differentiates by renewable carbon verification and oxidative stability certification. Pricing pressure stems from castor oil harvest volatility compressing margins on natural estolide tiers. Automotive OEMs exhibit lowest price sensitivity due to performance database requirements, while agricultural adjuvant formulators drive volume negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale lubricant base stock demand, while specialty chemical distributors serve fragmented personal care compounders. Production clusters in the United States, Germany, and Japan anchor global supply, drawing from castor oil plantations in India and Brazil plus meadowfoam cultivation in Oregon. Feedstock concentration on agricultural yield cycles creates commodity price volatility risk. Distribution runs through vertically integrated oleochemical houses with captive estolide output and toll-manufacturing arrangements for regional cosmetic brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The estolides market compounds steadily as biobased procurement mandates harden across automotive and personal care procurement panels, embedding renewable carbon requirements into long-term contract structures.
For Market Incumbents: Deploy backward integration into hydroxy fatty acid supply to defend against polyalphaolefin substitution in automotive lubricant formulations. Secure ECHA pre-registration dossiers for modified estolide architectures before authorization list expansion tightens substitution timelines. Channel control through direct plantation traceability systems protects premium positioning against emerging biobased process platforms. For New Entrants and Emerging Players: The mid-tier price gap between premium biobased estolides and economy synthetic volumes offers white-space entry through BIS-compliant emollient supply for Indian personal care expansion. Aviation turbine oil specifications represent the most penetrable application segment given thermal stability alignment. A fermentation-origin feedstock narrative unlocks Japanese cosmetic brand procurement panels requiring METI biobased labeling documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH data gap closure extends commercialization cycles beyond 18 months, straining mid-scale ester specialists without captive safety dossier resources. Long-term viability favors vertically integrated oleochemical houses with backward integration into castor oil processing and direct cosmetic brand relationships. Watch for ECHA substance evaluation timeline acceleration as the inflection signal for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydroxy Fatty Acid Supply | Captive castor and meadowfoam oil sourcing secures margin protection against agricultural yield volatility. |
| Enzymatic Esterification Scale-Up | Room-temperature biocatalytic routes reduce energy input for cosmetic-grade estolide output in Germany and Japan. |
| REACH Pre-Registration Dossier Expansion | ECHA-registered modified estolide architectures capture EU automotive fluid procurement ahead of authorization deadlines. |
| Direct Plantation Traceability Systems | Full feedstock documentation satisfies Japanese cosmetic brand consolidation around vertically integrated suppliers. |
| Aviation Turbine Oil Qualification | Thermal stability certification opens next-generation jet engine lubricant specifications to estolide base stocks. |
Research Methodology
Bottom-up lubricant and cosmetics demand modeling reconciled against top-down hydroxy fatty acid supply tracking forms the analytical core. Primary interviews with estolide plant managers, procurement leads at automotive OEMs, personal care R&D directors, and specialty chemical distribution partners cross-validated secondary sources including ECHA registration databases, USDA BioPreferred product listings, SEC 10-K filings from listed oleochemical houses, and customs trade data on castor oil derivatives. Triangulation between consumption-side volume builds and production-capacity assessments ensures dimensional consistency.
Input-output matrices map feedstock availability, condensation reactor utilization, and end-use specification requirements across the projection horizon. Segmentation dimensions include product type tier, application performance window, end-user procurement concentration, and regional regulatory cluster. CAGRs derive from slope analysis of normalized adoption curves against biobased mandate implementation schedules, with oxidative stability benchmarking and pour point specifications informing lubricant segment elasticity assumptions.
Caveats apply where ECHA substance evaluation timeline acceleration or castor oil harvest disruption could materially shift the outlook. Forecasts embed assumptions around enzymatic route scale-up economics and automotive OEM fluid specification stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
Europe Wax Market
Oleochemicals
Glycerol Esters Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Ethylhexyl Cocoate Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Paraffin Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
US Esters Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Decanoyl Chloride Market