
 Global Chlorinated Paraffin Market | 2026-2036
Global Chlorinated Paraffin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlorinated Paraffin Market Foresight
Specialty chemical distribution channels across South Asia and the Middle East are reconfiguring as regional traders consolidate warehousing positions near chlor-alkali clusters. INOVYN leverages its European chlor-alkali backbone to sustain captive feedstock flows into chlorinated paraffin lines. Aditya Birla Chemicals anchors Indian supply through its Gujarat manufacturing base, while KLJ Group competes on specialized plasticizer grades for domestic cable compounders.
Chlorinated paraffins are chlorinated derivatives of n-paraffins with chlorine content typically ranging from 30% to 70% by weight, produced via thermal chlorination or photochlorination of paraffin wax feedstocks. These compounds function primarily as secondary plasticizers, extreme-pressure lubricant additives, and flame-retardant synergists in polyvinyl chloride and metalworking formulations. Medium-chain grades occupy the largest volume position due to their balanced compatibility across lubricant and plasticizer applications, while long-chain variants are gaining formulation share as regulatory pressure curtails short-chain availability in protective coatings. The flame-retardant additive segment commands premium positioning in electronics manufacturing, where halogenated compounds must meet stringent thermal stability thresholds.
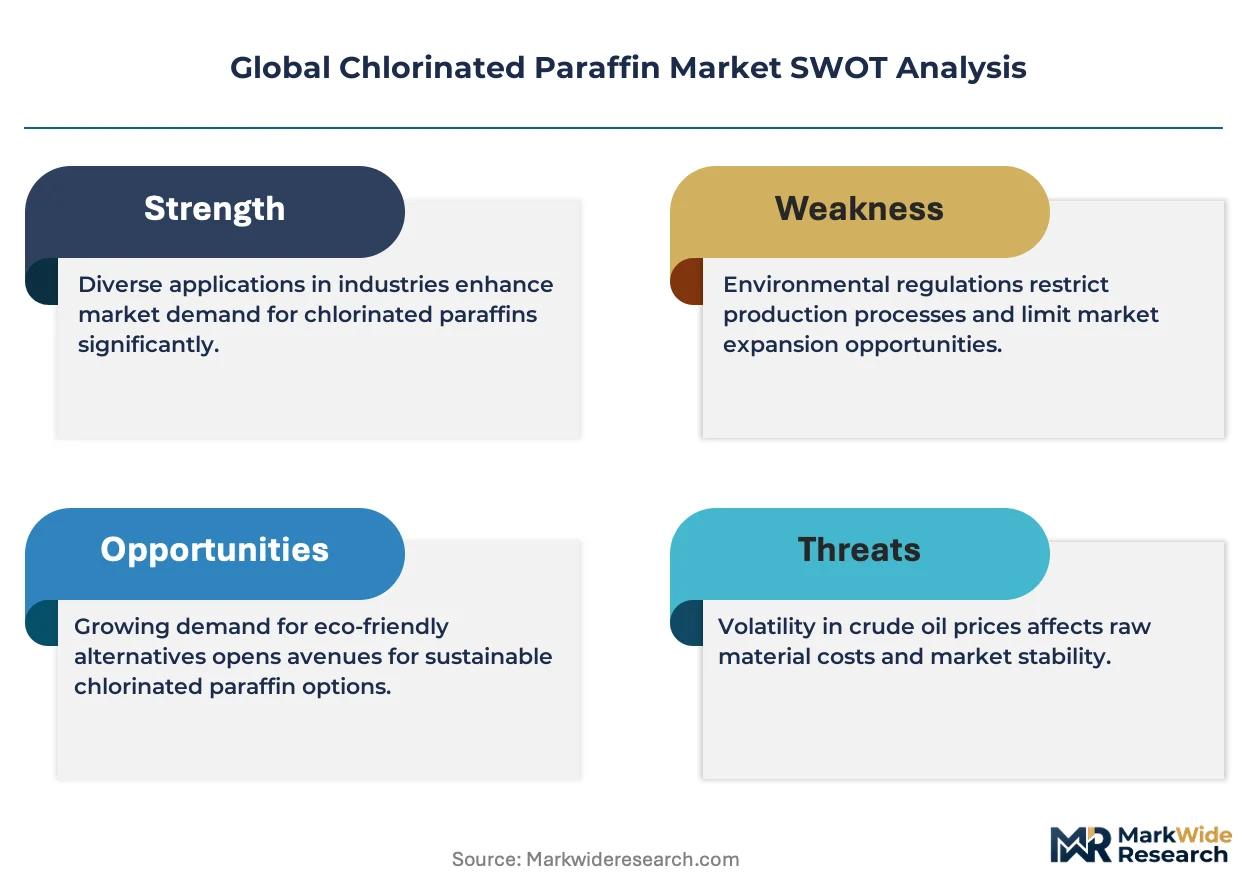
EPA scrutiny under the Toxic Substances Control Act and ECHA's REACH restrictions on short-chain chlorinated paraffins are reshaping permissible product portfolios and import documentation requirements across North American and European markets. India's BIS certification mandates and China's GB standards on chlorinated hydrocarbons in industrial applications add compliance layers for cross-border suppliers. Stakeholders must monitor regulatory reclassification timelines and pre-register alternative chemistries before existing formulation approvals lapse in key jurisdictions.
Market Dynamics
REACH restrictions on short-chain chlorinated paraffins are forcing formulation houses across Europe to rebuild product portfolios around medium-chain and long-chain alternatives, compressing R&D timelines and redirecting raw material procurement toward integrated chlor-alkali producers.
Growth Catalysts
- Metalworking fluid demand:Indian machining centers are expanding consumption of medium-chain grades as domestic automotive and aerospace component manufacturing scales.
- Flame-retardant mandates:Electronics manufacturers in East Asia face tightening thermal stability requirements for wire and cable compounds, pulling chlorinated paraffin volumes into PVC jacketing applications.
- REACH regulatory pivot:European formulators are accelerating long-chain grade adoption to maintain product registrations, creating sustained pull for C18-C30 chain lengths in protective coatings.
Market Restraints
- Feedstock cost volatility:Paraffin wax prices track crude oil movements, compressing margin stability for non-integrated chlorinators lacking captive slack wax supply.
- Substitution pressure:Phosphate ester and brominated flame retardants are capturing specification share in high-end electronics where halogen content faces brand-level restrictions.
- Supply concentration risk:Shandong province dominates global chlor-alkali integrated output, exposing downstream buyers to localized environmental enforcement disruptions.
Strategic Opportunities
- Brazilian industrial expansion:ANVISA registration pathways for chlorinated hydrocarbons remain underpenetrated by Asian exporters, offering first-mover positioning in Latin American cable compounding.
- Bio-based feedstock integration:Hydrotreated vegetable oil wax streams are converging with conventional chlorination infrastructure, enabling carbon intensity claims for EU-bound product.
- PLI scheme alignment:India's production-linked incentive framework for specialty chemicals rewards domestic chlor-alkali expansion, lowering capital barriers for integrated paraffin chlorination capacity.
Industry Challenges
- REACH pre-registration complexity:Formulators face compressed timelines to dossier alternative chemistries before 2027 sunset clauses eliminate short-chain approvals.
- Chlorine handling certification:New plant commissioning requires extended permitting for pressurized chlorine systems, stretching project timelines by 18-24 months in most jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlorinated Paraffin Market |
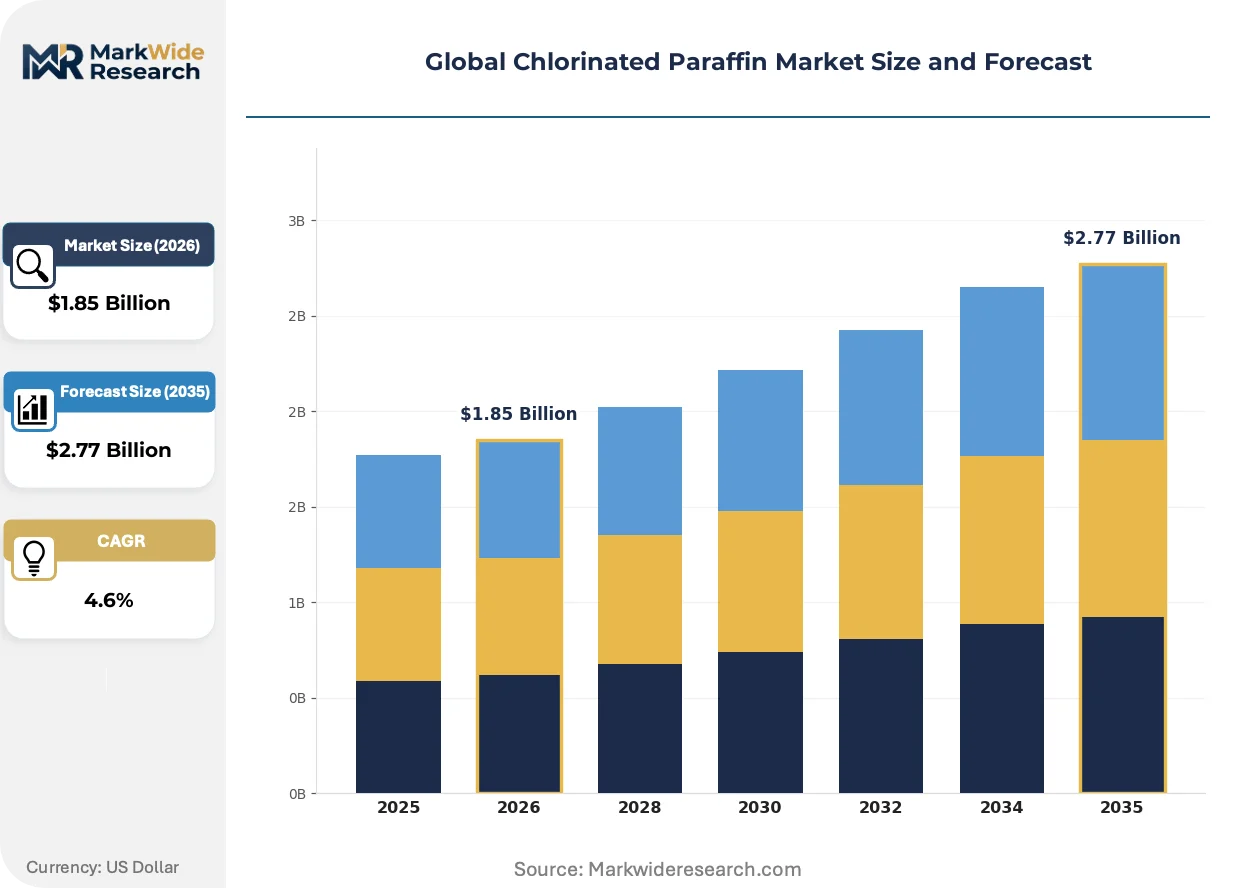
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short Chain, Medium Chain, Long Chain, Special Grade Application: Plasticizers, Lubricants, Flame Retardants, Additives End User Industry: Construction, Electronics Manufacturing, Metalworking, Paints & Coatings Packaging Type: Drums, Totes, Bulk Containers, Intermediate Bulk Containers |
| Companies Covered | JSC Kaustik, Aditya Birla Chemicals, INOVYN, Altair Chimica SpA, KLJ Group, Dover Chemical Corporation, LEUNA-Tenside GmbH, Caffaro Industrie S.p.A, Grasim Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlorinated Paraffin Market Shifts & Advancements
Formulation chemistry is pivoting around regulatory survival rather than performance optimization, with R&D investment concentrating on chain-length substitution strategies and feedstock traceability systems that satisfy emerging due diligence requirements.
Photochlorination reactor technology is migrating from batch to continuous-flow configurations, enabling tighter chlorine distribution control across paraffin chain lengths. Specialty lubricant blenders in Germany and Japan are adopting these systems to meet narrow viscosity specifications for aerospace metalworking fluids. The shift is compressing capital requirements for mid-scale producers while raising technical barriers for legacy thermal chlorination operators.
ECHA's 2022 restriction on short-chain chlorinated paraffins in consumer articles has triggered cascading documentation demands across European supply chains. Industrial coating formulators must now certify chain-length composition through carbon-number testing, adding analytical costs that favor integrated producers with in-house chromatography capabilities. The burden falls heaviest on import-dependent distributors lacking direct feedstock provenance.
Buyer consolidation among Indian cable compounders is compressing supplier rosters and extending contract durations. Domestic manufacturers like Polycab and KEI Industries are demanding multi-year supply agreements with fixed chlorine content specifications, displacing spot-market purchasing that previously dominated regional trade. The shift concentrates volume with chlor-alkali integrated suppliers capable of backward control over paraffin feedstock quality.
Global Chlorinated Paraffin Market Segmentation
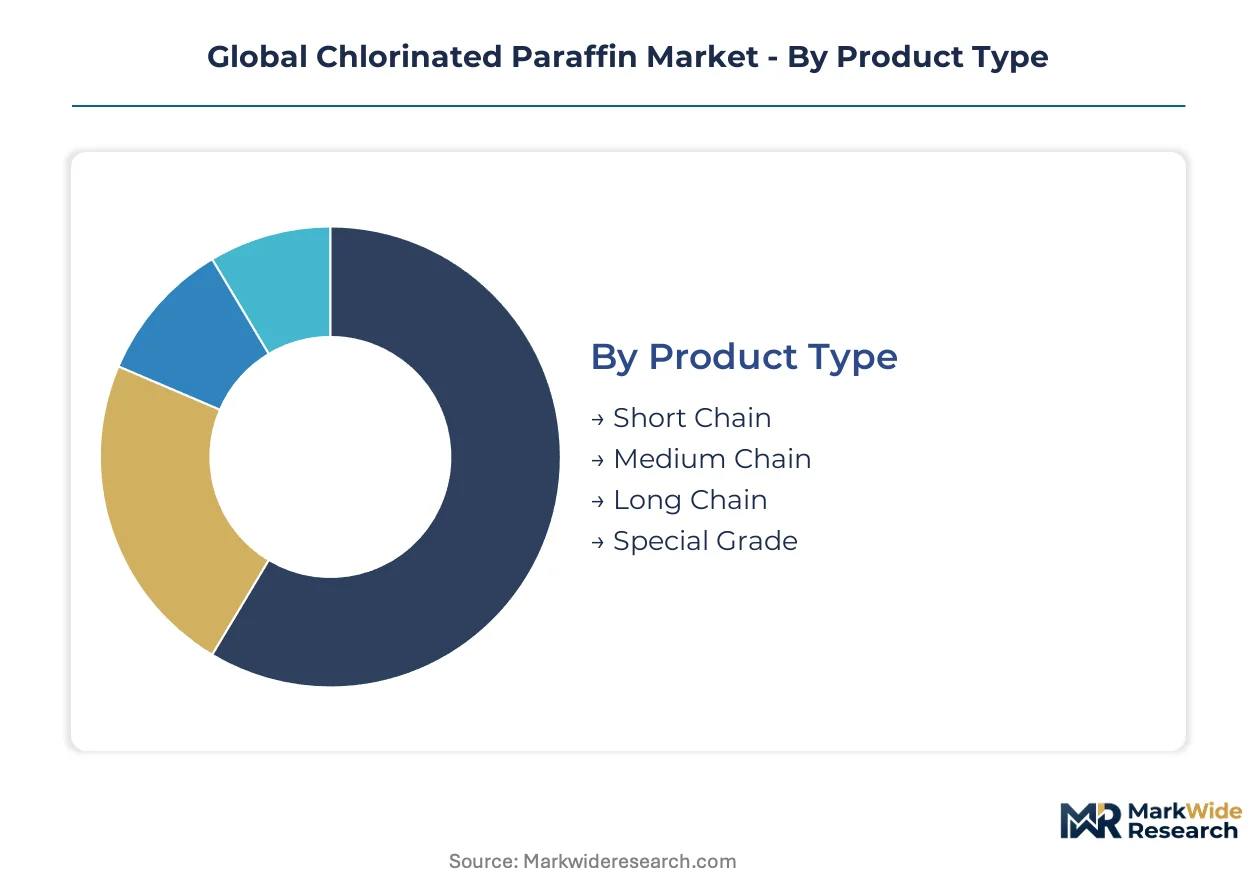
Segmentation in chlorinated paraffins tracks how regulatory pressure on chain-length chemistry reshapes procurement patterns across formulation houses. Buyers segment supply by carbon distribution to manage REACH compliance exposure and by packaging format to optimize chlorine-handling logistics at plant gates.
Product Type:
Inventory velocity varies sharply across chain lengths, with short-chain stocks turning fastest amid sunset-clause destocking while long-chain positions accumulate as formulators rebuild compliant formulations.
- Short Chain:Carbon-chain distributions of C10-C13 with chlorine content typically 40-70%. European coating formulators are liquidating positions ahead of ECHA's complete phase-out deadlines, compressing spot availability for legacy metalworking fluid recipes still permitted in non-consumer industrial applications.
- Medium Chain:C14-C17 chain lengths balance compatibility across plasticizer and lubricant applications. Indian automotive component manufacturers are expanding offtake as domestic machining activity intensifies, pulling volumes toward Gujarat and Maharashtra industrial corridors.
- Long Chain:C18-C30 variants with superior thermal stability profiles. REACH-driven substitution is accelerating specification migration in European protective coatings.
- Special Grade:Narrow-cut fractions for aerospace and electronics applications requiring certified carbon-number distribution. German and Japanese lubricant blenders specify these for narrow viscosity tolerances.
Medium chain dominates installed base. Long chain is where expansion concentrates.
Application:
Margin structures diverge by functional chemistry, with flame-retardant specifications commanding analytical certification premiums that commodity plasticizer grades cannot support.
- Plasticizers:Secondary plasticizer function in PVC compounding, extending primary phthalate or adipate performance. Cable jacketing demand in India and China absorbs the largest volume flows, with KEI Industries and Polycab consolidating supplier rosters around integrated chlor-alkali sources.
- Lubricants:Extreme-pressure additives for metalworking fluids, functioning through chlorine's reactivity with ferrous surfaces at cutting-zone temperatures. German aerospace fluid formulators are adopting photochlorination-derived grades for tighter viscosity control.
- Flame Retardants:Synergist role in halogenated systems, enhancing char formation. Electronics manufacturers in East Asia face tightening thermal stability specifications for wire and cable compounds.
- Additives:Ancillary functions including sealant plasticization and adhesive modification. Construction sector demand tracks regional building activity cycles.
Plasticizers anchor volume throughput. Flame retardants are climbing the fastest on specification premiums.
End User Industry:
Customer concentration patterns separate project-driven construction purchasing from continuous manufacturing demand in electronics and metalworking.
- Construction:PVC membrane and sealant applications with cyclical demand tied to infrastructure spending. Chinese provincial stimulus packages are sustaining Shandong province consumption.
- Electronics Manufacturing:Wire and cable jacketing for consumer electronics and data infrastructure. Thermal stability thresholds are tightening for server farm and telecommunications cable specifications.
- Metalworking:Cutting and grinding fluid formulations, the original application category. Indian machining centers are expanding consumption as domestic automotive and aerospace component manufacturing scales.
- Paints & Coatings:Protective and marine coatings, where long-chain substitution is most advanced due to REACH short-chain restrictions. European industrial coating formulators now require carbon-number certification.
Metalworking retains the deepest installed specification base. Electronics manufacturing is gaining share fastest on cable compounding expansion.
Packaging Type:
Handling economics and chlorine safety protocols segment procurement by delivery scale, with integrated producers favoring bulk configurations that maximize logistics efficiency.
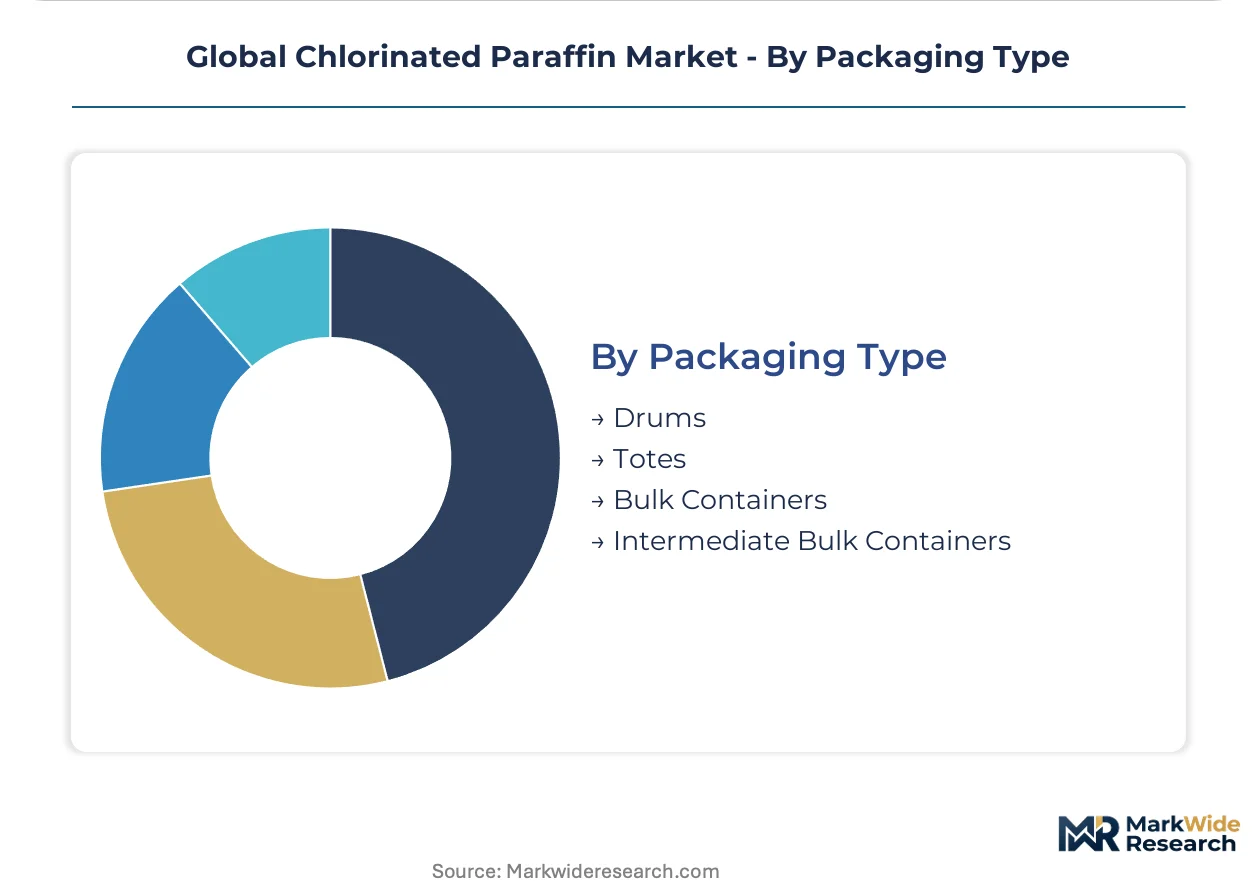
- Drums:Standard 200-liter steel containers for mid-volume formulators lacking bulk unloading infrastructure. Spot-market purchasers in fragmented distribution channels rely on this format.
- Totes:Intermediate flexible or rigid containers for regional compounders with moderate throughput. Specialty lubricant blenders in Germany specify totes for photochlorination-derived grades requiring controlled handling.
- Bulk Containers:Tank truck and railcar deliveries for chlor-alkali integrated producers supplying captive or contractually bound formulation houses. Aditya Birla Chemicals and INOVYN leverage this format for Gujarat and European supply bases.
- Intermediate Bulk Containers:1000-liter standardized units for multi-site manufacturers seeking to balance inventory flexibility with unit cost reduction.
Bulk containers dominate integrated supply relationships. Totes are expanding most quickly among mid-scale specialty formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port container terminals anchor Shandong province's dominance in chlor-alkali integrated chlorinated paraffin output, handling bulk chemical flows that feed downstream formulation houses across East Asia.
China
Shandong province concentrates captive chlor-alkali capacity that supplies metalworking fluid compounders and PVC cable manufacturers. GB standards on chlorinated hydrocarbons mandate carbon-number documentation for industrial applications. The Yangtze River Delta electronics manufacturing corridor pulls long-chain grades for wire and cable jacketing as thermal stability specifications tighten.
Germany
Specialty lubricant blenders in Bavaria and Baden-Württemberg specify photochlorination-derived narrow-cut fractions for aerospace metalworking fluids. REACH restrictions on short-chain formulations force protective coating houses to rebuild portfolios around C18-C30 alternatives. The Ruhr industrial region hosts formulation R&D facilities accelerating long-chain grade adoption.
India
Gujarat's chlor-alkali manufacturing base anchors domestic supply through integrated paraffin chlorination capacity serving cable compounders in Maharashtra. BIS certification mandates add compliance layers for cross-border suppliers. The Delhi-Mumbai Industrial Corridor expands machining activity, pulling medium-chain grades into automotive component manufacturing.
United States
EPA scrutiny under the Toxic Substances Control Act reshapes permissible product portfolios for metalworking fluid formulators in the Midwest manufacturing belt. The Gulf Coast petrochemical corridor provides paraffin wax feedstock flows to chlorination facilities. Ohio and Michigan machining centers sustain demand for extreme-pressure lubricant additives.
Brazil
ANVISA registration pathways for chlorinated hydrocarbons remain underpenetrated by Asian exporters, creating first-mover positioning opportunities in Latin American cable compounding. São Paulo state industrial parks host PVC manufacturers seeking secondary plasticizer supply. The Southeast region's automotive wire harness production pulls flame-retardant synergist volumes.
Global Chlorinated Paraffin Market Competitive Landscape
On the supply side, the industry is consolidating around chlor-alkali integrated producers with captive feedstock control, compressing margins for non-integrated operators exposed to paraffin wax price volatility. Three archetypes dominate: integrated chemical conglomerates with backward control over chlorine and paraffin supply, regional specialists competing on specialized grade certification, and distribution-focused traders managing regulatory documentation burdens. Capacity expansion and portfolio diversification toward long-chain alternatives represent the dominant competitive moves as regulatory sunset clauses approach.
Within the integrated chemical conglomerate tier, INOVYN and Aditya Birla Chemicals exemplify producers leveraging captive chlor-alkali infrastructure to sustain feedstock cost advantages. KLJ Group occupies a position among specialized regional suppliers competing on dedicated plasticizer grades for domestic cable compounders. These three entities represent the competitive positioning spectrum from scale-driven integration to niche specialization.
| Leading Market Players |
|---|
| JSC Kaustik |
| Aditya Birla Chemicals |
| INOVYN |
| Altair Chimica SpA |
| KLJ Group |
| Dover Chemical Corporation |
| LEUNA-Tenside GmbH |
| Caffaro Industrie S.p.A |
| Grasim Industries Limited |
| Others |
Supply & Pricing Matrix
Shandong province's chlor-alkali integration concentrates captive paraffin chlorination output, anchoring margin pools with integrated producers while exposing non-integrated operators to paraffin wax cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume commitment. Premium tiers attach to photochlorination-derived narrow-cut fractions with carbon-number documentation for REACH compliance, while economy tiers serve spot-market drum purchasers without feedstock provenance. Cost compression in standard grades is intensifying because Indian cable compounders are consolidating supplier rosters around fixed-price multi-year contracts. Spot-market buyers in fragmented distribution channels exhibit highest price sensitivity; integrated formulators with captive chlorine supply show least.
Supply Chain Analysis
Paraffin wax feedstock streams from Gulf Coast petrochemical corridors and Middle Eastern slack wax refiners tether chlorination output to crude oil movements. China, India, and Germany anchor finished product supply, with Shandong province, Gujarat state, and the Ruhr industrial region hosting integrated production clusters. Single-source vulnerability concentrates in Shandong's environmental enforcement exposure. Distribution runs through bulk tanker deliveries for integrated producers and steel drum channels for spot purchasers lacking unloading infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photochlorination reactor engineering and REACH-compliant carbon-number certification represent scarce technical capabilities that separate viable competitors from margin-compressed commodity suppliers.
For Market Incumbents: Pre-empt regulatory displacement by accelerating long-chain grade capacity ahead of ECHA sunset clauses. Backward integration into captive slack wax supply defends margin position against feedstock volatility. Invest in continuous-flow photochlorination systems to capture aerospace metalworking fluid specifications that thermal chlorination cannot meet. For New Entrants and Emerging Players: Brazilian ANVISA registration pathways offer underpenetrated white-space for Asian exporters seeking Latin American cable compounding entry. India's PLI scheme for specialty chemicals lowers capital barriers for integrated chlor-alkali expansion. Target bio-based feedstock certification as differentiation lever for EU-bound product positioning. For Investors and Strategic Acquirers: Capital is best deployed toward chlor-alkali integrated producers with captive paraffin supply and in-house chromatography capabilities for REACH documentation. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Watch for ECHA enforcement acceleration as inflection signal for short-chain inventory destocking velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paraffin Feedstock | Captive slack wax supply insulates margin from crude-linked volatility for INOVYN and Aditya Birla. |
| Photochlorination Capacity Expansion | Continuous-flow reactors enable narrow-cut fraction output for German aerospace lubricant specifications. |
| REACH Pre-Registration Dossier Completion | Alternative chemistry documentation ahead of sunset clauses preserves European market access. |
| Bio-Based Feedstock Certification | Hydrotreated vegetable oil integration supports carbon intensity claims for EU Green Deal alignment. |
| Brazilian ANVISA Registration | First-mover positioning in Latin American cable compounding escapes Asian supply concentration. |
Research Methodology
Operator-level perspectives from chlor-alkali plant managers, PVC cable compounder procurement leads, metalworking fluid R&D directors, and specialty chemical distribution channel partners anchored the qualitative base. Secondary validation drew from ECHA restriction dossiers, Indian BIS certification records, Chinese GB standards documentation, and customs trade flow data. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation by chain-length grade, end-use application, packaging format, and regional production hub. CAGRs derived from regression against industrial output indices and regulatory phase-out timelines. Forecast inputs incorporated chlorine handling permitting delays and photochlorination technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed producers or accelerated ECHA enforcement would shift outcomes. Cross-checking against chlor-alkali industry capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Higher Olefins Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
Squalane Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Glycerine Market
Oleochemicals
1-Decene Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Diisostearyl Fumarate Market