
 Asia-Pacific Oleochemicals Market | 2026-2036
Asia-Pacific Oleochemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oleochemicals Market Analytics
Buyer concentration in Asia-Pacific oleochemicals is pivoting as multinational personal care brands consolidate supplier rosters while regional mid-tier formulators fragment procurement across specialty distributors. Wilmar International Ltd leverages its integrated palm oil-to-oleochemicals chain to sustain cost leadership across fatty acid supply. KLK OLEO anchors Malaysian production capacity with backward integration into plantation assets. IOI Corporation Berhad competes through specialty glycerol and ester derivatives that command premium positioning in pharmaceutical-grade segments.
Oleochemicals comprise fatty acids, fatty alcohols, methyl esters, and glycerol derived from natural oils and fats through hydrolysis, transesterification, or hydrogenation, serving as biodegradable replacements for petrochemical surfactants and lubricant bases. Fatty acids dominate volume flows into soap and detergent manufacturing, where margin pools remain deepest due to scale economics. Fatty alcohols represent the fastest-growing structural segment as personal care brands shift formulation toward ethoxylated surfactants with lower aquatic toxicity profiles. Glycerol supply tightens intermittently as biodiesel policy fluctuations redirect feedstock volumes, concentrating margin volatility in refined pharmaceutical and food-grade tiers.
Malaysia's Department of Standards enforces MSPO certification thresholds that shape export market access for palm-derived oleochemicals, while Indonesia's Ministry of Industry implements downstream processing mandates that redirect crude palm oil toward domestic fatty acid and alcohol production. China's SAMR enforces GB standards for food-grade glycerol purity that filter which regional producers qualify for cross-border pharmaceutical and food ingredient sales. Stakeholders must monitor feedstock certification divergence between Indonesian and Malaysian sustainability frameworks, as incompatible traceability requirements threaten to fragment supply chain compliance costs across Southeast Asian production networks.
Market Dynamics
Integrated oleochemical complexes in Indonesia and Malaysia are consolidating feedstock control while personal care brands accelerate reformulation toward plant-derived surfactants, tightening specification requirements across fatty acid and glycerol supply tiers.
Growth Catalysts
- MSPO Certification Thresholds:Malaysia's Department of Standards mandates sustainable palm certification that unlocks premium export channels for fatty acid producers targeting European and North American personal care formulators.
- Fatty Alcohol Ethoxylation:Personal care brands are substituting petrochemical surfactants with ethoxylated fatty alcohols to meet aquatic toxicity reduction targets, pulling volume through integrated Malaysian production complexes.
- Indonesia:Downstream processing mandates from the Ministry of Industry redirect crude palm oil toward domestic fatty acid and methyl ester production, capturing margin previously exported as raw feedstock.
Market Restraints
- Crude Palm Oil Price Volatility:Feedstock cost swings compress margin pools for non-integrated fatty acid producers lacking captive plantation supply.
- Biodiesel Policy Fluctuations:Indonesian and Malaysian biofuel mandates intermittently divert glycerol feedstock volumes, creating supply tightness in pharmaceutical and food-grade refined tiers.
- Technical Limitation:Current hydrogenation catalysts impose yield ceilings on C12-C14 fatty alcohol production, constraining output growth for premium surfactant applications.
Strategic Opportunities
- Vietnam:Underpenetrated personal care manufacturing base offers first-mover positioning for fatty acid distributors establishing technical service capabilities.
- Pharmaceutical-Grade Glycerol:China's SAMR-enforced GB standards for food-grade purity create qualification barriers that reward producers investing in refining asset upgrades.
- Enzymatic Transesterification:Convergence of biocatalysis and continuous processing technology enables lower-temperature methyl ester production with reduced energy intensity.
Industry Challenges
- Specialized Process Engineering Talent:Shortage of hydrogenation and distillation specialists delays commissioning timelines for new fatty alcohol capacity additions.
- Traceability System Integration:Divergent Indonesian and Malaysian sustainability certification platforms fragment compliance documentation requirements across Southeast Asian supply networks.
- Capex Intensity:Pharmaceutical-grade glycerol refining trains require stainless steel construction and GMP-compliant infrastructure that extends payback periods versus commodity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oleochemicals Market |
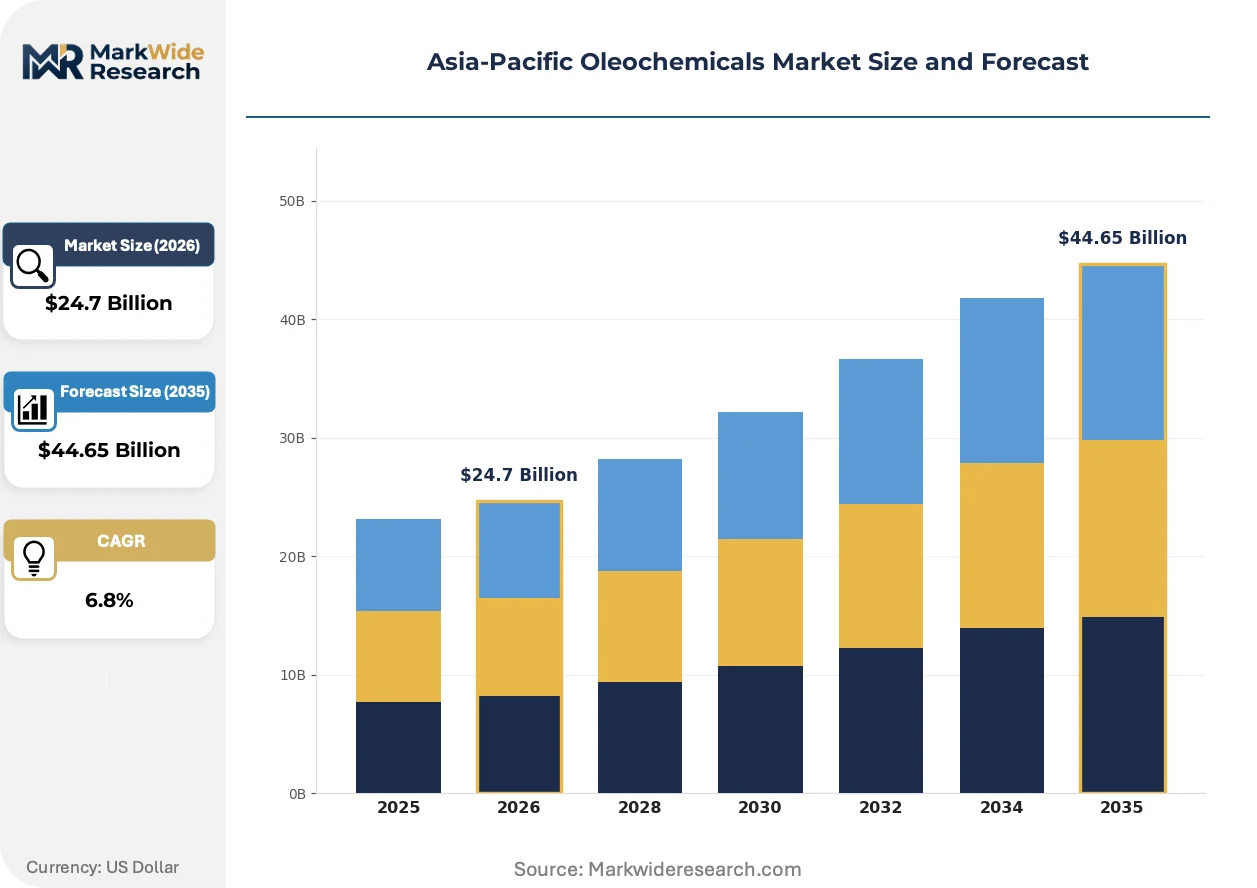
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Alcohols, Fatty Acids, Glycerol, Methyl Ester End User: Personal Care, Food & Beverage, Pharmaceuticals, Animal Feed Application: Surfactants, Emulsifiers, Lubricants, Cleaners Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Wilmar International Ltd, Emery Oleochemicals, KLK OLEO, IOI Corporation Berhad, Musim Mas, Ecogreen Oleochemicals, Kao Corporation, Croda International Plc, Sinarmas Cepsa Pte. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oleochemicals Market Evolving Landscape
Biocatalytic process intensification and sustainability certification digitization are compressing traditional production economics while reshaping how buyers qualify suppliers across the Asia-Pacific oleochemicals value chain.
Enzymatic interesterification is absorbing capital allocation from chemical catalyst systems in new methyl ester capacity builds. Specialty chemical distributors serving Japanese and South Korean personal care formulators are specifying enzymatic routes in procurement tenders. This technology is absorbing margin pressure from energy-intensive thermal processing by cutting reaction temperatures and reducing downstream purification steps.
Indonesia's sustainable palm certification requirements are tightening documentation standards for export-bound fatty acid shipments. The Ministry of Industry now mandates chain-of-custody verification that traces feedstock to certified plantation blocks. Small and mid-tier producers without integrated plantation assets face compliance cost escalation that favors scaled competitors with captive upstream supply.
Personal care brands are consolidating supplier rosters from fragmented distributor networks toward direct contracting with integrated oleochemical producers. Multinational formulators in Thailand and the Philippines are bypassing regional traders to secure specification-grade fatty alcohols with locked-in MSPO documentation. This concentration is most visible in premium ethoxylated surfactant procurement, where batch consistency and certification reliability outweigh spot price advantages.
Asia-Pacific Oleochemicals Market Segmentation
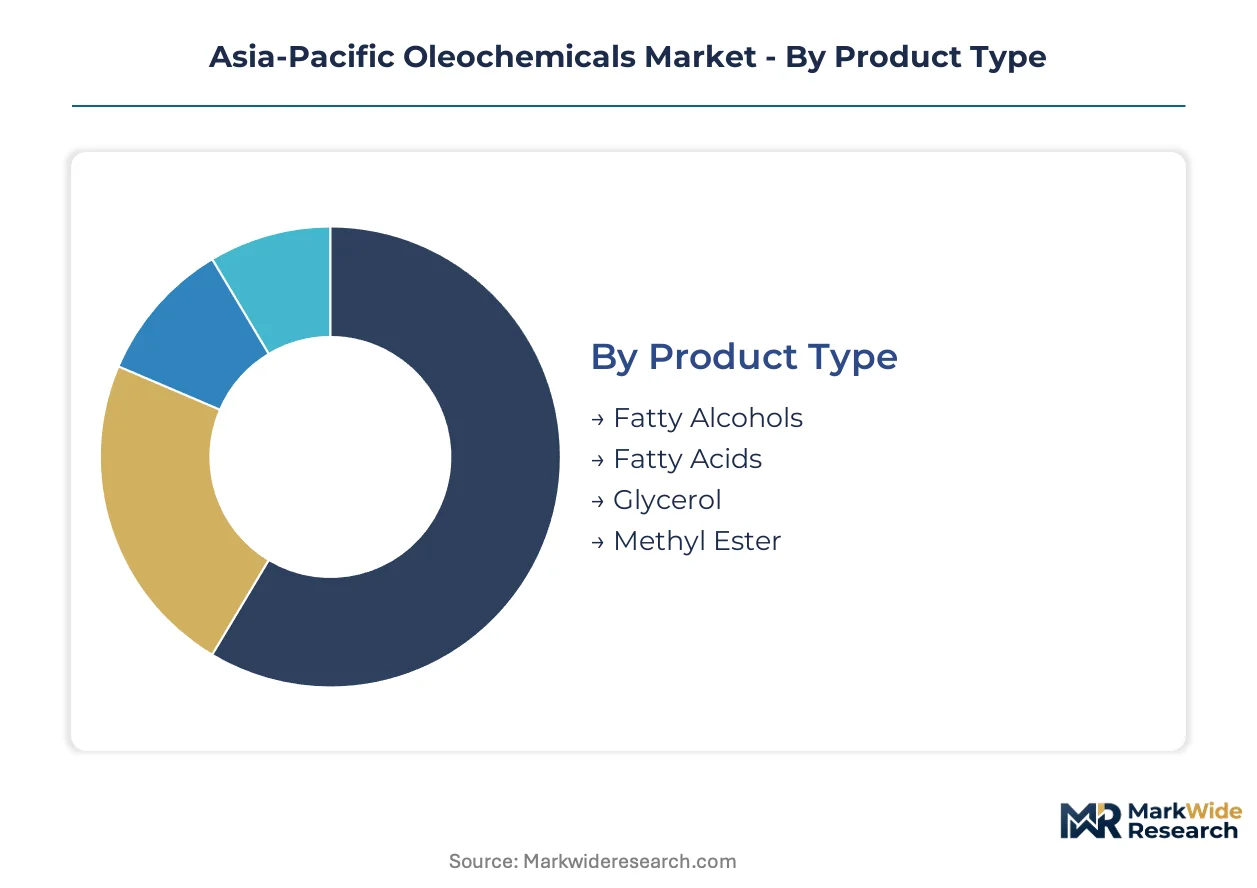
Segmentation reveals how oleochemical value pools split across specification tiers, with fatty alcohols commanding premium positioning in personal care while commodity fatty acids anchor volume flows. Understanding these fault lines exposes where integrated producers capture margin versus where distributors intermediate fragmented demand.
Product Type:
Production assets cluster in Malaysian and Indonesian integrated complexes, with hydrogenation capacity and fractionation trains determining which molecular cuts each producer dominates.
- Fatty Alcohols:C12-C18 chain lengths produced via high-pressure hydrogenation of methyl esters or fatty acids. Demand concentrates in Thai and Philippine personal care manufacturing hubs as formulators shift ethoxylated surfactant sourcing toward MSPO-certified supply chains.
- Fatty Acids:Split via hydrolysis of palm kernel and coconut oils into saturated C8-C18 fractions. Indonesian oleochemical complexes capture downstream margin through Ministry of Industry processing mandates that retain CPO for domestic fatty acid production rather than raw export.
- Glycerol:Biodiesel co-product refined to USP or food-grade specifications. Supply tightens when Indonesian biofuel mandates spike, redirecting crude glycerol away from oleochemical refiners.
- Methyl Ester:Transesterification intermediates for fatty alcohol production and biodiesel blending. Enzymatic process routes gain capital allocation for energy-intensity reduction.
Today's leader: Fatty Acids. Tomorrow's challenger: Fatty Alcohols.
End User:
Customer procurement patterns diverge sharply, with multinational personal care brands consolidating direct supplier relationships while food and pharmaceutical buyers enforce certification barriers that fragment vendor qualification.
- Personal Care:Multinational formulators in Thailand, Philippines, and Vietnam consolidate supplier rosters toward integrated Malaysian producers with locked-in MSPO documentation. Ethoxylated surfactant specifications tighten aquatic toxicity thresholds.
- Pharmaceuticals:China's SAMR enforces GB standards for glycerol purity that filter regional producers. USP-grade fatty acid esters command premium positioning through GMP-compliant infrastructure requirements.
- Food & Beverage:Emulsifier and coating applications drive food-grade glycerol and fatty acid ester demand. Refining asset upgrades separate qualified suppliers from commodity players.
- Animal Feed:Glycerol as energy-dense caloric additive and methyl ester byproducts for rumen bypass fats. Price sensitivity favors lower-specification refined tiers.
Personal Care absorbs the steepest expansion trajectory. Pharmaceuticals erect the highest entry barriers.
Application:
Functional performance requirements stratify pricing, with surfactant specifications tightening fastest as aquatic toxicity regulations propagate across ASEAN personal care markets.
- Surfactants:Ethoxylated fatty alcohols displace petrochemical alternatives in shampoo and detergent formulations. Malaysian producers with captive upstream supply secure preferred supplier status.
- Emulsifiers:Fatty acid esters and glycerol derivatives stabilize food and cosmetic formulations. Pharmaceutical-grade specifications reward stainless steel refining trains.
- Lubricants:Methyl ester and fatty acid base stocks for biodegradable metalworking and hydraulic fluids. Industrial buyers prioritize oxidative stability metrics.
- Cleaners:Fatty acid soaps and alcohol ethoxylates for household and institutional applications. Cost competition favors large-scale Malaysian production complexes.
Surfactants claim volume leadership. Emulsifiers capture margin concentration.
Distribution Channel:
Channel structure inverts with customer scale, as multinational formulators bypass distributors while mid-tier buyers fragment procurement across specialty chemical traders.
- Direct Sales:Integrated Indonesian and Malaysian producers contract directly with multinational personal care brands for specification-grade fatty alcohols with batch-level certification traceability.
- Distributors:Regional specialty chemical traders serve fragmented Vietnamese and Philippine mid-tier formulators lacking volume to justify direct supplier contracts.
- Online:Emerging procurement channel for standard-grade glycerol and commodity fatty acids among small compounders and regional traders.
- Retail:Limited to packaged glycerol and fatty acid derivatives for artisanal soap makers and small food processors.
Direct Sales consolidates share fastest. Distributors defend relevance in mid-tier fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia and Indonesia diverge in regulatory approach even as both anchor Asia-Pacific oleochemical production, with Kuala Lumpur emphasizing MSPO certification for export access while Jakarta prioritizes downstream processing retention through domestic refining mandates.
Indonesia
Personal care formulators in Jakarta and Surabaya drive fatty alcohol consumption as multinational brands localize ethoxylated surfactant production. The Ministry of Industry enforces downstream processing mandates that redirect crude palm oil toward domestic fatty acid and methyl ester output. Integrated oleochemical complexes cluster in North Sumatra and Riau provinces near plantation feedstock origins.
Malaysia
Peninsular Malaysian producers capture premium positioning through locked-in MSPO documentation serving European and North American personal care buyers. The Department of Standards mandates sustainable palm certification thresholds that filter export market access. Port Klang and Pasir Gudang industrial zones concentrate hydrogenation capacity for C12-C18 fatty alcohol production.
Thailand
Bangkok-based personal care manufacturers consolidate supplier rosters toward direct contracts with integrated Malaysian producers. The Thai Industrial Standards Institute enforces TISI labeling requirements for biodegradable surfactant content in consumer detergents. Eastern Economic Corridor chemical parks attract fatty acid distributors establishing technical service capabilities for mid-tier formulators.
Philippines
Manila and Cebu personal care hubs fragment procurement across regional specialty distributors lacking volume for direct supplier contracts. The Food and Drug Administration implements cosmetic ingredient disclosure rules that tighten documentation requirements for plant-derived surfactants. Batangas industrial zones host compounders importing specification-grade fatty alcohols with batch-level certification traceability.
Vietnam
Ho Chi Minh City and Hanoi personal care manufacturing bases remain underpenetrated by integrated oleochemical producers with captive upstream supply. The Ministry of Science and Technology enforces QCVN standards for chemical purity that create qualification barriers for cross-border ingredient sales. Binh Duong province industrial parks attract first-mover fatty acid distributors establishing local technical service networks.
Asia-Pacific Oleochemicals Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia-Pacific oleochemicals, with plantation-integrated groups commanding feedstock cost advantages while specialty chemical houses capture premium positioning in pharmaceutical-grade tiers. The vendor base stratifies between scale-driven commodity producers and specification-focused derivative manufacturers. Three archetypes dominate: upstream-integrated plantation conglomerates, midstream hydrogenation specialists, and downstream formulation ingredient houses. Capacity expansion and backward integration into captive feedstock supply represent the dominant competitive moves as margin pools concentrate in certified sustainable tiers.
Within the plantation-integrated tier, Wilmar International Ltd and KLK OLEO exemplify upstream control strategies that sustain cost leadership across fatty acid supply chains. IOI Corporation Berhad anchors specialty positioning through glycerol and ester derivative focus. These three entities represent divergent pathways—diversified agribusiness scale, Malaysian production concentration, and premium pharmaceutical-grade specialization—illustrating how feedstock access and specification tier selection determine competitive positioning.
| Leading Market Players |
|---|
| Wilmar International Ltd |
| Emery Oleochemicals |
| KLK OLEO |
| IOI Corporation Berhad |
| Musim Mas |
| Ecogreen Oleochemicals |
| Kao Corporation |
| Croda International Plc |
| Sinarmas Cepsa Pte. Ltd. |
| Others |
Value Network & Pricing Analysis
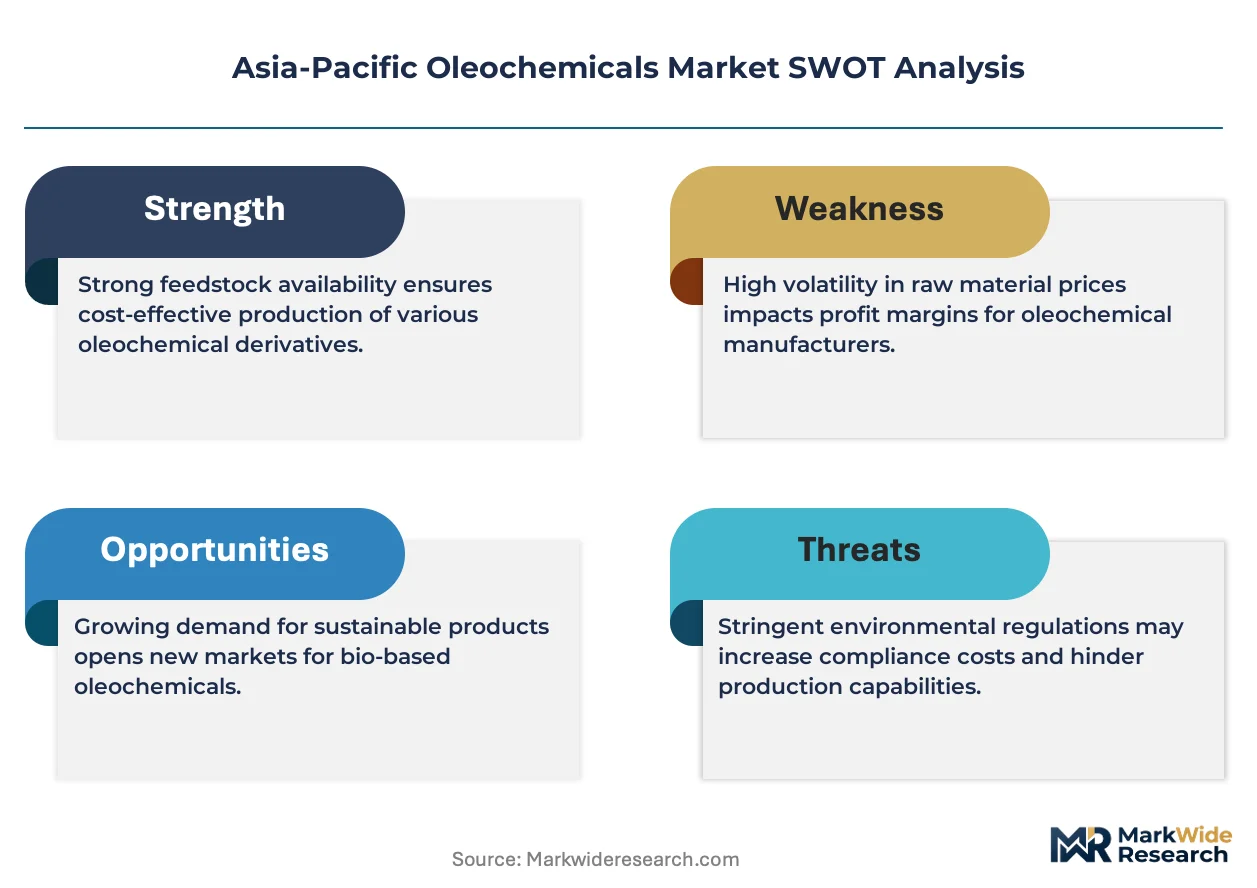
Crude palm oil cost fluctuations cascade through fatty acid pricing tiers as Malaysian integrated producers leverage captive plantation supply to undercut non-integrated competitors in spot market transactions. Indonesian downstream processing mandates redirect feedstock toward domestic refining, compressing export availability and amplifying price volatility for regional buyers lacking long-term offtake contracts.
Pricing Analysis
Capacity additions in Malaysia are reshaping price floors for C12-C18 fatty alcohols as hydrogenation trains commission near Port Klang. Three-tier pricing structure across MSPO-certified premium, standard industrial-grade, and economy biodiesel-co-product tiers separates qualified suppliers from commodity traders. Cost compression in pharmaceutical-grade glycerol is intensifying because stainless steel refining infrastructure extends payback periods versus commodity grades. Animal feed compounders exhibit highest price sensitivity, while multinational personal care brands prioritize certification reliability over spot discounts.
Supply Chain Analysis
Direct-to-brand channels handle multinational formulator demand for specification-grade fatty alcohols with batch-level MSPO traceability. Feedstock supply concentrates in Indonesia and Malaysia, with integrated complexes clustering in North Sumatra, Riau, and Peninsular Malaysian palm belts. Hydrogenation catalysts, high-pressure reactor vessels, and fractionation column capacity constitute critical equipment dependencies. Single-source vulnerability runs through Malaysian hydrogenation specialists serving Thai and Philippine personal care hubs. Distribution runs through specialty chemical traders for mid-tier Vietnamese and Philippine formulators lacking volume for direct supplier contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific oleochemicals function as a regulatory compounder where Malaysia's MSPO certification thresholds and Indonesia's downstream processing mandates are restructuring competitive access and margin distribution.
For Market Incumbents: Anticipate biodiesel policy fluctuations redirecting glycerol feedstock volumes by locking in multi-year plantation supply contracts and commissioning pharmaceutical-grade refining trains ahead of China's SAMR enforcement waves. Backward integration into captive upstream supply and GMP-compliant infrastructure investment represent defensive levers against specialty chemical houses capturing premium positioning. For New Entrants and Emerging Players: Enter via technical service capabilities in Vietnam's underpenetrated personal care manufacturing base, where Binh Duong province industrial parks lack integrated oleochemical producers with local specification support. First-mover positioning in fatty acid distribution for mid-tier formulators, combined with enzymatic transesterification technology partnerships, offers viable go-to-market angles against established Malaysian scale players. For Investors and Strategic Acquirers: Consolidation pressure builds where small and mid-tier producers face compliance cost escalation from divergent Indonesian and Malaysian sustainability certification platforms. Long-term viability favors acquisition targets with locked-in MSPO documentation and hydrogenation capacity serving ethoxylated surfactant demand. The signal to watch is enzymatic process route capital allocation displacing chemical catalyst systems in new methyl ester capacity builds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive crude palm oil supply insulates Malaysian producers from feedstock volatility compressing non-integrated margins. |
| Pharmaceutical-Grade Refining Asset Upgrades | Stainless steel GMP infrastructure qualifies producers for China's SAMR-enforced glycerol purity thresholds. |
| Enzymatic Transesterification Technology Adoption | Lower-temperature processing cuts energy intensity and attracts Japanese and South Korean personal care procurement tenders. |
| Direct Sales Channel Expansion | Bypassing regional distributors captures multinational formulator demand for locked-in MSPO certification traceability. |
| Vietnam Technical Service Network Buildout | First-mover positioning in underpenetrated personal care manufacturing clusters near Ho Chi Minh City industrial parks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oleochemical plant managers, procurement leads at Thai and Philippine personal care manufacturers, Malaysian distribution channel partners, and technical R&D directors at hydrogenation specialists with secondary validation through customs and trade data, Malaysian Department of Standards MSPO certification records, Indonesian Ministry of Industry downstream processing mandate filings, and SEC 10-K disclosures from plantation-integrated conglomerates. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Segment-weighting across product type, end user, application, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs were derived from regression analysis of historical production capacity commissioning timelines against personal care formulation shift patterns. Key inputs included biodiesel policy fluctuation scenarios, hydrogenation catalyst yield ceilings, and MSPO certification penetration rates by export destination.
Inputs from plantation-integrated producers and specialty chemical distributors were available through the study window; gaps in small and mid-tier producer cost structure data introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions regarding sustained personal care brand reformulation toward plant-derived surfactants and continued divergence between Indonesian and Malaysian sustainability frameworks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Glycerine Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Petrolatum Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Butyl Stearate Market
Oleochemicals
Glycerol Monostearate Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Oleophilic Materials Market