
 Fatty Acid Ester Market | 2026-2036
Fatty Acid Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Acid Ester Market Analysis
Modular formulation kits are rebalancing how personal care buyers source fatty acid esters, shifting from single-ingredient orders to bundled emollient systems. BASF SE leverages its integrated oleochemicals platform to supply pre-blended ester modules for cosmetics R&D labs. Kao Corporation anchors its regional procurement through captive supply networks across Southeast Asian palm processing hubs. Wilmar International Limited competes on upstream control over vegetable oil refining, extending cost advantages into specialty ester derivatives.
Fatty acid esters comprise glycerol or polyol esters of saturated and unsaturated fatty acids, typically synthesized through esterification or transesterification at temperatures between 150°C and 250°C with acid or base catalysis; these compounds function as surfactants, emulsifiers, lubricants, and plasticizers across industrial and consumer applications. Vegetable oil-derived triesters dominate volume production due to abundant palm and soybean feedstock availability, while synthetic-source polyesters command premium positioning in pharmaceutical-grade applications where batch consistency exceeds natural variability limits. Food additive monoesters sustain mature demand from processed food manufacturers seeking emulsification stability, whereas biofuel diesters represent the fastest-expanding application segment as renewable diesel specifications tighten cetane requirements.
REACH registration through ECHA mandates full toxicological dossiers for ester imports into Europe, elevating compliance costs for smaller traders while favoring producers with dedicated regulatory affairs capacity. FDA food-contact substance notifications and EPA biofuel pathway approvals in the US create dual-track certification requirements for suppliers serving both nutrition and energy end markets. Stakeholders must monitor evolving biogenic carbon accounting rules under EU Green Deal implementation, as these frameworks will determine which feedstock origins qualify for preferential procurement by multinational formulators.
Market Dynamics
Modular formulation kits are restructuring procurement patterns across personal care and industrial segments, compressing traditional single-ingredient sourcing into bundled emollient systems that demand integrated supply capabilities from ester producers.
Growth Catalysts
- EU Green Deal biogenic carbon rules:Preferential procurement frameworks are redirecting multinational formulators toward feedstock origins with verified sustainability credentials, accelerating demand for certified palm-derived esters.
- Personal care R&D labs:Pre-blended ester modules are reducing formulation cycle times, with cosmetics manufacturers consolidating supplier relationships around integrated oleochemical platforms.
- Indonesia-Malaysia palm clusters:Integrated refining and esterification infrastructure is capturing downstream margin expansion as regional processing capacity concentrates in Southeast Asian hubs.
Market Restraints
- Crude palm oil price volatility:Feedstock cost swings compress margin predictability for non-integrated ester producers lacking captive refining assets.
- REACH toxicological dossier requirements:ECHA registration costs create asymmetric compliance burdens that favor large producers with dedicated regulatory affairs capacity over smaller traders.
- Petrochemical-based synthetic esters:Batch-consistent polyesters retain premium positioning in pharmaceutical applications where natural variability limits disqualify vegetable-derived alternatives.
Strategic Opportunities
- Renewable diesel cetane specifications:Biofuel diesters represent an underpenetrated volume channel as EPA pathway approvals tighten fuel quality mandates.
- Modular emollient kit distribution:Direct-to-formulator digital platforms are disintermediating traditional chemical distributors in cosmetics procurement.
- FDA-EPA dual-track certification:Suppliers achieving concurrent food-contact and biofuel approvals capture cross-market sourcing contracts from diversified processors.
Industry Challenges
- Esterification catalyst optimization:Process engineering talent scarcity constrains yield improvements at temperatures between 150°C and 250°C.
- Batch-to-batch consistency certification:Pharmaceutical-grade validation timelines extend customer qualification periods, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Acid Ester Market |
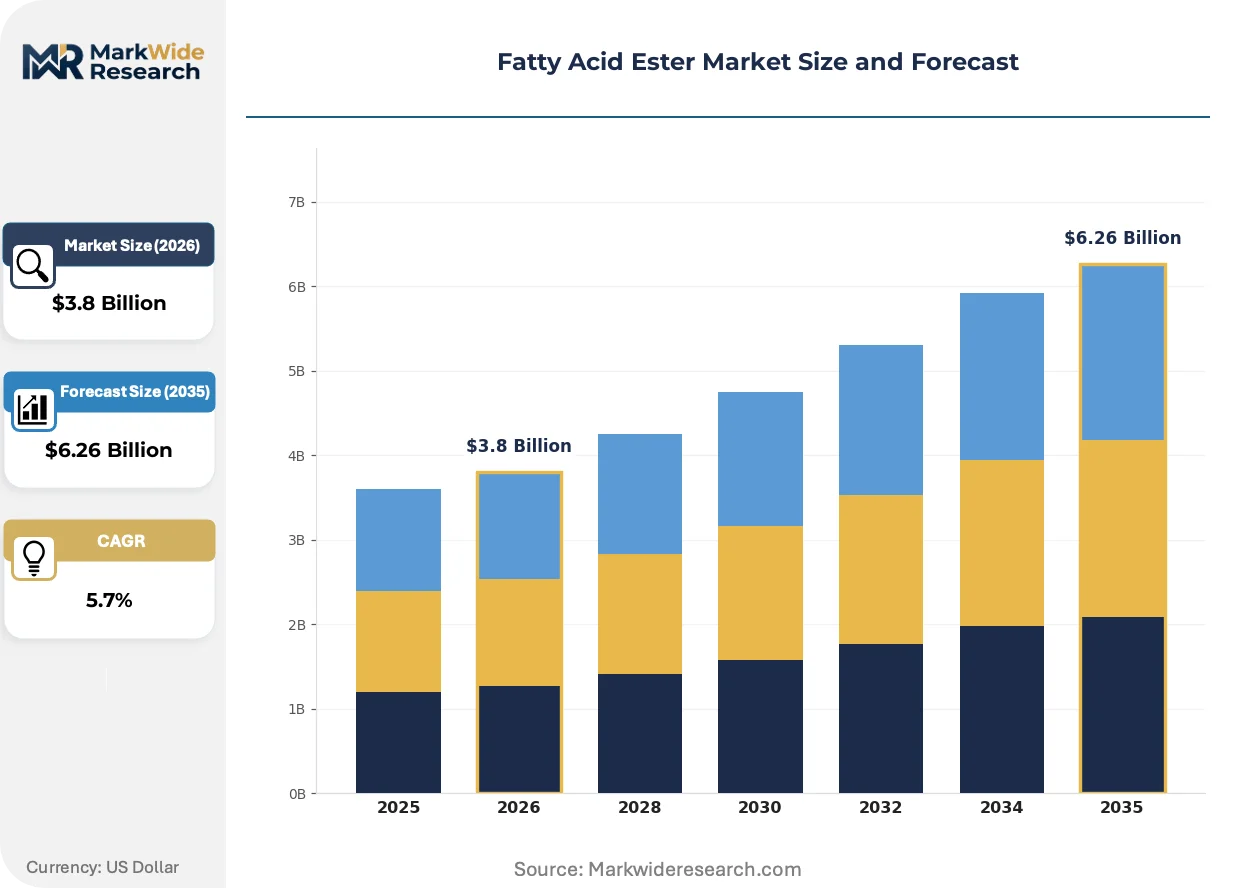
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoesters, Diesters, Triesters, Polyesters Application: Cosmetics, Food Additives, Biofuels, Pharmaceuticals End User: Food Industry, Personal Care, Automotive, Industrial Source: Vegetable Oils, Animal Fats, Synthetic, Others |
| Companies Covered | BASF SE, Evonik Industries AG, Wilmar International Limited, Kao Corporation, Croda International Plc, Cargill Incorporated, Kuala Lumpur Kepong Berhad, Avril Group, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Acid Ester Market Emerging Trajectories
Enzymatic esterification processes are displacing traditional acid-base catalysis, altering capital deployment patterns and yield economics across vegetable oil derivative production.
Enzymatic transesterification using immobilized lipase biocatalysts operates at lower temperatures with reduced energy inputs compared to conventional thermal processes. Personal care formulators in Southeast Asia are adopting enzyme-derived esters for sensitive-skin applications where residual catalyst traces raise tolerability concerns. This technology is overtaking acid-catalyzed systems in premium emollient segments, compressing equipment amortization schedules for producers retrofitting existing reactor infrastructure.
REACH registration amendments through ECHA are expanding substance evaluation criteria for imported ester mixtures. Industrial consequence includes mandatory supply chain disclosure requirements that elevate documentation costs for traders sourcing from non-EU palm processing facilities. Specialty ester grades destined for pharmaceutical applications face the most intensive dossier scrutiny, prompting producers to segregate production lines by end-use certification tier.
Personal care brands are consolidating supplier panels around integrated emollient system providers rather than discrete fatty acid ester merchants. Cosmetics R&D procurement teams now specify pre-validated formulation modules that compress in-house compounding time. This pattern concentrates most visibly in Southeast Asian markets where regional palm derivative clusters enable same-week delivery of customized ester blends.
Fatty Acid Ester Market Segmentation
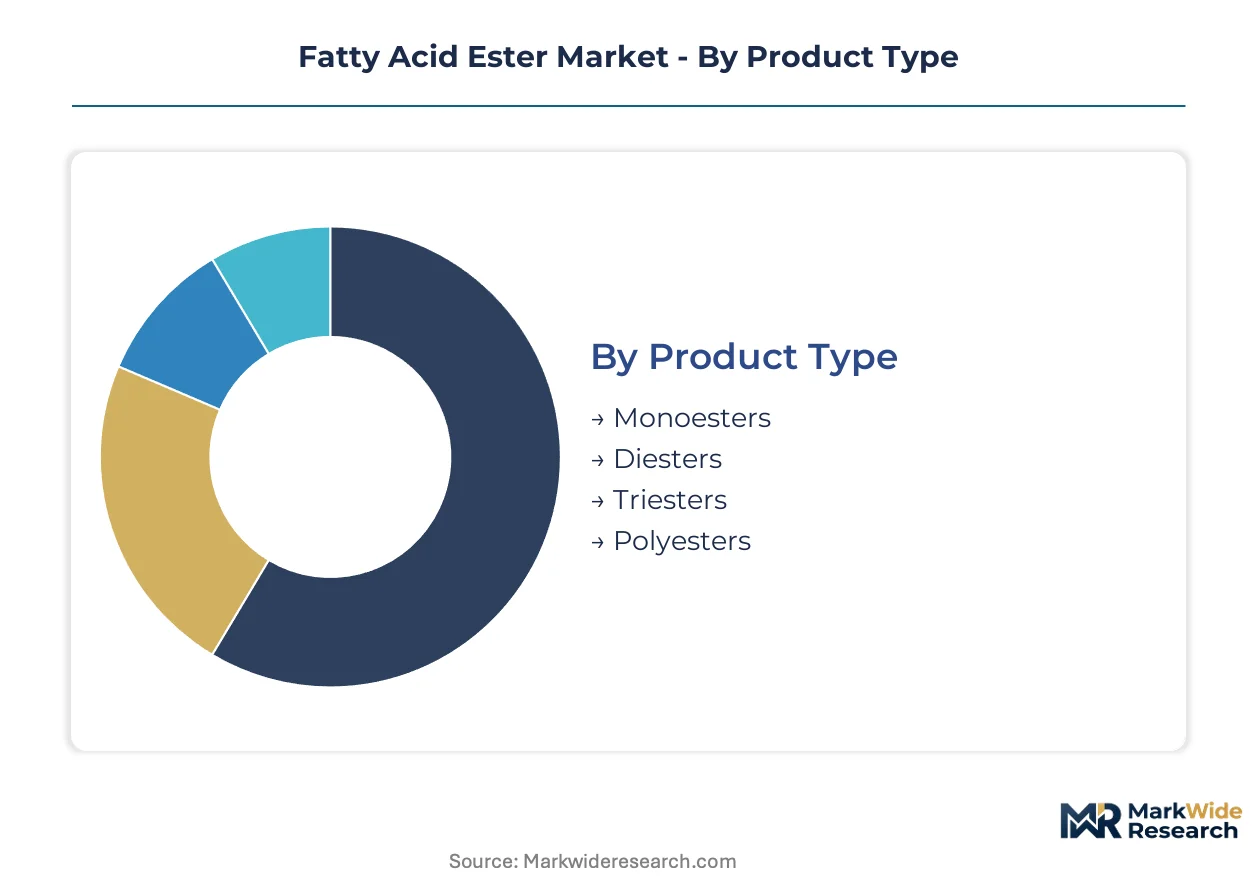
Fatty acid ester specifications determine downstream compatibility across incompatible end-use requirements. Pharmaceutical-grade batches demand synthetic consistency that vegetable-derived alternatives cannot match. Segmentation clarity enables suppliers to align production lines with certification tiers rather than commodity positioning.
Product Type:
Carbon chain saturation and esterification degree define functional performance across lubrication, emulsification, and solubility applications.
- Monoesters:Single fatty acid chains bonded to glycerol or polyol backbones deliver superior emulsification stability. Food additive manufacturers in Southeast Asia specify monoesters for processed dairy applications where EFSA emulsifier codes mandate purity documentation.
- Diesters:Dual-ester configurations balance viscosity reduction with oxidative stability. Biofuel blenders in the US target diesters for renewable diesel formulations as EPA cetane pathway approvals tighten fuel quality specifications.
- Triesters:Triglyceride-derived structures dominate volume production through palm and soybean feedstock abundance. Cost positioning tracks crude vegetable oil futures with limited margin insulation for non-integrated producers.
- Polyesters:Multi-functional ester networks command premium positioning in pharmaceutical-grade applications. Batch consistency requirements under FDA drug master file protocols disqualify natural variability sources.
Mature deployment sits with triesters. Newer deployment is concentrated in diesters.
Application:
End-use certification requirements fragment supply capabilities across incompatible regulatory pathways.
- Cosmetics:Emollient-grade esters for skincare formulations demand REACH-compliant toxicological dossiers. Personal care R&D labs in Indonesia and Malaysia are consolidating procurement around pre-blended modular systems from integrated oleochemical platforms.
- Food Additives:Monoester emulsifiers sustain mature demand from processed food manufacturers. FDA food-contact substance notifications create documentation burdens that favor suppliers with dedicated regulatory affairs capacity.
- Biofuels:Diester configurations for renewable diesel represent the application segment climbing the fastest. EPA pathway approvals and EU Green Deal biogenic carbon accounting rules are redirecting feedstock sourcing toward certified sustainable palm origins.
- Pharmaceuticals:Synthetic-source polyesters dominate where batch-to-batch consistency exceeds natural variability limits. EMA quality documentation extends customer qualification timelines.
Volume concentration rests with food additives. Steepest expansion trajectory belongs to biofuels.
End User:
Customer procurement patterns diverge between specification-driven industries and cost-sensitive commodity buyers.
- Food Industry:Processed food manufacturers specify emulsifier stability under FSSAI and FDA parallel compliance frameworks. Monoester procurement concentrates among multinational formulators with pan-regional sourcing contracts.
- Personal Care:Cosmetics manufacturers are shifting from single-ingredient orders to bundled emollient systems. Southeast Asian brands specify same-week delivery capabilities from regional palm derivative clusters.
- Automotive:Renewable diesel blenders drive diester demand as cetane specifications tighten. US and European fuel quality mandates are diverging on biogenic carbon verification requirements.
- Industrial:Lubricant and plasticizer applications prioritize cost positioning over certification tier. Synthetic polyesters retain share where performance specifications tolerate petrochemical sourcing.
Procurement maturity clusters in food industry accounts. Personal care buyers are restructuring sourcing fastest.
Source:
Feedstock origin determines regulatory qualification under emerging sustainability frameworks.
- Vegetable Oils:Palm and soybean triesters dominate volume production through integrated refining infrastructure in Indonesia and Malaysia. EU Green Deal biogenic carbon rules are elevating documentation requirements for non-certified origins.
- Animal Fats:Tallow-derived esters serve niche lubricant applications with limited cosmetics penetration due to consumer preference shifts. Regulatory acceptance varies across EFSA and FDA jurisdiction boundaries.
- Synthetic:Petrochemical-based polyesters command pharmaceutical-grade positioning where batch consistency protocols apply. Premium pricing reflects capital-intensive production rather than feedstock scarcity.
- Others:Algae and microbial fermentation sources remain pre-commercial despite pilot-scale trials. Yield economics at scale have not displaced established vegetable oil pathways.
Established supply anchors in vegetable oils. Alternative sourcing experiments concentrate in others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia concentrate upstream fatty acid ester production through integrated palm oil refining clusters, while demand dispersion stretches across formulation centers in Germany, the United States, and Japan where cosmetics and pharmaceutical manufacturers operate.
Indonesia
Personal care brands in Jakarta and Surabaya are expanding procurement of emollient-grade esters for skincare formulations. The national government enforces sustainability certification requirements for palm derivative exports under EU Green Deal alignment pressures. Integrated refining and esterification infrastructure in North Sumatra captures downstream margin expansion as regional processing capacity concentrates.
Malaysia
Kuala Lumpur Kepong Berhad anchors captive supply networks across Southeast Asian palm processing hubs. ECHA REACH compliance mandates full toxicological dossiers for ester imports into Europe, elevating documentation burdens for Malaysian exporters. The Port Klang corridor hosts specialty ester derivative production facilities serving multinational cosmetics formulators.
Germany
BASF SE leverages its integrated oleochemicals platform to supply pre-blended ester modules for cosmetics R&D labs across Europe. ECHA registration amendments expand substance evaluation criteria for imported ester mixtures, intensifying scrutiny of supply chain disclosures. The Ludwigshafen chemical complex maintains pharmaceutical-grade polyester production where batch consistency protocols apply.
United States
Biofuel blenders drive diester demand as EPA cetane pathway approvals tighten renewable diesel specifications. FDA food-contact substance notifications create dual-track certification requirements for suppliers serving nutrition and energy end markets. Houston and Chicago metropolitan areas concentrate lubricant and plasticizer applications where synthetic polyesters retain industrial share.
Japan
Kao Corporation consolidates regional procurement through integrated supply relationships with Southeast Asian palm derivative clusters. METI standards govern industrial chemical purity thresholds for domestic manufacturing inputs. The Osaka-Kobe industrial zone maintains enzymatic esterification capacity for sensitive-skin cosmetic applications where residual catalyst tolerability concerns dominate formulation specifications.
Fatty Acid Ester Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated oleochemical platforms with captive feedstock control, regional palm derivative processors leveraging geographic proximity, and synthetic polyester specialists serving pharmaceutical-grade consistency requirements. Capacity expansion and regulatory certification stacking constitute the dominant competitive moves as producers seek cross-market approvals.
Within the integrated platform tier, BASF SE and Wilmar International Limited exemplify upstream control strategies that extend cost advantages into specialty derivatives. Kao Corporation occupies a position bridging Japanese formulation expertise with Southeast Asian supply integration. These three entities anchor divergent geographic and vertical positioning approaches without converging on identical capability sets.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Wilmar International Limited |
| Kao Corporation |
| Croda International Plc |
| Cargill Incorporated |
| Kuala Lumpur Kepong Berhad |
| Avril Group |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal biogenic carbon accounting rules gate qualified supply access and premium-tier pricing for fatty acid ester producers serving multinational formulators. Certification-compliant palm derivatives from Indonesia and Malaysia command price premiums over uncertified alternatives, while REACH dossier costs concentrate procurement relationships around integrated oleochemical platforms with dedicated regulatory affairs capacity.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade polyesters accelerates because synthetic-source batch consistency requirements disqualify natural variability alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FDA drug master file-certified grades from REACH-compliant industrial tiers and commodity triesters. Price differentiation rests on certification tier and vertical integration depth, with non-integrated traders facing margin compression from crude palm oil volatility. Personal care buyers exhibit lowest price sensitivity for enzymatic-derived emollients, while industrial lubricant purchasers prioritize cost positioning.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian palm oil refining clusters that feed integrated esterification infrastructure. Feedstock dependencies draw from crude palm oil, glycerol, and immobilized lipase biocatalysts. Supply chain risk centers on EU sustainability certification requirements that disqualify non-compliant origins from preferential procurement frameworks. Distribution runs through direct-to-formulator digital platforms disintermediating traditional chemical distributors in cosmetics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in fatty acid esters has become a vertical-integration race anchored in captive control over Southeast Asian palm processing assets. Players lacking upstream refining relationships face structural margin compression.
For Market Incumbents: Anchor defensive positioning through backward integration into North Sumatra and Port Klang refining clusters. BASF SE and Wilmar International Limited exemplify cost advantages from captive vegetable oil processing. Incumbents must invest in concurrent FDA-EPA dual-track certification to capture cross-market sourcing contracts from diversified processors. Enzymatic esterification capacity investments defend premium emollient segments against emerging biocatalyst specialists. For New Entrants and Emerging Players: Direct-to-formulator digital platforms offer the most penetrable route into cosmetics procurement relationships. New entrants should target modular emollient kit distribution to Southeast Asian personal care R&D labs seeking same-week delivery capabilities. White-space opportunities concentrate in biofuel diesters for renewable diesel blenders, where EPA pathway approvals create qualification barriers for established food-additive suppliers. Enzymatic process technology licensing from Japanese specialists enables premium positioning without capital-intensive reactor infrastructure. For Investors and Strategic Acquirers: REACH registration amendments expanding substance evaluation criteria are the leading indicator that regulatory affairs capacity will determine acquisition premiums. Long-term viability favors vertically integrated platforms with Southeast Asian palm cluster access over pure-play traders facing asymmetric compliance burdens. Target acquisition archetypes include Indonesian and Malaysian processors with existing ECHA dossier infrastructure. Watch for EPA biofuel pathway approval acceleration as the signal for diester segment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Refining | Captive feedstock control insulates margin from crude vegetable oil volatility in Indonesia-Malaysia clusters. |
| Enzymatic Esterification Capacity Buildout | Lower-temperature biocatalyst processes capture premium positioning in sensitive-skin cosmetic applications. |
| REACH-FDA Dual-Track Certification | Concurrent regulatory approvals enable cross-market contracts from food and biofuel processors. |
| Direct-to-Formulator Digital Platform | Disintermediation of chemical distributors compresses procurement cycle times for cosmetics R&D labs. |
| Long-term Supply Agreement with Renewable Diesel Blenders | EPA cetane pathway approvals lock in diester volume commitments ahead of competitor qualification. |
Methodological Framework
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone for supply-side capacity and regulatory compliance mapping. Primary interviews with oleochemical plant managers, cosmetics procurement leads, biofuel blenders, and distribution channel partners validated production cost structures and demand patterns. Bottom-up triangulation across producer capacity data and top-down reconciliation against end-use consumption estimates anchored volume and value outputs.
Bottom-up modeling tracked fatty acid ester production by grade tier, end-use industry, and regional processing hub across the analysis window. Segmentation dimensions included product type, application, and feedstock origin with pharmaceutical-grade consistency protocols modeled separately from commodity triesters. CAGRs were derived from regression analysis of historical capacity expansion rates against regulatory-driven demand inflection points. Crude palm oil futures curves and enzymatic process yield improvements served as industry-specific forecast inputs.
The model holds under sustained EU Green Deal implementation and EPA biofuel pathway approval timelines; deviation in sustainability certification recognition or renewable diesel policy would shift demand trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Palm Wax Market
Oleochemicals
Estolides Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Oleyl Alcohol Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
2-tert-Butylcyclohexanol Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
2-Ethylhexyl Acetate Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Triethyl Citrate Market