
 Camphor Oil Market | 2026-2036
Camphor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Camphor Oil Market Outlook
Multi-source procurement from Cinnamomum camphora growers across Southeast Asia is recalibrating supply security for European fragrance houses. Albert Vieille leverages long-term distillation partnerships in Indonesia to secure consistent cineole-rich fractions. Robertet Group anchors its competitive position through backward integration into plantation management in Madagascar. Treatt Plc differentiates via specialty fractionation capabilities that isolate high-purity camphor crystals for pharmaceutical-grade applications.
Camphor oil is a volatile essential oil distilled from the wood, roots, and leaves of Cinnamomum camphora trees, typically containing 30-50% camphor along with cineole, safrole, and terpineol fractions depending on botanical origin and distillation method. Its primary commercial purpose spans topical therapeutic formulations, fragrance compounding, and flavoring applications where controlled volatility and characteristic aromatic profile deliver functional value. Natural camphor oil occupies the premium tier in fragrance applications, while synthetic variants supply volume-driven pharmaceutical and cleaning product segments. The topical analgesics application commands concentrated margin pools due to stringent pharmacopeial compliance requirements, whereas fragrance applications sustain broader volume throughput across cosmetics and personal care channels.
India's BIS and CDSCO enforce purity thresholds for camphor oil used in pharmaceutical preparations, while China's NMPA and GB standards govern essential oil imports for domestic formulation. REACH registration requirements in Europe constrain market access for unregistered Asian distillers, redirecting trade flows toward compliant intermediaries. Stakeholders must monitor evolving botanical sourcing sustainability certifications and synthetic biology alternatives that could restructure feedstock economics.
Market Dynamics
Pharmaceutical formulators in India and China are tightening purity specifications for natural-grade camphor oil, compressing margins for Southeast Asian distillers while concentrating procurement power among backward-integrated fragrance houses with captive plantation access.
Growth Catalysts
- India's BIS quality mandates:Tightened purity thresholds for topical analgesic production are filtering out low-grade suppliers and consolidating procurement among certified distillers.
- East Asian manufacturing clusters:Co-location of downstream fragrance and API facilities with refining operations in Jiangsu Province and Gujarat State is reducing logistics costs and batch-to-batch variability.
- Biomass fractionation advances:Continuous steam distillation methods are improving cineole recovery rates from Cinnamomum camphora feedstock, expanding yields for pharmaceutical-grade applications.
Market Restraints
- Raw material concentration:Over 70% of Cinnamomum camphora biomass originates from Indonesian and Chinese plantations, creating weather-dependent supply volatility.
- REACH registration barriers:European chemical compliance requirements block direct market access for unregistered Asian distillers, forcing reliance on costly intermediary traders.
- Synthetic camphor substitution:Petroleum-derived camphor crystals from Chinese chemical manufacturers undercut natural oil pricing in volume-driven cleaning product segments.
Strategic Opportunities
- Madagascar plantation backward integration:Fragrance houses securing direct tree-to-bottle control can bypass volatile spot markets for cineole-rich fractions.
- Sustainability certification premiums:FairWild and organic botanical sourcing standards are opening price-tier separation in European cosmetics channels.
- Specialty fractionation services:Isolating high-purity camphor crystals for pharmacopeial compliance represents an underserved technical service niche.
Industry Challenges
- Skilled distillation operator scarcity:Traditional knowledge of fractional separation techniques for safrole and terpineol control is aging out in Indonesian and Chinese processing facilities.
- Batch-to-batch standardization:Natural variation in botanical origin oil composition complicates pharmaceutical customers' validation protocols for topical formulation stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camphor Oil Market |
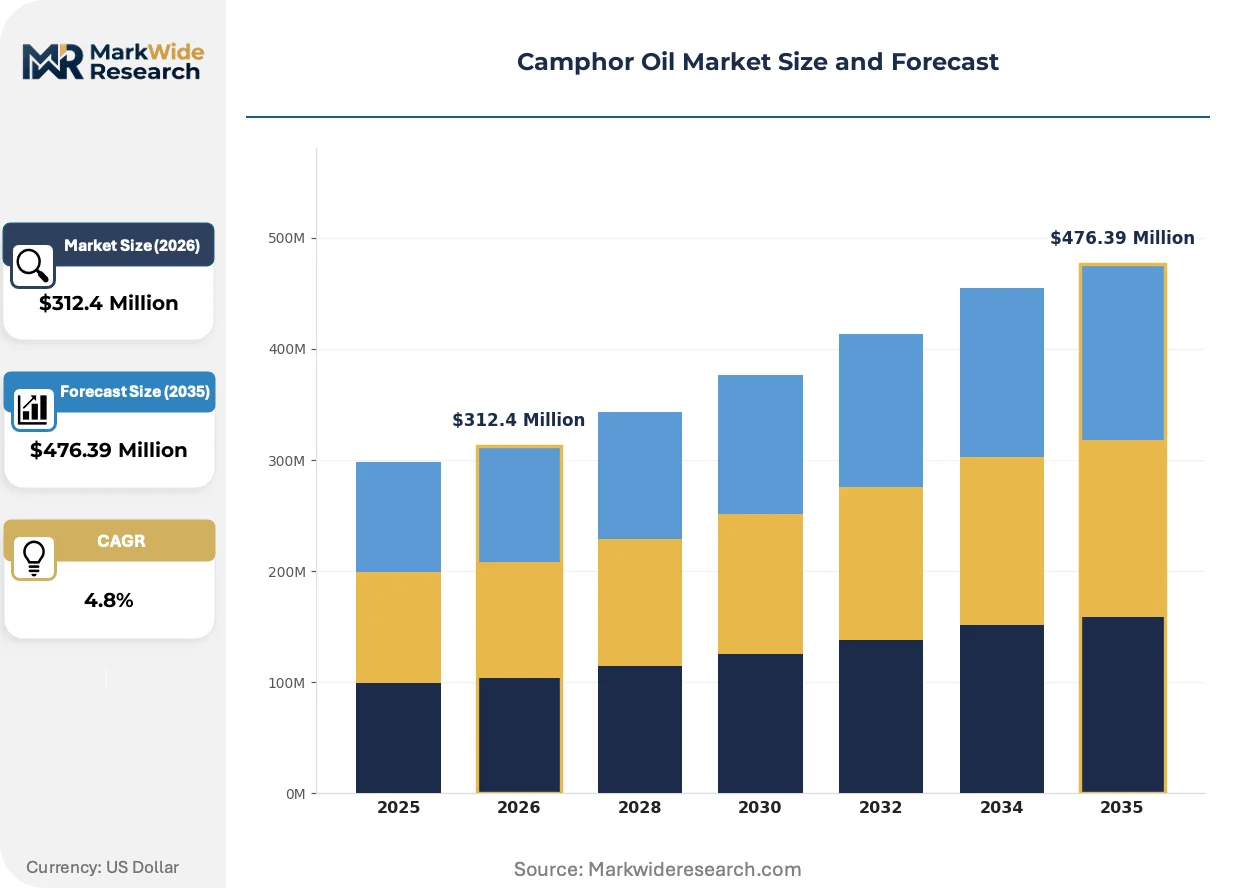
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Medicinal, Aromatherapy End Use: Pharmaceuticals, Cosmetics, Food & Beverage, Cleaning Products Application: Topical Analgesics, Antiseptics, Flavoring Agents, Fragrance Distribution Channel: Online Stores, Retail, Pharmacies, Wholesale |
| Companies Covered | Albert Vieille, Berje, Elixens, Robertet Group, Fleurchem, Ultra International, Treatt Plc, Ernesto Ventos, Penta Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camphor Oil Market Strategic Shifts
Steam distillation automation and blockchain-based provenance tracking are reshaping how fragrance houses verify botanical origin while pharmaceutical buyers demand ever-tighter compositional specifications.
Supercritical CO2 extraction technology is decentralizing camphor oil production from traditional steam-distillation strongholds. Mid-sized processors in Vietnam and Madagascar are adopting modular extraction units that operate at lower temperatures, preserving heat-sensitive terpenoid fractions for premium fragrance applications. This distributed processing model is compressing the historical dominance of large-scale Indonesian distillers.
China's GB standards for essential oil imports are tightening cineole and safrole content specifications for pharmaceutical-grade applications. Domestic formulators must now submit third-party chromatographic analysis with each shipment, raising documentation burdens for Southeast Asian exporters. Indian API manufacturers are responding by establishing in-house testing capabilities rather than relying on supplier certificates.
Direct contracting between fragrance houses and plantation cooperatives is displacing traditional commodity trading channels. European cosmetics brands now require chain-of-custody documentation from specific Cinnamomum camphora growing regions, bypassing spot-market intermediaries entirely. This specification-driven sourcing is most visible in French and German personal care formulation, where provenance claims command shelf-price premiums.
Camphor Oil Market Segmentation
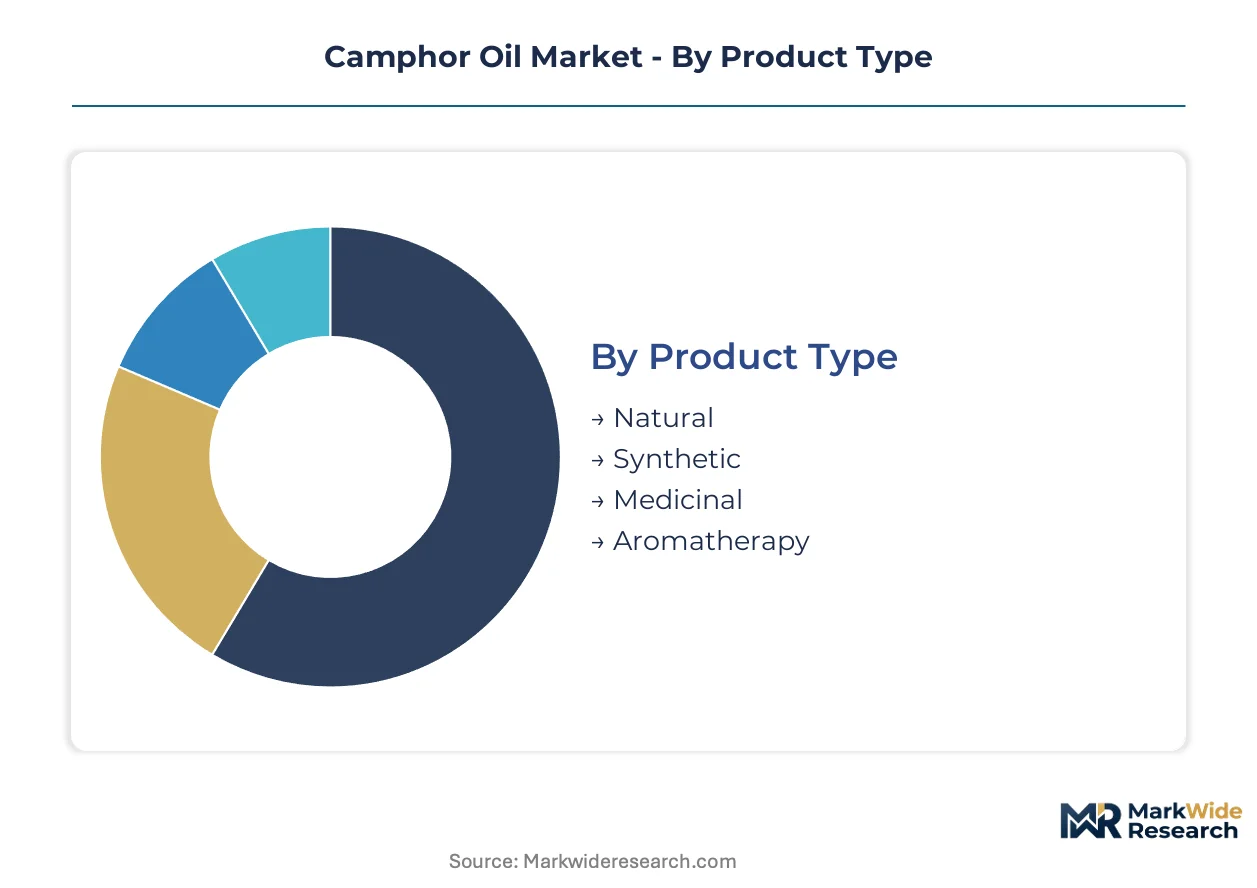
Segmentation in the camphor oil market separates premium botanical grades from commodity synthetics, with purity thresholds determining access to pharmaceutical versus cleaning product channels. Distinct supply chains serve fragrance houses requiring cineole-rich fractions versus formulators demanding pharmacopeial compliance.
Product Type:
Supply concentration for Cinnamomum camphora biomass in Indonesian and Chinese plantations directly shapes product tier availability and pricing volatility across natural and synthetic categories.
- Natural:Steam-distilled from Cinnamomum camphora wood and leaf biomass, containing 30-50% camphor with variable cineole, safrole, and terpineol fractions. Pharmaceutical formulators in Jiangsu Province and Gujarat State concentrate procurement here for topical analgesic production under tightening BIS and GB purity mandates.
- Synthetic:Petroleum-derived camphor crystals manufactured through chemical synthesis, offering batch-to-batch consistency at lower unit cost. Chinese chemical producers dominate volume supply for cleaning product segments where natural provenance carries no price premium.
- Medicinal:Pharmacopeial-grade material meeting USP, BP, or IP specifications for therapeutic applications.
- Aromatherapy:Lower-concentration formulations for wellness and home fragrance diffusion.
Today's leader: Natural. Tomorrow's challenger: Synthetic.
End Use:
Cost tier separation between pharmaceutical compliance investments and commodity volume throughput defines competitive positioning across end-use segments.
- Pharmaceuticals:Topical analgesic and antiseptic formulations requiring validated stability protocols and third-party chromatographic documentation. India's CDSCO and China's NMPA enforcement of purity thresholds is filtering supplier bases toward certified distillers with captive plantation access.
- Cosmetics:Fragrance compounding for personal care where provenance claims command shelf-price premiums in French and German formulation channels.
- Food & Beverage:Flavoring applications with FSSAI and FDA food-grade compliance requirements.
- Cleaning Products:Volume-driven segments where synthetic camphor undercuts natural oil pricing.
Pharmaceuticals anchors margin pools. Cosmetics climbs the fastest on sustainability certification premiums.
Application:
Application-level demand varies by volatility control requirements and regulatory documentation burdens across therapeutic and sensory use cases.
- Topical Analgesics:Concentrated margin pools due to pharmacopeial compliance requirements and batch validation protocols. Formulators in East Asian manufacturing clusters co-locate with refining operations to reduce variability.
- Antiseptics:Hospital and consumer disinfectant applications with institutional procurement standards.
- Flavoring Agents:Controlled volatility requirements for food and beverage integration.
- Fragrance:Broader volume throughput across cosmetics channels where natural camphor oil occupies premium positioning.
Topical Analgesics defends premium positioning. Fragrance expands addressable volume.
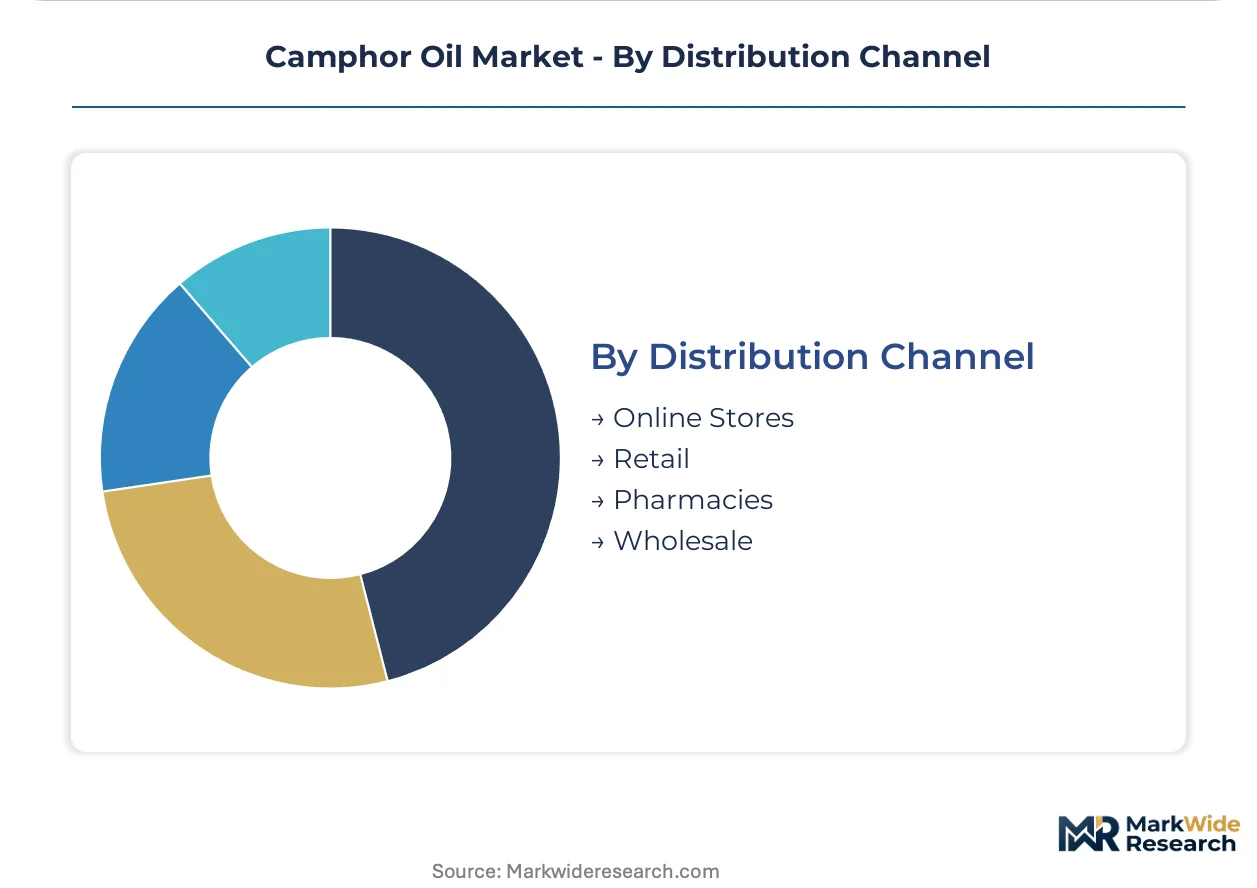
Distribution Channel:
Customer type separation between specification-driven direct contracting and spot-market intermediation is restructuring traditional trading channels.
- Online Stores:Direct-to-consumer aromatherapy and wellness product sales with chain-of-custody documentation requirements.
- Retail:Mass-market personal care and cleaning product distribution.
- Pharmacies:Regulated therapeutic product dispensing with CDSCO and NMPA oversight.
- Wholesale:Bulk supply to fragrance houses and API manufacturers, where European cosmetics brands now require specific regional provenance documentation bypassing spot-market intermediaries entirely.
Wholesale retains volume dominance. Online Stores gains share fastest on provenance transparency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu Province anchors pharmaceutical-grade camphor oil demand through its concentration of topical analgesic manufacturers serving domestic and export markets. India's Gujarat State and Indonesia's Sumatran processing clusters complete the triangular supply architecture for natural-grade distillation.
China
Jiangsu Province pharmaceutical formulators are expanding procurement of natural-grade camphor oil for topical analgesic production under tightening GB standards for essential oil imports. NMPA enforcement of third-party chromatographic documentation requirements is filtering supplier bases toward certified distillers with captive plantation access.
India
Gujarat State downstream fragrance and API facilities co-locate with refining operations to reduce logistics costs and batch-to-batch variability. BIS quality mandates and CDSCO purity thresholds for pharmaceutical preparations are compressing margins for Southeast Asian distillers while consolidating procurement power among backward-integrated operators.
Indonesia
Sumatran and Javanese Cinnamomum camphora plantations supply over 70% of global biomass, creating weather-dependent supply volatility that fragrance houses mitigate through long-term distillation partnerships. Traditional knowledge of fractional separation techniques for safrole and terpineol control is aging out in processing facilities.
Madagascar
Plantation cooperatives in eastern growing regions are securing direct contracts with European fragrance houses requiring chain-of-custody documentation from specific Cinnamomum camphora origins. FairWild and organic botanical sourcing standards are opening price-tier separation in French and German personal care formulation channels.
Germany
REACH registration requirements constrain market access for unregistered Asian distillers, redirecting trade flows toward compliant intermediaries in Hamburg and Frankfurt chemical trading hubs. ECHA enforcement of chemical compliance blocks direct import channels, forcing reliance on registered traders for pharmaceutical-grade applications.
Camphor Oil Market Competitive Environment
Global majors compete with regional champions across plantation access and fractionation capabilities. The vendor base separates into fragrance houses with backward integration, independent distillers with spot-market exposure, and synthetic manufacturers with petroleum-derived cost structures. Three archetypes dominate: plantation-integrated fragrance compounders, specialty fractionation service providers, and volume-scale synthetic producers. Consolidation is accelerating through direct contracting between cosmetics brands and plantation cooperatives, while capacity expansion concentrates in modular supercritical CO2 extraction units.
Within the plantation-integrated tier, Robertet Group exemplifies upstream control through Madagascar operations, while Albert Vieille anchors Indonesian supply security through long-term distillation partnerships. Treatt Plc occupies a position in specialty fractionation services, isolating high-purity camphor crystals for pharmacopeial compliance.
| Leading Market Players |
|---|
| Albert Vieille |
| Berje |
| Elixens |
| Robertet Group |
| Fleurchem |
| Ultra International |
| Treatt Plc |
| Ernesto Ventos |
| Penta Manufacturing Company |
| Others |
Value Chain & Pricing Dynamics
Cinnamomum camphora biomass spot indices in Sumatran and Javanese markets cascade through three distinct pricing tiers, with pharmaceutical-grade natural oil commanding substantial premiums over synthetic alternatives while fragrance houses absorb volatility through long-term plantation contracts.
Pricing Analysis
Input-cost pass-through from Indonesian plantation gate prices flows unevenly across buyer segments. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-grade natural oil from fragrance-grade fractions and commodity synthetic crystals. Price differentiation rests on GB and BIS certification compliance versus unverified spot supply. Pricing pressure stems from Chinese synthetic manufacturers undercutting natural grades in cleaning product channels. Cleaning product formulators exhibit highest price sensitivity, while pharmaceutical buyers prioritize batch validation over unit cost.
Supply Chain Analysis
Camphor oil supply rests on Cinnamomum camphora biomass concentrated in Indonesian and Chinese plantations, with Madagascar emerging as a secondary cultivation zone. Feedstock dependencies include mature tree stock for steam distillation, supercritical CO2 extraction equipment, and chromatographic testing reagents for compliance documentation. Single-source vulnerability concentrates in Sumatran processing clusters exposed to monsoon disruption. Distribution runs through Hamburg and Frankfurt chemical trading hubs for European REACH-compliant channels, with direct contracting displacing spot intermediaries in fragrance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
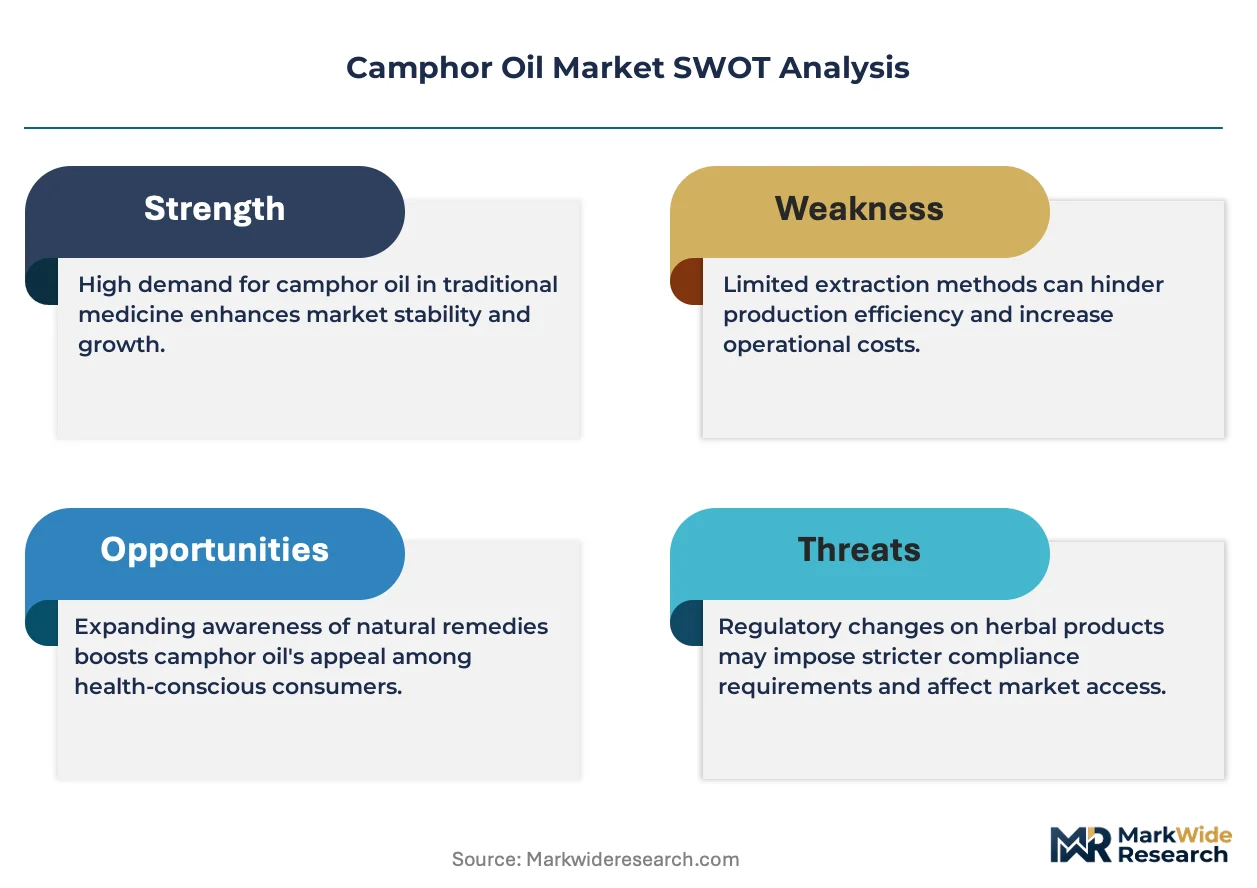
Camphor oil functions as a stable compounder anchored by pharmaceutical formulators' non-discretionary demand for topical analgesic inputs under tightening BIS and GB purity mandates.
For Market Incumbents: Lock in plantation access through direct cooperative contracts in Madagascar and Indonesia before competitor consolidation accelerates. Deepen backward integration into captive biomass supply to offset synthetic substitution pressure in volume segments. Prioritize pharmacopeial certification investments over fragrance-grade capacity expansion. For New Entrants and Emerging Players: Begin with specialty fractionation services isolating high-purity camphor crystals for USP and IP compliance, where technical barriers limit incumbent replication. Target East Asian manufacturing clusters in Jiangsu Province and Gujarat State with modular supercritical CO2 units offering lower-temperature terpenoid preservation. Lead with third-party chromatographic documentation capabilities as your go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with plantation-integrated fragrance compounders possessing direct tree-to-bottle control over cineole-rich fractions. Long-term viability favors operators with captive biomass supply rather than spot-market dependent distillers. Watch synthetic biology alternatives to botanical feedstocks as the critical inflection signal for natural-grade pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Management | Direct biomass control insulates Robertet Group and Albert Vieille from Sumatran spot volatility. |
| Pharmacopeial Certification Investment | USP and IP compliance opens concentrated margin pools in topical analgesic formulation channels. |
| Modular Supercritical CO2 Capacity Expansion | Vietnamese and Madagascar processors preserve heat-sensitive fractions for premium fragrance applications. |
| Long-term Supply Agreement with API Manufacturers | Co-location in Gujarat State and Jiangsu Province reduces batch-to-batch variability for CDSCO and NMPA compliance. |
| Sustainability Certification Program | FairWild and organic standards unlock price-tier separation in French and German cosmetics channels. |
Study Parameters
Coverage spans East Asian manufacturing clusters, European fragrance formulation centers, and Southeast Asian plantation zones, with primary inputs from each. The approach combines interviews with distillation facility operators, pharmaceutical procurement managers at API manufacturers, fragrance house technical directors, and essential oil trading specialists with secondary validation. Sources include BIS and CDSCO regulatory filings, GB standards documentation, customs trade records for Cinnamomum camphora biomass, and REACH registration databases. Bottom-up plantation yield estimates and top-down pharmaceutical demand projections undergo cross-triangulation.
Granularity-level modeling captures product type splits across natural, synthetic, and pharmacopeial grades; end-use segmentation across pharmaceuticals, cosmetics, and cleaning products; and application-level demand for topical analgesics versus fragrance compounding. CAGRs derive from volume-weighted average growth across these dimensions over the projection horizon. Industry-specific inputs include cineole recovery rate assumptions from continuous steam distillation and supercritical CO2 extraction yield differentials.
Several conditions sit outside the modeled scope, including abrupt shifts in Chinese synthetic camphor production economics and unanticipated botanical disease outbreaks in Indonesian plantations. Forecasts reflect assumptions about sustained BIS and GB purity mandate enforcement and stable REACH compliance costs for European market access. A small set of named triggers warrants ongoing watch: synthetic biology feedstock breakthroughs, monsoon disruption severity in Sumatra, and NMPA documentation requirement tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Global Palm Wax Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Neodecanoyl Chloride Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
1-Decene Market
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
US Esters Market
Oleochemicals
Oily Waste Cans Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Ethoxylates Market