
 Octylphenol Ethoxylate Market | 2026-2036
Octylphenol Ethoxylate Market Size, Share, and Industry Trends Forecast 2026-2036
Octylphenol Ethoxylate Market Outlook
Multi-source procurement for ethylene oxide feedstock is restructuring supply relationships across the octylphenol ethoxylate value chain. BASF SE leverages its integrated petrochemical network to secure backward control over key intermediates. Huntsman International LLC anchors its position through specialized surfactant manufacturing scale in North American industrial corridors. Clariant AG differentiates via application-specific formulations for textile and coatings customers.
Octylphenol ethoxylates are nonionic surfactants produced by ethoxylation of octylphenol, typically containing 1–40 moles of ethylene oxide to tune hydrophilic-lipophilic balance for emulsification, wetting, and dispersion tasks. Their primary commercial purpose centers on industrial and institutional cleaning, textile processing, and agrochemical formulation where stable oil-water interfaces prove critical. Liquid grades dominate volume flows due to ease of handling in automated dosing systems, while powder forms command margin pools in specialized coatings and dry-mix detergent applications. The cosmetics application segment faces structural pressure from regulatory scrutiny, redirecting R&D investment toward industrial and agricultural end uses where performance requirements tolerate tighter hazard classifications.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements in Europe constrain product placement and mandate extensive hazard communication documentation. India's Central Pollution Control Board enforces effluent discharge limits that affect textile processors using octylphenol ethoxylate-based wetting agents, shaping local formulation choices. Stakeholders must monitor evolving hazard classifications under the Globally Harmonized System and assess substitution economics against bio-based surfactant alternatives before committing to capacity expansion or contract restructuring.
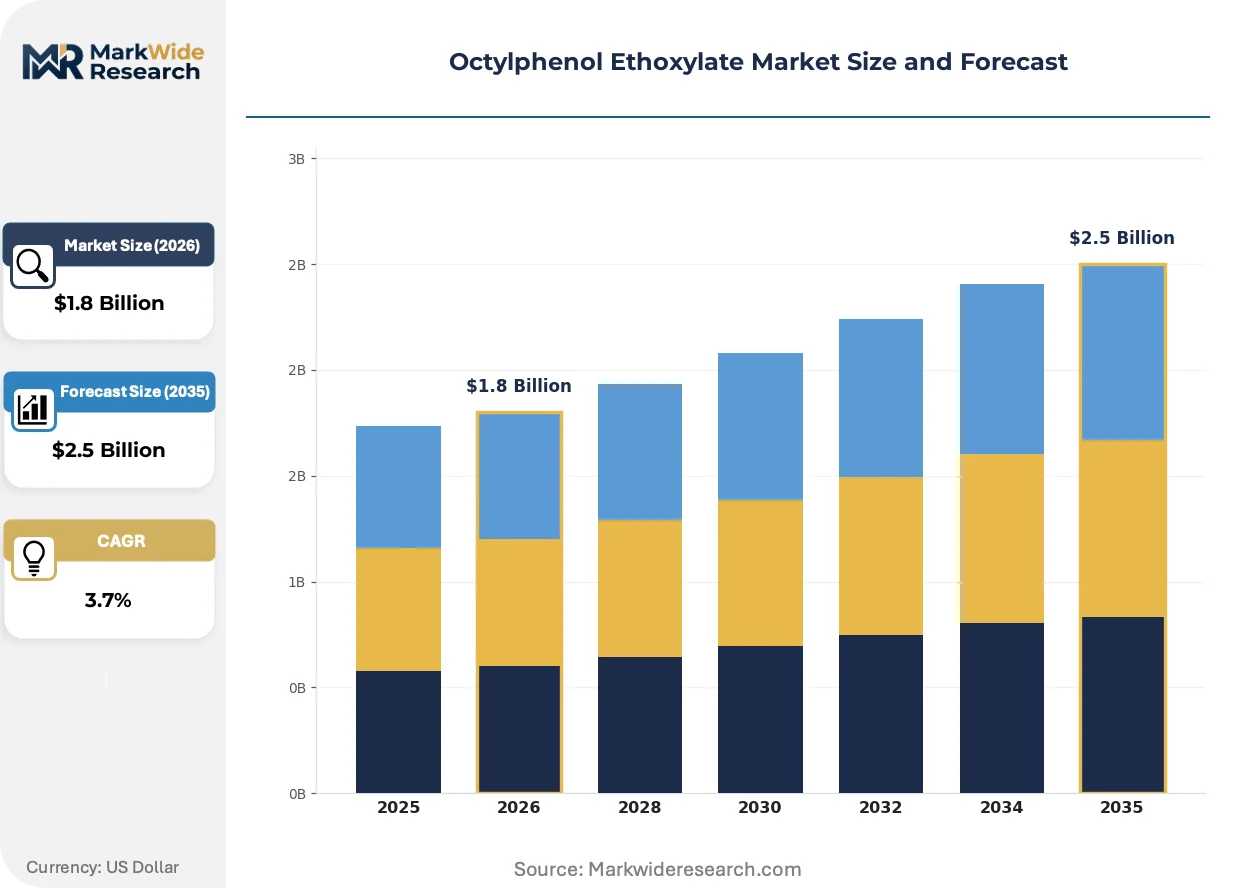
Market Dynamics
REACH restrictions on alkylphenol ethoxylates are forcing European formulators to restructure product portfolios around controlled-use exemptions and alternative chemistries, while Indian textile processors scale domestic surfactant consumption to capture regional supply chain efficiencies.
Growth Catalysts
- Textile wetting agent demand:Indian textile clusters in Surat and Tiruppur are expanding processing capacity, driving consumption of octylphenol ethoxylates for fabric preparation and dye leveling.
- REACH controlled-use pathways:European manufacturers are securing exemptions for industrial applications where substitution proves technically unviable, preserving formulation volumes in coatings and agrochemical sectors.
- Ethoxylation process improvements:Narrow-range ethoxylation technology is enabling tighter ethylene oxide distribution control, yielding surfactants with more predictable performance in automated dosing systems.
Market Restraints
- Ethylene oxide feedstock volatility:Petrochemical-derived ethylene oxide pricing fluctuates with naphtha and ethylene cracker economics, compressing margin predictability for surfactant producers.
- Substitution pressure from bio-based alternatives:Alkyl polyglucosides and sorbitan esters are displacing octylphenol ethoxylates in cosmetics and food-contact applications where hazard classifications tighten.
- REACH authorization timelines:Sunset date uncertainties for nonylphenol ethoxylates create parallel compliance anxiety for octylphenol variants, freezing long-term contract commitments.
Strategic Opportunities
- Agrochemical emulsifier expansion:India's Central Insecticides Board registration pathways for pesticide formulations present growth vectors for surfactant suppliers serving domestic crop protection manufacturing.
- Specialized coatings applications:Powder-grade octylphenol ethoxylates command premium positioning in epoxy and polyurethane systems where liquid handling proves impractical.
- Effluent treatment integration:Textile processors in Gujarat and Tamil Nadu are bundling surfactant procurement with wastewater treatment services, creating bundled solution opportunities.
Industry Challenges
- Globally Harmonized System classification complexity:Evolving hazard communication requirements demand continuous reformulation documentation and safety data sheet revisions across export markets.
- Ethoxylation reactor capex intensity:Pressure vessel and safety system investments for ethylene oxide handling create barriers for mid-scale entrants seeking backward integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octylphenol Ethoxylate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Emulsion Application: Detergents, Coatings, Textiles, Cosmetics End Use: Industrial, Agricultural, Household, Commercial Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | The Dow Chemical Company, BASF SE, Clariant AG, Huntsman International LLC, Matangi Industries LLP, Rimpro India, Venus Ethoxyethers Pvt. Ltd, India Glycols Limited, Jiahua Chemicals Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octylphenol Ethoxylate Market Strategic Shifts
Formulation chemistry is pivoting toward performance-optimized ethoxylate distributions, while regulatory compliance automation and procurement restructuring reshape how surfactant value flows through industrial channels.
Narrow-range ethoxylation catalysts are rewriting surfactant performance specifications. Textile processors in India and coatings formulators in Germany are adopting these materials to achieve tighter hydrophilic-lipophilic balance control. The technology is compressing quality variability penalties in automated production lines where batch-to-batch consistency determines throughput economics.
REACH sunset review procedures for category 2 endocrine disruptors are accelerating substitution timelines. Industrial cleaning and institutional maintenance sectors face reformulation mandates that favor alcohol ethoxylates in open systems. European formulators are responding by segmenting product portfolios between exempt closed-loop industrial applications and consumer-facing alternatives.
Consolidated procurement platforms are restructuring surfactant purchasing patterns. Large Indian textile houses and North American agrochemical blenders are migrating from spot transactions to annual framework agreements with volume commitments. This shift is most visible in Gujarat's chemical trading corridors, where processor buying power concentrates around integrated distributors offering technical service bundled with supply security.
Octylphenol Ethoxylate Market Segmentation
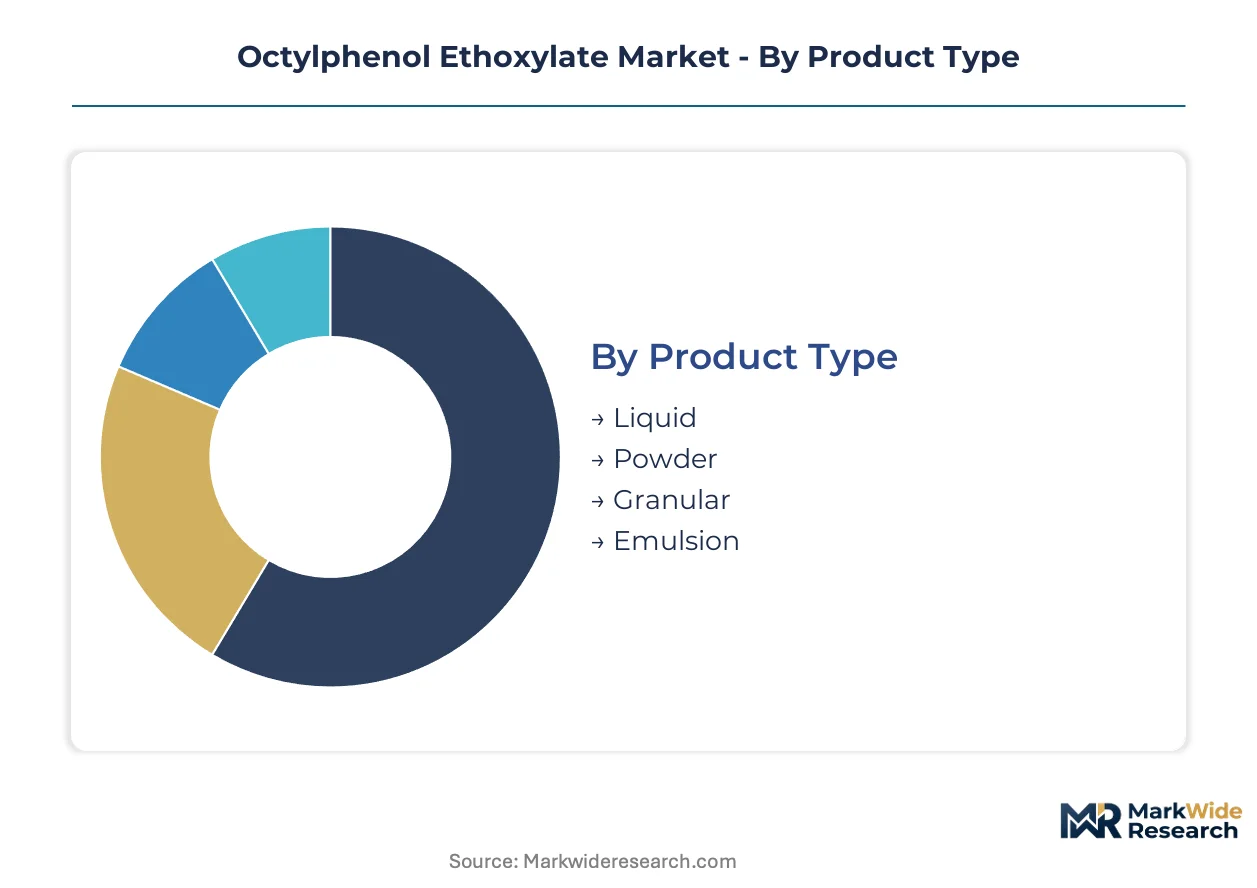
Segmentation in the octylphenol ethoxylate market tracks how regulatory burden, physical form requirements, and channel economics split demand across incompatible use cases. Each dimension carries distinct compliance obligations and margin profiles that shape supplier portfolio decisions.
Product Type:
Liquid grades carry EPA TSCA registration requirements for industrial handlers, while powder forms trigger REACH dust exposure protocols and OSHA respirable crystalline silica monitoring in US facilities. Emulsion variants face dual jurisdiction from FDA food-contact approvals and EPA pesticide inert substance listings.
- Liquid:Dominant physical state for automated textile wetting systems and agrochemical tank-mix applications. Indian processors in Surat and Tiruppur favor liquid grades for continuous dyeing lines where precise dosing controls chemical costs.
- Powder:Engineered for coatings systems where solvent-free handling is mandatory and liquid carriers would compromise cure chemistry. German coatings formulators specify powder grades for epoxy powder coatings in automotive underbody protection.
- Granular:Intermediate flowability for dry-blend detergent manufacturing. Compact agglomerates reduce dust generation versus fine powders during high-speed packaging operations.
- Emulsion:Pre-dispersed aqueous systems for cosmetics and institutional cleaning where end-user mixing infrastructure is limited. Water-based delivery simplifies hazard communication in downstream formulations.
Liquid sits at the top of the volume ranking, with emulsion climbing the fastest as water-based delivery systems displace solvent carriers in institutional applications.
Application:
Cost tier differentiation separates commodity detergent applications from specialized coatings and regulated cosmetics segments, with textile processing occupying the mid-tier where performance premiums justify moderate price elevation.
- Detergents:Volume anchor for standard ethoxylate grades with 7-10 mole ethylene oxide content. Household and industrial cleaning formulations in India consume bulk liquid deliveries through distributor networks.
- Coatings:Narrow-range ethoxylates command specification premiums in automotive and protective coatings where surface tension control determines film integrity. Powder grades dominate this segment due to solvent-free formulation constraints.
- Textiles:Fabric preparation and dye leveling in Surat's synthetic processing clusters and Tiruppur's cotton dyeing houses. Wetting agent specifications vary by fiber type and dye chemistry compatibility.
- Cosmetics:Facing structural displacement from alkyl polyglucosides as REACH endocrine disruptor classifications tighten. Remaining volumes concentrate in industrial hand cleansers and institutional personal care where hazard classifications are tolerated.
Textiles generates the steepest expansion trajectory, with cosmetics contracting as formulators execute substitution mandates.
End Use:
Customer type segmentation separates price-sensitive agricultural commodity buyers from performance-driven industrial processors, with commercial service providers occupying a hybrid position requiring technical support bundled with supply security.
- Industrial:Metal cleaning, degreasing, and process chemical applications where stable emulsion performance justifies higher surfactant loadings. EPA oversight under TSCA mandates extensive exposure documentation for manufacturing facility operators.
- Agricultural:Pesticide emulsifiers and tank-mix adjuvants for India's Central Insecticides Board-registered formulations. Domestic crop protection manufacturing scales are concentrating demand around Gujarat and Maharashtra production corridors.
- Household:Laundry and hard surface cleaning products where cost minimization drives specification toward standard ethoxylate distributions. Brand owners balance performance claims against ingredient disclosure pressures.
- Commercial:Institutional maintenance and food service cleaning where procurement consolidates through facility management contractors. Bundled chemical and equipment supply agreements are restructuring purchasing patterns.
Industrial holds the largest position by value, with agricultural expanding most quickly as India scales domestic pesticide formulation capacity.
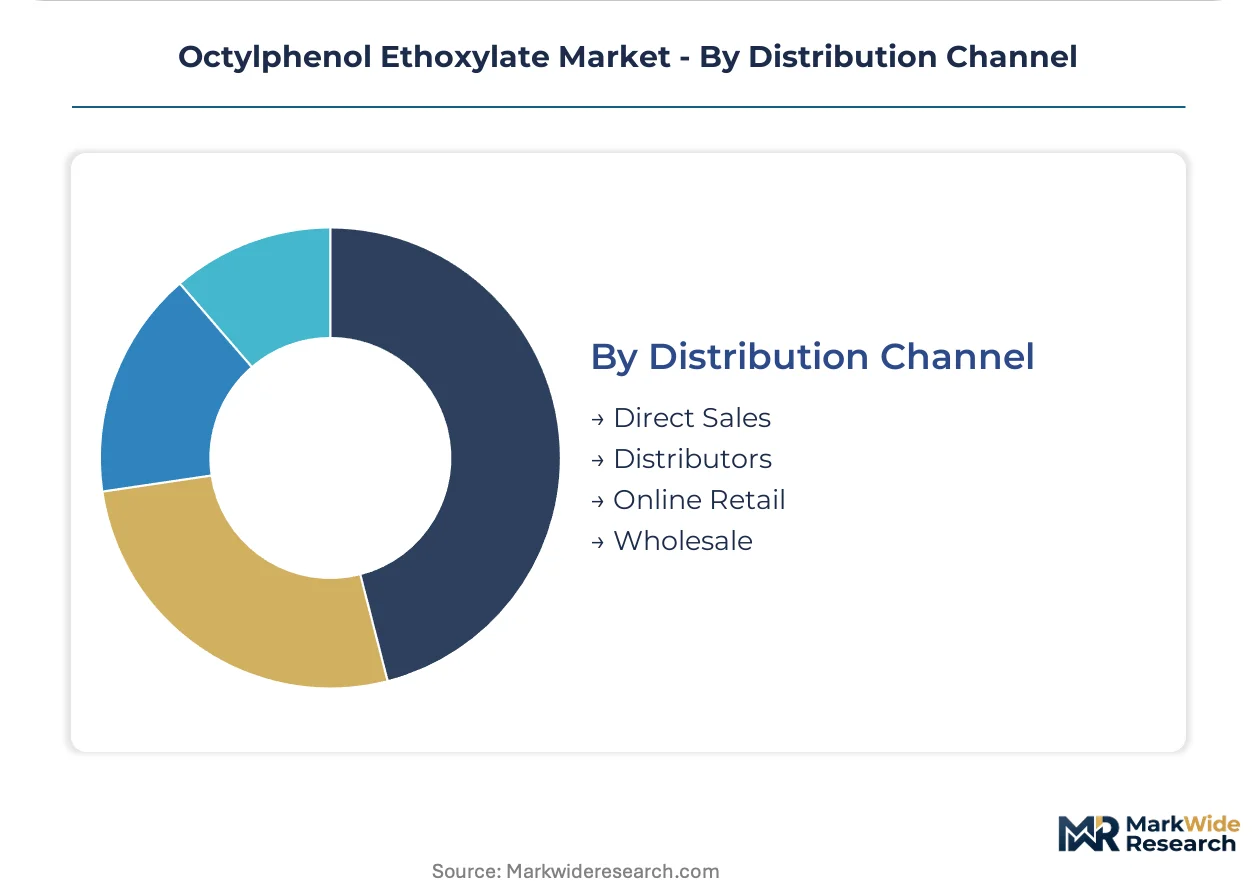
Distribution Channel:
Supply concentration in ethoxylation reactor assets favors direct sales relationships for volume accounts, while fragmented downstream demand sustains distributor networks for mid-scale processors lacking technical specification expertise.
- Direct Sales:Annual framework agreements with volume commitments from large Indian textile houses and North American agrochemical blenders. BASF SE and Huntsman International LLC anchor positions through captive technical service teams.
- Distributors:Chemical trading corridors in Gujarat and Tamil Nadu concentrate buying power around integrated distributors offering inventory management and effluent treatment bundling. Critical access point for mid-scale processors.
- Online Retail:Emerging channel for small-batch laboratory and pilot-scale procurement. Limited to non-hazardous formulations due to shipping restrictions on ethylene oxide-derived materials.
- Wholesale:Bulk break-bulk operations for standard grades where specification differentiation is minimal. Price transparency compresses margins, favoring high-volume, low-touch fulfillment models.
Direct sales dominates value capture, with distributors gaining share fastest as procurement consolidation concentrates technical service requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat's synthetic textile processing corridor anchors global consumption of octylphenol ethoxylate wetting agents. The Central Pollution Control Board enforces effluent discharge limits that reshape formulation choices in Gujarat's chemical belt. Regional demand patterns diverge sharply between REACH-constrained European industrial applications and Asia-Pacific textile expansion corridors.
United States
Agrochemical blenders in the Midwest Corn Belt consume surfactant volumes for pesticide tank-mix formulations. EPA oversight under the Toxic Substances Control Act mandates extensive exposure documentation for manufacturing facility operators. Houston's petrochemical corridor concentrates ethoxylation reactor assets serving domestic industrial cleaning and coatings sectors.
Germany
Coatings formulators in North Rhine-Westphalia specify narrow-range ethoxylates for automotive and protective coatings applications. REACH sunset review procedures for category 2 endocrine disruptors accelerate substitution timelines across open-system industrial cleaning. BASF SE leverages its integrated petrochemical network in Ludwigshafen to secure backward control over key intermediates.
India
Tiruppur's cotton dyeing houses and Surat's synthetic processing clusters expand wetting agent consumption for fabric preparation and dye leveling. The Central Insecticides Board registration pathways for pesticide formulations present growth vectors for surfactant suppliers serving domestic crop protection manufacturing. Gujarat's chemical trading corridors concentrate buying power around integrated distributors offering technical service bundled with supply security.
China
Textile processors in the Yangtze River Delta scale surfactant consumption for export-oriented fabric finishing operations. The Ministry of Ecology and Environment enforces dual carbon goals that reshape petrochemical-derived feedstock economics. Shandong Province's surfactant manufacturing bases serve regional agrochemical formulation and industrial cleaning demand.
Japan
Specialty coatings manufacturers in the Kansai region specify high-purity ethoxylates for electronics and automotive applications. METI industrial chemical regulations mandate hazard communication documentation aligned with Globally Harmonized System classifications. Osaka's chemical trading networks facilitate procurement of narrow-range ethoxylates for precision manufacturing sectors.
Octylphenol Ethoxylate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized surfactant formulations and regional supply chain integration. The market structure consolidates around integrated petrochemical conglomerates with captive ethylene oxide supply and independent surfactant specialists serving niche application requirements. Three archetypes dominate: backward-integrated multinational chemical groups, regional ethoxylation specialists with technical service capabilities, and trading-oriented distributors bundling supply with effluent treatment solutions. Competitive intensity centers on M&A activity targeting regional surfactant formulators and capacity expansion in Indian and Chinese manufacturing corridors.
Among integrated chemical conglomerates, BASF SE and Huntsman International LLC exemplify archetypes of multinational producers with petrochemical network leverage. Clariant AG occupies a position within the specialty formulation tier, differentiating via application-specific product development for textile and coatings customers. Matangi Industries LLP and Rimpro India represent the regional specialist archetype, anchoring supply relationships with domestic Indian textile processors through proximity manufacturing and technical service bundling. These company patterns illustrate how competitive positioning stratifies across global scale, regional specialization, and integrated distribution capabilities.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| BASF SE |
| Clariant AG |
| Huntsman International LLC |
| Matangi Industries LLP |
| Rimpro India |
| Venus Ethoxyethers Pvt. Ltd |
| India Glycols Limited |
| Jiahua Chemicals Inc |
| Others |
Value Chain & Pricing Dynamics
Naphtha price volatility cascades through ethylene oxide cracker economics into octylphenol ethoxylate pricing tiers, compressing margins for non-integrated surfactant producers while rewarding backward-integrated petrochemical conglomerates with captive feedstock supply.
Pricing Analysis
Ethylene oxide contract pass-through clauses dominate surfactant procurement agreements between Indian textile houses and ethoxylation specialists. Price differentiation hinges on ethoxylate mole distribution precision and REACH registration documentation depth, with narrow-range grades commanding specification premiums in German coatings applications. Cost compression in standard-grade liquid formulations intensifies as Gujarat's domestic surfactant production scales. Agricultural pesticide formulators exhibit highest price sensitivity due to commodity crop economics, while automotive coatings buyers tolerate premium positioning for powder-grade consistency.
Supply Chain Analysis
Intermodal freight costs from Ludwigshafen to North Rhine-Westphalia coatings clusters and from Gujarat ports to Tiruppur textile corridors shape landed cost structures for surfactant deliveries. Manufacturing concentrates in Germany, India, and China, with ethoxylation reactor assets clustered around petrochemical feedstock hubs. Supply chains rest on ethylene oxide, octylphenol intermediate, and narrow-range catalyst dependencies. Single-source vulnerability runs through specialized catalyst suppliers controlling ethoxylate distribution precision. Distribution runs through direct annual frameworks for volume accounts and integrated distributor networks for mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The octylphenol ethoxylate market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed formulation savings in Indian textile corridors by a margin that rewards multi-hemisphere supply positioning.
For Market Incumbents: Anticipate alkyl polyglucoside substitution pressure in cosmetics and food-contact segments by accelerating narrow-range ethoxylation R&D investments. Secure backward integration into ethylene oxide supply through captive cracker relationships or long-term offtake agreements with Ludwigshafen and Houston corridor producers. Channel control through technical service bundling defends margin position against trading-oriented distributors in Gujarat's chemical belt. For New Entrants and Emerging Players: Launch via effluent-treatment-integrated distribution partnerships serving Surat and Tiruppur textile processors facing Central Pollution Control Board discharge enforcement. Target agrochemical emulsifier supply to Maharashtra and Gujarat crop protection manufacturers scaling under Central Insecticides Board registration pathways. White-space availability concentrates in powder-grade specialty coatings for automotive underbody protection where liquid handling constraints create specification stickiness. For Investors and Strategic Acquirers: Consolidation pressure builds where regional ethoxylation specialists lack captive ethylene oxide supply and face feedstock cost volatility eroding project returns. Long-term viability favors acquirers of Indian surfactant formulators with technical service capabilities and Central Insecticides Board registration expertise. The acquisition target archetype combines regional manufacturing presence with narrow-range ethoxylation catalyst access. Watch REACH sunset review timelines for category 2 endocrine disruptor classifications as inflection signals for substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates BASF SE and Huntsman International LLC from naphtha volatility. |
| Narrow-Range Ethoxylation Capacity Expansion | Precision catalyst investments enable specification premiums in German automotive coatings applications. |
| REACH Registration Documentation Investment | Controlled-use exemption pathways preserve European formulation volumes in industrial cleaning sectors. |
| Effluent Treatment Service Bundling | Integrated distributors in Gujarat capture textile processor procurement consolidation. |
| Central Insecticides Board Registration Pathway | Domestic agrochemical formulation scaling in Maharashtra opens surfactant supply contracts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ethoxylation plant managers, textile procurement leads at Surat processing houses, coatings R&D directors in North Rhine-Westphalia, and agrochemical formulation specialists in Gujarat with secondary validation against customs trade data, SEC 10-K filings, and ECHA registration databases. Bottom-up segment sizing and top-down petrochemical demand modeling triangulated volume estimates.
Comparable historical periods anchored the projection horizon across ethoxylate mole distribution tiers, application segments spanning textile wetting and agrochemical emulsification, and regional production hub clusters. CAGRs derived from ethoxylation capacity utilization trends, textile processing expansion rates in Indian chemical corridors, and REACH substitution timeline assumptions. Forecast inputs incorporated narrow-range catalyst adoption curves and Central Insecticides Board registration throughput.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH authorization timeline acceleration or ethylene oxide supply disruptions from cracker maintenance cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Isobutyl Stearate Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Global Wax Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Pentalide (Cyclopentadecanolide) Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Paraffin Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
1-Decene Market
Oleochemicals
Stearyl Tartrate Market