
 India Full Service Restaurants Market | 2026-2036
India Full Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
India Full Service Restaurants Market Insights
FSSAI compliance certification is bifurcating the competitive landscape into organized chains and fragmented unlicensed operators. Barbeque Nation Hospitality Ltd leverages its live-grill format to sustain repeat visitation across tier-1 and tier-2 cities. ITC Limited anchors premium positioning through its luxury hotel F&B portfolio, while Speciality Restaurants Ltd competes on regional cuisine depth with its Mainland China and Oh! Calcutta banners.
India full service restaurants encompass dine-in establishments where patrons receive table service, menu customization, and experiential ambiance across cuisines and price points; operations depend on cold-chain logistics for perishables, standardized recipes for consistency, and trained front-of-house staff for service delivery. The cuisine type dimension shows Indian cuisine dominating volume due to cultural affinity, while continental and Italian formats command higher per-cover spending in urban centers. Within ambiance, casual dining occupies the broadest footprint, whereas fine dining captures disproportionate margin pools from business entertainment and celebration occasions.
FSSAI licensing mandates govern food safety protocols, while state-level excise departments regulate liquor permits that determine revenue mix for full-service formats. The Bureau of Indian Standards (BIS) certification for packaged drinking water and kitchen equipment adds another compliance layer for chain operators. Stakeholders must monitor evolving GST rate structures on restaurant services and emerging municipal zoning restrictions on commercial kitchen exhaust and waste disposal.
Market Dynamics
FSSAI licensing mandates are restructuring competitive viability across India, forcing capital deployment toward kitchen infrastructure and ingredient traceability systems that unorganized operators cannot absorb.
Growth Catalysts
- Urban Millennial Dine-Out Frequency:Metropolitan consumers aged 25-40 demonstrate sustained table-service visitation patterns across Maharashtra and Karnataka, creating volume anchors for organized format expansion.
- Cold-Chain Logistics Maturation:Temperature-controlled distribution networks for perishables now reach tier-2 cities, enabling standardized recipe execution outside traditional metro strongholds.
- FSSAI Compliance Regime:The licensing framework creates competitive moats for chains with documented kitchen protocols and supplier audit trails.
Market Restraints
- Commercial Real Estate Concentration:Premium high-street and mall frontage in Delhi NCR and Mumbai commands rental structures that compress margin pools for mid-market formats.
- State-Level Excise Fragmentation:Liquor permit heterogeneity across Maharashtra, Karnataka, and Delhi NCR forces location-specific revenue modeling and inventory management complexity.
- Skilled Front-of-House Scarcity:Trained service staff availability constrains table-turn optimization and consistent experience delivery across expansion targets.
Strategic Opportunities
- Tier-2 City Penetration:Organized chains face limited branded competition in Jaipur, Lucknow, and Indore, where disposable income growth precedes supply response.
- Regional Cuisine Depth:Format innovation around Bengali, Chettinad, and Awadhi specialization captures celebration occasions with premium per-cover economics.
- GST Rate Rationalization:Potential service tax restructuring would improve post-tax margin visibility for capital-intensive kitchen investments.
Industry Challenges
- Ingredient Traceability Documentation:FSSAI-mandated supplier verification creates administrative burden and procurement friction for multi-location operators.
- Municipal Zoning Compliance:Commercial kitchen exhaust and waste disposal regulations in Delhi NCR and Bengaluru impose location-specific operational constraints and retrofit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Full Service Restaurants Market |
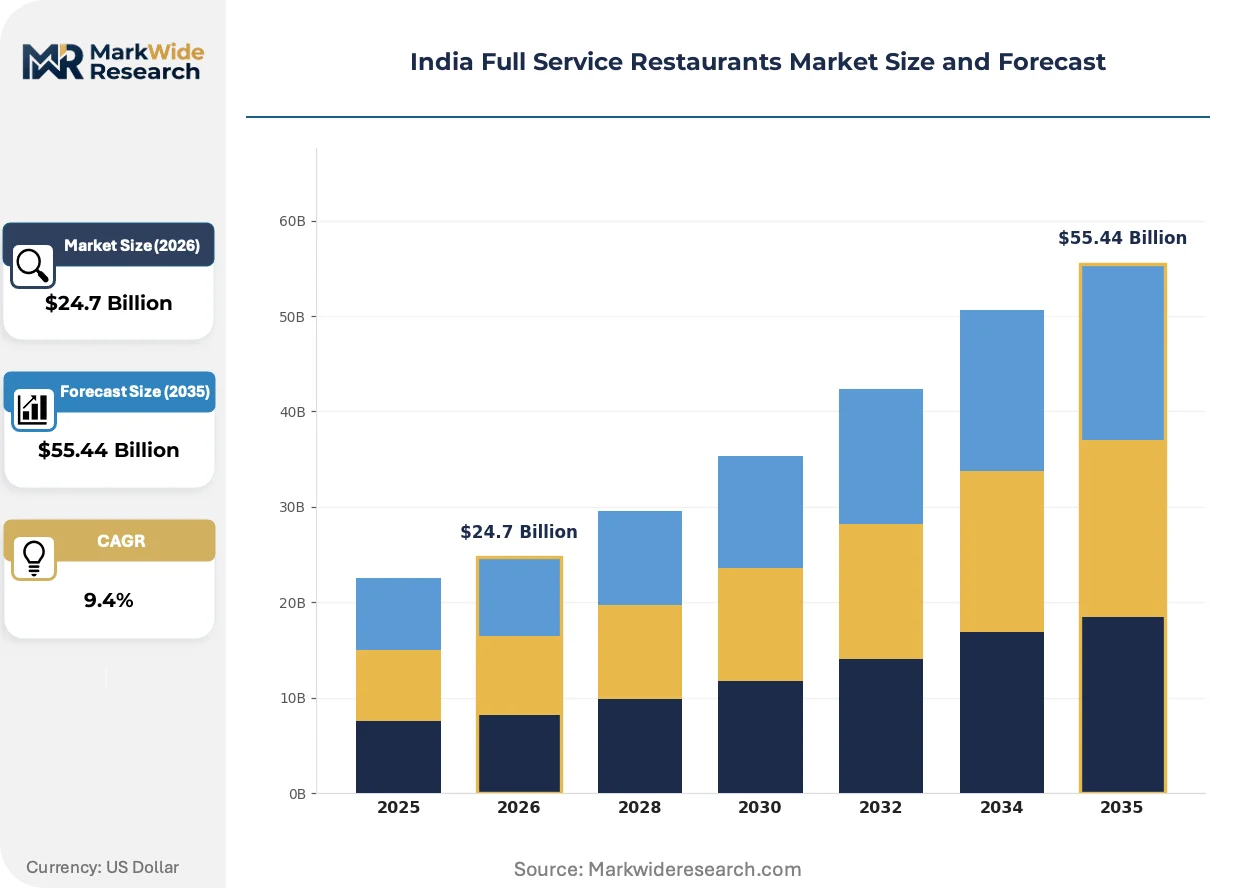
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $55.44 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Model: Dine-in, Takeaway, Delivery, Buffet Cuisine Type: Indian, Italian, Chinese, Continental Customer Type: Families, Couples, Business, Tourists Ambiance: Casual Dining, Fine Dining, Fast Casual, Themed |
| Companies Covered | Haldiram Foods International Pvt Ltd, Hotel Saravana Bhavan, Barbeque Nation Hospitality Ltd, Ohri's Group, Sagar Ratna Restaurants Private Limited, The Indian Hotels Company Limited, Speciality Restaurants Ltd, Paradise Food Court Pvt Ltd, ITC Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Full Service Restaurants Market Trends and Innovations
Digital ordering infrastructure and live-kitchen transparency are redefining patron expectations, while regulatory pressure on food safety documentation accelerates technology adoption across operational workflows.
Cloud-based kitchen display systems with real-time order tracking are supplanting paper ticket workflows in casual dining chains. Operators in Bengaluru and Mumbai deploy these platforms to synchronize front-of-house and back-of-house pacing. The technology compresses service cycle variance and enables labor reallocation toward guest interaction.
FSSAI's digitized licensing portal and mandatory food safety supervisor certification are tightening compliance documentation requirements. Kitchen infrastructure investments now prioritize audit-ready layouts with segregated raw-cooked zones and temperature logging automation. Premium casual formats in Delhi NCR absorb these costs fastest, using certification visibility as patron reassurance.
Patron preference for open-kitchen visibility and live-cooking theater is rotating demand toward experiential formats. Casual dining chains respond with grill-at-table and tandoor-view configurations that justify per-cover premiums. This behavior concentrates in Maharashtra and Karnataka urban centers where social media documentation drives venue selection.
India Full Service Restaurants Market Segmentation
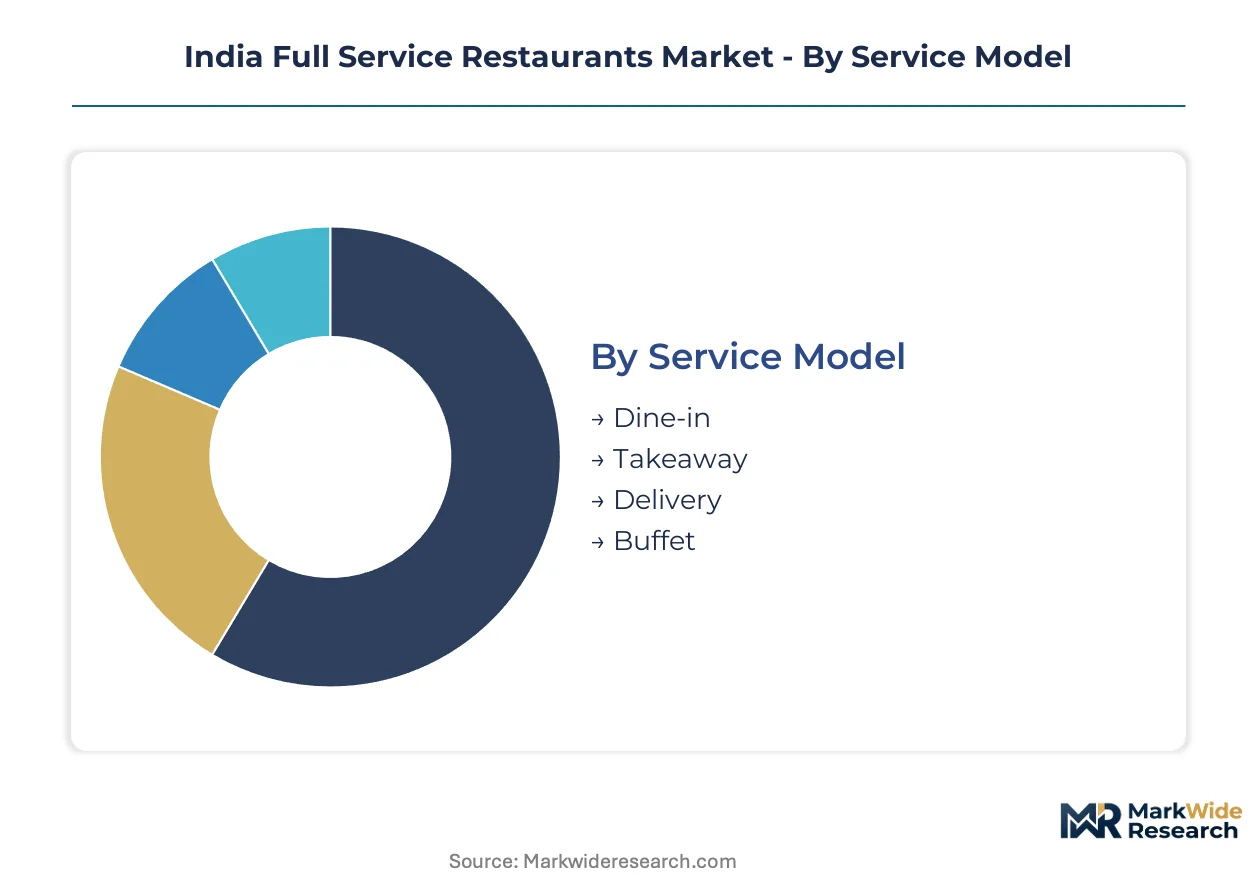
Segmentation in the India full service restaurants market reveals how substitution pressure from cloud kitchens and quick-service formats reshapes format viability. Each dimension exposes distinct vulnerability profiles and defensive positioning opportunities for table-service operators.
Service Model:
Dine-in formats face acute substitution threat from delivery aggregators and dark kitchens, forcing experiential differentiation as the primary defense mechanism.
- Dine-in:Table-service format with full front-of-house staffing and ambiance investment constitutes the core revenue pool for organized chains. Maharashtra and Karnataka urban centers sustain this format through celebration occasion clustering and business entertainment demand that delivery cannot replicate.
- Buffet:Fixed-price unlimited consumption model leverages operational predictability and per-cover economics that outperform à la carte during weekday lunch rushes. Barbeque Nation's live-grill buffet format demonstrates how theatrical cooking stations create defensible repeat visitation in tier-1 and tier-2 cities.
- Takeaway:Counter-collection format with minimal service interaction captures convenience-oriented demand without the real estate burden of full dining rooms.
- Delivery:Third-party aggregator-dependent channel exposes operators to commission structures and brand dilution risks.
Dine-in retains volume leadership; buffet holds the steepest expansion curve as experiential formats penetrate beyond metropolitan cores.
Cuisine Type:
Cost tier stratification separates mass-market affinity formats from premium positioning opportunities in metropolitan India.
- Indian:Indigenous cuisine formats command cultural default status across all price tiers, with regional specialization (Chettinad, Awadhi, Bengali) enabling premium positioning within the category. Speciality Restaurants Ltd demonstrates this through Oh! Calcutta's focused Bengali menu architecture.
- Continental:European-influenced preparations attract higher per-cover spending in Delhi NCR and Mumbai business districts where international clientele and expatriate populations concentrate. ITC Limited's luxury hotel F&B portfolio anchors this positioning through ingredient sourcing standards and wine program integration.
- Chinese:Pan-Asian format with Indian adaptation history sustains broad appeal but faces compression from dedicated Asian quick-service competitors.
- Italian:Pizza-pasta focused formats occupy mid-premium positioning with standardized supply chains enabling consistency across locations.
Indian cuisine commands absolute volume; continental formats capture the widest per-cover premium spreads.
Customer Type:
Volume concentration patterns reveal which occasion types sustain table-service economics against delivery substitution.
- Families:Multi-generational dining occasions drive weekend peak capacity utilization and buffet format preference across tier-1 cities. This segment's price sensitivity and occasion infrequency create vulnerability to casual dining chains that balance experience with accessibility.
- Business:Corporate entertainment and client dining sustains fine dining margins through beverage attachment and private dining room utilization. Delhi NCR and Mumbai financial districts concentrate this demand with per-cover economics that justify premium real estate investments.
- Couples:Date-night and casual social occasions favor ambiance-forward formats with moderate price positioning and Instagram-compatible design elements.
- Tourists:Transient demand concentrates around heritage districts and hotel-adjacent locations with cuisine authenticity as the primary selection criterion.
Family occasions anchor absolute volume; business dining sustains the highest margin contribution per seat.
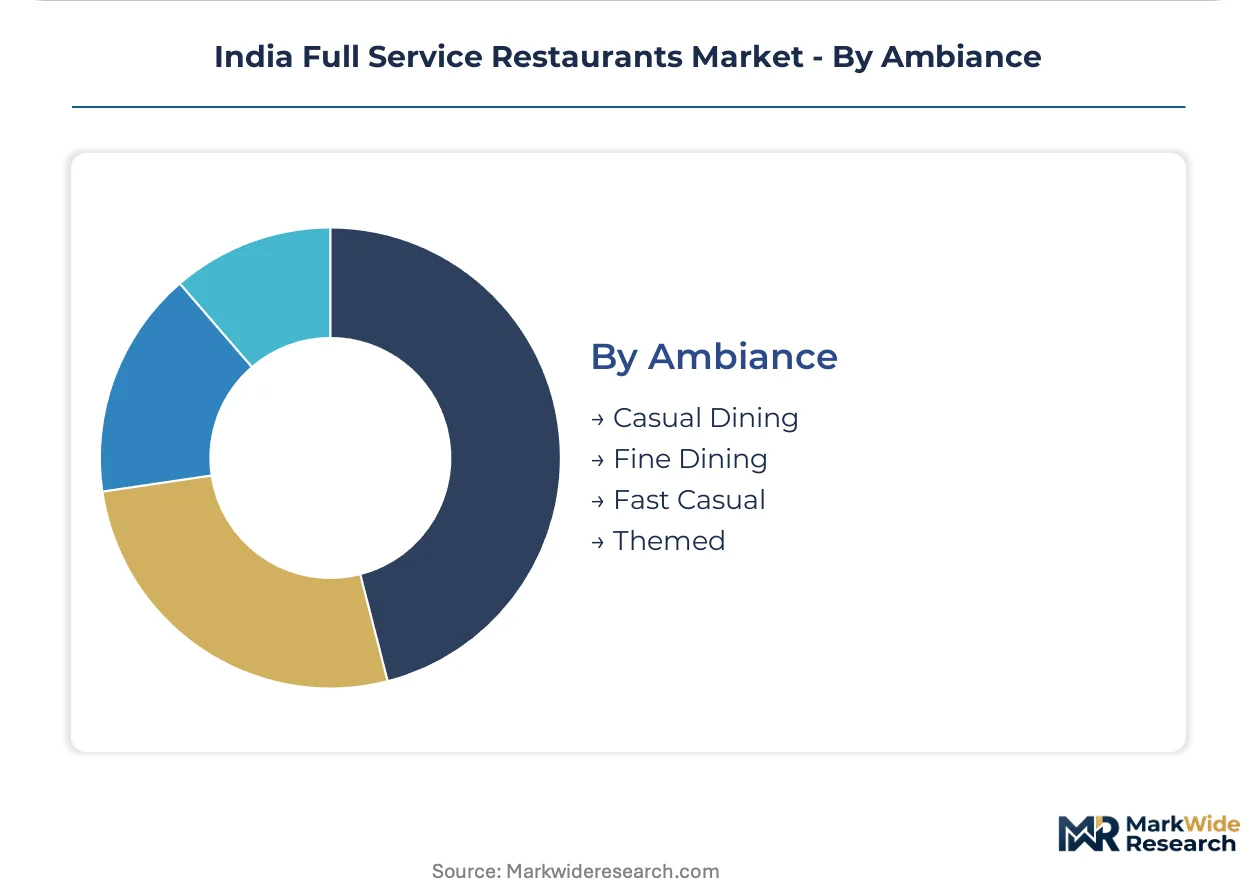
Ambiance:
Maturity gradients separate established format conventions from emerging hybrid positioning opportunities.
- Casual Dining:Mid-market table-service format with standardized menus and trained service protocols occupies the broadest geographic footprint. This segment absorbs FSSAI compliance costs most efficiently through scale, with chains like Barbeque Nation leveraging format replication across 25+ cities.
- Fine Dining:Premium occasion-focused format with chef-driven menus and extensive beverage programs captures disproportionate margin pools from celebration and business segments. ITC Limited's luxury hotel restaurants exemplify this positioning through integrated hospitality ecosystems.
- Fast Casual:Hybrid format combining counter service with elevated ingredient quality and contemporary design occupies an emerging niche between quick-service and full-service economics.
- Themed:Experiential format with immersive decor and entertainment elements commands premium pricing but faces replication constraints and location-specific demand volatility.
Casual dining retains the widest location footprint; fast casual is gaining share fastest as urban millennials seek experience-quality balance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI's digitized licensing portal and mandatory food safety supervisor certification are restructuring competitive viability across Indian states. Organized chains with documented kitchen protocols capture disproportionate expansion opportunities as compliance costs fragment unorganized operators.
Maharashtra
Mumbai and Pune metropolitan clusters sustain the highest dine-out frequency among urban millennials aged 25-40. The Maharashtra excise department's liquor permit regulations force location-specific revenue modeling for full-service formats. Thane and Nashik corridors concentrate mid-market casual dining expansion as organized chains displace unbranded local eateries.
Karnataka
Bengaluru's technology workforce generates sustained business entertainment and celebration occasion demand. State-level FSSAI enforcement through Karnataka's food safety commissionerate tightens kitchen infrastructure requirements. Whitefield and Electronic City sub-markets absorb premium casual dining formats with experiential live-cooking theater configurations.
Delhi NCR
Gurgaon and Noida financial districts anchor fine dining margin pools through corporate client entertainment spending. Municipal zoning restrictions on commercial kitchen exhaust and waste disposal impose retrofit costs and location-specific operational constraints. Select Citywalk and Cyber Hub clusters concentrate branded chain footprints with disproportionate per-cover economics.
Telangana
Hyderabad's pharmaceutical and IT corridors generate dual-income household disposable income growth. The state's FSSAI regional office mandates ingredient traceability documentation that favors organized operators with supplier audit systems. Banjara Hills and Jubilee Hills micro-markets attract regional cuisine depth specialists targeting celebration occasions.
Tamil Nadu
Chennai's conservative dining culture sustains family occasion clustering across multi-generational households. Tamil Nadu's municipal corporation licensing for commercial kitchen operations adds compliance layering beyond central FSSAI mandates. T. Nagar and Adyar corridors concentrate South Indian cuisine format replication with standardized recipe execution.
India Full Service Restaurants Market Competitive Landscape
Player mix skews toward organized domestic chains with demonstrated format replication capability across tier-1 and tier-2 cities. The competitive structure bifurcates between capital-intensive kitchen infrastructure investors and fragmented unlicensed operators facing compliance-driven exit pressure. Two strategic archetypes dominate: experiential format specialists leveraging live-cooking theater for repeat visitation, and luxury hotel F&B portfolios anchoring premium positioning through integrated hospitality ecosystems. Dominant competitive moves include geographic expansion into underpenetrated tier-2 markets and portfolio diversification around regional cuisine depth.
Within the experiential format tier, Barbeque Nation Hospitality Ltd and Speciality Restaurants Ltd exemplify archetype differentiation through live-grill buffet configurations and focused regional cuisine banners respectively. ITC Limited anchors luxury positioning through its hotel F&B portfolio structure. Haldiram Foods International Pvt Ltd occupies a position spanning casual dining and packaged foods with distribution infrastructure that supports format adjacencies. The Indian Hotels Company Limited represents integrated hospitality ecosystem approaches where restaurant operations capture guest capture economics within accommodation-dominant properties.
| Leading Market Players |
|---|
| Haldiram Foods International Pvt Ltd |
| Hotel Saravana Bhavan |
| Barbeque Nation Hospitality Ltd |
| Ohri's Group |
| Sagar Ratna Restaurants Private Limited |
| The Indian Hotels Company Limited |
| Speciality Restaurants Ltd |
| Paradise Food Court Pvt Ltd |
| ITC Limited |
| Others |
Pricing and Supply Chain Analysis
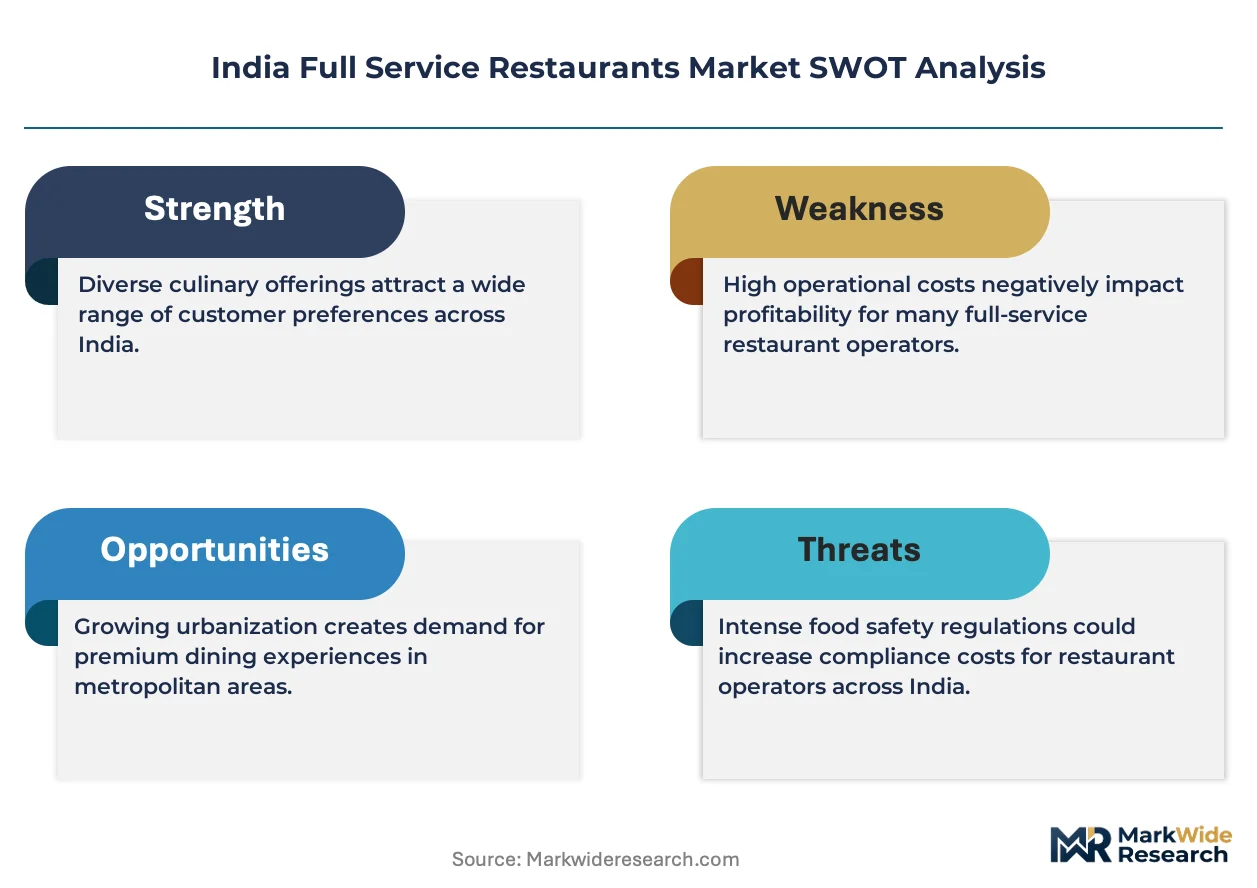
FSSAI certification tiers gate both supplier qualification and per-cover pricing power across Indian metropolitan clusters. Organized chains absorb kitchen infrastructure costs to access premium positioning, while unlicensed operators face margin compression from compliance-driven procurement friction.
Pricing Analysis
Certification level creates the primary spread between premium and mass-market formats. Three-tier pricing structure across FSSAI-compliant premium, organized standard, and unlicensed economy segments anchors market stratification. Pricing pressure stems from commercial real estate concentration in Mumbai and Delhi NCR corridors. Family dining segments exhibit highest price sensitivity, while business entertainment occasions sustain premium tier resilience.
Supply Chain Analysis
Cold-chain logistics maturation from Maharashtra and Karnataka distribution hubs reduces perishable spoilage costs for tier-2 city expansion. Key inputs draw from domestic agricultural belts for fresh produce, imported seafood landing at Mumbai and Chennai ports, and packaged goods from Haryana and Uttar Pradesh manufacturing clusters. Single-source vulnerability concentrates in specialty ingredient categories like Himalayan trout and Kashmiri saffron. Distribution runs through company-owned central kitchens feeding satellite locations, supplemented by third-party logistics for last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's digitized licensing portal and mandatory food safety supervisor certification create a regulatory inflection that rewards capital-intensive compliance investments. This framework accelerates displacement of fragmented unlicensed operators by documented kitchen protocols.
For Market Incumbents: Secure FSSAI audit-ready kitchen layouts with segregated raw-cooked zones and automated temperature logging. Lock in tier-2 city real estate in Jaipur, Lucknow, and Indore before rental structures compress. Vertical integration into central kitchen infrastructure defends against delivery aggregator commission erosion.
For New Entrants and Emerging Players: Differentiate on regional cuisine depth with Chettinad, Awadhi, or Bengali specialization capturing celebration occasion premiums. Target Hyderabad and Chennai micro-markets where branded competition remains sparse. Deploy experiential live-cooking theater formats to justify per-cover premiums against cloud kitchen substitution.
For Investors and Strategic Acquirers: FSSAI compliance regime reshapes the acquisition landscape toward organized chains with documented supplier audit trails. Long-term viability favors targets with demonstrated format replication across 15-plus cities and integrated cold-chain capabilities. Watch for municipal zoning rulings on commercial kitchen exhaust in Bengaluru and Delhi NCR as inflection signals for retrofit cost exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| FSSAI Compliance Certification | Creates competitive moats against unlicensed operators in Maharashtra and Karnataka clusters. |
| Tier-2 City Geographic Expansion | Captures disposable income growth in Jaipur and Indore ahead of branded supply response. |
| Regional Cuisine Format Diversification | Targets celebration occasions with Bengali and Chettinad specialization at premium per-cover economics. |
| Central Kitchen Infrastructure Investment | Enables standardized recipe execution and supplier traceability documentation for multi-location scale. |
| Live-Cooking Theater Configuration | Justifies experiential premiums through grill-at-table and tandoor-view formats in urban millennial segments. |
Research Methodology
A spread of perspectives from restaurant operations directors, FSSAI compliance officers, supply chain managers at cold-chain logistics providers, and procurement leads at multi-location chains converged on the working assumptions. Secondary validation drew from FSSAI licensing databases, state excise department permit records, municipal corporation zoning filings, and Bureau of Indian Standards certification registries. Bottom-up location-level revenue modeling and top-down cuisine segment aggregation were triangulated against metropolitan disposable income indices.
Segmentation dimensions modeled include service model, cuisine type, customer occasion, and ambiance tier across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory compliance cost absorption rates. Forecast inputs incorporated cold-chain logistics penetration curves and state-level excise permit issuance patterns.
Material uncertainties — FSSAI enforcement intensity variations across states, municipal zoning retrofits, and GST rate restructuring — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance cost trajectories and real estate rental structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Smoker Grill Market
Food Service
Europe Airline Catering Services Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Limited-Service Restaurants Market
Food Service
Gas Floor Fryers Market
Food Service
Egypt Food Service Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Latin America Online Grocery Market
Food Service
Restaurant Griddle Market
Food Service
Commercial Rice Cooker Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
GCC Food Service Market
Food Service
Food Service Market
Food Service
India Inflight Catering Market
Food Service
Commercial Pizza Oven Market
Food Service
Restaurant Glassware Market