
 Chained Consumer Foodservice Market | 2026-2036
Chained Consumer Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Chained Consumer Foodservice Market Outlook
Delivery platform partnerships is reshaping how chained foodservice operators reach consumers, collapsing traditional distance barriers between kitchen and household. McDonald's leverages its global real estate footprint to sustain drive-thru dominance across suburban corridors. Starbucks anchors premium coffee shop positioning through beverage innovation and workspace-oriented store formats. Chipotle Mexican Grill differentiates with fresh-ingredient supply chain control and customizable menu architecture.
Chained consumer foodservice denotes branded restaurant networks operating under centralized ownership, franchising, or licensing agreements with standardized menus, procurement protocols, and quality assurance systems spanning multiple locations. These operations rely on cold-chain logistics, point-of-sale integration, and batch-cooking processes to deliver consistent product experiences at scale. Fast food chains command the largest revenue pools through high-volume, low-margin throughput models, while coffee shop segments capture superior per-transaction yields. Delivery service type represents the fastest-expanding channel as mobile ordering infrastructure matures, though dine-in formats retain stronger attachment rates in casual dining sub-segments.
FDA food safety protocols, USDA nutritional labeling mandates, and local health department inspection regimes collectively dictate operational compliance burdens across US-based chains. EFSA hygiene standards and EU Green Deal sustainability reporting requirements shape European market entry and menu reformulation strategies. Stakeholders must weigh capital allocation between ghost kitchen expansion and physical footprint renovation as consumer channel preferences continue fragmenting.
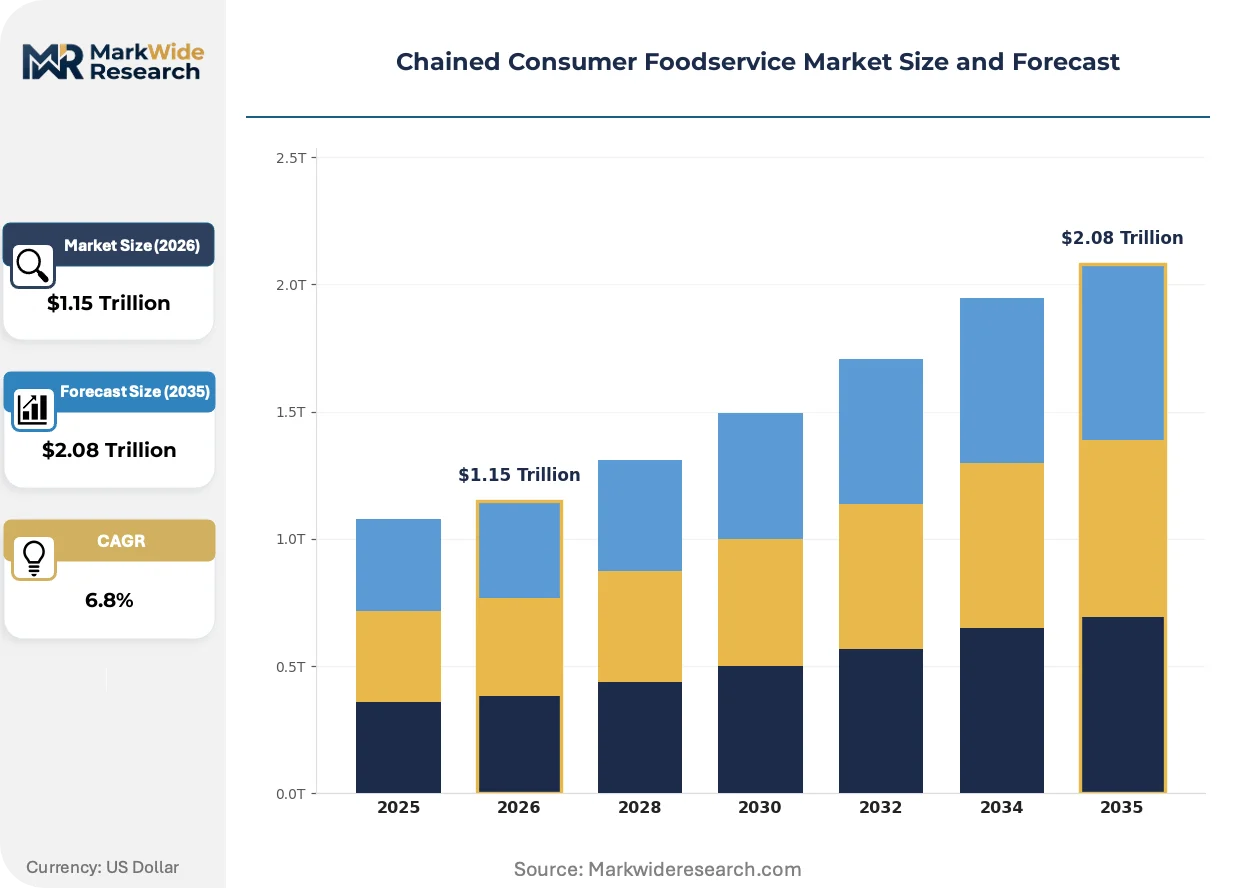
Market Dynamics
Digital ordering infrastructure is collapsing traditional distance barriers between kitchen and household, forcing chained operators to reallocate capital between ghost kitchen expansion and physical footprint renovation.
Growth Catalysts
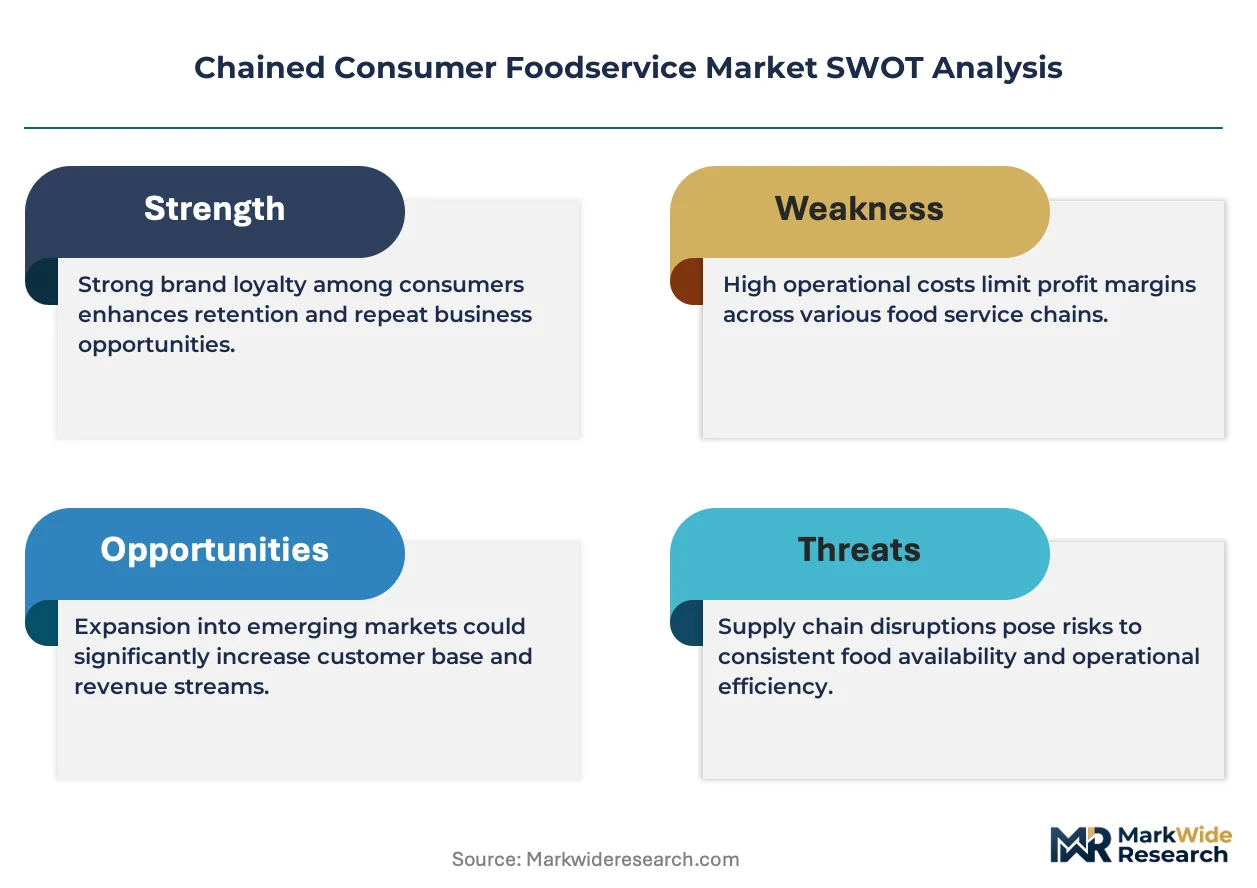
- EU Green Deal sustainability reporting:Mandates for supply chain transparency are accelerating menu reformulation and packaging innovation across European markets.
- Mobile ordering platforms:Urban young adult demographics in China's tier-one cities are driving delivery volume through integrated app ecosystems.
- Kitchen automation:Batch-cooking process standardization is reducing labor dependency and throughput variability in high-volume operations.
Market Restraints
- Commercial real estate concentration:Prime suburban corridor sites for drive-thru formats face bidding competition from retail and logistics tenants.
- Cold-chain logistics cost volatility:Refrigerated transport and storage energy inputs fluctuate with electricity pricing regimes.
- Substitution by prepared retail:Grocery deli sections and convenience store hot food programs capture occasion-based meal demand.
Strategic Opportunities
- India's tier-two urbanization:Chained penetration in secondary cities remains underdeveloped relative to metropolitan corridors.
- Workspace-oriented formats:Premium coffee shop concepts with WiFi and seating infrastructure target remote worker segments.
- US IRA energy incentives:Kitchen equipment electrification and solar installation subsidies reduce facility operating costs.
Industry Challenges
- Point-of-sale integration complexity:Legacy franchise systems require costly middleware to connect with third-party delivery APIs.
- Health department inspection variability:Local jurisdiction protocols create compliance friction for multi-state operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chained Consumer Foodservice Market |
| Market Size in 2026 | $1.15 Trillion |
| Market Size in 2035 | $2.08 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-In, Takeout, Delivery, Drive-Thru Product Type: Fast Food, Casual Dining, Coffee Shop, Buffet Customer Type: Families, Young Adults, Seniors, Students End User: Individuals, Corporations, Institutions, Events |
| Companies Covered | Dunkin', Domino's Pizza, McDonald's, Wendy's, Burger King, Starbucks, Taco Bell, Chipotle Mexican Grill, Subway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chained Consumer Foodservice Market Strategic Shifts
Operational technology stacks are converging around cloud-native architectures, collapsing the distinction between front-of-house service and back-of-house production planning.
Kitchen display systems and predictive prep algorithms are virtualizing the traditional expediter role, compressing ticket-to-handoff times. Quick-service chains with drive-thru dominance are adopting these systems fastest, enabling dynamic menu boards that adjust offerings based on real-time throughput capacity. This virtualization of kitchen coordination is reducing labor hours per transaction while maintaining consistency across dispersed locations.
EFSA hygiene standards are tightening cross-border supply documentation requirements for protein and produce sourcing. European operators must now maintain blockchain-traceable lot records from farm to fryer. Coffee shop and fast-casual segments face the heaviest compliance burden, responding by consolidating supplier bases and investing in automated temperature logging systems.
Young adult consumption patterns are fragmenting across occasion types rather than consolidating around brand loyalty. Drive-thru formats capture suburban commuter demand while ghost kitchens serve apartment-dwelling households without parking access. China's tier-one cities exhibit the most pronounced channel bifurcation, with Western and local chains competing through delivery-exclusive menu items rather than dine-in experience differentiation.
Chained Consumer Foodservice Market Segmentation
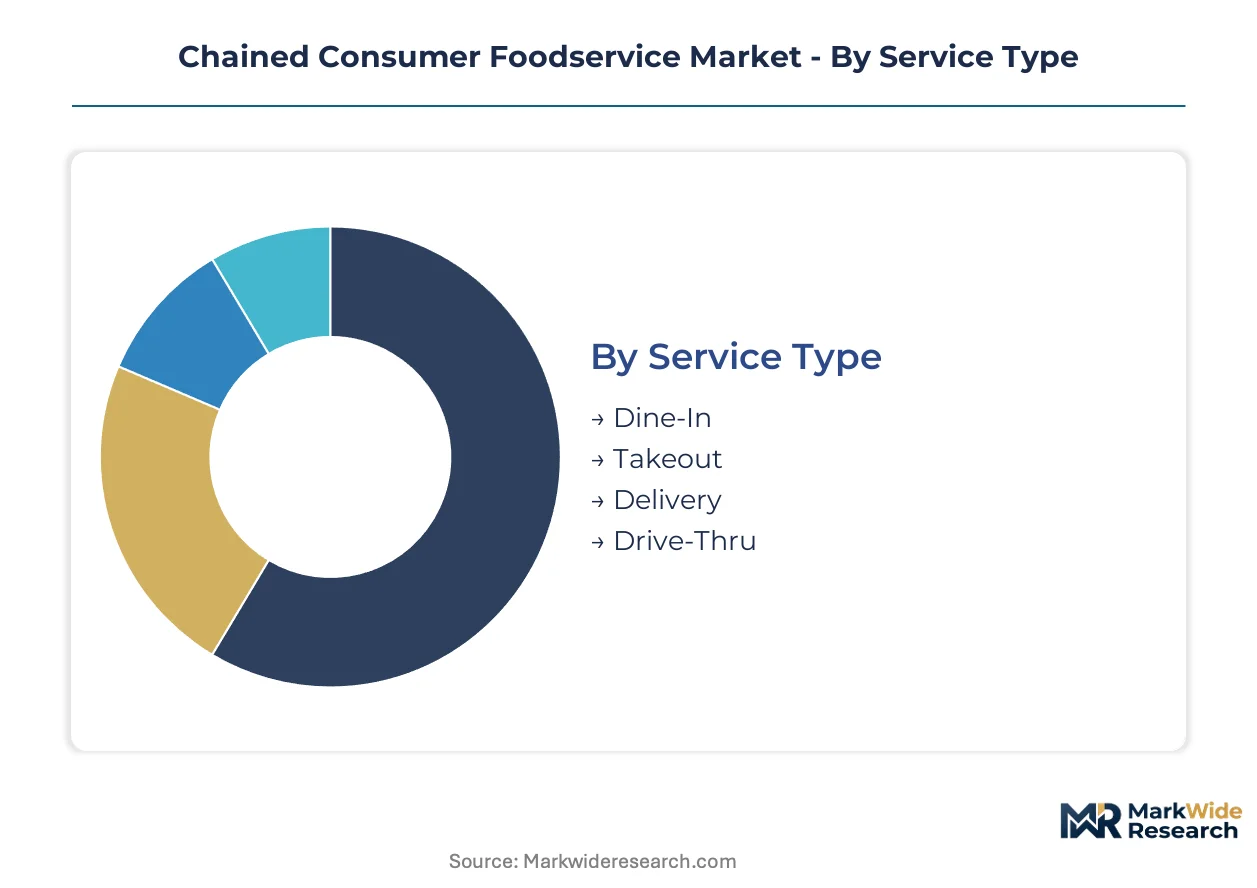
Segmentation in chained consumer foodservice exposes how operational format, product positioning, and customer occasion interact to determine capital allocation and site selection strategies. Operators must match service architecture to demographic density and consumption context.
Service Type:
Mature formats dominate suburban corridors while emerging modalities reshape urban penetration economics.
- Dine-In:Full-service floor operations with dedicated seating infrastructure and front-of-house labor deployment. Casual dining chains in China's tier-one cities retain stronger attachment rates here as social occasion anchor, though per-location throughput caps limit expansion velocity.
- Delivery:Kitchen-to-doorstep fulfillment through third-party platform integration or captive app ecosystems. Young adult demographics in dense urban clusters drive order frequency, with ghost kitchen infrastructure collapsing real estate requirements to pure production space.
- Takeout:Counter-service handoff without on-premise consumption, common in fast-casual and coffee shop formats. Starbucks leverages mobile order-ahead to compress wait times and reduce lobby congestion.
- Drive-Thru:Vehicle-based ordering and fulfillment via dedicated lane infrastructure. McDonald's sustains dominance through suburban real estate footprint optimized for commuter traffic patterns.
Drive-Thru handles the majority of throughput; Delivery is expanding most quickly on share.
Product Type:
Volume scale separates mass-market throughput models from premium yield architectures.
- Fast Food:Standardized menu items produced through batch-cooking processes with sub-180-second service targets. High-frequency, low-margin throughput models concentrate in US suburban corridors and emerging Indian tier-two cities.
- Casual Dining:Full-service experience with table service and extended dwell times. Chipotle's fresh-ingredient supply chain control exemplifies differentiation through customizable architecture rather than speed.
- Coffee Shop:Beverage-centric operations with workspace-oriented seating and WiFi infrastructure. Premium per-transaction yields support urban rent structures that exclude food-only concepts.
- Buffet:Self-service format with fixed-price access to rotating menu stations. Institutional and event end-use sustains residual demand despite pandemic-era hygiene sensitivity.
Fast Food captures the largest revenue pools; Coffee Shop delivers the steepest per-unit economics.
Customer Type:
Demographic targeting determines daypart strategy and menu complexity investment.
- Families:Multi-generational occasion-based demand concentrated in suburban dine-in and drive-thru formats. Value bundling and child-oriented menu items sustain visit frequency.
- Young Adults:Digital-native consumption through mobile ordering platforms, concentrated in delivery and coffee shop channels. China's tier-one cities exhibit the most pronounced platform integration.
- Seniors:Daypart-early demand with preference for familiar menu items and accessible seating. Loyalty program attachment exceeds other segments.
- Students:Price-sensitive volume with concentration near educational institutions. Limited-service formats with promotional pricing dominate capture.
Families generate the highest per-visit spend; Young Adults are gaining share fastest through digital channel migration.
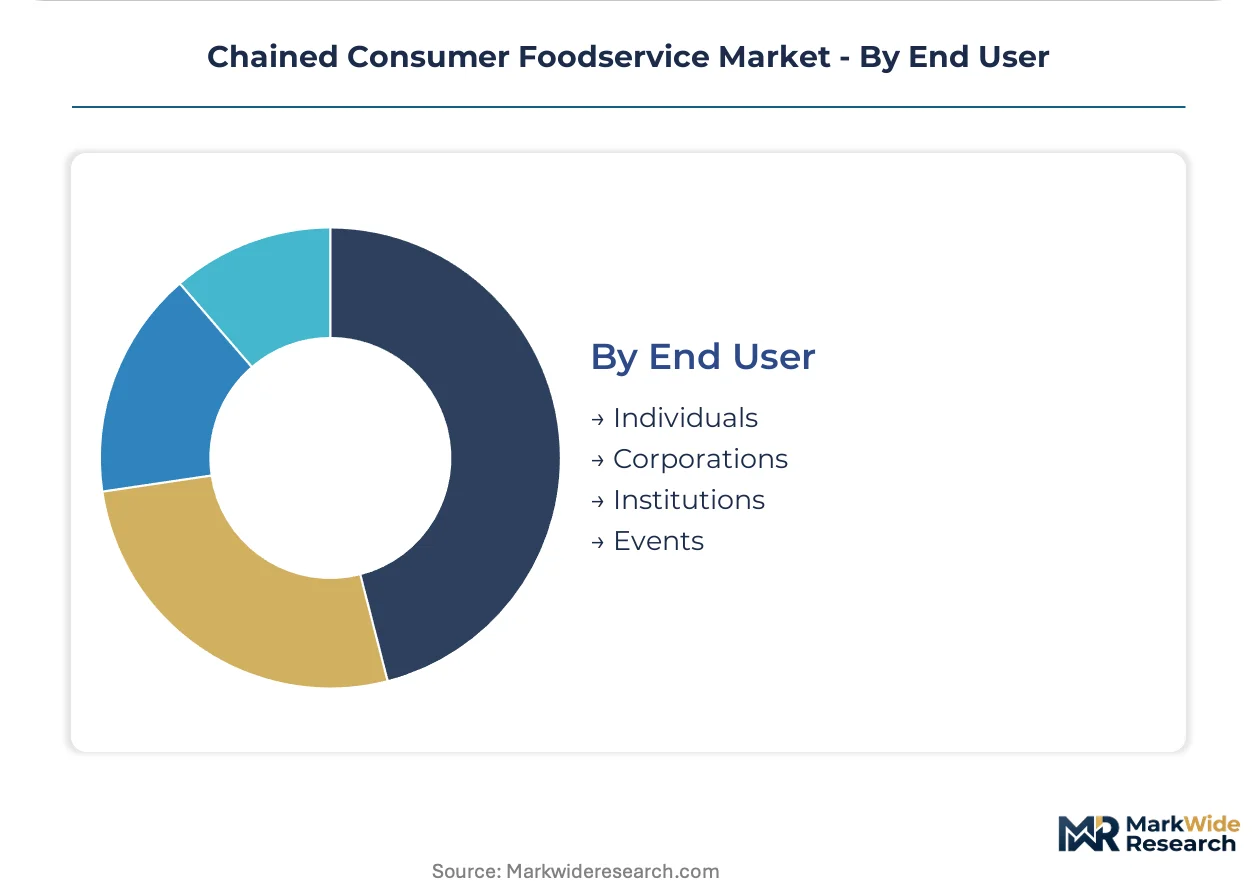
End User:
Occasion type separates individual discretionary spend from institutional procurement scale.
- Individuals:Single-transaction discretionary consumption across all service types. Mobile ordering infrastructure has collapsed friction for impulse and planned occasions alike.
- Corporations:Contracted catering and meeting services with volume guarantees and invoice-based settlement. Coffee shop chains capture recurring workplace procurement through account-based programs.
- Institutions:Schools, hospitals, and government facilities with nutritional compliance requirements and extended contract terms. Cold-chain logistics and food safety documentation intensity exceeds commercial standards.
- Events:Temporary demand spikes requiring scalable production and portable service architecture. Ghost kitchen networks enable rapid deployment without permanent footprint.
Individuals account for the transaction volume base; Corporations provide the most predictable revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US IRA energy incentives are reshaping kitchen equipment procurement economics, while EU Green Deal mandates accelerate sustainability reporting across European operations. China's tier-one cities concentrate delivery platform competition between Western and domestic chains.
United States
Suburban drive-thru corridors sustain McDonald's throughput dominance among commuter demographics. FDA food safety protocols and USDA nutritional labeling mandates dictate operational compliance burdens across multi-state operators. Texas and Florida metro corridors anchor ghost kitchen expansion as real estate costs in coastal cities pressure unit economics.
China
Young adult consumption in Shanghai and Beijing drives delivery volume through integrated app ecosystems. SAMR food safety regulations and dual carbon goals impose documentation requirements on cross-border supply chains. Yangtze River Delta manufacturing clusters supply kitchen automation equipment to domestic and Western chains alike.
Germany
Workspace-oriented coffee shop formats capture remote worker segments in Berlin and Munich urban cores. EFSA hygiene standards and EU Green Deal sustainability reporting requirements shape menu reformulation and packaging innovation strategies. Bavaria's food processing equipment sector supplies automated cooking systems to Central European operators.
India
Tier-two urbanization in Gujarat and Karnataka presents underpenetrated expansion opportunities for quick-service chains. FSSAI licensing mandates and state-level health department protocols create compliance friction for interstate operators. Mumbai and Delhi-NCR corridors concentrate existing chained foodservice infrastructure while secondary cities lag penetration rates.
United Kingdom
Premium coffee shop positioning through beverage innovation sustains Starbucks' London footprint against independent competitors. EFSA-aligned post-Brexit food standards and CSRD reporting requirements impose documentation burdens on supply chain transparency. Southeast England logistics clusters support cold-chain distribution to high-density urban catchments.
Chained Consumer Foodservice Market Competitive Environment
On the supply side, the industry is consolidating around scale-driven throughput models while fragmenting across specialized format niches. Global quick-service chains command suburban real estate corridors through drive-thru dominance, whereas regional coffee shop operators capture urban premium yields. Two strategic archetypes predominate: real estate-heavy format specialists optimizing for traffic patterns, and asset-light platform integrators leveraging third-party delivery infrastructure. Competitive moves concentrate on ghost kitchen network expansion and kitchen automation technology licensing.
Among North American quick-service operators, McDonald's, Starbucks, and Chipotle Mexican Grill exemplify divergent archetypes within the chained foodservice structure. McDonald's anchors suburban drive-thru economics through real estate footprint scale. Starbucks occupies the premium beverage and workspace-oriented format tier. Chipotle represents fast-casual differentiation through supply chain control and customizable menu architecture.
| Leading Market Players |
|---|
| Dunkin' |
| Domino's Pizza |
| McDonald's |
| Wendy's |
| Burger King |
| Starbucks |
| Taco Bell |
| Chipotle Mexican Grill |
| Subway |
| Others |
Value Chain & Pricing Dynamics
China's Yangtze River Delta manufacturing clusters for kitchen automation equipment concentrate production capacity for fryers, grills, and robotic assembly systems, anchoring margin capture for Western chains that outsource equipment procurement while domestic operators achieve cost advantages through localized supply relationships.
Pricing Analysis
Volume-discount tiering structures dominate equipment procurement contracts, with premium-mid-economy pricing differentiation separating cloud-native kitchen display systems from legacy hardware refreshes. Price differentiation hinges on certification grade — EFSA-aligned hygiene documentation commands 15-25% premiums — and customization level for franchise system integration. Cost compression in standard-tier equipment is intensifying because Yangtze Delta overcapacity feeds global distributor networks. Quick-service chains with 500+ unit footprints exhibit least price sensitivity; independent coffee shop operators show highest elasticity.
Supply Chain Analysis
Export-control regime friction around semiconductor components for IoT-enabled cooking systems limits flows of advanced sensors and edge-computing modules to certain jurisdictions. Geographic supply concentration centers on China for equipment fabrication, Germany for precision control systems, and the United States for cloud infrastructure software. Raw material dependencies span stainless steel grades, refrigerant gases, and food-grade packaging films. Single-source vulnerability in cold-chain compressor manufacturing creates exposure. Distribution runs through regional equipment lessors and direct OEM relationships with large chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chained consumer foodservice market is entering a cyclical recovery phase as post-pandemic occasion-based dining normalizes and urban office occupancy rates stabilize commuter traffic patterns.
For Market Incumbents: Harden drive-thru throughput dominance through dynamic menu board deployment and predictive kitchen systems that compress ticket-to-handoff times. Consolidate supplier bases to meet EFSA blockchain-traceable lot documentation requirements without fragmenting procurement overhead. Ghost kitchen network expansion remains the priority lever against delivery-platform disintermediation.
For New Entrants and Emerging Players: Build out India's tier-two urban corridors in Gujarat and Karnataka where chained penetration lags metropolitan benchmarks by 40-60%. India's secondary cities present the most penetrable geography for quick-service format introduction. Anchor go-to-market strategy through delivery-exclusive menu architecture rather than dine-in footprint investment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fast-casual platforms that consolidated during pandemic-era distress but now require growth capital for automation retrofit. Long-term viability over a 5-10 year window favors operators with captive supply chain control and multi-channel service type flexibility. Watch kitchen automation technology licensing velocity as the inflection signal for margin expansion sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Network Expansion | Collapses real estate requirements to pure production space in dense urban clusters. |
| Kitchen Automation Technology Licensing | Enables franchise systems to standardize batch-cooking processes without capital intensity. |
| Delivery Platform Integration | Connects legacy POS infrastructure to third-party APIs through middleware investment. |
| Sustainability Certification Program | Aligns European operations with EU Green Deal supply chain transparency mandates. |
| Workspace-Oriented Format Rollout | Captures remote worker segments through WiFi infrastructure and extended dwell-time design. |
Study Parameters
A standing panel of quick-service franchise operations directors, supply chain procurement leads, kitchen equipment OEM technical sales heads, and third-party delivery platform account managers provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA food safety guidance documents, EFSA hygiene standard updates, SAMR regulatory circulars, FSSAI licensing protocols, and SEC 10-K filings from publicly traded operators. Bottom-up unit economics modeling and top-down market sizing triangulation anchored value projections.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning service type, product positioning tier, customer demographic, and end-use occasion. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated urbanization velocity in India's tier-two cities, delivery platform commission rate evolution, and kitchen automation equipment replacement cycles.
Stress conditions across commodity protein pricing, refrigerated transport energy costs, and local health department inspection variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about channel preference stabilization and labor cost trajectories. Material shifts in FDA food safety protocol stringency or EU Green Deal reporting timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
India Online Grocery Market
Food Service
Vietnam Food Service Market
Food Service
Kamado Grill Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Food Contract Manufacturing Market
Food Service
Integrated Stove Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Self-Heating Hot Pot Market
Food Service
United States Food Truck Market
Food Service
Commercial Bar Supplies Market
Food Service
Sandwich Toasters Market
Food Service
Personal Chef Services Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Shaker Bottles Market
Food Service
United States Cafes & Bars Market