
 China Food Service Market | 2026-2036
China Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Service Market Insights
Corporate cafeteria outsourcing from technology campuses is realigning procurement patterns across tier-one Chinese cities. Yum China Holdings anchors its position through centralized supply chain control over poultry and produce sourcing. Haidilao International Holding differentiates via in-house production of soup bases and robotic kitchen automation. Meituan leverages its super-app ecosystem to dominate last-mile delivery logistics and merchant SaaS penetration.
China food service encompasses commercial preparation and sale of ready-to-consume meals through organized outlets, governed by GB food safety standards covering temperature control, additive limits, and traceability documentation from farm to table. The sector serves urban consumption, workplace sustenance, and social dining occasions across a population exceeding four hundred million middle-income consumers. Fast food and online delivery command the largest volume pools, while fine dining captures concentrated margin in Shanghai and Beijing. Cafes and catering segments exhibit the fastest structural expansion, driven by hybrid work normalization and campus outsourcing trends.
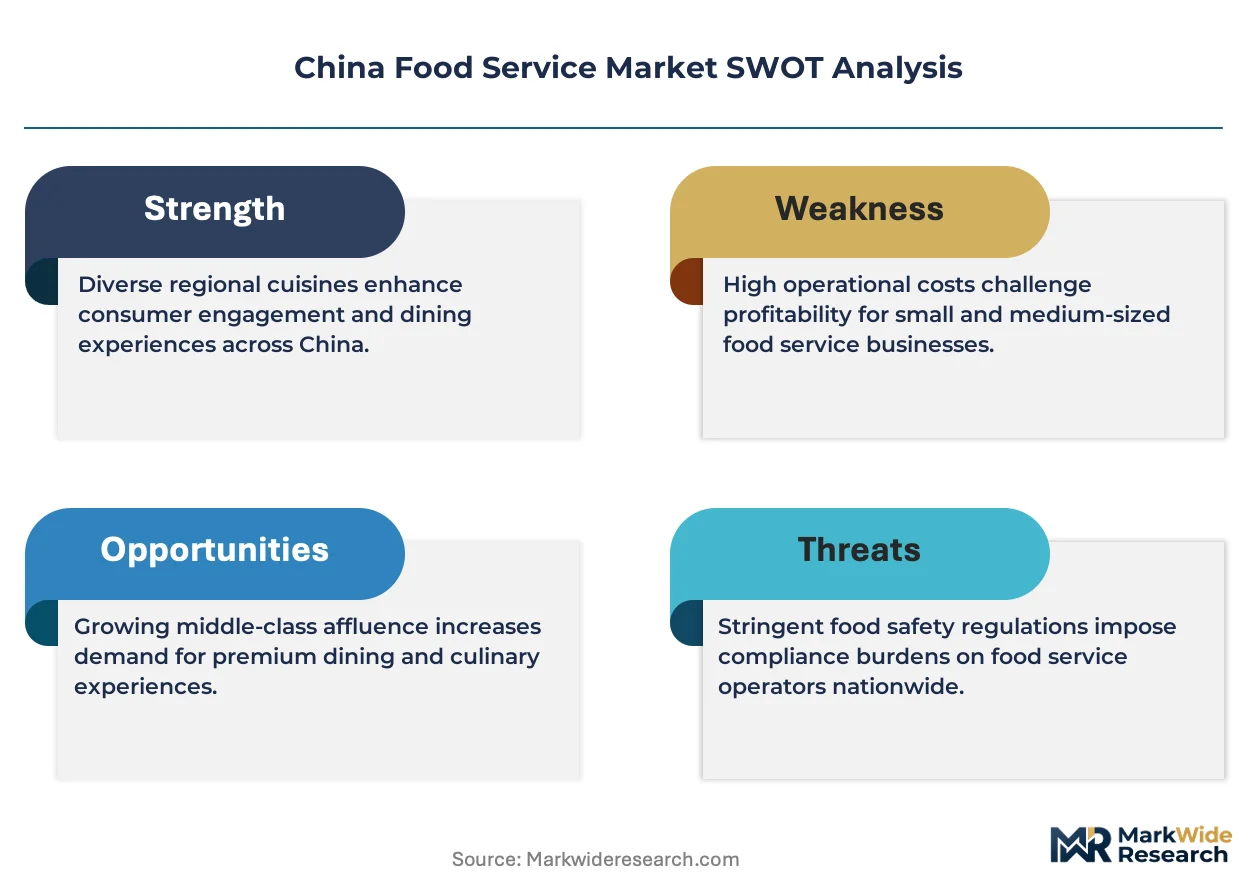
SAMR enforces food safety compliance through licensing audits and real-time kitchen monitoring mandates, while NHC digitization protocols require blockchain-enabled ingredient traceability for chain operators above fifty outlets. GB standards on oil recycling frequency and additive disclosure directly shape kitchen equipment specifications and supplier qualification criteria. Stakeholders must monitor regulatory pacing between national rollout and provincial implementation variance to calibrate capital deployment across multi-city expansion plans.
Market Dynamics
Centralized procurement from technology campuses is compressing supplier margins while forcing kitchen compliance infrastructure upgrades under NHC digitization mandates.
Growth Catalysts
- Campus Outsourcing Mandates:Technology corridors in Shenzhen and Beijing are consolidating cafeteria operations under single-vendor contracts, creating volume concentration for qualified operators.
- GB Standards Enforcement:SAMR's real-time kitchen monitoring requirements are accelerating equipment replacement cycles and favoring capitalized chains over independent operators.
- Dual Carbon Goals:MEE energy efficiency standards for commercial kitchens are driving electric equipment adoption and renewable energy integration in new outlet construction.
Market Restraints
- Poultry Supply Concentration:White-feather broiler processing remains dominated by three integrated suppliers, creating input cost volatility during disease outbreaks.
- Blockchain Traceability Costs:NHC mandates for ingredient documentation above fifty outlets impose fixed compliance burdens that disproportionately strain mid-size regional chains.
- Real Estate Escalation:Tier-one city commercial rents in Shanghai's core districts consume disproportionate revenue share, forcing outlet relocation to peripheral zones.
Strategic Opportunities
- Robotic Kitchen Integration:Automated stir-fry stations and unmanned serving systems are converging with labor-scarce markets in Chengdu and Hangzhou.
- Central Kitchen Networks:Pre-processing facilities in suburban industrial zones enable same-day delivery to multiple urban outlets, reducing per-unit preparation labor.
- Catering SaaS Platforms:Campus procurement portals are opening API integrations for inventory management and nutritional compliance reporting.
Industry Challenges
- Certified Chef Scarcity:Food safety supervisor credentials required under SAMR licensing face persistent training pipeline gaps in secondary cities.
- Legacy POS Migration:Older outlet networks struggle with real-time data transmission requirements for NHC compliance dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Service Market |
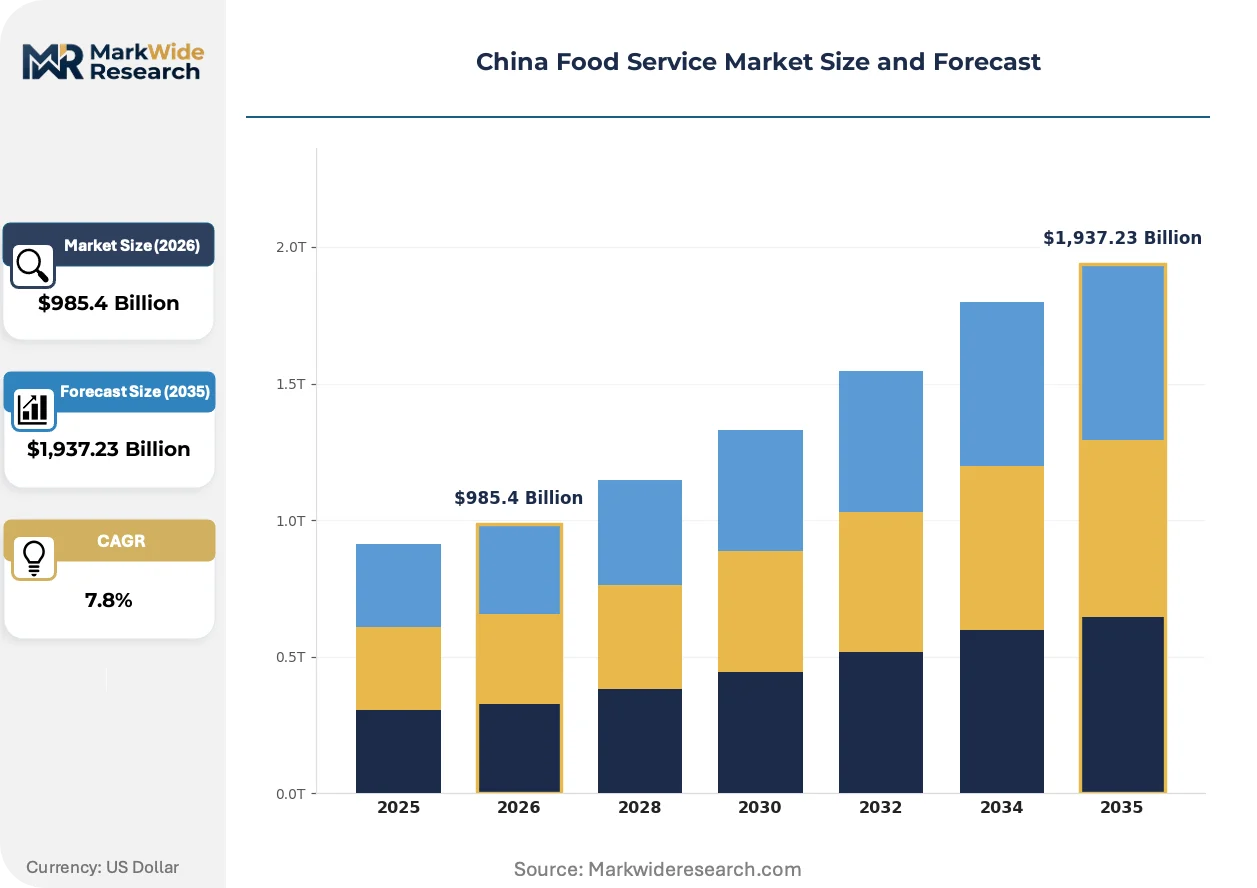
| Market Size in 2026 | $985.4 Billion |
| Market Size in 2035 | $1,937.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Cafes Distribution Channel: Online Delivery, Takeaway, Dine-in, Catering End User: Families, Students, Professionals, Tourists Menu Type: Vegetarian, Non-Vegetarian, Vegan, Gluten-Free |
| Companies Covered | Luckin Coffee, Meituan, Yum China Holdings, Jiumaojiu International Holdings, China Quanjude (Group), McDonald's Corporation, Haidilao International Holding, Guangzhou Restaurant Group, Starbucks Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Service Market Trends and Innovations
Kitchen automation and regulatory digitization are compressing operational timelines while reshaping procurement relationships between food service operators and technology infrastructure providers.
Computer vision systems for cooking process monitoring are converging with temperature logging hardware to create unified compliance dashboards. Campus operators in Shenzhen's Nanshan district are deploying these integrated systems to satisfy SAMR audit requirements without manual documentation. The technology is converging with blockchain traceability platforms to compress compliance verification from days to minutes.
NHC digitization protocols now mandate blockchain-enabled ingredient traceability for chain operators above fifty outlets. This policy is forcing supplier qualification systems to integrate with government monitoring platforms or face procurement exclusion. Full-service chains in Shanghai and Beijing are responding by consolidating vendor lists to reduce documentation complexity.
Corporate cafeteria contracts are migrating from per-meal pricing to fixed monthly service fees with performance guarantees. Technology campuses in Hangzhou and Chengdu are leading this shift, replacing transactional relationships with outcome-based partnerships. Procurement teams now prioritize operators with integrated nutrition reporting and dietary accommodation capabilities over unit cost minimization.
China Food Service Market Segmentation
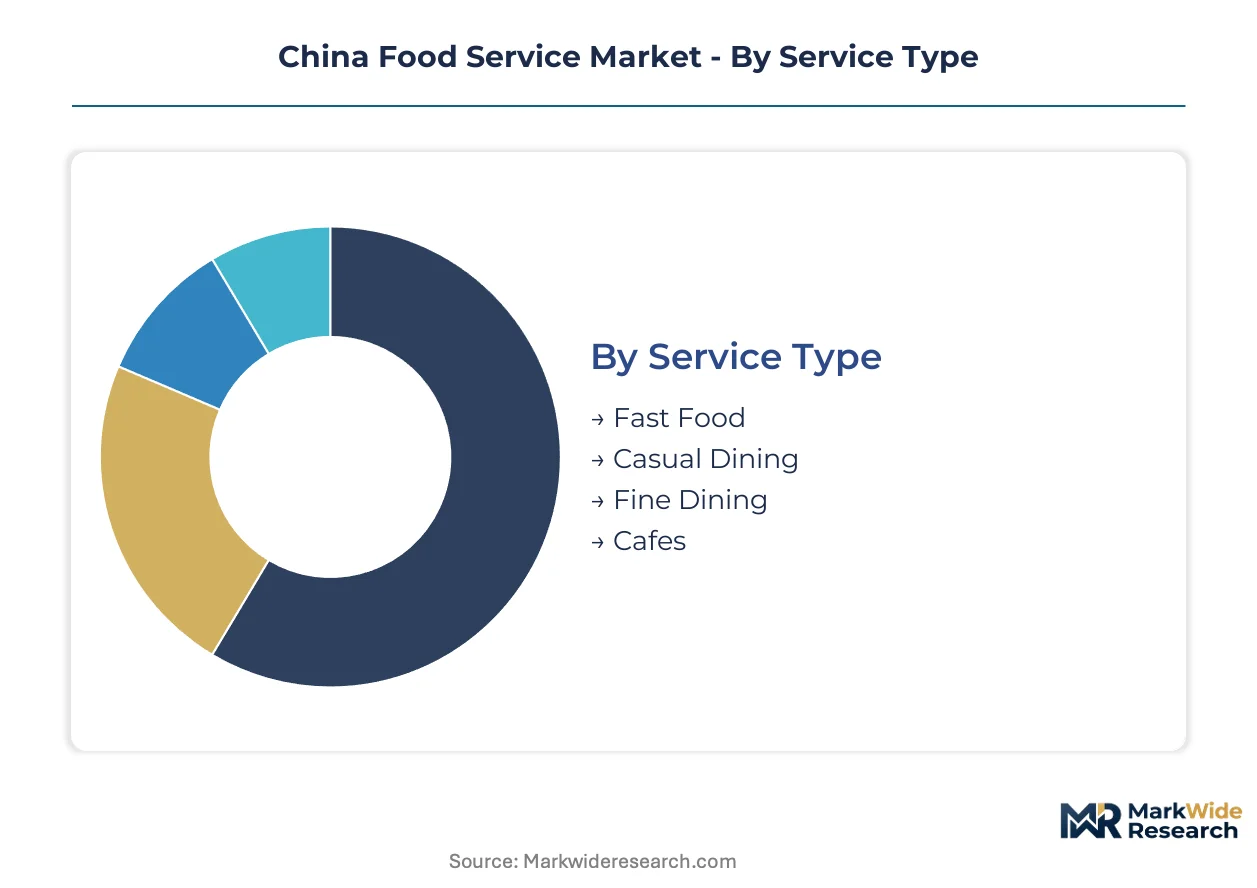
Segmentation reveals how procurement concentration and regulatory digitization are fragmenting competitive arenas across China's food service landscape. Operators must align capital deployment with distinct compliance burdens and volume dynamics in each category.
Service Type:
Format specifications determine kitchen automation feasibility and labor intensity thresholds across urban deployment zones.
- Fast Food:Standardized production protocols and limited menu breadth enable robotic kitchen integration at scale. Demand clusters in Shenzhen Nanshan technology corridors and Shanghai subway-adjacent districts under corporate campus outsourcing contracts.
- Casual Dining:Moderate table service combined with flexible seating configurations targets middle-income families in Hangzhou and Chengdu mixed-use developments. NHC blockchain traceability mandates favor capitalized chains with centralized procurement systems over independent operators.
- Fine Dining:Chef-driven preparation and premium ingredient sourcing concentrate in Shanghai Lujiazui and Beijing Sanlitun, where real estate costs consume disproportionate revenue share.
- Cafes:Hybrid work normalization is accelerating outlet expansion in Shanghai Jing'an and Guangzhou Tianhe business districts.
Fast Food leads on scale; Cafes lead on momentum.
Distribution Channel:
Logistics infrastructure requirements separate capital-intensive platforms from asset-light service models.
- Online Delivery:Super-app ecosystems dominate last-mile logistics through algorithmic rider dispatch and merchant SaaS penetration. Volume concentrates in tier-one city dense residential zones where delivery radius economics favor cloud kitchen aggregation.
- Takeaway:Packaging specifications under GB standards and temperature control mandates shape equipment investment for urban outlet networks.
- Dine-in:SAMR real-time kitchen monitoring requirements accelerate POS replacement cycles in legacy outlet portfolios.
- Catering:Fixed monthly service fee contracts are displacing per-meal pricing across Beijing and Shenzhen technology campuses, prioritizing operators with integrated nutrition reporting capabilities.
Online Delivery commands volume concentration; Catering exhibits steepest expansion trajectory.
End User:
Consumption occasion patterns dictate menu engineering and service format selection across demographic cohorts.
- Families:Multi-generational dining occasions favor spacious seating configurations and dietary accommodation protocols in suburban Shanghai and Beijing shopping mall developments.
- Students:Price-sensitive demand concentrates near university clusters in Wuhan and Xi'an, where campus outsourcing mandates are consolidating cafeteria operations under single-vendor contracts.
- Professionals:Time-compressed lunch occasions in Shanghai Pudong and Shenzhen Futian central business districts favor grab-and-go formats and pre-ordering platforms.
- Tourists:Experience-driven dining in Beijing hutong districts and Shanghai Bund heritage zones supports premium positioning for regional cuisine specialists.
Professionals anchor weekday revenue stability; Students represent volume concentration under procurement reform.
Menu Type:
Ingredient specification tiers create distinct supply chain qualification barriers and margin structures.
- Vegetarian:Plant-forward formulations require dedicated preparation zones and cross-contamination protocols under GB food safety standards, favoring operators with central kitchen networks.
- Non-Vegetarian:White-feather broiler supply concentration among three integrated processors creates input cost volatility during disease outbreaks, compressing margins for poultry-dependent chains.
- Vegan:Strict elimination of animal derivatives demands supplier certification systems that integrate with NHC blockchain traceability platforms for chains above fifty outlets.
- Gluten-Free:Specialized ingredient sourcing and preparation protocols target health-conscious professionals in Shanghai and Beijing, where dietary accommodation capabilities influence corporate catering contract awards.
Non-Vegetarian dominates volume throughput; Vegan is gaining share fastest on health positioning and regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta anchors national food service procurement concentration through Shanghai's central business district and Hangzhou technology corridors, where corporate cafeteria outsourcing mandates are compressing supplier margins while accelerating kitchen compliance infrastructure deployment.
Shanghai Municipality
Lujiazui financial district and Jing'an business zone drive premium dining demand from multinational headquarters and professional services firms. SAMR enforces real-time kitchen monitoring requirements through licensing audits that accelerate POS replacement cycles in legacy outlet portfolios. Cloud kitchen aggregation concentrates in dense residential zones across Pudong and Minhang districts.
Beijing-Tianjin-Hebei
Technology campuses in Zhongguancun and Yizhuang corridors are consolidating cafeteria operations under single-vendor contracts with fixed monthly service fee structures. NHC digitization protocols mandate blockchain-enabled ingredient traceability for chain operators above fifty outlets. Sanlitun and Guomao districts concentrate fine dining margin capture.
Guangdong Province
Pearl River Delta manufacturing belts and Shenzhen Nanshan technology corridor generate concentrated demand for automated food preparation and unmanned serving systems. MEE energy efficiency standards for commercial kitchens drive electric equipment adoption in new outlet construction. Guangzhou Tianhe district anchors cafe expansion from hybrid work normalization.
Sichuan-Chongqing
Chengdu's mixed-use developments and university clusters create demand for dietary accommodation protocols and price-sensitive campus dining. Certified chef scarcity under SAMR licensing requirements faces persistent training pipeline gaps. Robotic kitchen integration trials converge with labor-scarce markets in suburban industrial zones.
Zhejiang Province
Hangzhou technology campuses lead the shift from per-meal pricing to outcome-based catering partnerships with performance guarantees. Central kitchen networks in Xiaoshan and Yuhang industrial zones enable same-day delivery to multiple urban outlets. Procurement portals open API integrations for inventory management and nutritional compliance reporting.
China Food Service Market Competitive Landscape
Vertical integration dominates the current landscape as operators consolidate upstream control over poultry processing and soup base production. The market structure tiers between capitalized national chains with centralized procurement systems and regional independents struggling with NHC blockchain traceability compliance costs. Three archetypes anchor competitive positioning: super-app ecosystem platforms, automated kitchen specialists, and heritage restaurant groups with captive supply networks. M&A activity and central kitchen capacity expansion represent the dominant competitive moves as operators defend margin position against input cost volatility.
Within the platform ecosystem tier, Meituan exemplifies super-app dominance through algorithmic logistics and merchant SaaS penetration. Yum China Holdings and Haidilao International Holding occupy positions as capitalized chains with in-house production capabilities and robotic automation deployments. These three entities represent distinct strategic responses to regulatory digitization and procurement concentration pressures.
| Leading Market Players |
|---|
| Luckin Coffee |
| Meituan |
| Yum China Holdings |
| Jiumaojiu International Holdings |
| China Quanjude (Group) |
| McDonald's Corporation |
| Haidilao International Holding |
| Guangzhou Restaurant Group |
| Starbucks Corporation |
| Others |
Pricing and Supply Chain Analysis
Robotic kitchen automation in Shenzhen Nanshan and Hangzhou technology corridors is compressing labor cost differentials while concentrating procurement power among operators with capitalized equipment budgets. This production-method transition simultaneously elevates fixed cost thresholds and consolidates supplier relationships toward vendors with integrated compliance documentation systems.
Pricing Analysis
Input-cost pass-through from white-feather broiler supply concentration dominates margin dynamics for poultry-dependent chains. Three-tier pricing structure across premium, standard, and economy levels separates Haidilao's chef-driven positioning from Yum China's standardized formats and campus cafeteria fixed-fee contracts. Cost compression in the mid-tier is intensifying because NHC blockchain traceability mandates impose fixed compliance burdens regardless of outlet scale. Students near Wuhan and Xi'an university clusters exhibit highest price sensitivity; multinational headquarters in Shanghai Lujiazui show lowest.
Supply Chain Analysis
Certification gating under SAMR licensing and NHC digitization protocols is disqualifying unqualified suppliers from procurement lists for chains above fifty outlets. Geographic supply concentration centers on domestic white-feather broiler processors, Shandong vegetable production belts, and Guangdong equipment manufacturers. Raw material dependencies include poultry, cooking oils, and automated kitchen hardware components. Single-source vulnerability in broiler processing creates input cost volatility during disease outbreaks. Distribution runs through centralized procurement portals opening API integrations for inventory management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China food service has entered a late-cycle quality phase where corporate cafeteria outsourcing mandates favor operators with integrated nutrition reporting over unit cost minimization. This demand-shift toward premium specifications rewards capitalized chains with compliance infrastructure already deployed.
For Market Incumbents: Deploy central kitchen network expansion as the priority lever. Incumbents should consolidate vendor lists to reduce NHC blockchain documentation complexity while adding suburban pre-processing capacity in Xiaoshan and Yuhang industrial zones. Robotic kitchen automation trials in Chengdu and Hangzhou defend against labor scarcity in secondary cities. Campus procurement portal API integration captures fixed-fee contract volume from technology corridor outsourcing mandates.
For New Entrants and Emerging Players: Campus procurement SaaS platforms offer the most penetrable entry vector for new operators lacking legacy outlet networks. White-space targets include dietary accommodation protocols for gluten-free and vegan segments in Shanghai and Beijing corporate catering. Hangzhou technology campuses lead the shift from per-meal pricing to outcome-based partnerships, creating openings for operators with integrated compliance reporting. Direct API integration with campus inventory management systems provides the critical go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for regional chains with thirty to forty-nine outlets because NHC digitization thresholds at fifty outlets create acquisition targets facing imminent compliance cost cliffs. Long-term viability favors operators with backward integration into soup base production or captive poultry supply agreements. The signal to watch is SAMR enforcement pacing between national rollout and provincial implementation variance, which determines capital deployment timing for multi-city expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Network Expansion | Xiaoshan and Yuhang industrial zone facilities enable same-day delivery to multiple urban outlets. |
| Robotic Kitchen Integration | Automated stir-fry stations in Chengdu and Hangzhou address certified chef scarcity under SAMR licensing. |
| Campus Procurement Portal API Integration | Fixed monthly service fee contracts in Hangzhou and Shenzhen prioritize operators with nutritional compliance reporting. |
| Blockchain Traceability Platform Deployment | NHC mandates for chains above fifty outlets require supplier qualification systems integrating with government monitoring. |
| Electric Equipment Adoption | MEE energy efficiency standards for commercial kitchens drive renewable energy integration in new outlet construction. |
Research Methodology
Bottom-up campus procurement modeling reconciled against top-down poultry supply tracking forms the analytical core of this study. Primary interviews with food safety supervisors, central kitchen operations directors, campus procurement officers, and SAMR compliance consultants combined with secondary validation from customs records, GB standards documentation, and NHC digitization protocol filings. Top-down triangulation against Meituan delivery volume disclosures and Yum China outlet expansion filings ensures cross-verification.
Input-output matrix framing connects outlet deployment assumptions to ingredient throughput requirements across service type, distribution channel, and menu type dimensions. Segmentation modeling spans fast food, casual dining, fine dining, and cafe formats alongside online delivery, takeaway, dine-in, and catering channels. CAGRs were derived from elasticity-adjusted demand projections tied to middle-income consumer expansion and technology campus outsourcing penetration. Forecast inputs include SAMR licensing audit frequency and NHC blockchain mandate rollout pacing.
The model assumes a particular technology adoption path; alternative pathways for robotic kitchen automation would alter the outlook if labor scarcity resolves faster than equipment cost curves decline. Forecasts reflect assumptions about regulatory enforcement consistency and white-feather broiler supply stability. A model refresh is warranted upon material change in SAMR real-time kitchen monitoring mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Restaurant Rangers Market
Food Service
Galley Equipment Market
Food Service
North America Cafes & Bars Market
Food Service
Food Logistics Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Contract Catering Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Online Food Delivery Market
Food Service
Tabletop Pizza Oven Market
Food Service
Peer-To-Peer Dining Market
Food Service
Brazil Foodservice Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
United States Quick Service Restaurants Market
Food Service
Global Cafe and Bars Market
Food Service
West Africa Food Services Market
Food Service
United States Smokeless Indoor Grills Market