
 Asia Pacific Food Platform-To-Consumer Delivery Market | 2026-2036
Asia Pacific Food Platform-To-Consumer Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Food Platform-To-Consumer Delivery Market Outlook
Asset-light franchising and rider fleet leasing is reconfiguring capital requirements for new entrants across Southeast Asia. Meituan Inc. leverages its super-app infrastructure to dominate on-demand meal logistics in China. GrabFood anchors its multi-service ecosystem across Singapore, Malaysia, and Indonesia, while Delivery Hero SE competes through localized brand portfolios rather than unified platforms.
Asia Pacific Food Platform-To-Consumer Delivery encompasses digital intermediaries that match prepared food, meal kits, or grocery inventory to end consumers through algorithmic dispatch and last-mile rider networks, typically operating on commission or delivery-fee revenue models with average fulfillment windows under 45 minutes. The service type dimension spans meal kits, grocery delivery, ready-to-eat, and fresh produce, with ready-to-eat commanding the dominant transaction volume due to impulse-driven urban consumption patterns. Customer type segments include households, restaurants, catering services, and offices, where household demand generates the highest frequency but restaurant-to-consumer intermediation yields superior per-order margins through commission stacking.
India's FSSAI mandates hygiene audits for cloud kitchens, while China's SAMR enforces antitrust scrutiny on platform commission rates and rider welfare obligations. Japan's METI guidelines on gig economy classification further shape labor cost structures for cross-border operators. Stakeholders must monitor how divergent national approaches to rider employment status reshape unit economics and platform scalability across the region.
Market Dynamics
Algorithmic dispatch systems and gig-economy labor classification disputes are compressing fulfillment windows while inflating compliance costs across Asia Pacific's food delivery networks. Cloud kitchen proliferation in dense urban corridors is decoupling food preparation from restaurant real estate, fundamentally altering capital deployment patterns for new market entrants.
Growth Catalysts
- Dual-income household density:Metropolitan Seoul, Mumbai, and Bangkok generate recurring order frequency above five transactions weekly per active user. Time-constrained professionals treat platform delivery as infrastructure rather than discretionary spend.
- FSSAI hygiene audit mandates:India's food safety regulator forces standardization across cloud kitchen operations, accelerating consolidation toward compliant operators with centralized supply chains.
- Super-app convergence:Ride-hailing platforms integrating meal delivery leverage existing rider networks and payment rails to reduce customer acquisition costs below standalone competitors.
Market Restraints
- Rider welfare obligations:China's SAMR mandates social insurance contributions for gig workers, elevating per-delivery labor costs by fifteen to twenty percent in tier-one cities.
- Input cost volatility:Fluctuating fuel prices and two-wheeler lease rates expose fleet-dependent operators to margin compression without pricing power to pass through.
- Regulatory fragmentation:Divergent national approaches to platform employment classification prevent standardized operating models across Southeast Asian markets.
Strategic Opportunities
- Tier-two Indian urban corridors:Cities including Jaipur, Lucknow, and Indore show penetration gaps exceeding forty percent versus Mumbai and Bangalore, offering first-mover expansion potential.
- Meal kit subscription models:Pre-portioned ingredient delivery targeting health-conscious households in Tokyo and Sydney bypasses restaurant commission structures entirely.
- Japan's METI gig economy guidelines:Clearer contractor classification rules reduce litigation risk for platforms deploying hybrid employment models.
Industry Challenges
- Real-time inventory synchronization:Cloud kitchens must integrate POS, delivery aggregator, and procurement systems without standardized APIs, causing fulfillment failures during peak demand windows.
- Cross-border data localization:Australia's TGA and China's SAMR impose conflicting requirements on consumer transaction records, complicating regional platform architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Food Platform-To-Consumer Delivery Market |
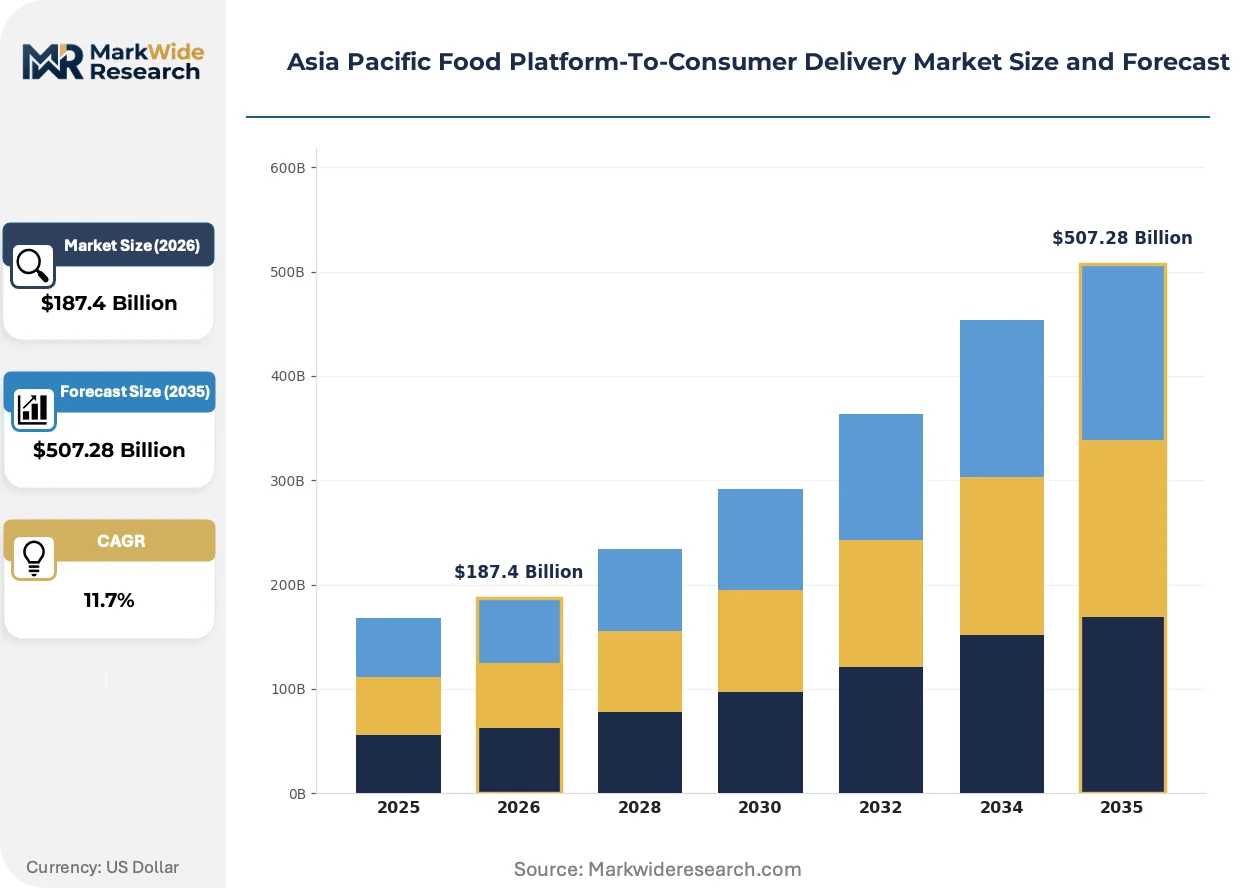
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Kits, Grocery Delivery, Ready-to-Eat, Fresh Produce Customer Type: Households, Restaurants, Catering Services, Offices Delivery Model: On-Demand, Scheduled, Subscription, Bulk Delivery Payment Method: Credit Card, Mobile Wallet, Cash on Delivery, Bank Transfer |
| Companies Covered | Meituan Inc., ELEME Inc, GrabFood, Zomato Limited, Swiggy, Foodpanda GmbH, Delivery Hero SE, Uber Eats, DoorDash Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Food Platform-To-Consumer Delivery Market Strategic Shifts
Dark store networks and predictive demand algorithms are compressing the gap between order placement and doorstep arrival, redefining consumer expectations across Asia Pacific metropolitan zones.
AI-powered demand forecasting is hybridizing historical order patterns with real-time weather and event data to pre-position inventory at neighborhood dark stores. Quick-commerce operators in Singapore and Jakarta now stock prepared meals alongside groceries, collapsing the distinction between restaurant delivery and convenience retail. This convergence is compressing average fulfillment windows toward twenty-minute benchmarks.
China's SAMR antitrust scrutiny on platform commission rates is forcing revenue model diversification away from pure restaurant take rates. Aggregators now monetize through advertising slots, payment float, and logistics-as-a-service to enterprise clients. Cloud kitchen operators in Shanghai and Shenzhen face margin pressure as capped commissions limit pass-through of rising compliance costs.
Subscription-based meal planning is displacing impulse-driven ordering among health-conscious households in Tokyo, Melbourne, and Bangalore. Platforms offering weekly curated menus with dietary customization capture higher lifetime value than transactional competitors. This behavioral shift concentrates revenue predictability with operators possessing robust culinary R&D capabilities rather than pure logistics specialists.
Asia Pacific Food Platform-To-Consumer Delivery Market Segmentation
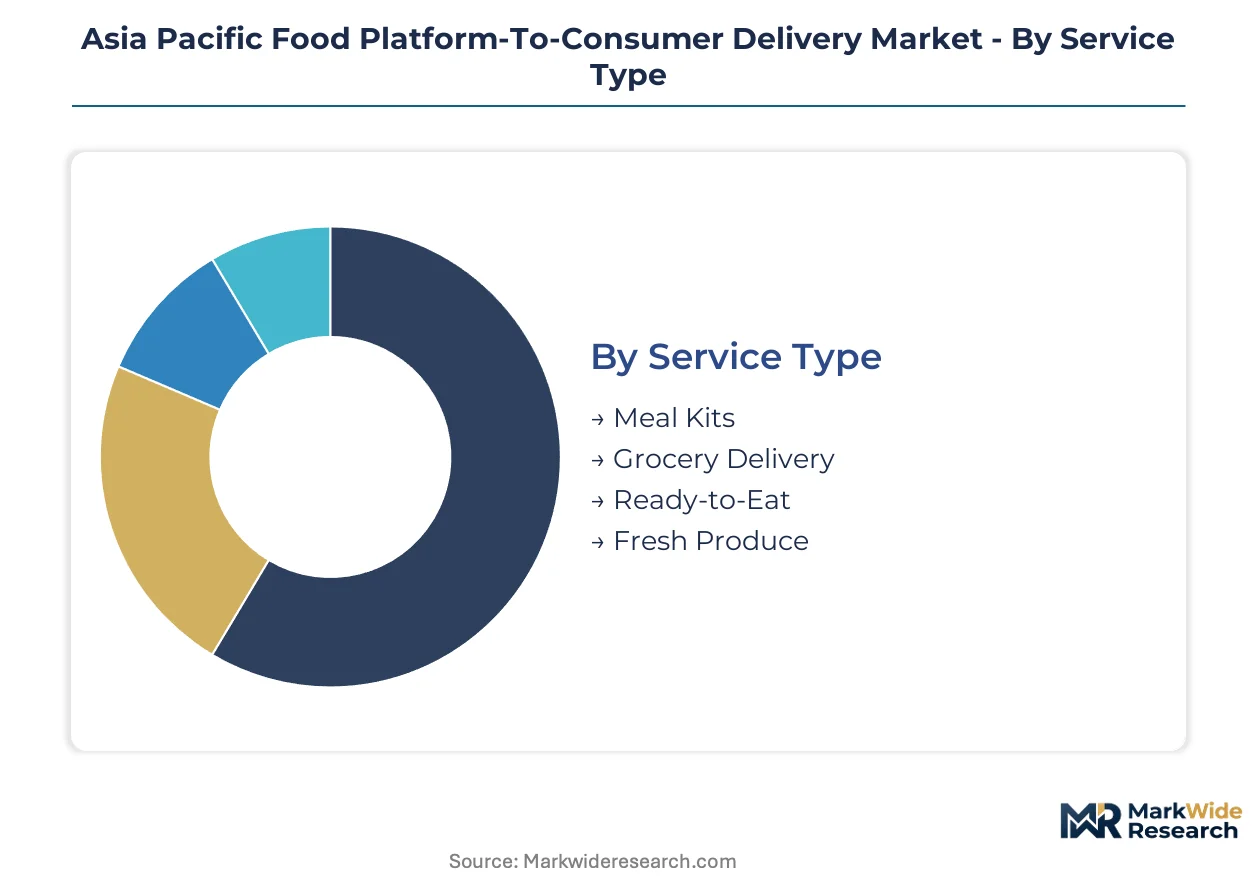
Platform operators in Asia Pacific configure service portfolios around distinct fulfillment economics and customer lifetime value profiles. Each segment demands specialized rider network density, inventory positioning, and payment infrastructure investments that reshape capital allocation across urban corridors.
Service Type:
After-sales service intensity varies sharply across preparation formats, with perishable handling requirements and quality dispute rates driving operational complexity.
- Ready-to-Eat:Prepared meals dispatched from restaurant kitchens or cloud facilities dominate transaction velocity across Seoul, Mumbai, and Bangkok metropolitan zones. Urban professionals treat this category as infrastructure rather than discretionary spend, generating recurring order frequency above five transactions weekly per active user.
- Meal Kits:Pre-portioned ingredient bundles with recipe instructions target health-conscious households in Tokyo and Sydney. Subscription-based meal planning captures higher lifetime value than transactional competitors, concentrating revenue predictability with operators possessing robust culinary R&D capabilities.
- Grocery Delivery:Supermarket inventory intermediation requires real-time POS synchronization and temperature-controlled logistics chains.
- Fresh Produce:Farm-to-door fruit and vegetable delivery demands rapid fulfillment windows to prevent spoilage losses.
By volume, Ready-to-Eat leads. By growth pace, Meal Kits is climbing the fastest.
Customer Type:
Cost tier stratification separates high-frequency household demand from enterprise accounts yielding superior per-order margins through commission stacking.
- Households:Individual consumers generate the highest order frequency across metropolitan India, where Swiggy and Zomato compete for share among time-constrained professionals. Dual-income household density in tier-one cities creates recurring demand patterns that stabilize rider fleet utilization.
- Restaurants:Foodservice intermediation yields superior per-order margins through commission stacking on prepared meal transactions. Cloud kitchen proliferation in dense urban corridors decouples food preparation from restaurant real estate, fundamentally altering capital deployment patterns.
- Catering Services:Event-based bulk orders require scheduled delivery windows and specialized handling equipment.
- Offices:Corporate meal programs concentrate demand during narrow lunchtime windows, straining dispatch algorithms.
Households generate the highest order count. Restaurants deliver the steepest margin expansion trajectory.
Delivery Model:
Application flexibility determines platform scalability across markets with divergent infrastructure maturity and consumer preference patterns.
- On-Demand:Immediate fulfillment within 45-minute windows commands premium positioning in China, where Meituan's super-app infrastructure dominates meal logistics. Algorithmic dispatch systems compress fulfillment windows while elevating rider network density requirements.
- Subscription:Recurring weekly or monthly delivery commitments reduce customer acquisition costs and stabilize demand forecasting for meal kit operators. Platforms offering curated menus with dietary customization capture predictable revenue streams in Tokyo and Melbourne.
- Scheduled:Advance-booked delivery slots optimize fleet utilization during off-peak hours.
- Bulk Delivery:Aggregated orders for corporate or institutional clients achieve economies in last-mile logistics.
On-Demand captures the dominant transaction share. Subscription is gaining share fastest among health-conscious urban demographics.
Payment Method:
Geography determines payment infrastructure adoption, with mobile-first markets leapfrogging card-based systems dominant in developed economies.
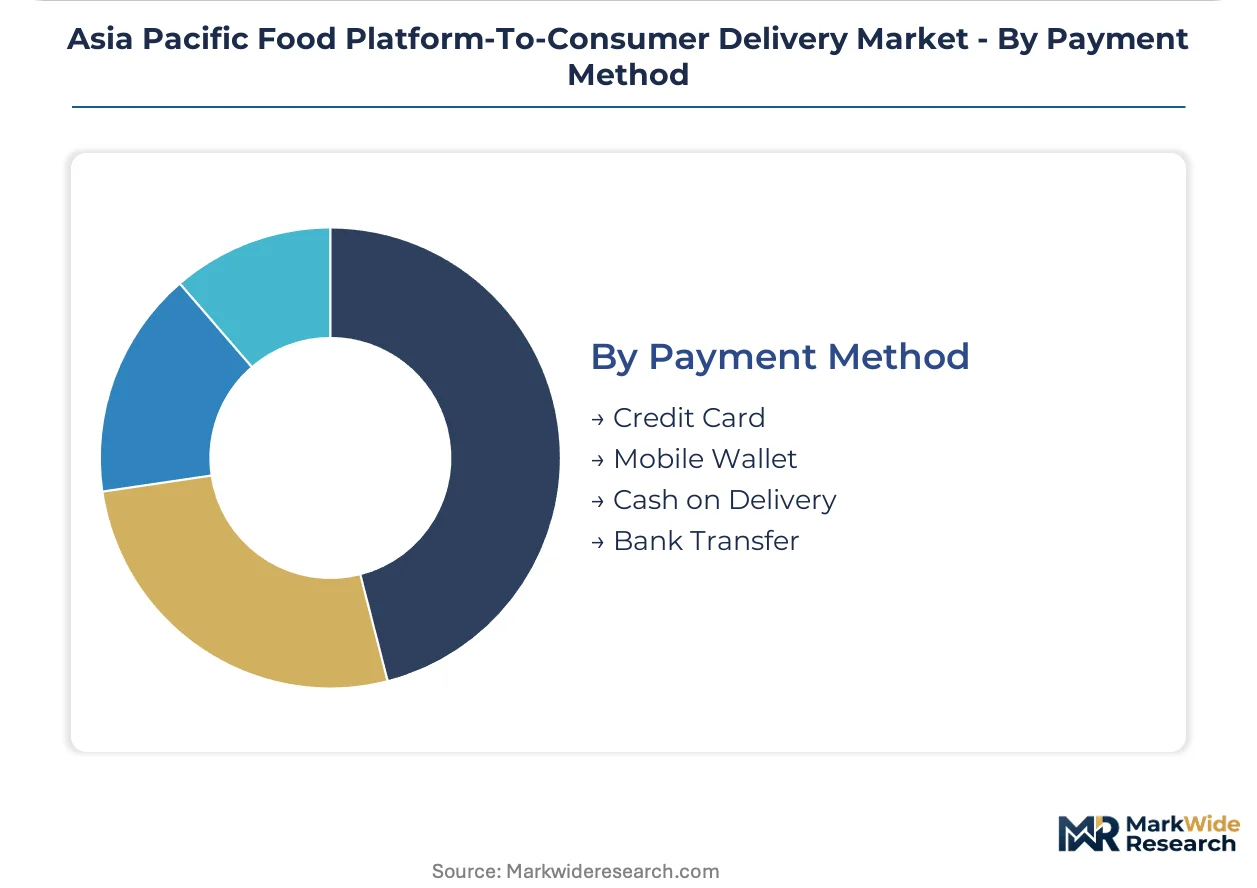
- Mobile Wallet:Super-app integrated payment rails reduce friction and capture transaction float across Southeast Asian markets where GrabFood anchors multi-service ecosystems. China's SAMR platform economy rules shape how payment data localizes and monetizes.
- Cash on Delivery:Remains essential for penetration in Indian tier-two corridors including Jaipur, Lucknow, and Indore, where digital payment adoption lags metropolitan centers. FSSAI compliance costs for cash-handling protocols add operational complexity.
- Credit Card:Dominates in Australian and Japanese markets with mature consumer credit infrastructure.
- Bank Transfer:Enterprise catering accounts prefer invoice-based settlement cycles.
Mobile Wallet leads in transaction velocity. Cash on Delivery retains the widest geographic reach across emerging urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia Pacific food delivery ecosystem operates as a net service importer, with capital and technology flows concentrated in Chinese super-apps while Southeast Asian markets absorb franchise and licensing models from regional headquarters in Singapore and Jakarta.
China
Meituan's algorithmic dispatch infrastructure anchors domestic demand in tier-one cities including Shanghai and Beijing. SAMR antitrust enforcement caps platform commission rates and mandates rider welfare contributions. The Yangtze River Delta corridor hosts the densest cloud kitchen clustering, with predictive inventory systems pre-positioning prepared meals at neighborhood dark stores.
India
Swiggy and Zomato compete for frequency among Mumbai and Bangalore professionals generating above five weekly transactions per active user. FSSAI hygiene audit mandates force standardization across cloud kitchen operations, accelerating consolidation toward compliant operators. Jaipur, Lucknow, and Indore present penetration gaps exceeding forty percent versus metropolitan benchmarks.
Japan
Subscription-based meal kit demand concentrates in Tokyo health-conscious households seeking dietary customization. METI gig economy guidelines clarify contractor classification rules, reducing litigation risk for platforms deploying hybrid employment models. The Kanto region drives premium service adoption with twenty-minute fulfillment benchmarks.
Singapore
GrabFood anchors multi-service ecosystem integration across ride-hailing and financial services. The national framework on platform economy data localization shapes cross-border architecture decisions. Quick-commerce operators stock prepared meals alongside groceries, collapsing distinctions between restaurant delivery and convenience retail.
Indonesia
Delivery Hero SE competes through localized brand portfolios rather than unified platforms across Jakarta and Surabaya metropolitan zones. The country's national platform economy regulator shapes labor classification disputes affecting rider fleet economics. Asset-light franchising reconfigures capital requirements for new entrants seeking tier-two urban expansion.
Asia Pacific Food Platform-To-Consumer Delivery Market Competitive Environment
On the supply side, the industry is consolidating around super-app ecosystems and specialized logistics networks. Meituan and Grab leverage existing rider density and payment rails to compress customer acquisition costs below standalone competitors. Three strategic archetypes dominate: algorithmic dispatch specialists, multi-service ecosystem integrators, and cloud kitchen infrastructure operators. M&A activity concentrates on franchise network acquisitions and dark store portfolio expansion.
Within the super-app tier, Meituan Inc. exemplifies algorithmic infrastructure dominance, while GrabFood occupies a position as the Southeast Asian ecosystem anchor. Among India-based intermediaries, Zomato Limited and Swiggy represent the duopoly structure driving commission stacking and rider network density investments in metropolitan corridors.
| Leading Market Players |
|---|
| Meituan Inc. |
| ELEME Inc |
| GrabFood |
| Zomato Limited |
| Swiggy |
| Foodpanda GmbH |
| Delivery Hero SE |
| Uber Eats |
| DoorDash Inc. |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta corridor anchors cloud kitchen capacity concentration across Shanghai and Shenzhen, where predictive inventory positioning at neighborhood dark stores translates directly into premium pricing power for sub-thirty-minute fulfillment windows. Meituan's algorithmic density in this cluster forces competing platforms to absorb higher rider costs or surrender price-setting authority in China's tier-one metropolitan zones.
Pricing Analysis
Industrial OEM buyers anchor commission-based pricing structures across restaurant-to-consumer intermediation, where per-order margins stratify by fulfillment speed tier and dietary customization depth. SAMR-mandated commission caps in China compress take-rate flexibility, forcing revenue diversification toward advertising slots and logistics-as-a-service monetization. Cost compression in the standard-delivery tier intensifies because rider welfare obligations elevate per-delivery labor costs by fifteen to twenty percent. Quick-commerce operators exhibit the least price sensitivity, while cash-dependent households in Indian tier-two corridors demonstrate acute elasticity.
Supply Chain Analysis
Extended payment terms from cloud kitchen operators to ingredient aggregators now stretch sixty to ninety days, with supply-chain finance facilities emerging as working-capital bridges across Southeast Asian franchising networks. Manufacturing concentration clusters in China, India, and Vietnam, where centralized procurement hubs feed distributed dark-store networks. Raw material dependencies center on temperature-controlled protein supplies, biodegradable packaging polymers, and two-wheeler fleet components. Single-source vulnerability persists in algorithmic dispatch software licensing. Distribution runs through super-app ecosystems that collapse meal delivery into broader service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network effects from rider density and payment-rail integration erect formidable defensive moats around incumbent super-app operators, with regulatory entrenchment through FSSAI and SAMR compliance deepening switching costs for restaurant partners.
For Market Incumbents: Harden cloud kitchen exclusivity agreements in the Yangtze River Delta and Mumbai metropolitan corridors to lock in supply-side capacity before emerging quick-commerce entrants achieve critical mass. Deepen backward integration into dark-store real estate portfolios across Jakarta and Surabaya, converting variable lease obligations into captive infrastructure that withstands margin compression from capped commission structures. For New Entrants and Emerging Players: Mid-market health-conscious households in Tokyo and Melbourne represent the most penetrable entry point, where subscription-based meal kit models bypass restaurant commission structures entirely and capture predictable weekly revenue streams. Tier-two Indian urban corridors including Jaipur, Lucknow, and Indore offer forty-percent penetration gaps versus metropolitan benchmarks, with cash-on-delivery protocols enabling market entry without digital payment infrastructure dependency. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among meal kit operators with robust culinary R&D capabilities, where weekly curated menu subscriptions generate lifetime value multiples exceeding transactional delivery competitors. Across the five-to-ten-year viability window, target acquisition profiles center on cloud kitchen infrastructure operators with FSSAI-compliant centralized supply chains and dark-store portfolios in underserved Southeast Asian markets. The signal to watch is SAMR enforcement intensity on rider welfare contributions, which would accelerate consolidation toward capitalized operators capable of absorbing compliance cost inflation.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Pre-positioned inventory in Jakarta and Singapore compresses fulfillment windows toward twenty-minute benchmarks. |
| Super-App Payment Rail Integration | GrabFood's financial services bundling reduces customer acquisition costs below standalone delivery competitors. |
| Cloud Kitchen Compliance Certification | FSSAI hygiene audit mandates accelerate consolidation toward operators with centralized supply chain control. |
| Subscription Model Conversion | Weekly curated menus in Tokyo capture higher lifetime value than impulse-driven transactional ordering. |
| Tier-Two Geographic Expansion | Jaipur and Indore penetration gaps exceed forty percent versus Mumbai and Bangalore benchmarks. |
Study Parameters
Initial hypotheses were tested against primary input from cloud kitchen operators, delivery aggregator platform executives, FSSAI compliance officers, and restaurant procurement managers and refined through secondary validation across SAMR regulatory filings, FSSAI audit protocols, SEC 10-K disclosures from listed super-app operators, and customs data on foodservice equipment imports. Bottom-up triangulation across metropolitan rider fleet densities and top-down validation against national platform economy revenue estimates anchored the analytical framework.
Demand-supply-balance modeling across the projection horizon integrated service type segmentation by preparation format, customer type stratification by order frequency and margin contribution, delivery model differentiation by fulfillment window commitment, and payment method infrastructure maturity by urban corridor. CAGRs were derived from algorithmic dispatch capacity expansion curves, cloud kitchen penetration rates, and super-app user monetization trajectories throughout the forecast period.
Macroeconomic conditions sit as an overlay; deviation in urban household disposable income growth, fuel price volatility, or gig-economy labor classification rulings would shift the trajectory. Forecasts reflect documented assumptions on rider network scaling efficiency and dark-store inventory turnover benchmarks. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Kamado Grill Market
Food Service
Food Contract Manufacturing Market
Food Service
Quick-Service Restaurants Market
Food Service
Pizza Oven Market
Food Service
Food Trays Market
Food Service
Global Digital Food Delivery Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Steam Tables and Food Well Market
Food Service
Spain Food Service Market
Food Service
Smart Food Logistics Market
Food Service
India Full Service Restaurants Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Bar Refrigeration Market
Food Service
Food Truck Services Market
Food Service
Rotisseries Market
Food Service
Switzerland Food Service Market