
 Client Onboarding Solutions Market | 2026-2036
Client Onboarding Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Client Onboarding Solutions Market Analysis
Buyer concentration in the BFSI sector is hardening as regional banks and credit unions consolidate technology procurement around unified onboarding stacks. HubSpot leverages its CRM-native architecture to anchor mid-market SaaS adoption. Rocketlane competes through project-management integration that reduces implementation timelines for enterprise software vendors. WalkMe specializes in digital adoption layers that overlay legacy core banking systems without replacement costs.
Client onboarding solutions encompass software platforms that automate identity verification, document collection, workflow orchestration, and progress tracking during new customer intake, typically incorporating REST APIs, SAML-based single sign-on, and AES-256 encryption for data transmission. These systems reduce manual processing errors and accelerate time-to-revenue across subscription and contractual relationships. Cloud-based deployment leads segment adoption due to elastic infrastructure that matches seasonal account-opening surges, while artificial intelligence integration represents the fastest-expanding technology category as natural language processing automates document classification and anomaly detection. Self-service portals command margin concentration through reduced support ticket volumes and lower per-customer acquisition costs.
The EU AI Act imposes risk-tiered compliance obligations on automated decision systems used in credit and insurance onboarding, forcing vendors to embed explainability modules and human-in-the-loop checkpoints. The US SEC and FINRA enforce know-your-customer and suitability documentation standards that shape product roadmaps for BFSI-focused platforms. Stakeholders must monitor evolving biometric consent frameworks across state-level privacy statutes to avoid deployment restrictions in California, Illinois, and Texas.
Market Dynamics
Automated decision systems are forcing BFSI enterprises to rearchitect compliance workflows around explainability mandates, compressing vendor evaluation cycles and consolidating procurement toward platforms with embedded audit capabilities.
Growth Catalysts
- EU AI Act Risk Tiers:Credit and insurance onboarding systems now require human-in-the-loop checkpoints, driving replacement of legacy black-box algorithms with interpretable machine learning stacks.
- Biometric Consent Frameworks:State-level privacy statutes in California, Illinois, and Texas mandate explicit opt-in protocols for facial recognition, expanding addressable market for consent-management modules.
- Healthcare Enterprise Modernization:Hospital systems and payers are replacing paper-based intake with API-first platforms to satisfy HIPAA audit requirements and reduce administrative labor.
Market Restraints
- Cloud Infrastructure Concentration:AWS, Azure, and Google Cloud dominate hosting for onboarding platforms, creating single-point-of-failure exposure and limiting vendor negotiating leverage.
- Legacy Core Banking Integration Costs:COBOL-based systems at regional banks require expensive middleware layers, inflating implementation timelines and total cost of ownership.
- Cross-Border Data Localization:GDPR Article 44 restrictions on third-country transfers force redundant infrastructure deployment, raising operational complexity for multinational deployments.
Strategic Opportunities
- Credit Union Technology Gap:Federally chartered credit unions with assets under $10 billion remain underpenetrated, presenting white space for modular SaaS onboarding stacks.
- Embedded Finance Convergence:Non-bank platforms integrating lending and payments need white-label onboarding APIs, creating new channel partnerships for identity-verification vendors.
- India Stack Integration:Aadhaar-based eKYC and DigiLocker document retrieval offer regulatory-compliant rails for rapid market entry in the world's fastest-growing digital payments ecosystem.
Industry Challenges
- ML Engineering Talent Scarcity:Explainable AI development requires specialized expertise in interpretability frameworks like SHAP and LIME, with compensation premiums exceeding 40% above standard software engineering roles.
- Multi-Jurisdiction Certification Overhead:SOC 2 Type II, ISO 27001, and PCI-DSS compliance audits demand 12-18 month timelines, delaying product launches and consuming executive bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Client Onboarding Solutions Market |
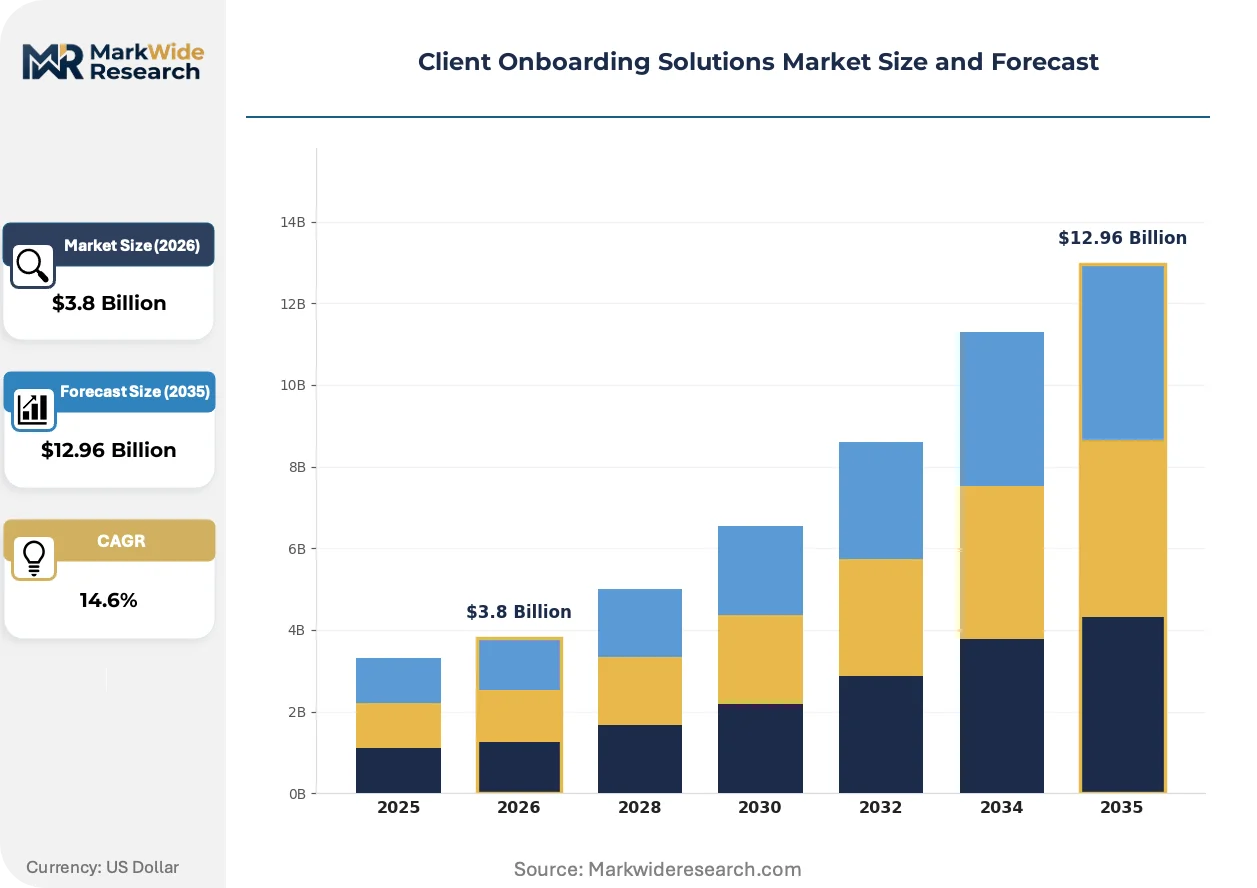
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Onboarding, In-Person Onboarding, Hybrid Solutions, Self-Service Portals Technology: Artificial Intelligence, Machine Learning, Biometric Verification, Cloud Computing End User: BFSI, Healthcare, Telecommunications, E-Commerce Deployment: On-Premise, Cloud-Based, Mobile Solutions, Web Platforms |
| Companies Covered | Pendo, Docebo, Rocketlane, Appcues, HubSpot, GuideCX, WalkMe, OnRamp, Dock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Client Onboarding Solutions Market Emerging Trajectories
Natural language processing engines are compressing document classification cycles from hours to seconds, while regulatory pressure on algorithmic transparency is reshaping how vendors architect decision systems.
Microservices-based identity orchestration is modularizing vendor selection for financial institutions. Banks now compose onboarding flows from specialized best-of-breed components rather than monolithic suites. This architecture enables rapid substitution of biometric providers or document parsers without platform replacement, shortening procurement cycles and reducing vendor lock-in.
The EU AI Act's risk-based classification system is mandating conformity assessments for automated credit decisions. High-risk systems must maintain technical documentation, human oversight protocols, and accuracy metrics subject to market surveillance authority review. German and French regulators are already enforcing these provisions, pushing BFSI vendors to embed governance dashboards and model cards into standard product offerings.
Self-service configuration portals are displacing professional services-led implementations. Mid-market SaaS buyers now expect no-code workflow builders and pre-certified connector libraries. This pattern is most visible among United States-based fintechs and insurtechs, where compressed fundraising timelines demand sub-30-day deployment schedules and immediate ROI demonstration.
Client Onboarding Solutions Market Segmentation
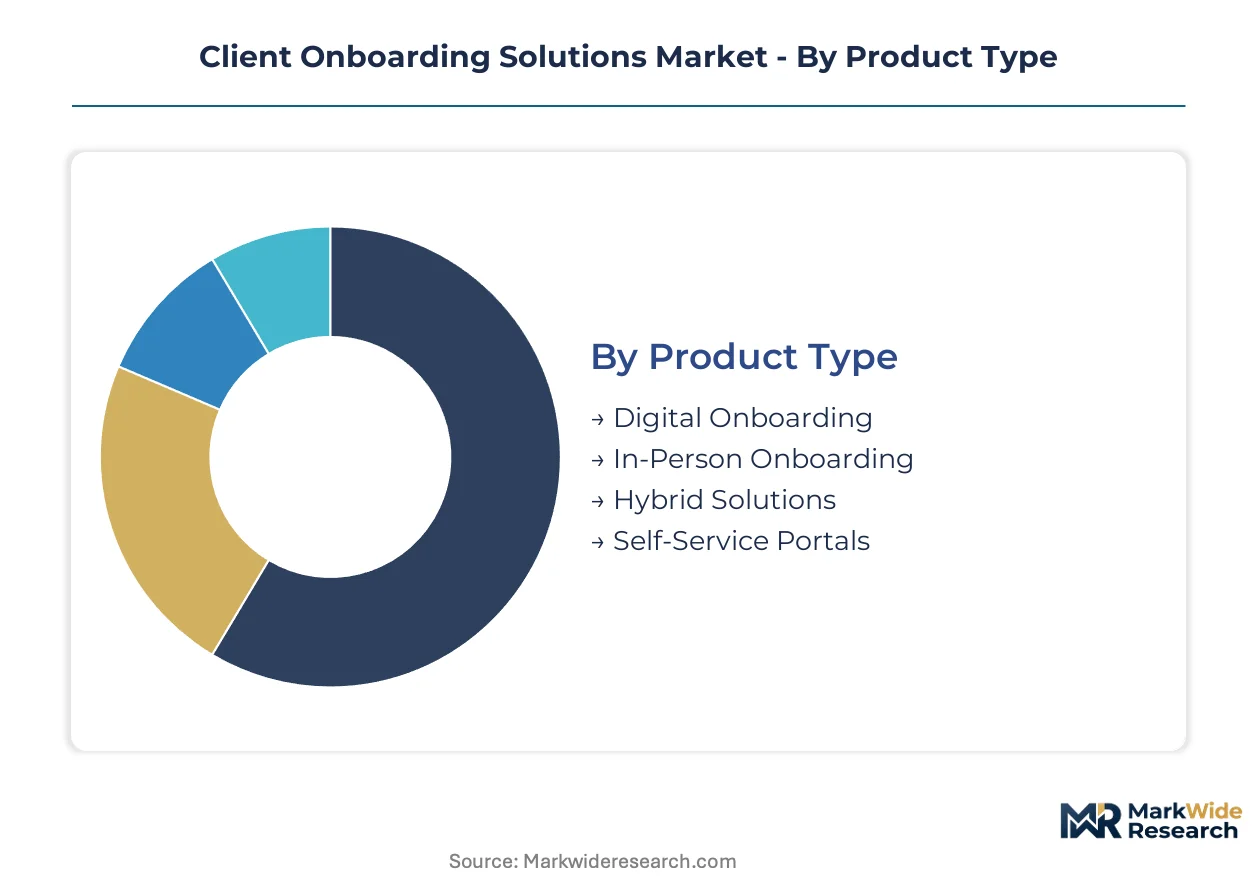
Client onboarding solutions fragment across four critical dimensions that determine compliance architecture and procurement priorities. Each segmentation axis carries distinct certification burdens, integration complexity, and margin profiles that shape vendor positioning and buyer decision frameworks.
Product Type:
SOC 2 Type II and ISO 27001 certifications dominate procurement requirements for cloud-hosted onboarding products, while in-person solutions face stricter biometric consent audits under state privacy statutes.
- Digital Onboarding:Fully automated web and mobile intake flows leveraging REST APIs and AES-256 encryption for document transmission and identity validation. Demand concentrates among United States-based fintechs and insurtechs seeking sub-30-day deployment schedules with immediate ROI demonstration. SOC 2 Type II certification is table stakes for enterprise procurement.
- Hybrid Solutions:Blended workflows combining digital self-service with scheduled human verification checkpoints, particularly in credit and insurance onboarding where EU AI Act mandates human-in-the-loop protocols for high-risk automated decisions. German and French regulators already enforce conformity assessments for these deployments.
- In-Person Onboarding:Branch-based or field-assisted intake requiring biometric capture hardware and witnessed document verification.
- Self-Service Portals:No-code configurable interfaces enabling end-customer driven account creation with embedded progress tracking.
Leading the category by volume: Digital Onboarding. Expanding most quickly: Hybrid Solutions.
Technology:
Technology selection determines explainability obligations under risk-tiered regulatory frameworks, with biometric and AI systems facing the heaviest documentation and audit burdens.
- Artificial Intelligence:Natural language processing engines automating document classification and anomaly detection, now compressing processing cycles from hours to seconds. NLP-powered classification is gaining share fastest among healthcare payers replacing paper-based intake systems to satisfy HIPAA audit requirements.
- Biometric Verification:Facial recognition, fingerprint capture, and liveness detection modules requiring explicit opt-in protocols under California, Illinois, and Texas privacy statutes. Consent-management module demand is expanding as these state frameworks proliferate.
- Machine Learning:Interpretable algorithm stacks replacing legacy black-box systems for credit decisions.
- Cloud Computing:Elastic infrastructure matching seasonal account-opening surges, though AWS, Azure, and Google Cloud concentration creates single-point-of-failure exposure.
Dominating procurement spend: Artificial Intelligence. Steepest expansion trajectory: Biometric Verification.
End User:
End-user verticals exhibit divergent compliance maturity, with BFSI and healthcare enterprises driving premium pricing for audit-ready platforms while telecom and e-commerce prioritize speed-to-deploy over certification depth.
- BFSI:Banks, credit unions, insurers, and wealth managers subject to SEC, FINRA, and EU AI Act know-your-customer and suitability documentation standards. Regional banks and credit unions are consolidating procurement around unified onboarding stacks with embedded governance dashboards.
- Healthcare:Hospital systems and payers replacing legacy intake with API-first platforms to reduce administrative labor and satisfy HIPAA technical safeguard requirements. This vertical shows the strongest replacement cycle momentum among enterprise buyers.
- Telecommunications:Mobile network operators and cable providers automating subscriber activation with reduced identity verification depth.
- E-Commerce:Marketplace sellers and platform merchants requiring lightweight merchant onboarding with minimal regulatory friction.
Commanding the largest addressable market: BFSI. Replacement cycle accelerating fastest: Healthcare.
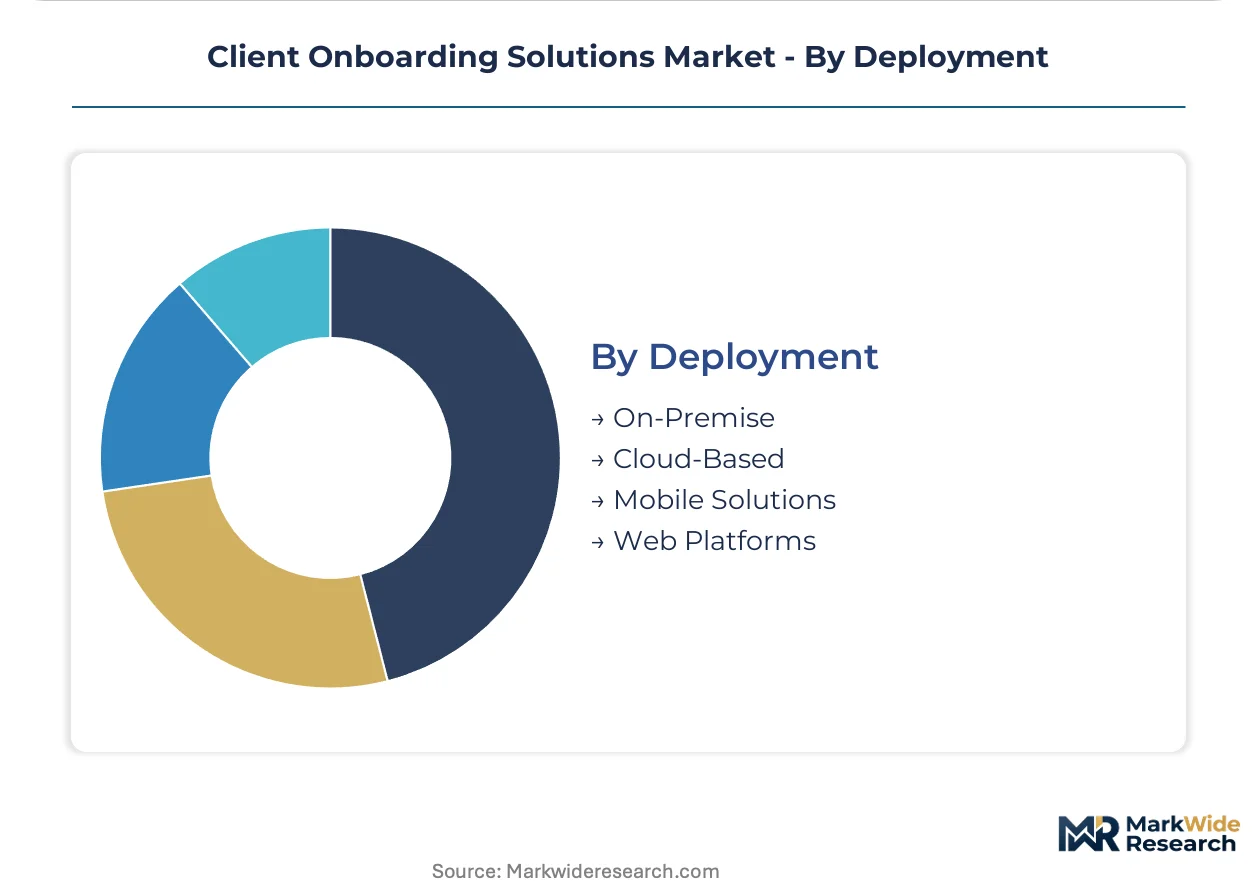
Deployment:
Deployment mode selection reflects infrastructure ownership preferences and data residency constraints, with cloud and mobile solutions facing cross-border transfer restrictions under GDPR Article 44.
- Cloud-Based:Multi-tenant SaaS architectures with elastic scaling and pre-certified connector libraries, now expected by mid-market buyers as standard. Cloud deployment leads segment adoption due to infrastructure flexibility matching seasonal demand surges.
- Mobile Solutions:Native iOS and Android applications with offline document capture and encrypted sync capabilities. Demand is concentrating in India where Aadhaar-based eKYC and DigiLocker integration enables rapid regulatory-compliant market entry.
- On-Premise:Self-hosted installations maintaining data within enterprise-controlled data centers.
- Web Platforms:Browser-based responsive interfaces with broad device compatibility.
Highest volume deployment: Cloud-Based. Gaining share fastest: Mobile Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based BFSI and healthcare enterprises drive the strongest procurement intensity for automated onboarding stacks, while regulatory divergence across jurisdictions forces vendors to maintain multi-certification portfolios.
United States
Regional banks and credit unions consolidate technology procurement around unified onboarding platforms with embedded SEC and FINRA compliance modules. State-level biometric consent statutes in California, Illinois, and Texas mandate explicit opt-in protocols, expanding demand for consent-management overlays. The New York and Boston financial corridors anchor enterprise deployment velocity for cloud-native intake systems.
Germany
Automotive and industrial insurers drive adoption of hybrid onboarding workflows combining digital self-service with human verification checkpoints. The EU AI Act's risk-tiered classification system requires conformity assessments for automated credit decisions, with German regulators already enforcing technical documentation mandates. Frankfurt's financial services cluster leads implementation of explainable AI governance dashboards.
India
Digital payments platforms and neobanks leverage Aadhaar-based eKYC and DigiLocker document retrieval for regulatory-compliant rapid scaling. The RBI's KYC master direction and data localization requirements shape product architecture for foreign vendors entering the market. Mumbai and Bangalore's fintech corridors concentrate deployment of mobile-first onboarding with offline document capture capabilities.
United Kingdom
Wealth managers and challenger banks replace legacy intake systems with API-first platforms to satisfy FCA conduct rules and operational resilience requirements. The Financial Services and Markets Act's digital identity provisions create framework demand for biometric verification vendors. London's Square Mile and Manchester's emerging fintech cluster drive mid-market SaaS adoption with sub-30-day deployment expectations.
Brazil
Retail banks and insurance distributors modernize branch-based onboarding with mobile-enabled biometric capture and liveness detection. ANVISA and central bank regulations on data protection and electronic signatures shape vendor certification requirements. São Paulo's financial district anchors enterprise procurement while Rio de Janeiro's insurtech ecosystem drives modular API adoption.
Client Onboarding Solutions Market Vendor Landscape
United States vendors anchor the premium tier with CRM-native and digital adoption architectures; European specialists hold compliance-heavy segments with embedded governance modules. Market structure shows moderate consolidation around workflow orchestration platforms, with persistent fragmentation in identity verification point solutions. Three strategic archetypes dominate: CRM-integrated suites, project-management-centric implementations, and overlay digital adoption layers. Competitive moves concentrate on API ecosystem partnerships and no-code configuration capabilities that compress implementation timelines.
Within the CRM-native tier, HubSpot exemplifies mid-market SaaS anchoring through unified customer data architectures. Among project-management specialists, Rocketlane occupies a position representing implementation-timeline compression for enterprise software vendors. In the digital adoption overlay segment, WalkMe sits within the archetype of legacy system augmentation without core replacement costs. These three companies collectively represent the strategic positioning vectors—platform integration, implementation velocity, and legacy compatibility—that structure vendor evaluation frameworks across BFSI and healthcare procurement committees.
| Leading Market Players |
|---|
| Pendo |
| Docebo |
| Rocketlane |
| Appcues |
| HubSpot |
| GuideCX |
| WalkMe |
| OnRamp |
| Dock |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure licensing fees from AWS, Azure, and Google Cloud cascade through SaaS onboarding platforms into three-tier pricing structures across premium, standard, and economy levels, with SOC 2 Type II certification premiums separating enterprise-grade deployments from mid-market subscriptions.
Pricing Analysis
Volume concentrates in cloud-native mid-market SaaS tiers while margin pools in hybrid deployments with embedded compliance modules. Price differentiation hinges on certification depth—SOC 2 Type II and ISO 27001 tiers command substantial premiums over uncertified alternatives—and integration complexity with legacy core banking systems. Pricing pressure stems from compressed procurement cycles at regional banks and credit unions consolidating around unified stacks. Healthcare payers show least price sensitivity due to HIPAA audit imperatives; credit unions under $10 billion in assets exhibit highest sensitivity, driving modular SaaS adoption.
Supply Chain Analysis
Reverse-logistics flows for biometric hardware refurbishment and liveness detection device redeployment concentrate servicing operations in India and Mexico, with secondary channels handling EU data-localization compliance returns. Component sourcing draws from Taiwan for semiconductor modules, China for camera sensors, and Germany for precision optics. Single-source vulnerability runs through AWS infrastructure concentration for cloud-hosted platforms. Distribution runs through direct enterprise sales teams for BFSI verticals, with API marketplace channels serving embedded finance partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with control over identity-verification data pipelines and explainable AI model development representing the decisive upstream levers.
For Market Incumbents: Extend governance dashboard capabilities to preempt EU AI Act conformity assessment requirements, embedding human-in-the-loop checkpoints as standard architecture rather than premium add-ons. Consolidate procurement relationships with regional banks by absorbing middleware integration costs currently inflating total cost of ownership for COBOL-based core systems. Defend against modular best-of-breed substitution by certifying pre-built connector libraries for rapid workflow reconfiguration. For New Entrants and Emerging Players: API-first distribution partnerships with neobanks and embedded finance platforms offer the lowest customer acquisition cost route into the market. Federally chartered credit unions with assets under $10 billion present the most penetrable white space, with compliance-light modular SaaS positioning against incumbent complexity. Target India Stack integration—Aadhaar-based eKYC and DigiLocker connectivity—as the definitive go-to-market differentiator for rapid regulatory-compliant scaling. For Investors and Strategic Acquirers: Consolidation of biometric consent-management module vendors following California, Illinois, and Texas statute enforcement is the leading indicator that regulatory compliance capabilities are becoming the primary valuation multiple driver. Long-term viability centers on platforms with embedded explainable AI stacks interpretable under risk-tiered frameworks. Monitor EU AI Act market surveillance authority enforcement patterns in Germany and France for early signals of vendor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CRM-native architectures anchor mid-market SaaS procurement at BFSI enterprises consolidating technology stacks. |
| Acquisition of Specialist Firm | Biometric consent-management vendors command premiums as California, Illinois, and Texas statutes proliferate. |
| Product Launch | No-code workflow builders with pre-certified connector libraries displace professional services-led implementations. |
| Strategic Partnership | India Stack integration partnerships enable rapid regulatory-compliant entry into Aadhaar-based eKYC ecosystems. |
| Geographic Expansion | EU data localization infrastructure addresses GDPR Article 44 third-country transfer restrictions for multinational deployments. |
Methodological Framework
Document review covered SEC 10-K filings, EU regulatory guidance documents, and cloud infrastructure capex disclosures, complemented by interviews with CTOs at fintech platforms, compliance officers at regional banks, biometric hardware procurement leads, and integration specialists at core banking system vendors. Secondary validation drew from FINRA examination reports, HIPAA technical safeguard guidance, and RBI KYC master direction circulars. Bottom-up deployment estimates triangulated against top-down market sizing across the analysis window.
Cross-referencing historical adoption curves with panel input from BFSI procurement committees shaped the analytical framework. Segmentation dimensions modeled include deployment mode, organization size, vertical compliance maturity, integration complexity with legacy systems, and regional regulatory cluster. CAGRs derived from trend extrapolation of certified platform adoption rates and replacement cycle acceleration in healthcare enterprise settings.
The model holds under stable regulatory enforcement timelines; deviation in EU AI Act market surveillance intensity or state-level biometric statute expansion would shift vendor competitive positioning. Practitioners should monitor conformity assessment completion rates in Germany and France for early signals of platform displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Cloud CRM Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
US Customer Relationship Management Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
CRM Outsourcing Market