
 Global Product Management and Road Mapping Tool Market | 2026-2036
Global Product Management and Road Mapping Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Global Product Management and Road Mapping Tool Market Foresight
GDPR enforcement is hardening the cost-of-entry calculus for vendors serving European enterprise clients, forcing substantial investments in data residency architecture and consent management modules. Aha! leverages its deep integration ecosystem to sustain renewal rates among Fortune 500 technology divisions. Productboard anchors its competitive position through specialized voice-of-customer analytics that differentiate roadmap prioritization workflows.
Product management and road mapping tools constitute software platforms that enable strategic planning, feature sequencing, and stakeholder alignment through timeline visualization, resource allocation algorithms, and bidirectional API integrations with engineering systems. Their primary commercial purpose centers on reducing time-to-market latency by synchronizing product, engineering, and executive stakeholders around validated release schedules. Cloud-based deployment dominates procurement patterns among mid-market buyers, while on-premise installations retain structural importance in financial technology and defense-adjacent sectors where data sovereignty requirements override cost efficiency. Portfolio management functionality captures disproportionate margin pools as enterprises consolidate point solutions into unified platform contracts.
The EU AI Act, GDPR, and ISO 27001 framework collectively reshape vendor certification requirements, with conformance becoming a non-negotiable procurement filter for regulated industries across Germany, France, and the United Kingdom. HIPAA and SEC cybersecurity disclosure rules in the United States impose parallel compliance burdens that favor established providers with dedicated governance engineering teams. Stakeholders must monitor how fragmentation between regional data localization mandates affects platform architecture decisions and partner ecosystem investments.
Market Dynamics
The EU AI Act and GDPR compliance deadlines are compressing vendor development cycles, forcing architectural investments in consent management and data residency infrastructure that reshape competitive cost structures.
Growth Catalysts
- Cross-functional release orchestration:Enterprise software development teams now mandate unified roadmapping platforms to synchronize product, engineering, and executive stakeholders around validated release schedules. Cloud-native deployment models accelerate procurement velocity among mid-market buyers.
- GDPR Article 44 data localization:European enterprise procurement now requires verifiable data residency architecture, creating sustained demand for vendors with EU-based infrastructure and consent audit trails.
- API-first integration ecosystems:Bidirectional connectivity with Jira, GitHub, and Salesforce has become a non-negotiable evaluation criterion, pulling adoption toward platforms with mature integration marketplaces.
Market Restraints
- Compliance engineering cost inflation:ISO 27001, SOC 2 Type II, and GDPR certification timelines now extend 12-18 months, consuming 15-25% of annual R&D budgets for emerging vendors.
- On-premise infrastructure lock-in:Financial technology and defense-adjacent sectors in Germany and France retain data sovereignty requirements that override cloud cost efficiencies, fragmenting platform architecture roadmaps.
- Consolidation of point solutions:Enterprise buyers increasingly demand portfolio management functionality within unified contracts, compressing margins for standalone roadmapping specialists.
Strategic Opportunities
- Voice-of-customer analytics convergence:Platforms that embed qualitative feedback synthesis into prioritization workflows capture disproportionate pricing power among product-led growth companies.
- India PLI scheme digital infrastructure:Government incentives for software product development are catalyzing local vendor formation and enterprise SaaS adoption in Bangalore and Hyderabad.
- AI-assisted roadmap scenario modeling:Generative capabilities that simulate resource allocation trade-offs represent unclaimed white space distinct from existing project management automation.
Industry Challenges
- Product-ops talent scarcity:Organizations struggle to hire practitioners capable of translating strategic roadmaps into executable engineering backlogs, creating implementation failure rates above 40% for new deployments.
- Legacy system integration complexity:SAP and Oracle ERP environments in established enterprises require custom connector development, extending deployment timelines and eroding net revenue retention.
- Multi-jurisdiction certification fatigue:Simultaneous pursuit of HIPAA, SEC cybersecurity disclosure compliance, and EU AI Act conformance strains governance engineering capacity at sub-scale vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Product Management and Road Mapping Tool Market |
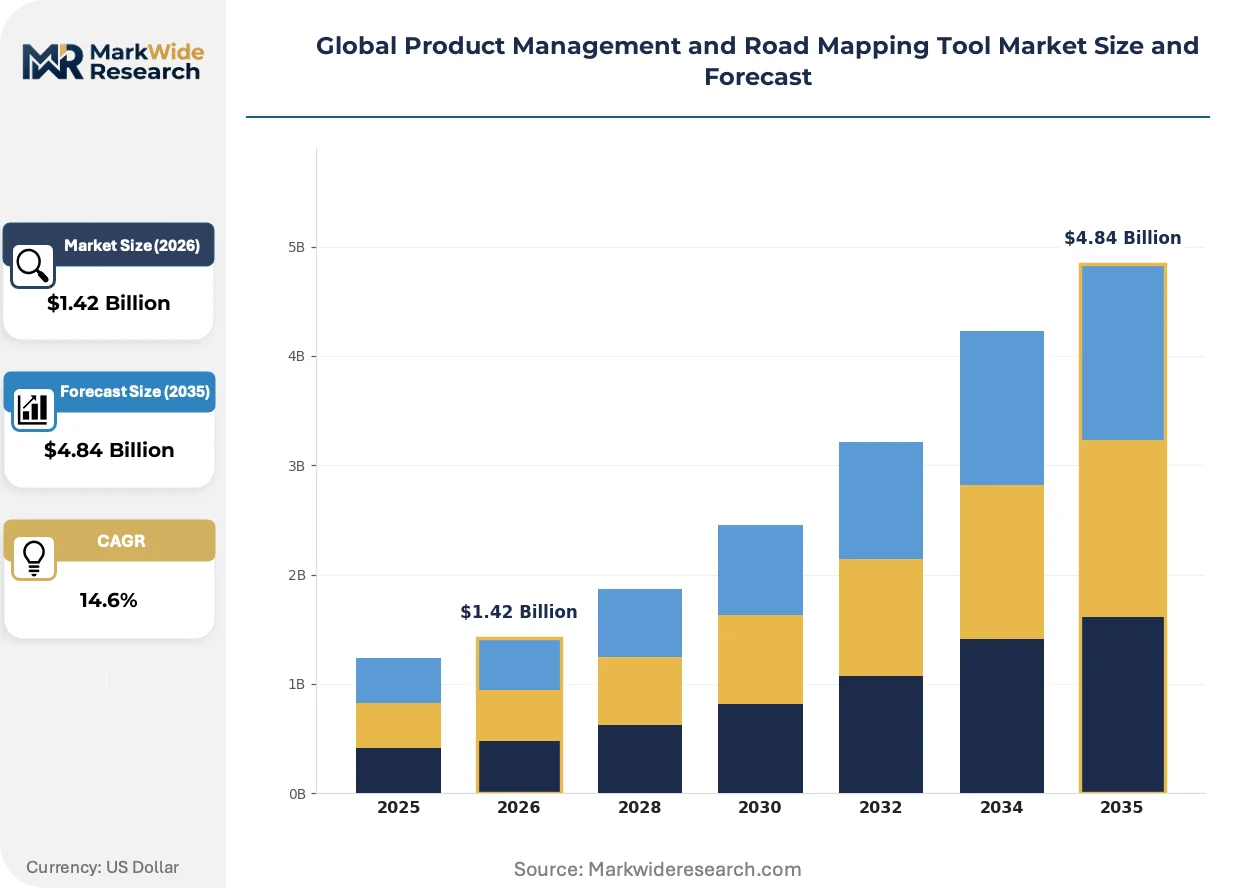
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Type: Road Mapping, Portfolio Management, Collaboration, Analytics, Idea Management End User Industry: IT Services, Telecommunications, Consumer Electronics, Software Development, Financial Technology Feature: Prioritization, Timeline Visualization, Resource Allocation, Integration, Reporting |
| Companies Covered | Aha!, Productboard, SharpCloud, Roadmunk, airfocus, Jira Advanced Roadmaps, Monday.com, ProductPlan, Planview, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Product Management and Road Mapping Tool Market Shifts & Advancements
Artificial intelligence capabilities are reconfiguring how product teams synthesize qualitative inputs and model resource allocation scenarios, while regulatory fragmentation across the Atlantic forces architectural divergence.
Embedded natural language processing is decentralizing roadmap prioritization authority from centralized product operations teams to distributed customer-facing functions. Customer success and sales engineering teams at SaaS scale-ups now directly input feature requests through conversational interfaces. This decentralization compresses the feedback-to-backlog latency from weeks to hours, though it risks overwhelming engineering capacity with unprioritized demand.
The EU AI Act risk classification framework is mandating algorithmic transparency documentation for AI-enhanced prioritization engines. Vendors must now maintain technical files demonstrating human oversight mechanisms and bias mitigation protocols. German automotive and French pharmaceutical enterprises have advanced procurement evaluations to Q3 2025, requiring vendors to demonstrate conformity assessment completion.
Enterprise buying committees now demand outcome-based pricing tied to measurable release velocity improvements rather than seat-based subscriptions. Procurement functions at US venture-backed technology companies are unbundling implementation services from platform fees, pressuring vendors to demonstrate standalone product value within 90-day pilot periods. This behavioral shift is most visible in the San Francisco Bay Area and Seattle technology corridors.
Global Product Management and Road Mapping Tool Market Segmentation
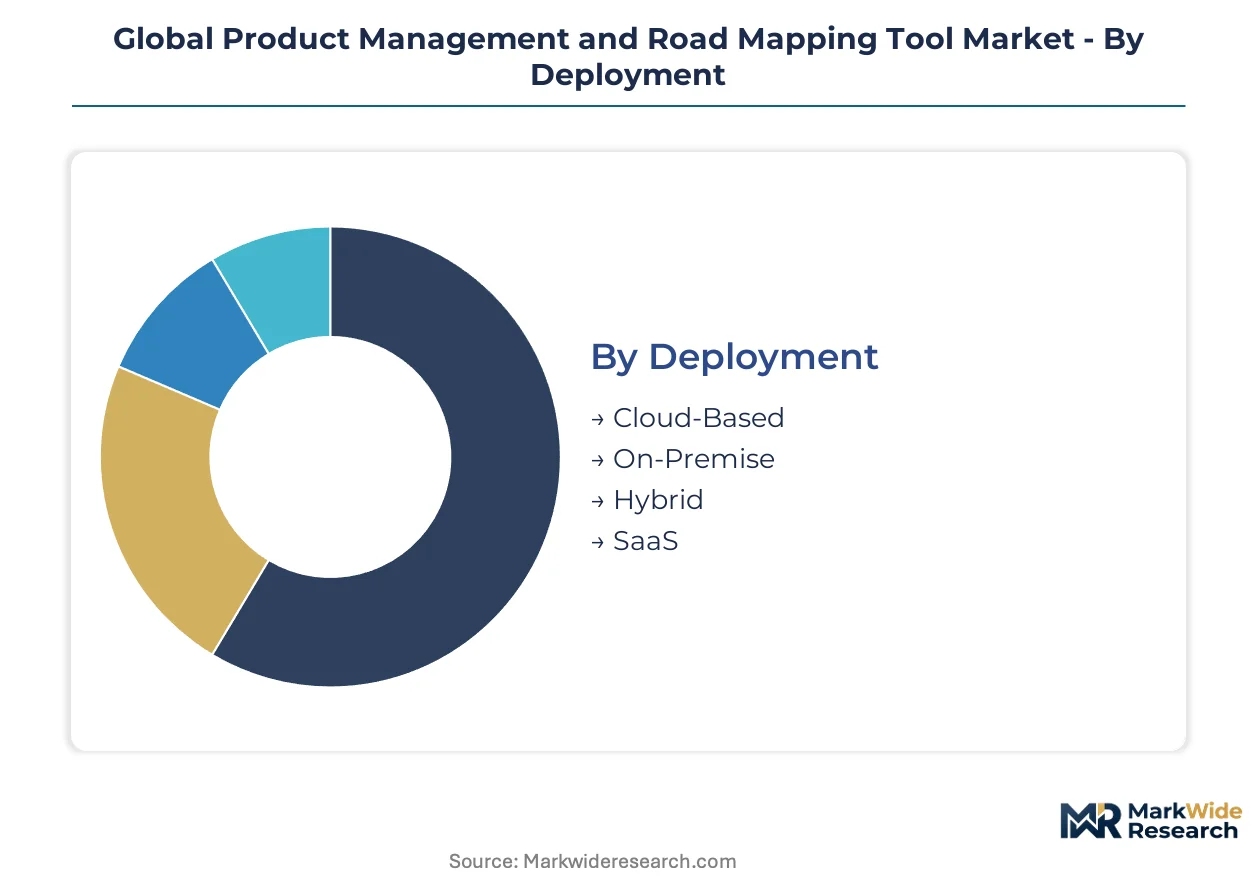
Segmentation reveals how compliance burdens and integration requirements concentrate demand across deployment modes and solution architectures. Vendors must align certification investments with the specific governance demands of each segment to capture procurement volume.
Deployment:
ISO 27001 and SOC 2 Type II certification timelines vary sharply across deployment architectures, with on-premise installations demanding hardware-level audit trails that cloud-native alternatives delegate to hyperscaler infrastructure.
- Cloud-Based:Multi-tenant architectures with automatic patching and elastic scaling dominate procurement among mid-market software development teams. Demand concentrates in the United States, where venture-backed SaaS companies prioritize rapid deployment over data sovereignty. SOC 2 Type II attestation has become a non-negotiable procurement filter for US buyers.
- SaaS:Subscription-native delivery models embed API-first integration marketplaces as core differentiators. German automotive and French pharmaceutical enterprises are advancing procurement evaluations to require EU AI Act conformity documentation for AI-enhanced prioritization engines.
- On-Premise:Air-gapped installations with custom hardware configurations serve financial technology and defense-adjacent sectors where data sovereignty overrides cost efficiency.
- Hybrid:Split architectures allow sensitive roadmap data to remain on-premise while collaboration layers operate in cloud environments.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
Solution Type:
Margin pools concentrate disproportionately in unified platform contracts that consolidate point solutions, reshaping how standalone specialists defend positioning.
- Portfolio Management:Enterprise-grade functionality for resource allocation across multiple product lines captures the highest contract values in procurement cycles. Financial technology buyers in London and New York demand consolidated dashboards that aggregate roadmap data from acquired subsidiaries.
- Road Mapping:Core timeline visualization and feature sequencing capabilities remain the entry-point purchase for scale-up product teams. Bangalore and Hyderabad software vendors are expanding adoption following India's PLI scheme digital infrastructure incentives.
- Collaboration:Stakeholder alignment workflows with bidirectional commenting and approval chains reduce cross-functional friction.
- Analytics:Quantitative release velocity tracking and predictive completion modeling support outcome-based pricing negotiations.
- Idea Management:Centralized intake portals for feature requests from customer-facing teams compress feedback-to-backlog latency.
Portfolio Management commands premium pricing. Road Mapping shows steepest expansion trajectory among scale-up buyers.
End User Industry:
Regulatory fragmentation across jurisdictions forces architectural divergence in feature development, with HIPAA and SEC cybersecurity disclosure rules imposing parallel compliance burdens to EU frameworks.
- Software Development:Native API integrations with Jira, GitHub, and CI/CD pipelines constitute baseline procurement requirements. San Francisco Bay Area and Seattle technology corridors unbundle implementation services from platform fees, demanding standalone value demonstration within compressed pilot periods.
- Financial Technology:Data residency mandates and SEC cybersecurity disclosure rules favor established providers with dedicated governance engineering teams. German and French buyers retain on-premise requirements that fragment platform architecture roadmaps.
- IT Services:Client-delivery organizations require white-label roadmap sharing and external stakeholder access controls.
- Telecommunications:Hardware-software coordination timelines demand specialized resource allocation algorithms for multi-year infrastructure deployments.
- Consumer Electronics:Seasonal release cycles and supply chain integration requirements shape prioritization workflow design.
Software Development anchors procurement volume. Financial Technology exhibits fastest compliance-driven spending growth.
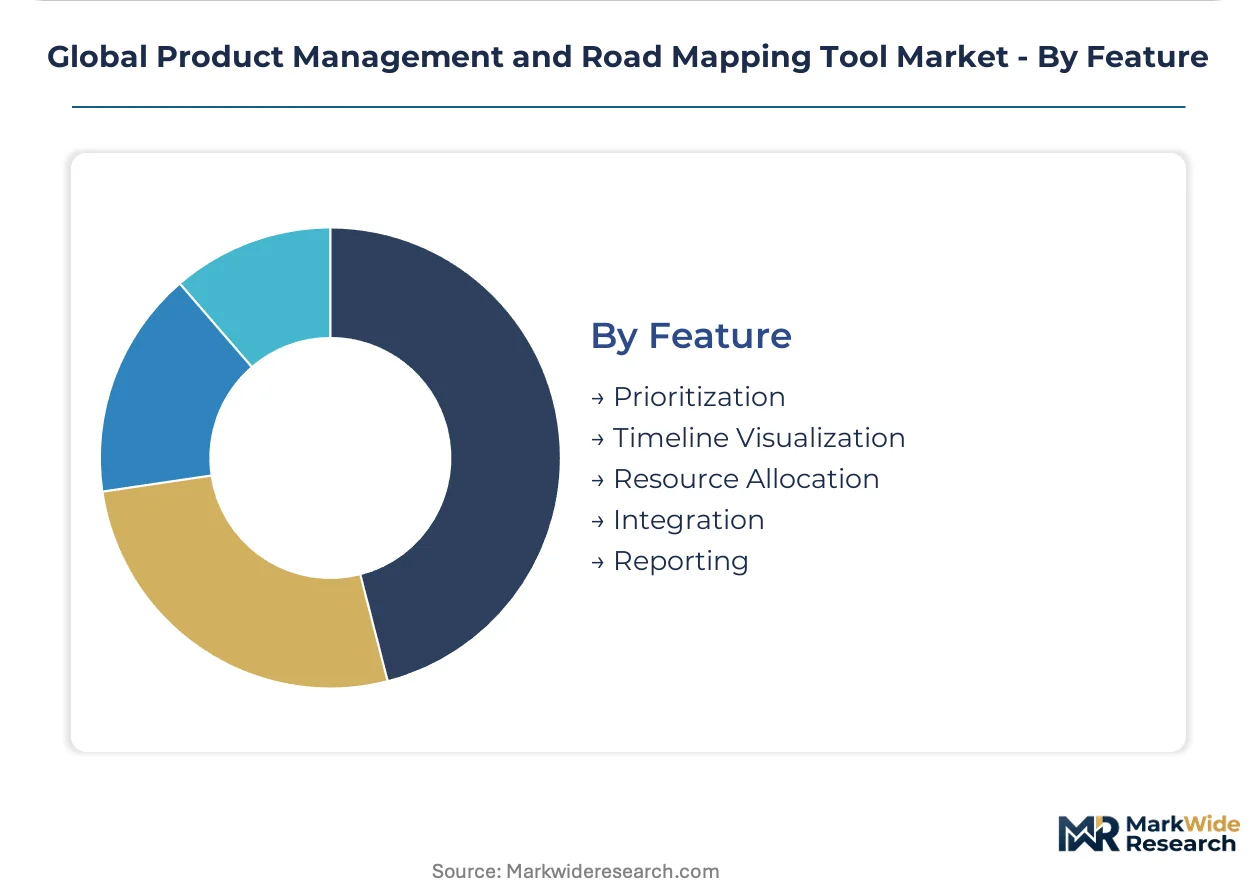
Feature:
AI-assisted capabilities are redistributing roadmap authority from centralized product operations to distributed customer-facing functions, with algorithmic transparency requirements emerging as a procurement filter.
- Integration:Bidirectional API connectivity with engineering systems and CRM platforms has become the primary evaluation criterion in competitive procurement. Mature integration marketplaces pull adoption toward platforms with pre-built connectors for Salesforce, SAP, and Oracle ERP environments.
- Prioritization:AI-enhanced scoring algorithms that synthesize qualitative feedback into quantitative rankings capture pricing power among product-led growth companies. EU AI Act risk classification mandates technical documentation demonstrating human oversight mechanisms.
- Timeline Visualization:Gantt and kanban-style roadmap presentations remain standard across all buyer tiers.
- Resource Allocation:Capacity planning algorithms that model engineering team constraints against feature demand reduce time-to-market latency.
- Reporting:Executive dashboard exports and compliance audit trails satisfy governance requirements in regulated industries.
Integration leads feature prioritization in procurement evaluations. Prioritization is gaining share fastest as AI capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volume concentrates in the United States, where venture-backed SaaS companies anchor demand, while compliance engineering investments reshape vendor economics across Germany, France, and the United Kingdom.
United States
San Francisco Bay Area and Seattle technology corridors unbundle implementation services from platform fees, demanding standalone value demonstration within compressed pilot periods. SEC cybersecurity disclosure rules impose governance documentation requirements that favor established providers with dedicated compliance engineering teams. Outcome-based pricing tied to measurable release velocity improvements is displacing traditional seat-based subscriptions among US venture-backed technology companies.
Germany
Automotive and pharmaceutical enterprises in Stuttgart and Munich have advanced procurement evaluations to require EU AI Act conformity documentation for AI-enhanced prioritization engines. GDPR Article 44 data localization mandates drive demand for verifiable EU-based infrastructure and consent audit trails. On-premise installations retain structural importance in financial technology sectors where data sovereignty requirements override cloud cost efficiencies.
France
Paris-based pharmaceutical and defense-adjacent enterprises impose hardware-level audit trail requirements that fragment platform architecture roadmaps. ANSM and CNIL enforcement actions harden the cost-of-entry calculus for vendors serving French enterprise clients. French buyers increasingly demand portfolio management functionality within unified contracts, compressing margins for standalone roadmapping specialists.
United Kingdom
London financial technology buyers demand consolidated dashboards that aggregate roadmap data from acquired subsidiaries across multiple jurisdictions. Post-Brexit regulatory divergence from EU frameworks creates parallel certification burdens for vendors maintaining UK and continental European operations. UK software development teams mandate unified roadmapping platforms to synchronize product, engineering, and executive stakeholders around validated release schedules.
India
Bangalore and Hyderabad software vendors expand adoption following India's PLI scheme digital infrastructure incentives for software product development. Government procurement now requires BIS certification for enterprise SaaS platforms serving public sector clients. Indian IT services organizations require white-label roadmap sharing and external stakeholder access controls for client-delivery operations.
Global Product Management and Road Mapping Tool Market Competitive Landscape
US producers anchor one tier; European specialists hold compliance-driven positioning in regulated industries. The vendor base organizes around three structural tiers: established platforms with mature integration marketplaces, emerging challengers with AI-native architectures, and legacy providers defending on-premise installations. Consolidation pressure intensifies as enterprise buyers demand portfolio management functionality within unified contracts. Strategic moves concentrate on API-first ecosystem expansion and vertical-specific compliance certification.
Within the established platform tier, Aha! and Productboard occupy positions defined by integration depth and voice-of-customer analytics specialization respectively. Roadmunk exemplifies the mid-market challenger archetype with timeline visualization capabilities. These three companies represent the competitive spectrum from enterprise-grade portfolio management to scale-up-focused roadmapping workflows, each defending distinct price-positioning through differentiated feature architecture rather than pure scale economics.
| Leading Market Players |
|---|
| Aha! |
| Productboard |
| SharpCloud |
| Roadmunk |
| airfocus |
| Jira Advanced Roadmaps |
| Monday.com |
| ProductPlan |
| Planview |
| Others |
Supply & Pricing Matrix
API-first integration ecosystems anchor both supply positioning and pricing power in this market, with vendors embedding bidirectional connectivity as a captive capability that locks in enterprise procurement and sustains subscription premiums against point-solution competitors.
Pricing Analysis
Seat-based subscriptions dominate the lower-volume tier while outcome-based contracts capture disproportionate margin pools among enterprise buyers. Price differentiation hinges on certification depth—ISO 27001 and SOC 2 Type II attestation command premium positioning—and integration marketplace maturity. Pricing pressure stems from consolidation demands as buyers bundle portfolio management into unified platform contracts. Mid-market SaaS scale-ups exhibit highest price sensitivity; defense-adjacent sectors with data sovereignty mandates show lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand while partner ecosystems extend reach into mid-market segments. Engineering talent concentrates in the United States, Germany, and India. Cloud infrastructure draws from AWS, Azure, and Google Cloud hyperscalers. Single-source vulnerability in AI model providers poses structural risk. Distribution runs through vendor-direct sales, systems integrators, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over voice-of-customer data pipelines represents the decisive upstream lever players are pursuing to defend roadmap authority against AI-native challengers.
For Market Incumbents: Anticipate margin compression from AI-native prioritization engines by deepening integration marketplace density and embedding consent management modules ahead of EU AI Act enforcement. Defensive consolidation through targeted acquisition of voice-of-customer analytics specialists will secure roadmap data pipeline control.
For New Entrants and Emerging Players: Begin with AI-assisted scenario modeling for resource allocation trade-offs, an unclaimed white space distinct from incumbent project management automation. India's PLI scheme digital infrastructure offers the most penetrable geography for local vendor formation. Go-to-market should anchor in Bangalore and Hyderabad software vendor ecosystems.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays by established enterprise software providers seeking roadmap functionality. Long-term viability favors vendors with demonstrated EU AI Act conformity documentation and dedicated governance engineering capacity. Monitor procurement evaluation timelines at German automotive and French pharmaceutical enterprises as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| API Marketplace Expansion | Bidirectional Jira and Salesforce connectors lock in Fortune 500 technology divisions. |
| EU AI Act Conformity Investment | Technical documentation for algorithmic transparency opens German automotive procurement. |
| Voice-of-Customer Analytics Acquisition | Specialized feedback synthesis capabilities differentiate roadmap prioritization workflows. |
| Hybrid Deployment Architecture | Split cloud-on-premise models satisfy French defense data sovereignty mandates. |
| Outcome-Based Pricing Pilot | Release velocity metrics displace seat-based subscriptions among US venture-backed SaaS. |
Research Methodology
Independent corroboration across product management executives, enterprise IT procurement officers, platform engineers, and integration specialists underwrites the qualitative findings. Primary interviews with CTOs at venture-backed SaaS companies and governance leads at regulated enterprises combined with secondary validation from SEC cybersecurity disclosure filings, hyperscaler partnership announcements, and EU regulatory conformity databases. Bottom-up deployment estimates and top-down market sizing triangulate volume figures.
Comparable historical reference periods anchored the forecast window to pre-pandemic procurement baselines and post-acceleration normalization trends. Segmentation dimensions modeled span deployment architecture, organization size, vertical compliance intensity, and regional adoption pattern. CAGRs derived from trend extrapolation adjusted for regulatory enforcement timelines and integration ecosystem maturation curves. Forecast inputs include EU AI Act implementation schedules and India's PLI scheme incentive disbursement patterns.
Underlying measurement precision varies by segment; cloud-based and SaaS deployment estimates carry tighter precision than on-premise and hybrid configurations given disclosure practices. Forecasts reflect assumptions about compliance timeline adherence and enterprise consolidation behavior. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Corporate Wellness Software Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Email Marketing Software Market
Software & Services
Business Email Market
Software & Services
Global Decision Support Software Market
Software & Services
Global Funeral Home Software Market
Software & Services
Saas Based HRM Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Journal App Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Global Automotive Software Market
Software & Services
App Development Software Market