
 Ticket Admission Systems Market | 2026-2036
Ticket Admission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ticket Admission Systems Market Analytics
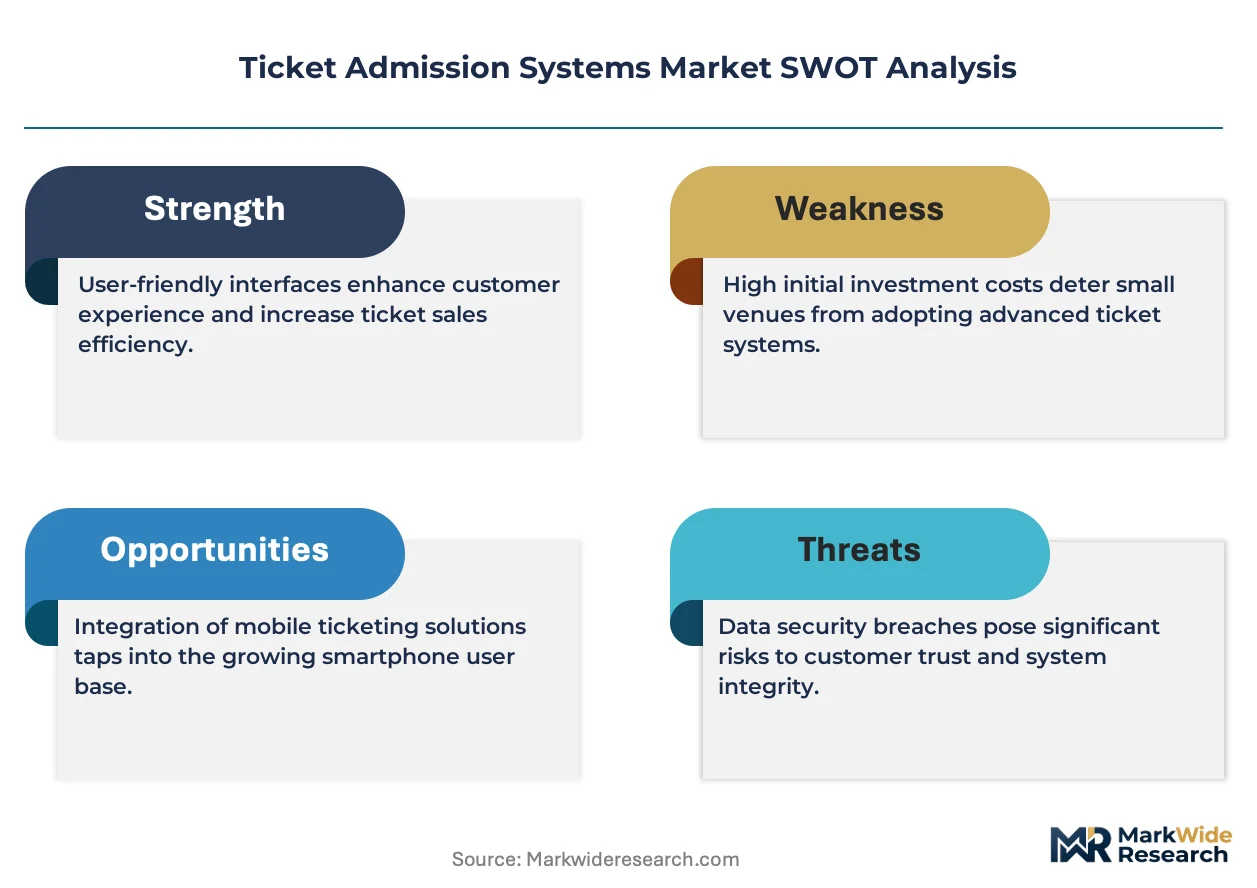
Mobile-first distribution channels is reconfiguring how venues reach audiences before events. Ticketmaster leverages its exclusive venue partnerships to control premium inventory access. Eventbrite competes through self-service tools that empower smaller promoters. CTS Eventim anchors Central European market presence with integrated ticketing and content platforms.
Ticket admission systems encompass hardware and software infrastructure that validates, processes, and records entry credentials at controlled-access venues, typically integrating barcode scanners, NFC readers, and cloud-synced databases operating under sub-second authentication thresholds. These systems serve commercial venues by eliminating counterfeit entry, enabling dynamic capacity management, and capturing real-time attendance analytics. Cloud-based deployment leads in new installations due to lower capital requirements and elastic scaling during peak event windows. NFC technology commands premium positioning where contactless speed and wallet integration reduce gate friction. Museums represent a maturing end-user segment with slower replacement cycles compared to entertainment venues chasing experiential differentiation.
The EU AI Act and GDPR shape biometric verification deployment across European venues, restricting facial recognition storage without explicit consent. The FCC governs wireless communication standards for NFC and RFID hardware operating in unlicensed spectrum bands in the United States. Venue operators must weigh authentication speed against privacy compliance when selecting technology stacks. Stakeholders should monitor regulatory divergence between biometric-permissive and biometric-restrictive jurisdictions as a determinant of platform architecture investment.
Market Dynamics
Mobile-first credentialing and biometric verification are compressing gate-processing times below one second while EU AI Act consent requirements force parallel authentication architectures across European venues.
Growth Catalysts
- NFC Wallet Integration:Apple Wallet and Google Pay native ticketing reduce friction at stadium turnstiles. Sports franchises in Germany and the United States are mandating contactless-only entry for premium sections.
- GDPR-Compliant Biometrics:Facial recognition with on-device processing satisfies EU data residency rules. Venues in France and Spain deploy edge-computing cameras that delete templates post-event.
- Dynamic Capacity Algorithms:Cloud-based gate management software enables real-time section reopening based on flow telemetry. Festival operators in Brazil and Australia use these tools to maximize yield per event.
Market Restraints
- Semiconductor Supply Concentration:NFC controller chips depend on TSMC and Samsung foundry capacity. Lead times for RFID readers stretch to 26 weeks during consumer electronics demand spikes.
- Biometric Storage Restrictions:France's CNIL and Germany's BfDI enforce strict facial template retention limits. Venues must purge data within 72 hours or face penalties.
- Legacy Hardware Stranded Investment:Magnetic stripe and barcode infrastructure at older arenas lacks firmware upgrade paths. Replacement cycles extend to seven years in municipal venues with constrained capital budgets.
Strategic Opportunities
- India Live Entertainment Expansion:IPL cricket and Bollywood touring circuits lack integrated ticketing infrastructure. Domestic platforms can capture venue relationships before international entrants establish presence.
- Blockchain Credential Verification:Non-transferable tokenized tickets eliminate secondary market fraud. Music promoters in the Netherlands pilot Ethereum-based ownership records.
- ISO 27001 Certification as Differentiator:Enterprise buyers mandate information security management for cloud ticketing contracts. Vendors with certified data centers win municipal and government venue RFPs.
Industry Challenges
- Cybersecurity Talent Scarcity:Cloud ticketing platforms require SOC 2 Type II auditors and penetration testing specialists. Compensation inflation in security engineering strains vendor operating margins.
- Legacy POS Integration Complexity:Concession and merchandise systems at historic venues run on 1990s-era protocols. API middleware development consumes 40% of deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ticket Admission Systems Market |
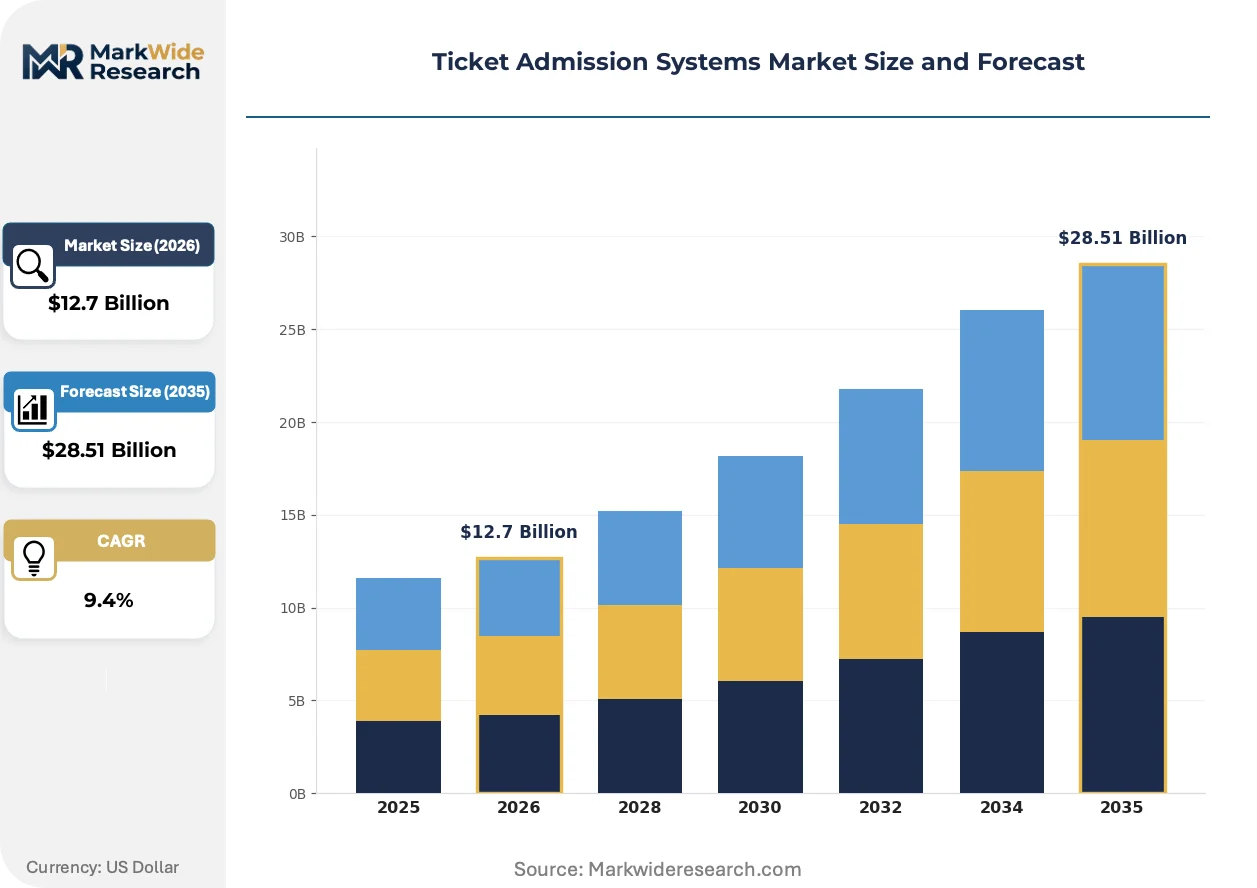
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: QR Code, NFC, RFID, Barcode Deployment: Cloud-Based, On-Premise, Hybrid, Mobile End User: Entertainment Venues, Sports Arenas, Theatres, Museums Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | Ticketmaster, Eventbrite, StubHub, Cubic Corporation, Thales, Conduent, Scheidt and Bachmann, AXS, CTS Eventim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ticket Admission Systems Market Evolving Landscape
Virtualization of credential infrastructure and regulatory fragmentation around biometric storage are forcing architectural bets that will determine vendor competitiveness through the decade.
Cloud-native access control platforms are virtualizing gate hardware into software-defined endpoints. Museum networks and mid-size theaters adopt browser-based validation tablets rather than dedicated scanning terminals. This virtualization compresses capital requirements by 60% and enables overnight deployment of temporary venues.
EU AI Act Article 5 restrictions on real-time biometric identification in public spaces are forcing European venues toward opt-in facial verification. Sports operators in Italy and Poland deploy explicit consent flows at ticket purchase. The regulation fragments vendor product roadmaps between biometric-permissive North American and biometric-restrictive European code bases.
Subscription-based season access models are displacing single-event ticket purchases in performing arts. Symphony orchestras in Germany and opera houses in Austria bundle flexible seating with dining credits. This behavioral shift concentrates buyer relationships onto platform ecosystems and reduces last-minute inventory risk for venue operators.
Ticket Admission Systems Market Segmentation
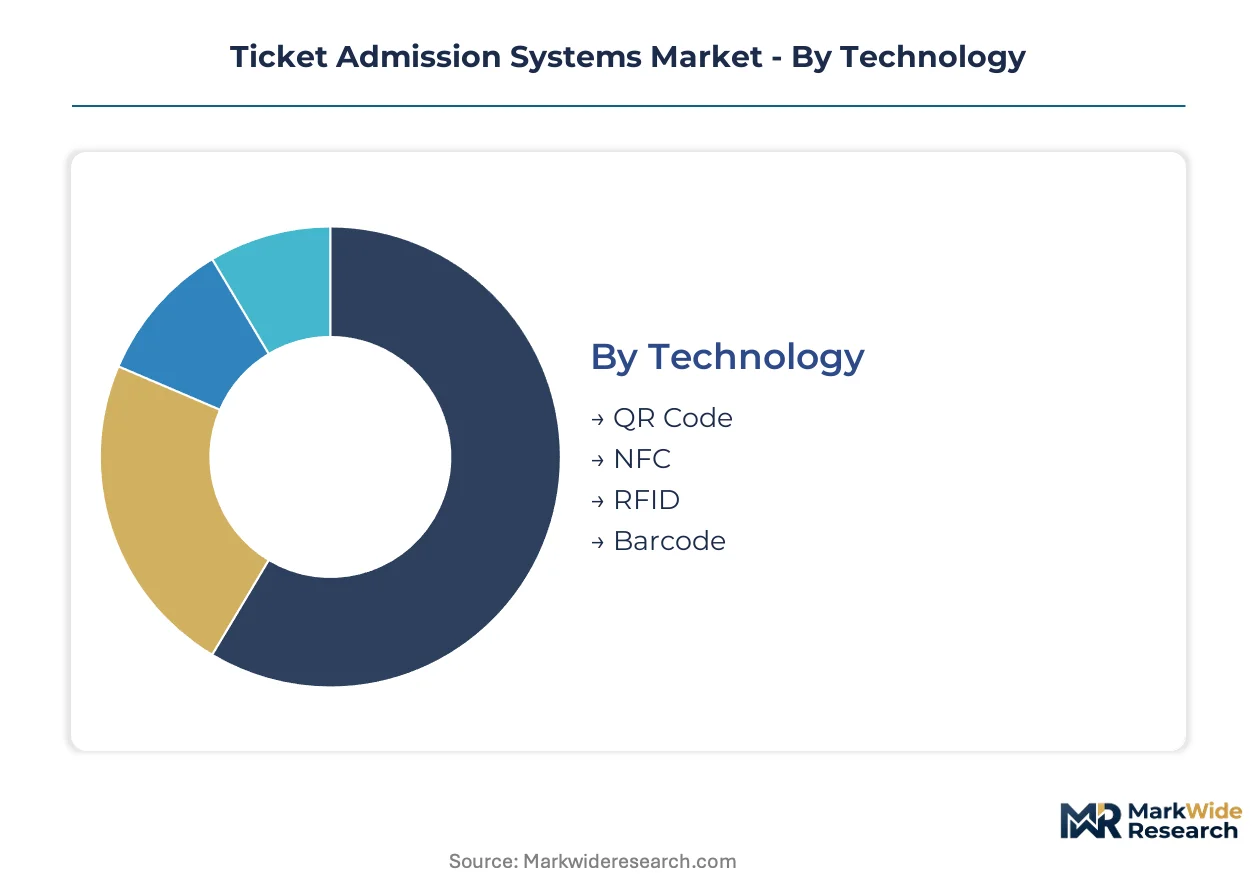
Technology choices in ticket admission systems determine authentication speed, infrastructure cost, and regulatory compliance posture across venue types. Deployment models shape capital allocation and operational flexibility for operators managing seasonal demand spikes. Understanding segment boundaries enables buyers to match platform architecture against specific throughput and privacy requirements.
Technology:
Use-case spectrum spans high-volume rapid entry at sports stadiums to low-friction museum access, with each technology optimizing for different authentication latency and hardware investment tradeoffs.
- QR Code:Two-dimensional matrix codes displayed on smartphone screens or printed media, readable by standard camera sensors without dedicated hardware. Demand concentrates in emerging markets and temporary event installations across Brazil and India where smartphone penetration outpaces NFC terminal deployment, constrained by daylight glare and damaged screen readability.
- NFC:Near-field communication operating at 13.56 MHz enables sub-500 millisecond tap-to-enter validation with native wallet integration. Sports franchises in Germany and the United States mandate contactless-only entry for premium seating sections, driven by Apple Wallet and Google Pay adoption eliminating physical credential handling.
- RFID:Radio-frequency identification using passive or active tags for hands-free gate traversal at distance. Festival operators in Australia deploy UHF bands for multi-day camping events where wristband durability matters more than smartphone battery dependence.
- Barcode:Linear one-dimensional encoding requiring laser scanning hardware, prevalent in legacy infrastructure at municipal venues and older theaters. Replacement cycles extend to seven years where capital budgets prioritize concession upgrades over gate modernization.
Established volume favors Barcode; emerging adoption favors NFC.
Deployment:
Cost tier separation runs from zero-capital mobile solutions to seven-figure on-premise data center commitments, with hybrid architectures capturing venues navigating privacy jurisdiction complexity.
- Cloud-Based:Software-as-a-service delivery with elastic compute scaling during peak event windows and automatic security patching. Mid-size theaters and museum networks across France and Spain adopt browser-based validation tablets, reducing capital requirements by eliminating dedicated scanning terminals.
- On-Premise:Local server infrastructure with full data residency control, mandated by government venues and defense-related facilities in Germany subject to BfDI strictures. Operators absorb higher upfront costs and internal IT burden for sovereignty compliance.
- Hybrid:Split architecture keeping sensitive biometric templates on local edge devices while routing transactional data to cloud analytics. European sports operators deploy this model to satisfy EU AI Article 5 consent requirements without sacrificing real-time capacity management.
- Mobile:Smartphone-native credential validation eliminating dedicated gate hardware entirely, suitable for pop-up venues and temporary exhibitions. Popularity climbs fastest among independent promoters in the Netherlands piloting decentralized entry verification.
Capital efficiency favors Cloud-Based; regulatory flexibility favors Hybrid.
End User:
Application maturity separates high-frequency entertainment venues chasing experiential differentiation from slow-cycle cultural institutions with extended replacement timelines.
- Entertainment Venues:Nightclubs, concert halls, and festival grounds prioritizing throughput velocity and social media integration. Dynamic capacity algorithms enable real-time section reopening based on flow telemetry, maximizing yield per event in Brazil and Australia.
- Sports Arenas:Professional stadiums and collegiate facilities with season-ticket holder relationships and concession bundling requirements. Subscription-based access models displace single-event purchases in Germany, concentrating buyer relationships onto platform ecosystems.
- Theatres:Performing arts venues with assigned seating and subscription patron bases, slower to adopt biometric verification due to older demographic preferences. Legacy POS integration complexity consumes 40% of deployment timelines at historic opera houses.
- Museums:Cultural institutions with sporadic attendance patterns and grant-dependent capital cycles. Slower replacement rhythms compared to entertainment venues, with edge-computing cameras for facial verification appearing first at high-traffic national collections in Italy.
Technology refresh velocity favors Entertainment Venues; stability requirements favor Museums.
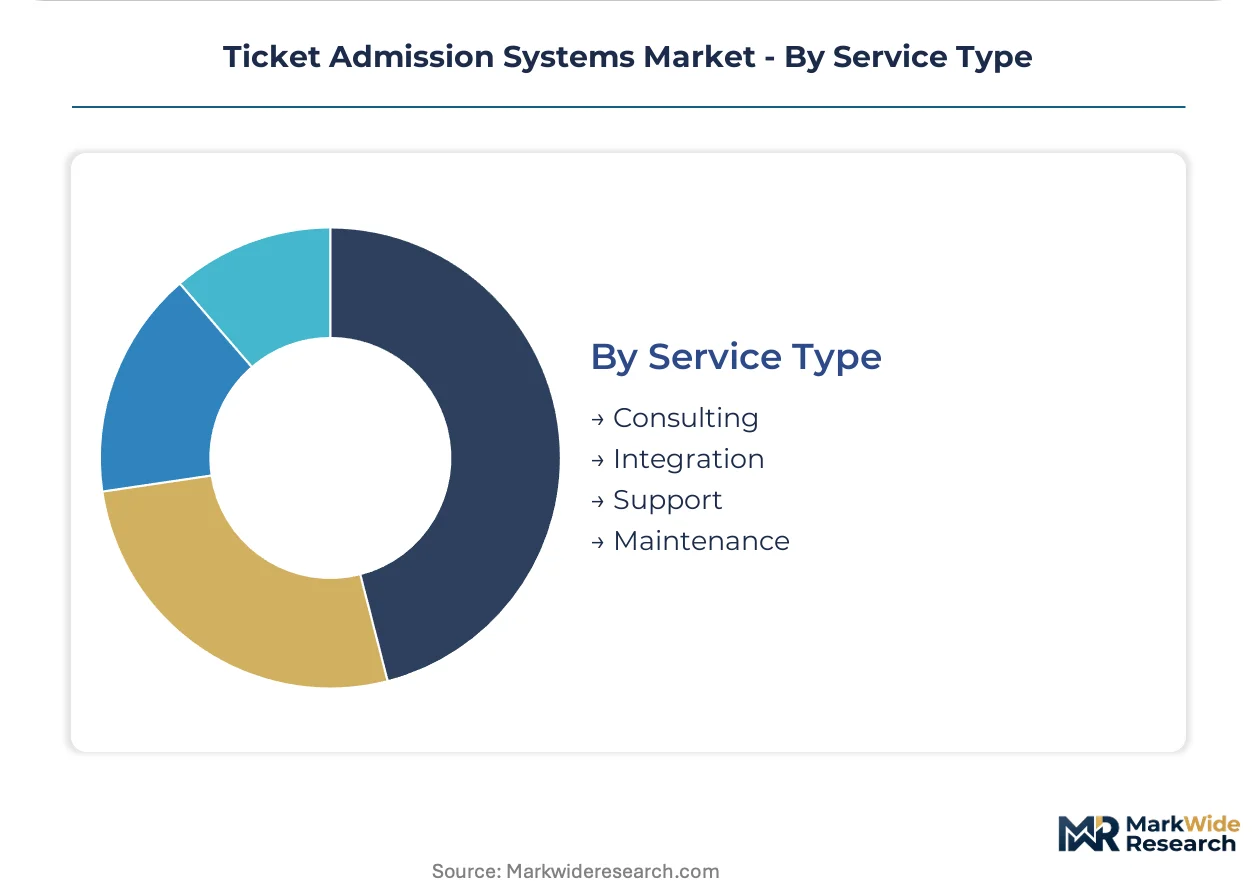
Service Type:
Customer type differentiation separates transactional project work from recurring revenue relationships, with integration complexity driving margin concentration.
- Consulting:Architecture assessment and vendor selection advisory for venue operators navigating EU AI Act compliance and biometric storage restrictions. Municipal buyers in France engage specialists to design consent workflows satisfying CNIL 72-hour data purge mandates.
- Integration:API middleware development connecting admission systems to legacy concession and merchandise platforms running 1990s-era protocols. This service captures 40% of deployment timelines at historic venues and commands premium pricing for scarce embedded systems expertise.
- Support:Help desk and on-site technical assistance during live events, typically bundled as annual contracts. Demand spikes correlate with festival season concentration in Central Europe.
- Maintenance:Preventive hardware servicing and firmware updates for scanning terminals and edge computing devices. Seven-year replacement cycles at municipal venues sustain predictable recurring revenue.
Project margin favors Integration; contract stability favors Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German venue networks where CTS Eventim's integrated platform commands premium margins, while Indian cricket stadiums absorb higher per-seat technology costs due to fragmented supplier relationships and infrastructure gaps.
United States
Professional sports franchises and collegiate athletics drive NFC wallet integration at stadium turnstiles, with Apple Pay and Google Pay adoption accelerating contactless mandates. The FCC governs unlicensed spectrum standards for RFID hardware deployment. Los Angeles and Dallas-Fort Worth anchor the largest venue upgrade cycles, with SoFi Stadium and AT&T Stadium setting contactless-only entry precedents.
Germany
CTS Eventim's platform dominance concentrates demand across Bundesliga football and concert touring circuits, enabling subscription-based season access models. The BfDI enforces strict biometric data residency rules under GDPR, mandating 72-hour facial template purges. Munich and Berlin host the densest cluster of hybrid cloud-edge deployments satisfying EU AI Act consent requirements.
India
IPL cricket franchises and Bollywood touring circuits lack integrated ticketing infrastructure, creating first-mover opportunities for domestic platforms. The central bank's digital payment push accelerates UPI-linked mobile credential adoption. Mumbai and Bengaluru concentrate venue technology investments, with Wankhede Stadium and M. Chinnaswamy Stadium piloting QR-NFC hybrid systems.
Brazil
Festival operators deploy dynamic capacity algorithms to maximize yield per event across multi-day camping circuits. ANVISA regulates health data collection at biometric entry points. São Paulo and Rio de Janeiro anchor live entertainment infrastructure, with Rock in Rio and Lollapalooza São Paulo driving cloud-based gate management adoption.
Australia
Festival and sporting venue operators prioritize UHF RFID wristbands for hands-free multi-day access at camping events. The TGA oversees medical device classifications for biometric health screening integrations. Sydney and Melbourne concentrate venue technology procurement, with the Melbourne Cricket Ground and Accor Stadium deploying edge-computing cameras for flow telemetry.
Ticket Admission Systems Market Competitive Landscape
Integrated platform operators and specialized hardware fabricators split the market into distinct capability tiers, with scale advantages concentrating among vertically consolidated service providers. The vendor base organizes around three strategic archetypes: full-stack venue technology suites, modular software-as-a-service platforms, and component-specialist hardware suppliers. M&A activity targets API middleware capabilities bridging legacy POS systems, while strategic partnerships secure exclusive venue inventory relationships.
Within the full-stack tier, Ticketmaster and CTS Eventim exemplify platform consolidation through captive venue relationships and integrated content distribution. Eventbrite occupies a position among modular self-service providers targeting independent promoters with lower-touch deployment models. Scheidt and Bachmann represent the hardware-specialist archetype, anchoring European transit and venue credentialing infrastructure through decades-long municipal relationships.
| Leading Market Players |
|---|
| Ticketmaster |
| Eventbrite |
| StubHub |
| Cubic Corporation |
| Thales |
| Conduent |
| Scheidt and Bachmann |
| AXS |
| CTS Eventim |
| Others |
Value Network & Pricing Analysis
Foundry undercapacity at TSMC and Samsung is compressing NFC controller availability and forcing tiered pricing spreads between standard and configured-to-order hardware bundles. Venue operators absorb longer procurement cycles while suppliers prioritize high-volume entertainment contracts over municipal buyers.
Pricing Analysis
The customization-premium spread separates standard SaaS subscription tiers from configured-to-order deployments with legacy POS middleware and biometric edge computing. Pricing stratifies across premium, standard, and economy tiers based on ISO 27001 certification status and after-sales integration support. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting on-premise incumbents. Municipal venues with seven-year replacement cycles exhibit highest price sensitivity; Bundesliga franchises with captive subscriber bases show lowest.
Supply Chain Analysis
Export control regimes on advanced semiconductor manufacturing equipment limit NFC and RFID chip flows from Taiwan and South Korea to Chinese packaging facilities. Component sourcing draws from German precision optics for facial recognition cameras, Japanese sensor arrays, and Malaysian assembly plants. Single-source vulnerability concentrates in TSMC's advanced node capacity for edge-AI processors. Distribution runs through CTS Eventim's captive venue networks in Central Europe and Ticketmaster's exclusive stadium partnerships in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated entertainment groups with multi-venue portfolios, fragmenting pricing leverage previously held by standalone municipal operators.
For Market Incumbents: Entrench platform stickiness through backward integration into biometric edge hardware and exclusive content distribution rights. Defend against modular SaaS challengers by embedding dynamic capacity algorithms into season-ticket subscription bundles. Prioritize BfDI-compliant data residency certifications to lock out non-European competitors from German municipal RFPs. For New Entrants and Emerging Players: Build out API-first middleware capabilities bridging 1990s-era concession POS systems at historic theaters and opera houses. India's IPL cricket infrastructure offers the most penetrable geography, with fragmented supplier relationships and no dominant platform incumbent. Pursue venue relationships through UPI-linked mobile credential pilots before international entrants establish presence. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because biometric-permissive North American jurisdictions will sustain code-base divergence from EU AI Act-restrictive markets for the decade. Target acquisition candidates with hybrid cloud-edge architectures and existing CNIL consent workflow deployments. Watch for BfDI enforcement actions against facial template retention violations as the inflection signal for compliance-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Edge Hardware Integration | On-device facial processing satisfies GDPR data residency rules for EU AI Act compliance. |
| Legacy POS Middleware Development | API bridging captures 40% of deployment timelines at historic venues with scarce embedded systems expertise. |
| ISO 27001 Certification Investment | Enterprise security management wins municipal and government venue procurement contracts. |
| Subscription Season Access Models | Flexible seating bundles concentrate buyer relationships and reduce last-minute inventory risk. |
| Blockchain Credential Pilot | Non-transferable tokenized tickets eliminate secondary market fraud for Dutch music promoters. |
Research Methodology
A spread of perspectives from venue technology procurement officers, cloud platform engineers, stadium operations directors, and regulatory compliance specialists converged on the working assumptions. Primary fieldwork combined structured interviews with CTS Eventim and Ticketmaster integration teams alongside secondary validation through SEC filings, EU AI Act regulatory texts, and BfDI enforcement databases. Bottom-up segment sizing triangulated against top-down venue capacity and event frequency estimates.
Demand-supply balance modeling anchored volume projections across the analysis window, with technology adoption curves segmented by deployment model, end-user venue type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted pricing trajectories and replacement cycle timing. Cloud-native platform penetration rates and NFC wallet integration velocity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed entrants or accelerated EU AI Act enforcement would shift outcomes. Material shifts in semiconductor foundry capacity allocation or biometric storage regulation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
IPTV Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Electrical Digital Twins Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
Poland ICT Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Service Mesh Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Global Smart Workplace Market
Digital Solutions
Cultivation Management Software Market