
 API Monetization Platform Market | 2026-2036
API Monetization Platform Market Size, Share, and Industry Trends Forecast 2026-2036
API Monetization Platform Market Outlook
Banking and fintech adoption is broadening the API Monetization Platform Market beyond traditional technology vendors. RapidAPI leverages a marketplace model that aggregates third-party interfaces for enterprise procurement teams. WSO2 anchors its position through open-source middleware roots and deep hybrid deployment capabilities. Apigee dominates cloud-native gateway deployments among Fortune 500 accounts seeking centralized policy management.
An API monetization platform is a software infrastructure layer that meters, prices, and settles access to programmable interfaces through policy engines, rate limiters, and billing connectors. These systems enforce throttling rules, authenticate subscribers, and generate usage-based invoices across RESTful, GraphQL, or WebSocket protocols. Cloud-based deployment leads in absolute revenue contribution due to hyperscaler co-selling and reduced infrastructure overhead. Subscription and freemium service types capture the fastest expansion as platform vendors seek to lower developer onboarding friction. GraphQL technology segments are gaining share where mobile and IoT clients demand efficient payload control.
The EU's PSD2 and GDPR frameworks mandate secure, consent-driven API access in financial services, while the U.S. Consumer Financial Protection Bureau supervises emerging open banking rulemakings. HIPAA constrains healthcare API monetization in the United States by requiring audit trails and patient authorization workflows. Stakeholders must monitor how sector-specific compliance layers fragment platform standardization and where regional regulatory divergence creates localization costs.
Market Dynamics
Open banking mandates and hyperscaler co-selling arrangements are compressing procurement cycles while fragmenting vendor selection criteria across enterprise buyers. Platform vendors must now simultaneously satisfy financial-grade compliance requirements and cloud-native deployment expectations.
Growth Catalysts
- PSD2 Compliance Mandates:European banks must expose payment initiation and account information interfaces through standardized APIs, creating captive demand for metering and billing infrastructure.
- Healthcare Data Liquidity:HIPAA-authorized patient access APIs in the United States require audit-capable monetization layers for third-party application developers.
- GraphQL Protocol Expansion:Mobile and IoT developers are migrating from REST to GraphQL for payload efficiency, forcing gateway vendors to support query complexity pricing models.
Market Restraints
- Cloud Concentration Risk:Hyperscaler marketplace fees and egress pricing create vendor lock-in that constrains multi-cloud deployment strategies for mid-market buyers.
- OAuth Token Management Costs:Cryptographic key rotation and consent record storage impose per-transaction overhead that erodes margin at high-volume tiers.
- Legacy SOAP Integration Drag:Enterprise core systems running SOAP protocols require protocol translation layers that increase latency and operational complexity.
Strategic Opportunities
- India UPI Ecosystem:The National Payments Corporation of India's open API specifications for real-time settlements create whitespace for localized billing orchestration platforms.
- AI Model Access APIs:Large language model providers need usage-based metering for token consumption, converging inference infrastructure with monetization tooling.
- Brazil Open Finance:Banco Central do Brasil's phased implementation timeline creates a regulatory tailwind for consent management and pricing engine vendors.
Industry Challenges
- DevOps Skill Scarcity:Platform operators struggle to hire engineers proficient in both Kubernetes ingress configuration and financial-grade audit logging.
- Multi-Protocol Certification Delays:SOC 2 Type II attestation for WebSocket traffic inspection extends sales cycles by four to six months in regulated verticals.
- Rate Limit Algorithm Standardization:Inconsistent sliding window implementations across gateway vendors complicate migration and pricing model portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | API Monetization Platform Market |
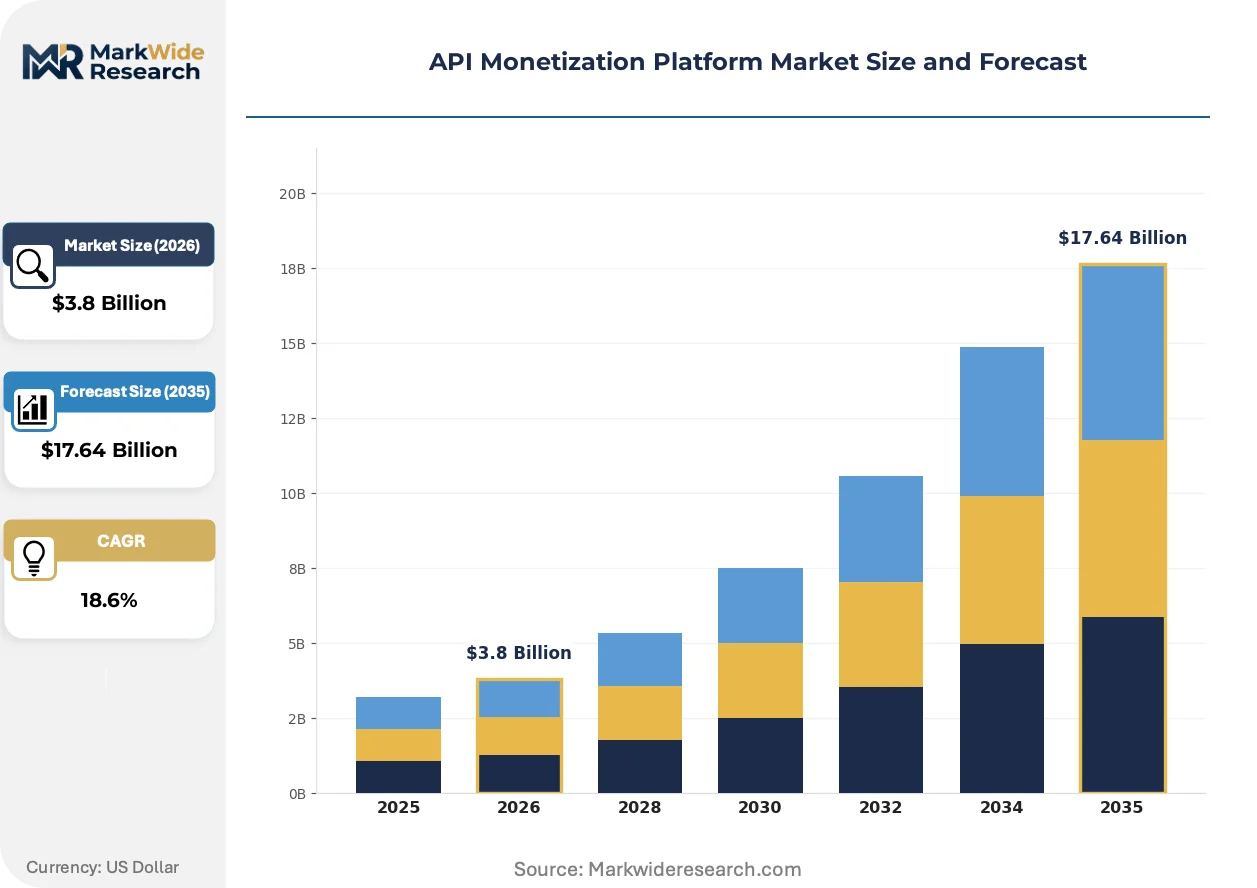
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription Model, Pay-Per-Use, Freemium, Revenue Sharing Deployment: Cloud-Based, On-Premises, Hybrid, Multi-Cloud Customer Type: Startups, Enterprises, SMBs, Developers Technology: RESTful APIs, GraphQL, SOAP, WebSocket |
| Companies Covered | DigitalAPICraft, RapidAPI, Apiable, KrakenD, Tyk Technologies, WSO2, Stigg, Zuplo, Apigee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
API Monetization Platform Market Strategic Shifts
Event-driven architecture patterns and embedded finance integrations are dissolving the boundary between API infrastructure and core business logic. Platform vendors now compete on developer experience metrics rather than raw throughput specifications.
API analytics engines are converging with real-time billing settlement systems to enable usage-based pricing with sub-hour invoicing granularity. Fintech developers in the United States and Germany are piloting these capabilities for high-velocity trading interfaces. This convergence is compressing the traditional separation between technical operations and financial operations teams within platform buyers.
The EU AI Act's risk classification framework imposes audit trail requirements on automated decision-making APIs that affect consumer credit or insurance pricing. Financial services deployers must now maintain explainability logs alongside standard access logs. Healthcare and recruitment API providers face the steepest compliance curve as they rearchitect inference pipelines for Article 14 transparency mandates.
Enterprise procurement teams are unbundling gateway functionality from full-stack platform contracts, selecting best-of-breed metering engines separate from policy enforcement layers. Systems integrators in the United Kingdom and Singapore are capturing margin by orchestrating multi-vendor deployments. This pattern fragments vendor account control and accelerates replacement cycles for incumbent platform providers.
API Monetization Platform Market Segmentation
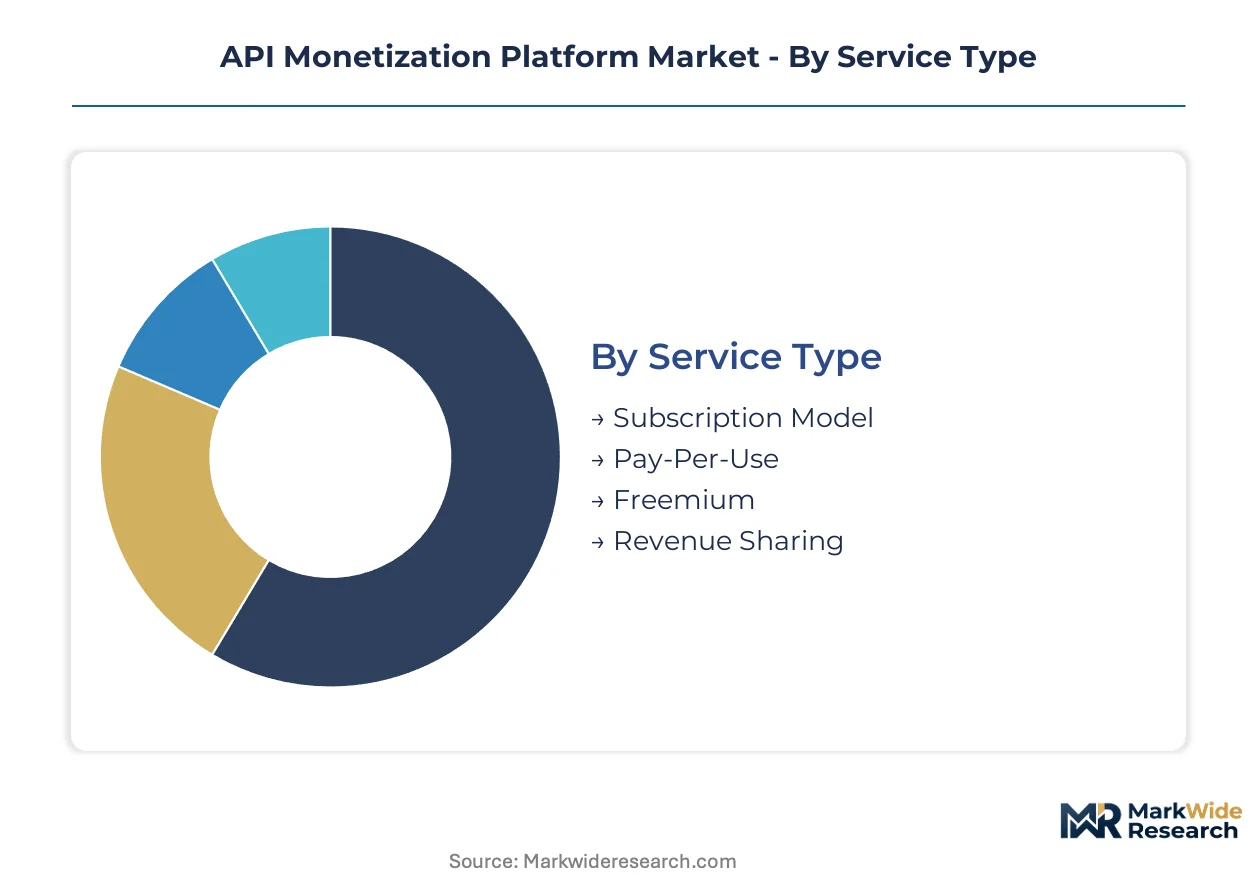
API monetization platforms fragment across service models, infrastructure choices, and technical protocols. Each segmentation dimension carries distinct procurement patterns and margin structures that shape vendor positioning.
Service Type:
Standalone billing engines integrate with external policy gateways, while embedded monetization modules ship inside full-stack platform contracts. The integration depth determines whether procurement teams unbundle metering from enforcement layers.
- Subscription Model:Fixed recurring fees for predictable API access tiers. Enterprise SaaS vendors in the United States favor this structure for budget certainty in multi-year procurement cycles.
- Pay-Per-Use:Metered consumption billing with granular rate cards. Fintech developers in Germany and Singapore pilot sub-hour settlement granularity for high-velocity trading interfaces.
- Freemium:Tiered access with zero-cost entry thresholds. Developer onboarding friction drops sharply when evaluation requires no procurement approval.
- Revenue Sharing:Percentage-based splits between API provider and platform operator. Marketplace aggregators deploy this model to align incentives with third-party developer success.
Subscription models anchor current revenue volumes; freemium structures are expanding most quickly.
Deployment:
Cost tiering separates hyperscaler-native deployments from self-managed infrastructure requiring dedicated DevOps investment.
- Cloud-Based:Fully managed SaaS delivery with hyperscaler backend integration. Reduced infrastructure overhead drives absolute revenue concentration in this category.
- On-Premises:Customer-controlled hardware with direct policy engine installation. Financial institutions in Switzerland and Germany mandate this model for data sovereignty compliance.
- Hybrid:Split traffic processing between cloud gateways and local enforcement nodes. Mid-market buyers balance latency requirements against operational complexity.
- Multi-Cloud:Orchestration across AWS, Azure, and GCP environments simultaneously. Egress pricing arbitrage motivates procurement but increases configuration overhead.
Cloud-based deployments dominate absolute spend; multi-cloud configurations show the steepest expansion trajectory.
Customer Type:
Maturity gradients separate procurement teams with formal vendor management processes from individual developers with credit-card purchasing authority.
- Startups:Venture-backed companies prioritizing speed-to-market over compliance depth. Freemium tiers and self-service onboarding dominate acquisition funnels.
- Enterprises:Fortune 500 procurement teams with SOC 2 attestation requirements. Centralized policy management and audit logging drive selection criteria.
- SMBs:Mid-market companies lacking dedicated platform engineering staff. Managed service wrappers reduce internal skill requirements.
- Developers:Individual practitioners and small teams building side-project integrations. Documentation quality and SDK availability outweigh enterprise-grade features.
Enterprises generate the highest contract values; developer segments show the fastest user base growth.
Technology:
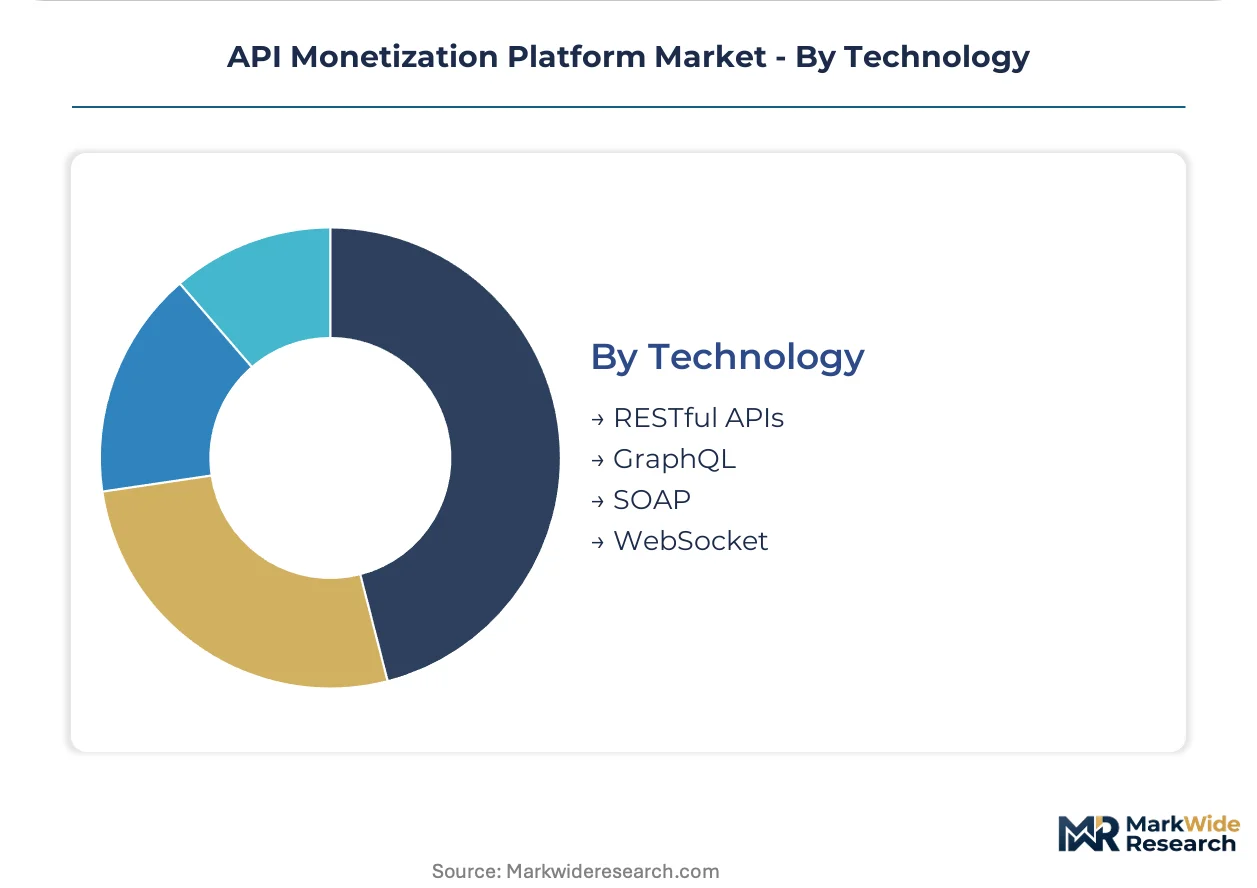
Protocol selection determines payload efficiency, caching behavior, and the complexity of usage-based pricing models.
- RESTful APIs:Stateless HTTP request-response patterns with standardized verb semantics. Mature tooling ecosystems and broad developer familiarity sustain dominance.
- GraphQL:Query languages allowing clients to specify exact field requirements. Mobile and IoT developers in the United States migrate here for payload efficiency.
- SOAP:XML-based protocols with rigid schema definitions. Legacy enterprise core systems in banking and healthcare require protocol translation layers.
- WebSocket:Persistent bidirectional connections for real-time data streams. Trading platforms and collaborative applications demand sub-second latency guarantees.
RESTful APIs carry the largest transaction volumes; GraphQL adoption is climbing the fastest among new implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley enterprise SaaS procurement teams drive the highest absolute platform spending worldwide. Cloud hyperscaler co-selling arrangements compress deployment timelines across North American and European financial centers. Regulatory divergence between PSD2-mandated Europe and emerging open banking frameworks in Asia-Pacific fragments vendor localization requirements.
United States
Fortune 500 technology and financial services procurement teams dominate enterprise contract values. The Consumer Financial Protection Bureau supervises emerging open banking rulemakings that will mandate standardized data sharing interfaces. New York City and San Francisco Bay Area fintech clusters pilot sub-hour billing settlement for high-velocity trading APIs.
Germany
Automotive OEMs and industrial machinery manufacturers demand hybrid deployment models for data sovereignty compliance. BaFin implements PSD2 technical regulatory standards that enforce strong customer authentication and consent management. Frankfurt's financial services cluster anchors European payment initiation API standardization efforts.
United Kingdom
Open Banking Implementation Entity specifications drive standardized account information and payment initiation interfaces. The Financial Conduct Authority mandates operational resilience requirements for critical third-party API providers. London's fintech corridor concentrates marketplace lending and embedded finance API development.
India
The National Payments Corporation of India's UPI ecosystem creates captive demand for real-time settlement billing orchestration. RBI guidelines on account aggregators mandate consent-driven data sharing frameworks for financial information. Mumbai and Bangalore technology parks host domestic platform engineering teams serving Southeast Asian expansion.
Singapore
Wealth management and trade finance institutions seek multi-protocol gateway certification for ASEAN cross-border operations. Monetary Authority of Singapore API exchange guidelines establish security and data standards for financial services interoperability. The island nation's technology corridor serves as regional headquarters for platform vendors targeting Indonesia and Vietnam markets.
API Monetization Platform Market Competitive Environment
Strategic partnership formation dominates the current landscape as platform vendors seek to unbundle gateway and metering functionality. The vendor base separates into three tiers: cloud-native SaaS providers, open-source rooted middleware specialists, and API marketplace aggregators. Two archetypes define competitive positioning: full-stack platform vendors defending account control through bundled contracts, and best-of-breed component suppliers capturing unbundling procurement trends. Technology licensing and vertical capability expansion represent the dominant competitive moves as vendors extend into AI model access metering and embedded finance orchestration.
Within the open-source middleware tier, WSO2 exemplifies hybrid deployment specialization for regulated European financial institutions. RapidAPI occupies a position as marketplace aggregator serving developer-centric procurement with freemium onboarding structures. Apigee anchors the cloud-native tier among Fortune 500 accounts seeking centralized policy management through hyperscaler-native delivery.
| Leading Market Players |
|---|
| DigitalAPICraft |
| RapidAPI |
| Apiable |
| KrakenD |
| Tyk Technologies |
| WSO2 |
| Stigg |
| Zuplo |
| Apigee |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between SOC 2 Type II attested platforms and self-managed open-source deployments manifests in both subscription pricing and infrastructure sourcing patterns. Premium-tier vendors pass through hyperscaler egress fees and audit compliance costs, while commodity-tier offerings draw from distributed engineering talent pools to compress implementation timelines.
Pricing Analysis
Input-cost pass-through from hyperscaler compute and egress pricing dominates SaaS-tiered subscription structures across the analysis window. Price differentiation separates financial-grade compliance bundles from developer-centric freemium tiers, with volume scale and audit trail depth as primary levers. Pricing pressure stems from mid-market buyers unbundling gateway and metering functions to optimize procurement spend. Startups exhibit highest price sensitivity, while Fortune 500 procurement teams prioritize budget certainty over per-unit optimization.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler-native platform vendors concentrated in the United States, Ireland, and Singapore data center regions. Core dependencies include Kubernetes orchestration layers, cryptographic key management hardware, and real-time analytics streaming infrastructure. Supply chain risk centers on tariff exposure for EU-based financial institutions sourcing US cloud infrastructure under evolving digital sovereignty frameworks. Distribution runs through direct enterprise sales teams, hyperscaler marketplace listings, and systems integrator channels serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in API monetization platforms rests on automation-driven cost compression in policy engine deployment and the shift toward premium compliance-tier subscriptions. Infrastructure abstraction and AI-powered metering analytics enable vendors to capture value previously lost to manual configuration overhead.
For Market Incumbents: Deepen hybrid deployment capabilities to defend against emerging cloud-native entrants targeting European data sovereignty requirements. Incumbents should anchor account control through bundled compliance certification services, while expanding metering engine R&D into GraphQL query complexity pricing. Threat from unbundling procurement trends demands proactive multi-cloud orchestration investments. For New Entrants and Emerging Players: AI model access metering represents a technology-first wedge into whitespace currently underserved by legacy gateway vendors. New entrants should target India and Brazil regulatory tailwinds for localized billing orchestration, with developer-experience-first go-to-market positioning emphasizing sub-hour settlement granularity. Embedded finance API segments offer lowest competitive density. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor fragmentation complicates enterprise procurement standardization across metering, policy, and settlement layers. Long-term viability favors platforms with proven multi-protocol certification velocity and hyperscaler co-selling traction. Acquisition target archetype: best-of-breed metering engines with financial services customer concentration. Signal to watch: DevOps skill scarcity driving managed service wrapper demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unbundled metering engines from policy gateways compress procurement cycles for Fortune 500 buyers. |
| Strategic Partnership | Hyperscaler co-selling arrangements accelerate deployment timelines in US financial services clusters. |
| Geographic Expansion | Localized billing orchestration captures India UPI and Brazil Open Finance regulatory tailwinds. |
| Product Launch | AI model access metering converges inference infrastructure with usage-based pricing tooling. |
| Acquisition of Specialist Firm | GraphQL-native gateway vendors address mobile and IoT payload efficiency demands. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged platform engineering directors, enterprise IT procurement officers, fintech integration leads, and systems integrator partners across North America, Europe, and Asia-Pacific. Secondary validation drew from SEC filings of publicly traded SaaS vendors, hyperscaler capex disclosure reports, open banking regulatory filings with the CFPB and BaFin, and API marketplace transaction data. Bottom-up segment sizing triangulated against top-down IT spend allocation models.
Segment-weighting approaches distributed value estimates across deployment models, service types, customer maturity tiers, and protocol technology segments. CAGRs were derived from fitted growth curves incorporating adoption velocity indicators, regulatory mandate timelines, and cloud infrastructure expansion rates. Industry-specific inputs included PSD2 compliance deadline progressions, HIPAA audit trail requirement evolutions, and GraphQL developer survey adoption metrics across the projection horizon.
The model holds under stable regulatory enforcement and sustained hyperscaler infrastructure investment; deviation in digital sovereignty legislation or AI Act implementation rigor would shift trajectory assumptions. Forecasts reflect documented base-case conditions with acknowledged sensitivity to DevOps labor market tightness and multi-cloud egress pricing volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
India PLM Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Digital Pen Market
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Smart Dictation Systems Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Barcode Software Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Cloud Manufacturing Execution System (MES) Market