
 EMEA Corrugated Board Packaging Market | 2026-2036
EMEA Corrugated Board Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Corrugated Board Packaging Market Foresight
Digital print integration into corrugated production lines is fragmenting legacy manufacturing workflows across Europe and the Middle East. Smurfit WestRock leverages high-volume containerboard capacity to sustain pricing power in Iberia and North Africa. Mondi plc anchors specialty kraftliner supply for premium fresh-produce exporters. Saica S.A. dominates recovered fiber sourcing across Mediterranean recycling networks.
EMEA corrugated board packaging consists of fluted paperboard sheets laminated between flat linerboards, typically manufactured through corrugating processes using recycled pulp or virgin kraft fibers with flute profiles ranging from A-flute to micro-flute formats. The material functions primarily as protective, stackable, and printable secondary packaging for shipping, retail display, and industrial distribution across consumer and business supply chains. Single-wall and double-wall product types lead volume throughput in high-velocity e-commerce and grocery channels, while die-cut formats capture margin pools in branded unboxing experiences and automated packing lines. Food and beverage end users drive baseline demand for moisture-resistant and grease-barrier board grades, whereas healthcare and electronics segments pull higher-specification triple-wall and anti-static insert configurations.
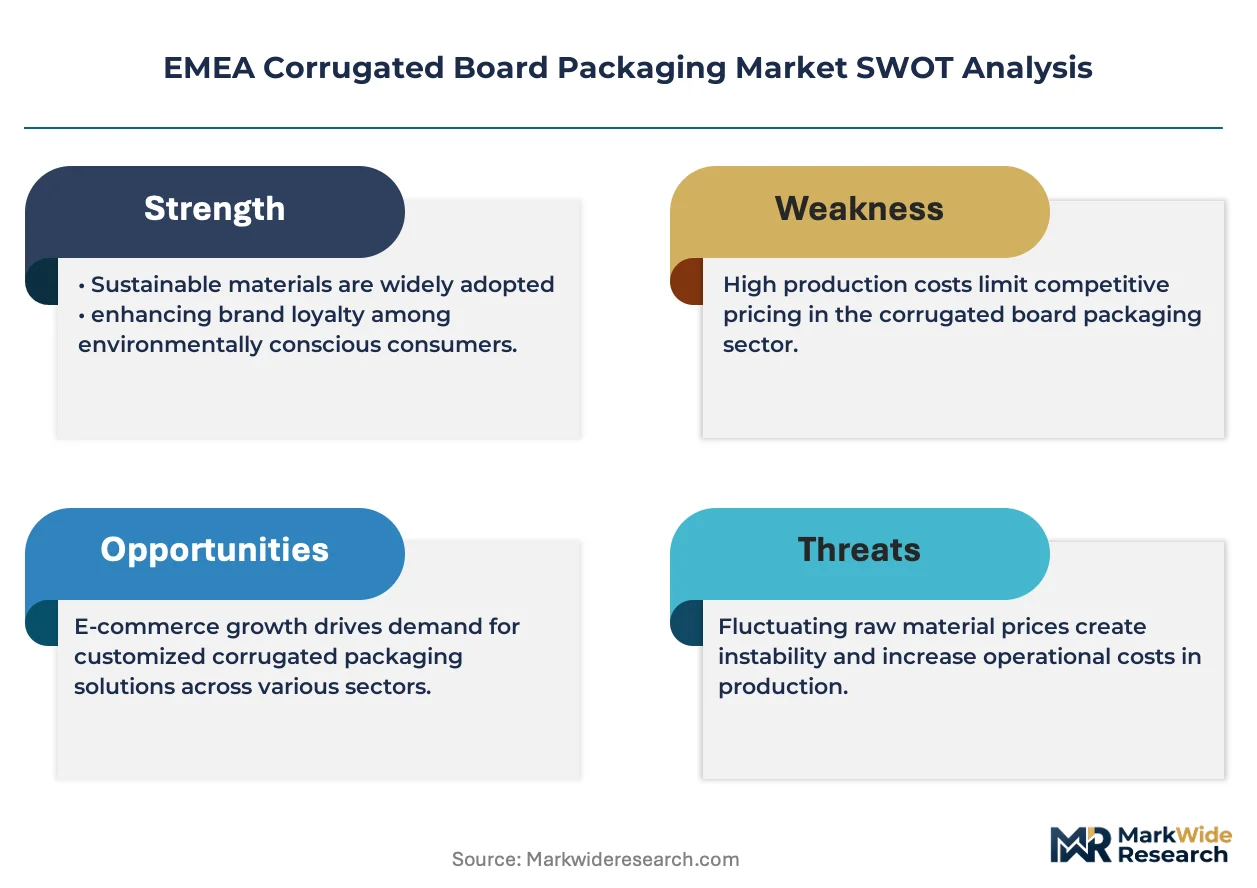
The EU Packaging and Packaging Waste Regulation (PPWR) mandates extended producer responsibility and recyclability thresholds that reshape board composition requirements across member states. ECHA REACH compliance restricts certain chemical treatments in water-resistant coatings, pushing mills toward bio-based barrier alternatives. FSC and PEFC chain-of-custody certification operates as a de facto market-access condition for branded FMCG procurement teams across Northern Europe. Stakeholders must monitor how divergent national transposition timelines for PPWR enforcement create compliance complexity for multi-country supply chains.
Market Dynamics
Digital print integration into corrugated production lines is fragmenting legacy manufacturing workflows across Europe and the Middle East. E-commerce fulfillment networks in Germany and France are accelerating format specialization while the EU PPWR reshapes material compliance requirements.
Growth Catalysts
- E-commerce fulfillment networks:Die-cut and double-wall formats gain pull from automated packing lines in France and Germany. Temperature-controlled food logistics expand moisture-resistant board specifications.
- EU PPWR mandates:Extended producer responsibility requirements drive recyclability investments. Member states accelerate material recovery target adoption.
- Fresh-produce export demand:Specialty kraftliner specifications rise for premium agricultural shipments from Iberia and Mediterranean ports.
Market Restraints
- Recovered fiber cost volatility:Mediterranean recycling network disruptions constrain pulp input stability. Saica S.A.'s dominance in regional fiber sourcing creates supply concentration exposure.
- ECHA REACH coating restrictions:Water-resistant chemical treatments face compliance friction. Mills redirect capital toward bio-based barrier development.
- Plastic substitution competition:Flexible film alternatives capture lightweight shipping applications. Corrugated weight penalties disadvantage certain parcel categories.
Strategic Opportunities
- North African production expansion:Iberian containerboard capacity extends into Moroccan and Tunisian markets. Smurfit WestRock leverages existing infrastructure for regional supply positioning.
- Healthcare anti-static specifications:Electronics and pharmaceutical segments pull triple-wall insert configurations. Higher-margin specialty grades offset commodity board compression.
- FSC-PEFC certification premiums:Northern European FMCG procurement teams mandate chain-of-custody documentation. Certified suppliers capture branded contract pools.
Industry Challenges
- Digital print technician scarcity:Corrugator workforce gaps constrain high-velocity line integration. Training pipelines lag equipment deployment timelines.
- PPWR transposition complexity:Divergent national enforcement schedules fragment compliance architecture. Multi-country supply chains face jurisdictional coordination costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Corrugated Board Packaging Market |
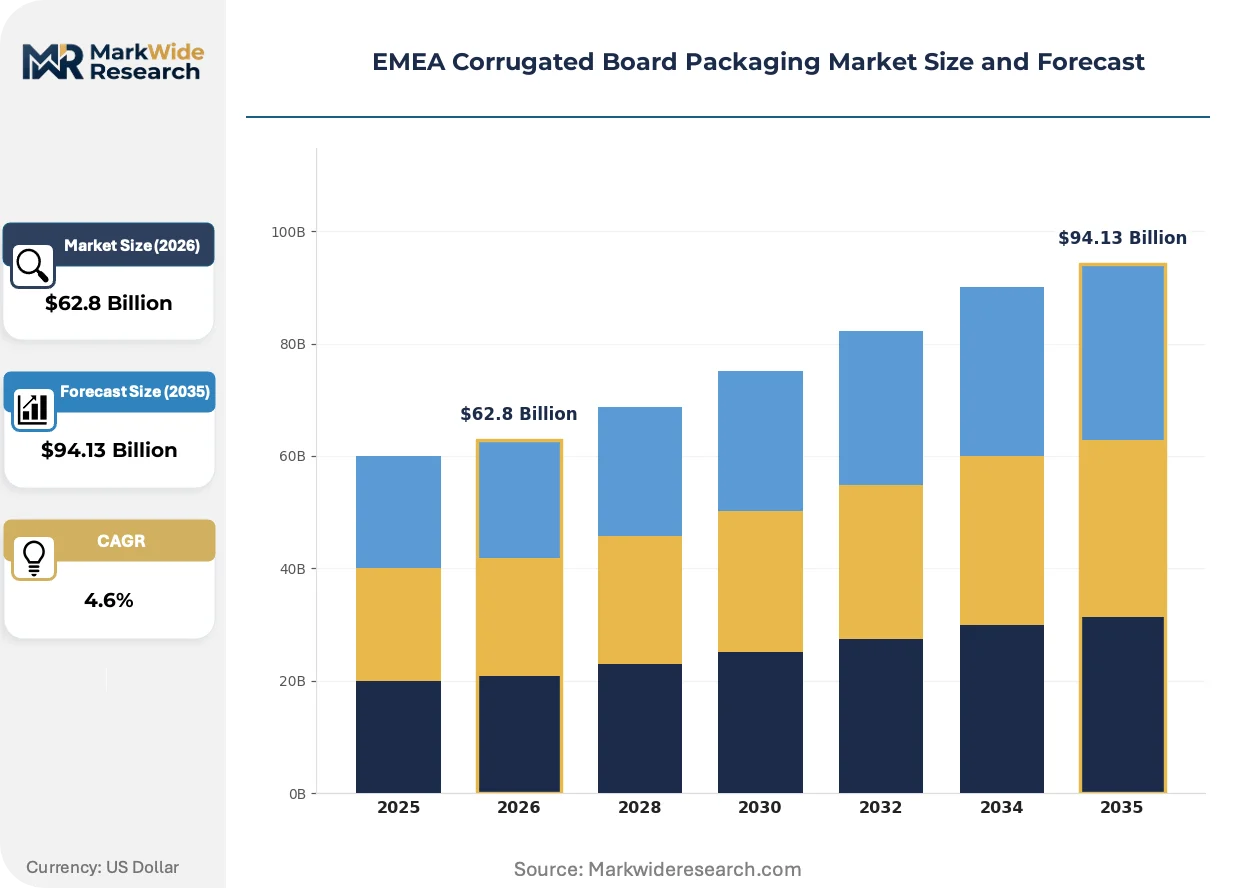
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $94.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Die-cut End User: Food & Beverage, Electronics, Healthcare, Personal Care Packaging Type: Boxes, Trays, Wraps, Inserts Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers |
| Companies Covered | DS Smith PLC, Saica S.A., Smurfit WestRock, Sealed Air Corporation, WestRock Co., Mondi plc, Stora Enso Oyj, SCA Group, International Paper Company, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Corrugated Board Packaging Market Shifts & Advancements
Automation and sustainability mandates are converging to reconfigure production economics across EMEA corrugated operations. Three developments are compressing legacy cost structures while opening premium service tiers.
Digital print technology is virtualizing pre-press workflows and enabling lot-size-one production economics. FMCG brand teams in the Netherlands and Belgium adopt variable-data corrugated for seasonal campaigns. Short-run flexibility is virtualizing the traditional volume-makes-unit-economics model that favored long production runs.
EU PPWR recyclability thresholds are forcing linerboard recomposition across member states. Mills in Poland and the Czech Republic retrofit corrugators for higher recycled-content specifications. Food and beverage exporters face the steepest compliance curves as grease-barrier coatings fall under enhanced scrutiny.
Subscription-box procurement models are consolidating buyer power among specialized e-commerce enablers. Third-party logistics providers in the UK and Germany now specify custom die-cut formats as standard. Unboxing experience requirements pull branded corrugated away from commodity auction dynamics toward specification-driven contracting.
EMEA Corrugated Board Packaging Market Segmentation
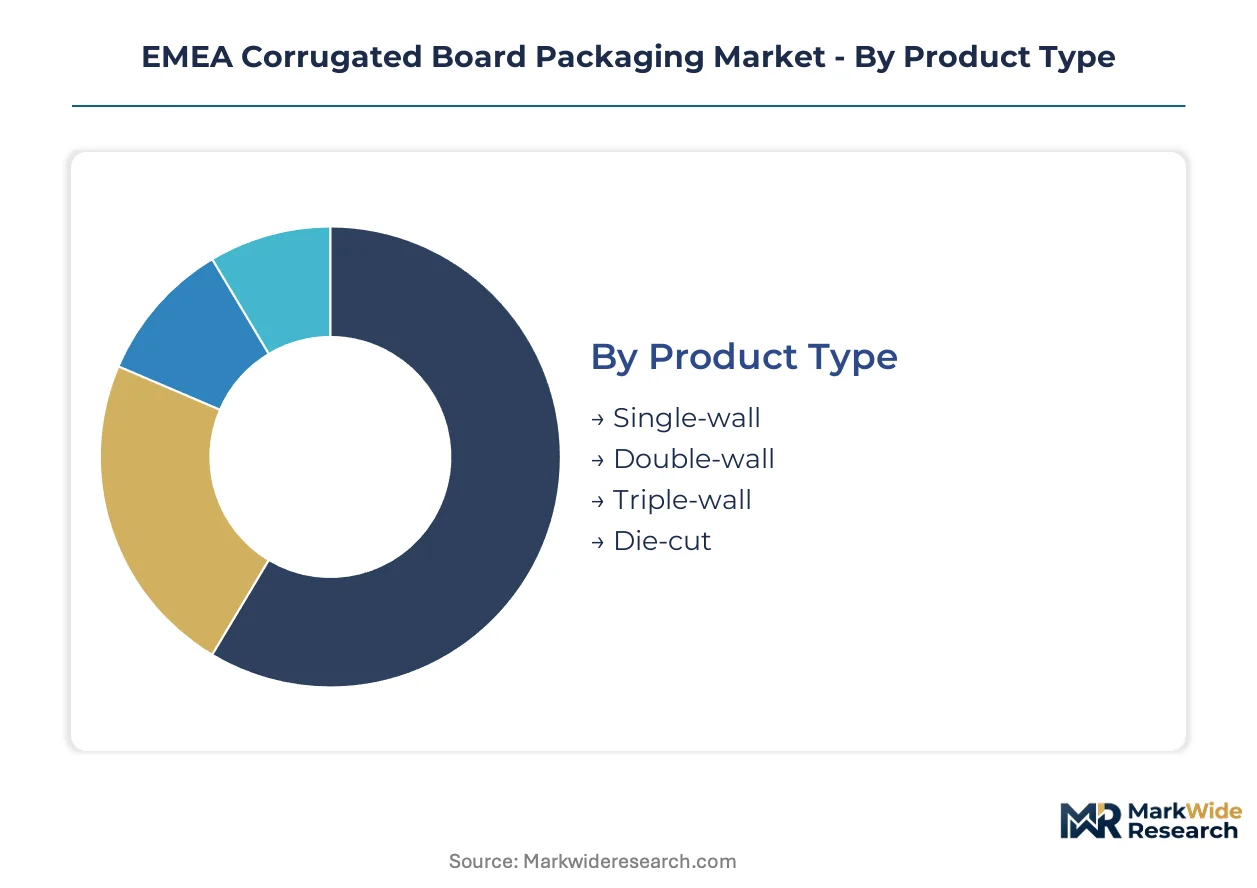
Corrugated packaging segmentation in EMEA reflects divergent velocity requirements across supply chains. Fast-turn e-commerce channels pull lightweight formats with compressed lead times, while industrial applications sustain longer production cycles for heavy-duty specifications.
Product Type:
Cycle times vary dramatically: single-wall formats turn in hours for high-velocity grocery replenishment, whereas triple-wall production stretches across days for capital-goods protection.
- Single-wall:One fluted medium sandwiched between linerboards delivers baseline protection for lightweight consumer goods. German and French e-commerce fulfillment networks absorb the highest volumes as automated packing lines demand consistent caliper and crush resistance.
- Double-wall:Two fluted layers provide enhanced stacking strength for medium-weight shipments. Temperature-controlled food logistics across Iberia and the Mediterranean specify moisture-resistant double-wall grades for shelf-stable distribution.
- Triple-wall:Three-layer construction serves heavy industrial and export applications requiring maximum load-bearing capacity.
- Die-cut:Custom-engineered blanks enable precision-fit unboxing experiences with minimal void fill.
Single-wall dominates installed base. Die-cut is where expansion concentrates.
End User:
Application requirements stratify by barrier specifications and regulatory exposure, with food-grade compliance commanding premium qualification cycles.
- Food & Beverage:Grease-resistant and moisture-barrier board grades protect temperature-sensitive and shelf-stable goods. EU PPWR recyclability thresholds force linerboard recomposition as mills retrofit for higher recycled-content specifications.
- Electronics:Anti-static and shock-absorbing insert configurations protect high-value components. Triple-wall and specialty-coated grades gain traction in semiconductor and device distribution.
- Healthcare:Sterile barrier compatibility and traceability documentation meet pharmaceutical supply chain protocols.
- Personal Care:Premium unboxing aesthetics drive branded die-cut adoption for subscription-box and retail-ready formats.
Food & Beverage anchors volume throughput. Electronics is climbing the fastest on margin expansion.
Packaging Type:
Format selection tracks handling automation levels, with rigid containers suiting palletized distribution and flexible wraps aligning with parcel networks.
- Boxes:Rigid six-panel construction remains the default for palletized shipping and warehouse storage. Direct sales channels in Germany and France specify standard RSC formats for ERP system compatibility.
- Trays:Open-top designs support retail-ready produce and beverage multipacks. Iberian fresh-produce exporters pull specialty kraftliner trays for premium agricultural shipments.
- Wraps:Sleeve and envelope formats reduce material intensity for flat goods. E-commerce channels adopt wraps for apparel and soft goods to minimize dimensional weight penalties.
- Inserts:Custom-fit partitions and cushioning components protect fragile contents. Healthcare and electronics segments specify anti-static and shock-absorbing insert configurations.
Boxes dominate installed base. Inserts are gaining share fastest on automation integration.
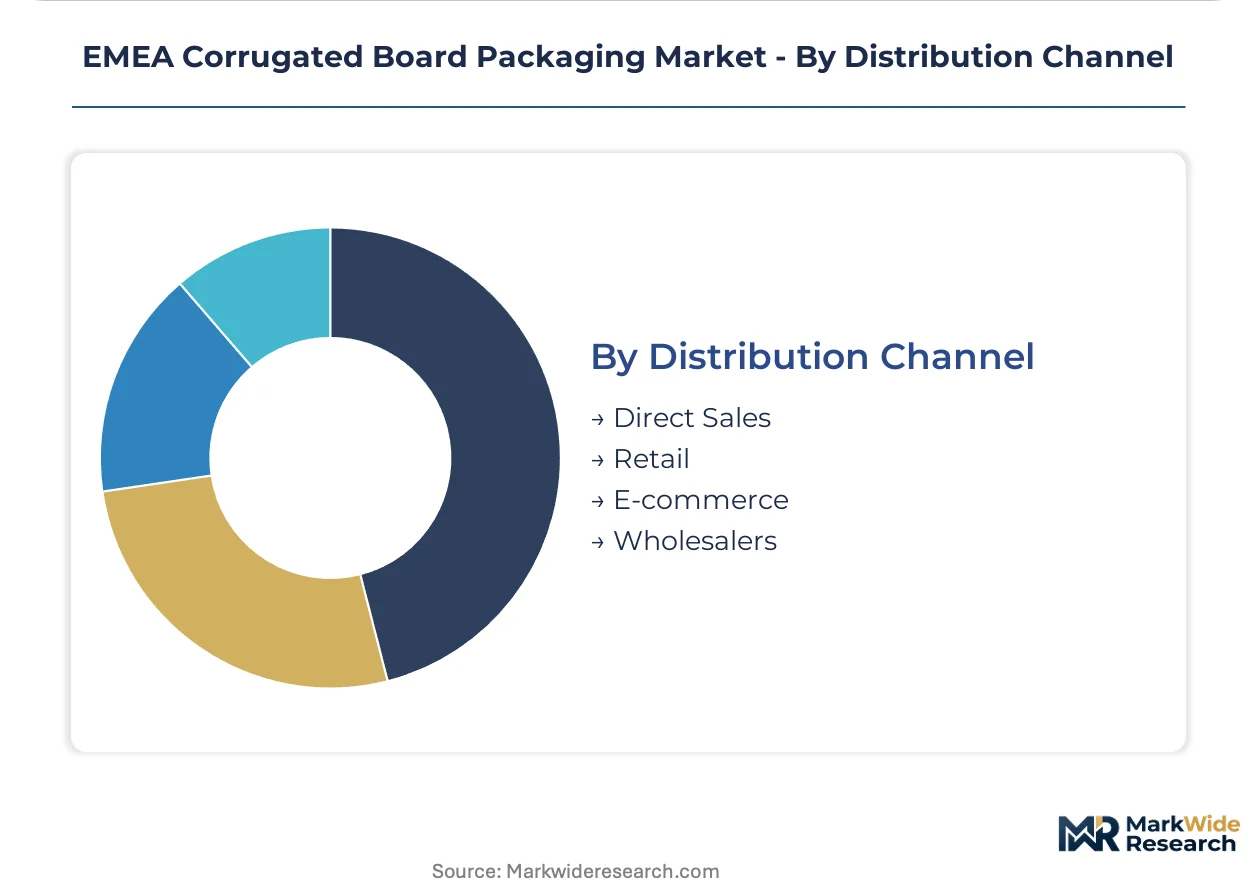
Distribution Channel:
Channel economics diverge by order fragmentation and specification control, with direct relationships enabling customization and wholesale pools commoditizing standard grades.
- Direct Sales:Mill-direct relationships serve high-volume accounts with custom specifications. Northern European FMCG procurement teams mandate FSC-PEFC chain-of-custody documentation through direct contracts.
- Retail:Big-box and grocery chains specify retail-ready packaging with shelf-impact graphics. Belgian and Dutch brand teams adopt variable-data corrugated for seasonal campaigns.
- E-commerce:Third-party logistics providers consolidate buyer power and specify custom die-cut formats as standard. UK and German 3PLs now require unboxing-optimized designs.
- Wholesalers:Inventory pooling serves fragmented small and mid-size accounts with limited specification leverage.
Direct Sales dominates installed base. E-commerce is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German containerboard exports to French e-commerce fulfillment networks anchor cross-border trade flows in the EMEA corrugated board packaging market. Iberian fresh-produce shipments to Northern European retail channels sustain specialty kraftliner demand. Mediterranean recycling networks feed recovered fiber into North African production expansion.
Germany
Automated packing lines in Bavaria and North Rhine-Westphalia pull die-cut and double-wall formats for high-velocity e-commerce channels. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility compliance for exporters. Frankfurt-Rhine-Main logistics clusters concentrate third-party logistics procurement power for specification-driven contracting.
France
Temperature-controlled food logistics across Île-de-France and Hauts-de-France expand moisture-resistant board specifications for shelf-stable distribution. ECHA REACH restrictions on water-resistant chemical treatments push mills toward bio-based barrier alternatives. Lille and Paris distribution hubs consolidate buyer power among specialized e-commerce enablers.
Spain
Premium fresh-produce exporters in Valencia and Andalusia drive specialty kraftliner specifications for agricultural shipments to Northern Europe. FSC and PEFC chain-of-custody certification operates as a de facto market-access condition for branded FMCG procurement teams. Barcelona and Madrid corrugator networks retrofit for higher recycled-content specifications under EU PPWR timelines.
United Kingdom
Subscription-box procurement models in the Southeast and Midlands consolidate buyer power among third-party logistics providers specifying custom die-cut formats. National transposition of EU PPWR enforcement creates compliance complexity for multi-country supply chains. London logistics clusters demand unboxing-optimized designs for branded retail experiences.
Poland
Mills in Silesia and Greater Poland retrofit corrugators for higher recycled-content specifications under EU PPWR recyclability thresholds. Central European location enables containerboard supply positioning for German and Czech export markets. Warsaw and Krakow industrial zones attract investment in digital print integration for short-run flexibility.
EMEA Corrugated Board Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions in the EMEA corrugated board packaging market. Consolidated containerboard capacity anchors pricing power for high-volume standardized grades, while fragmented specialty converters capture premium pools in branded and specification-driven segments. Three archetypes dominate: integrated containerboard-to-box producers, recovered fiber specialists with recycling network control, and premium kraftliner suppliers for agricultural export applications. M&A activity concentrates containerboard assets, while capacity expansion targets North African markets for regional supply positioning.
Among integrated producers, Smurfit WestRock and DS Smith PLC exemplify the scale-driven archetype with extensive containerboard-to-box operations. Mondi plc occupies a position within the specialty kraftliner tier, serving premium fresh-produce export demand from Iberian and Mediterranean ports. Saica S.A. represents the recovered fiber specialist model, anchoring pulp input stability through dominance in Mediterranean recycling networks. These three players illustrate how geographic footprint and raw material access stratify competitive positioning across the EMEA region.
| Leading Market Players |
|---|
| DS Smith PLC |
| Saica S.A. |
| Smurfit WestRock |
| Sealed Air Corporation |
| WestRock Co. |
| Mondi plc |
| Stora Enso Oyj |
| SCA Group |
| International Paper Company |
| Others |
Supply & Pricing Matrix
Recovered fiber cost volatility across Mediterranean recycling networks determines both the spread between virgin kraftliner and recycled-content board grades and the geographic configuration of mill capacity. EU PPWR compliance timelines and ECHA REACH coating restrictions compress margin pools at the commodity tier while opening premium capture opportunities for certified suppliers.
Pricing Analysis
Digital print capability gaps separate pricing tiers between legacy flexo-dependent producers and integrated digital-native operations. Three-tier pricing structure across premium FSC-PEFC certified, standard compliance-grade, and economy recycled-content levels tracks certification investment and barrier technology adoption. Cost compression in single-wall commodity grades intensifies as plastic film substitutes capture lightweight parcel applications. Small and mid-size accounts through wholesale channels exhibit highest price sensitivity, while direct-contract FMCG procurement teams absorb premiums for chain-of-custody documentation.
Supply Chain Analysis
Extended payment terms from German and French e-commerce consolidators strain working capital across Iberian and Mediterranean converter networks. Supply concentrates in Germany, Spain, and Poland for containerboard production, with North African expansion gaining traction. Raw material dependencies center on recovered fiber from Mediterranean recycling networks, virgin kraft pulp from Nordic mills, and bio-based barrier coatings under development. Single-source vulnerability to Saica S.A.'s regional fiber sourcing dominance creates input instability. Distribution runs through direct mill relationships for high-volume accounts and third-party logistics intermediaries for e-commerce specification control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping buyer-supplier relationships as subscription-box procurement models consolidate specification control among specialized e-commerce enablers. Interoperability between automated packing lines and custom die-cut formats is creating winner-take-most dynamics in contract allocation.
For Market Incumbents: Entrench containerboard-to-box integration through captive recovery fiber sourcing and digital print line deployment. Smurfit WestRock's Iberian-North African infrastructure demonstrates how geographic footprint control defends pricing power against plastic substitution threats. Accelerate FSC-PEFC certification coverage to lock in Northern European FMCG contract renewal cycles before PPWR transposition deadlines fragment compliance requirements. For New Entrants and Emerging Players: Pursue healthcare anti-static and triple-wall insert specifications where higher margins offset commodity board compression. Die-cut automation integration for UK and German 3PL channels represents the most penetrable white space, as incumbent workforce gaps constrain high-velocity line deployment. Lead with short-run digital print flexibility to capture seasonal campaign work from Belgian and Dutch brand teams. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors recovered fiber specialists with recycling network control and specialty kraftliner suppliers for agricultural export applications. Long-term viability hinges on backward integration into pulp inputs and certification infrastructure rather than pure capacity scale. Watch for PPWR enforcement acceleration as the signal indicating when compliance-premium capture shifts from optionality to necessity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Line Integration | Virtualizes pre-press workflows for lot-size-one production economics in Netherlands and Belgium. |
| Recovered Fiber Network Expansion | Anchors pulp input stability against Mediterranean recycling network disruption exposure. |
| FSC-PEFC Certification Investment | Unlocks branded FMCG contract pools across Northern European procurement teams. |
| North African Capacity Buildout | Extends Iberian supply positioning into Moroccan and Tunisian regional markets. |
| Bio-Based Barrier Development | Redirects capital from ECHA REACH-restricted water-resistant chemical treatments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory disclosure databases. Interviews with corrugator operations managers, FMCG packaging procurement leads, third-party logistics specification engineers, and recycling network coordinators combined with bottom-up capacity modeling and top-down demand triangulation. Secondary validation drew from EU PPWR implementation timelines, ECHA REACH restriction updates, FSC-PEFC chain-of-custody registries, and containerboard trade flow data.
Forecast inputs include product type segmentation by flute profile and wall construction, end-user demand stratification by barrier specification requirements, packaging format evolution tracking automation integration levels, and distribution channel economics by buyer consolidation patterns. CAGRs derive from production capacity expansion schedules, e-commerce fulfillment network growth trajectories, and regulatory compliance investment cycles across the analysis window. Modeled variables incorporate recovered fiber price volatility assumptions and digital print adoption curves by geography.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated producers or accelerated plastic substitution campaigns would shift outcomes. Macroeconomic deviation in cross-border trade flows, regulatory enforcement acceleration beyond PPWR baseline timelines, or breakthrough bio-based barrier technology commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Global Folding Boxboards Market