
 Refining Additives Market | 2026-2036
Refining Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Refining Additives Market Analytics
Aftermarket formulation services is rewriting margin capture across the refining additives value chain. BASF SE leverages its Ludwigshafen integrated production complex to control precursor supply for antioxidant packages. Evonik Industries specializes in high-performance pour point reducers for arctic fuel grades. Albemarle anchors its position through bromine-derived intermediates that feed multiple additive chemistries.
Refining additives comprise specialty chemical formulations—typically organometallic compounds, polymeric dispersants, or amine-based derivatives—dosed at 50–5000 ppm to upgrade hydrocarbon stream properties during distillation, cracking, or finishing operations. Their primary purpose centers on meeting product specifications for stability, flow, combustion quality, and emissions compliance. Antioxidant demand concentrates in gasoline and jet fuel storage stability applications where peroxide formation degrades product value. Demulsifier formulations command premium pricing in heavy crude processing segments where water-oil separation efficiency determines refinery throughput. The lubricants application channel sustains above-average growth as Group II/III base oil expansion in Asia requires corresponding additive treat rates.
EPA Tier 3 gasoline sulfur standards and IMO 2020 marine fuel specifications compel refiners to deploy higher additive volumes during hydrotreating and blending stages. REACH registration requirements in Europe filter non-compliant suppliers from the antioxidant and defoamer segments. Stakeholders must monitor biofuel mandate escalations in multiple jurisdictions, as fatty acid methyl ester compatibility creates reformulation demands across pour point reducer and demulsifier product lines.
Market Dynamics
The refining additives market faces a structural pivot as sulfur reduction mandates force reformulation of hydrotreating catalyst packages and cold-flow improvers across marine and road fuel segments.
Growth Catalysts
- IMO 2020 marine sulfur caps:Ship operators require low-sulfur residual fuel blends that depend on pour point reducers and combustion improvers to maintain engine operability.
- Group II/III base oil expansion:Asian lubricant producers demand higher treat rates of dispersants and antioxidants to compensate for reduced natural solvency in hydrocracked stocks.
- Arctic fuel logistics:Russian and Canadian pipeline operators deploy wax crystal modifiers to maintain flow assurance in sub-zero transport corridors.
Market Restraints
- Crude slate volatility:Heavy sour feedstock shifts between Venezuelan, Canadian, and Middle Eastern sources destabilize demulsifier formulation economics.
- Precursor supply concentration:Organometallic antioxidant intermediates depend on concentrated bromine and phosphorus derivative production in the US Gulf Coast and Dead Sea regions.
- REACH registration barriers:European Chemicals Agency compliance costs filter small-scale antioxidant and defoamer suppliers from EU market participation.
Strategic Opportunities
- SAF co-processing:Hydrotreated esters and fatty acids in sustainable aviation fuel streams require specialized thermal stability packages absent from conventional jet fuel additive portfolios.
- India BS-VI gasoline:The country's emission standard enforcement creates demand for octane boosters and deposit control additives in expanding refinery capacity.
- Digital dosing systems:Refinery automation vendors integrate real-time additive injection controls that enable precision blending and reduce over-treatment waste.
Industry Challenges
- Specialized formulation chemist scarcity:Expertise in organometallic synthesis and fuel compatibility testing concentrates among retiring technical staff at legacy additive houses.
- Multijurisdictional registration synchronization:Suppliers must sequence EPA, REACH, and China's MEE chemical inventory filings to avoid launch delays in sequential markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refining Additives Market |
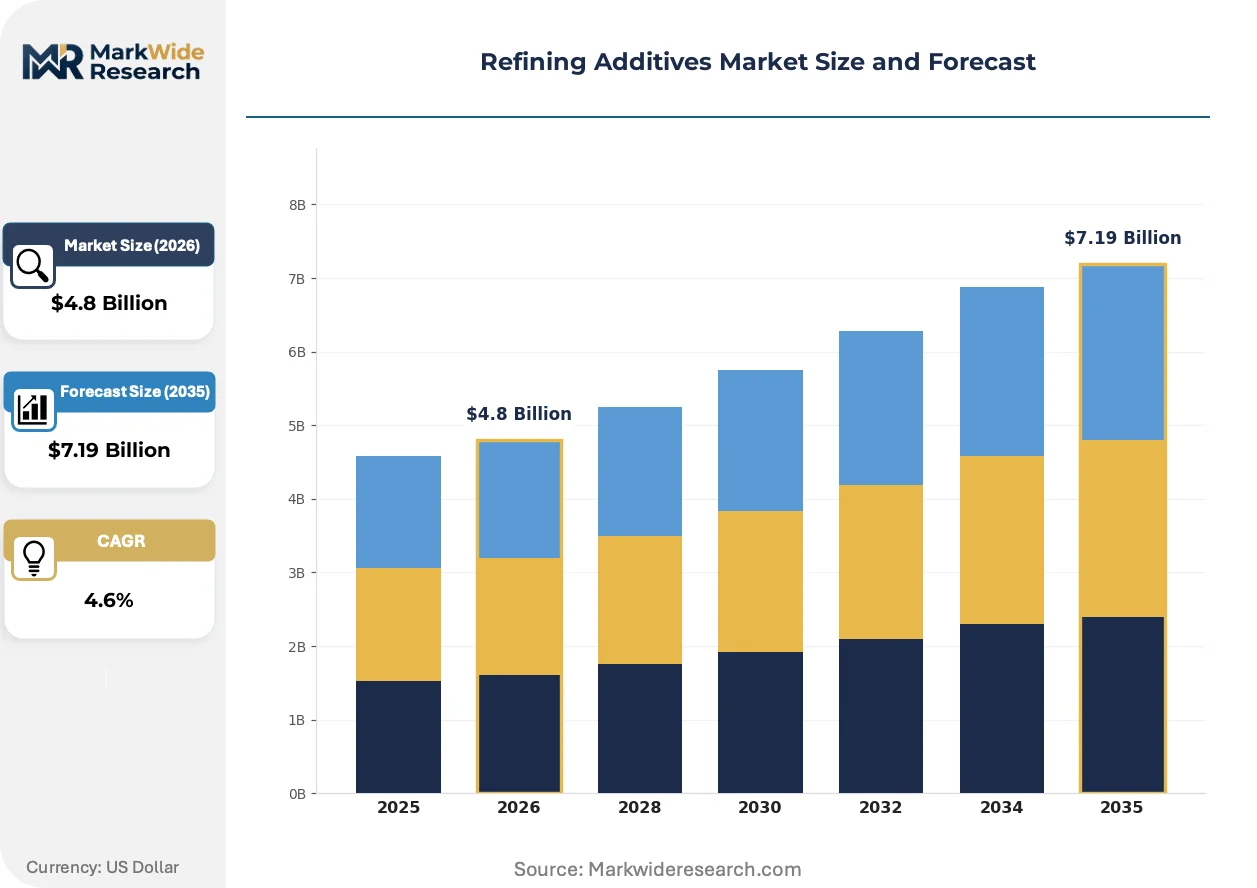
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Demulsifiers, Pour Point Reducers, Defoamers Application: Fuels, Lubricants, Asphalt, Chemicals End User: Oil Refineries, Petrochemical Plants, Chemical Manufacturers, Transport Sector Form: Liquid, Powder, Granule, Concentrate |
| Companies Covered | Dorf Ketal Chemicals, Grace Catalysts Technologies, BASF SE, Arkema, Nalco Company, Clariant, Albemarle, Evonik Industries, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refining Additives Market Evolving Landscape
Formulation science is pivoting toward molecular precision as refiners seek additive systems that perform across widening crude quality variance and tightening product specifications simultaneously.
Polymeric cold-flow improver chemistry is migrating from conventional ethylene-vinyl acetate copolymers toward methacrylate-based comb polymers with tailored side-chain crystallization kinetics. Arctic-grade diesel blenders in Canada and Scandinavia are adopting these materials to achieve lower operability temperatures without wax modifier over-dosage. The shift is compressing demand for traditional pour point depressants in premium fuel segments.
EPA Tier 3 gasoline sulfur standards and parallel state-level low-carbon fuel programs are forcing antioxidant package reformulation to maintain storage stability in ultra-low sulfur substrates. Refiners in California and the US Northeast are qualifying phenolic and aminic antioxidant combinations that compensate for reduced natural inhibition in hydrotreated streams. The regulatory pressure is elevating treat rates in finished gasoline blending operations.
Refinery procurement teams are consolidating additive supply contracts under multi-year framework agreements that bundle technical service, inventory management, and performance guarantees. Integrated oil companies in the US and EU are displacing spot purchasing of individual additive components. The concentration of buying power is compressing margins for standalone specialty chemical distributors.
Refining Additives Market Segmentation
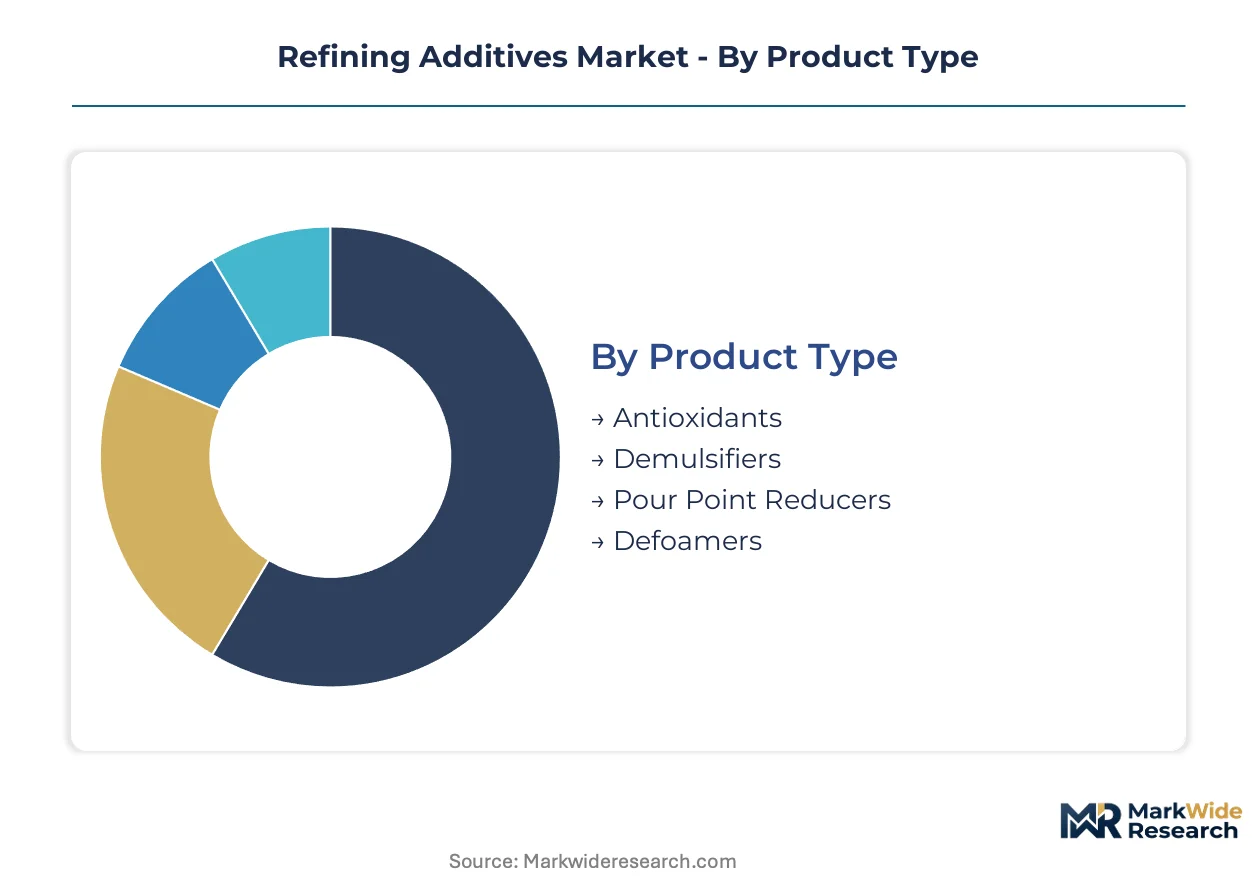
Refining additives segment along four distinct axes that govern procurement patterns and margin structures. Product chemistry determines technical service intensity. Application channel dictates regulatory exposure. End-user scale shapes contract duration and pricing power. Physical form influences logistics costs and dosing system compatibility.
Product Type:
Antioxidants turn over fastest due to continuous gasoline reformulation cycles. Demulsifiers and pour point reducers operate on longer replacement cycles tied to crude slate stability. Defoamers sit at the slowest refresh rate given their standardized hydrotreater applications.
- Antioxidants:Phenolic and aminic formulations stabilize peroxide-sensitive hydrotreated fuels. Demand concentrates in US Gulf Coast and Northeast refineries where EPA Tier 3 sulfur standards have eliminated natural inhibition from gasoline streams. Reformulation cycles accelerate as refiners qualify new base stock blends.
- Demulsifiers:Polymeric surfactant packages separate water from heavy crude emulsions. Canadian oil sands processors and Venezuelan-heavy blenders in the US Midwest deploy specialized chemistries where water-cut variability destroys throughput economics. Crude source switching forces continuous formulation adjustment.
- Pour Point Reducers:Methacrylate comb polymers and ethylene-vinyl acetate copolymers modify wax crystallization kinetics in arctic diesel and marine residual fuels.
- Defoamers:Silicone and polyglycol chemistries suppress foam in hydrotreater and coker units where gas-liquid contact efficiency determines unit capacity.
Antioxidants dominate installed base by volume. Pour point reducers are where expansion concentrates as arctic logistics and marine sulfur regulations tighten simultaneously.
Application:
Fuels applications command premium pricing due to emissions compliance liability. Lubricants offer volume scale through treat rate expansion. Asphalt and chemicals channels operate on commodity economics with thinner technical service margins.
- Fuels:Gasoline, diesel, and marine residual fuel blending requires stability, combustion quality, and cold-flow packages. Indian BS-VI enforcement and IMO 2020 marine specifications drive additive intensity in refineries from Jamnagar to Rotterdam. Regulatory stringency varies sharply by product grade and destination market.
- Lubricants:Dispersant, antioxidant, and antiwear packages compensate for reduced natural solvency in Group II/III hydrocracked base oils. Asian blenders in South Korea and Thailand demand higher treat rates as base oil production shifts toward hydroprocessed stocks. The segment climbs fastest as automotive OEM specifications tighten drain intervals.
- Asphalt:Rheology modifiers and adhesion promoters upgrade paving and roofing bitumen performance.
- Chemicals:Process additives support olefin production and intermediate purification in petrochemical complexes.
Fuels commands the largest revenue share. Lubricants is gaining share fastest as base oil quality migration accelerates across Asia.
End User:
Oil refineries consolidate purchasing power through multi-year framework agreements. Petrochemical plants and chemical manufacturers operate on spot markets with higher price volatility. Transport sector procurement fragments across marine operators, railroads, and fleet managers with divergent specification requirements.
- Oil Refineries:Integrated supermajors and independent refiners consume the bulk of antioxidant, demulsifier, and cold-flow additive volumes. Reliance Industries in India and Marathon Petroleum in the US negotiate bundled supply contracts covering technical service, inventory management, and performance guarantees. Procurement centralization compresses distributor margins.
- Petrochemical Plants:Olefin crackers and aromatics complexes require defoamers and process stabilizers where feedstock contamination risks unit run length.
- Chemical Manufacturers:Specialty chemical producers purchase refining-derived intermediates for downstream synthesis.
- Transport Sector:Marine operators, railroads, and trucking fleets procure cold-flow improvers and combustion enhancers for operational reliability in extreme climates.
Oil refineries anchor demand concentration. Transport sector procurement is where supplier diversification efforts concentrate as operators seek supply security.
Form:
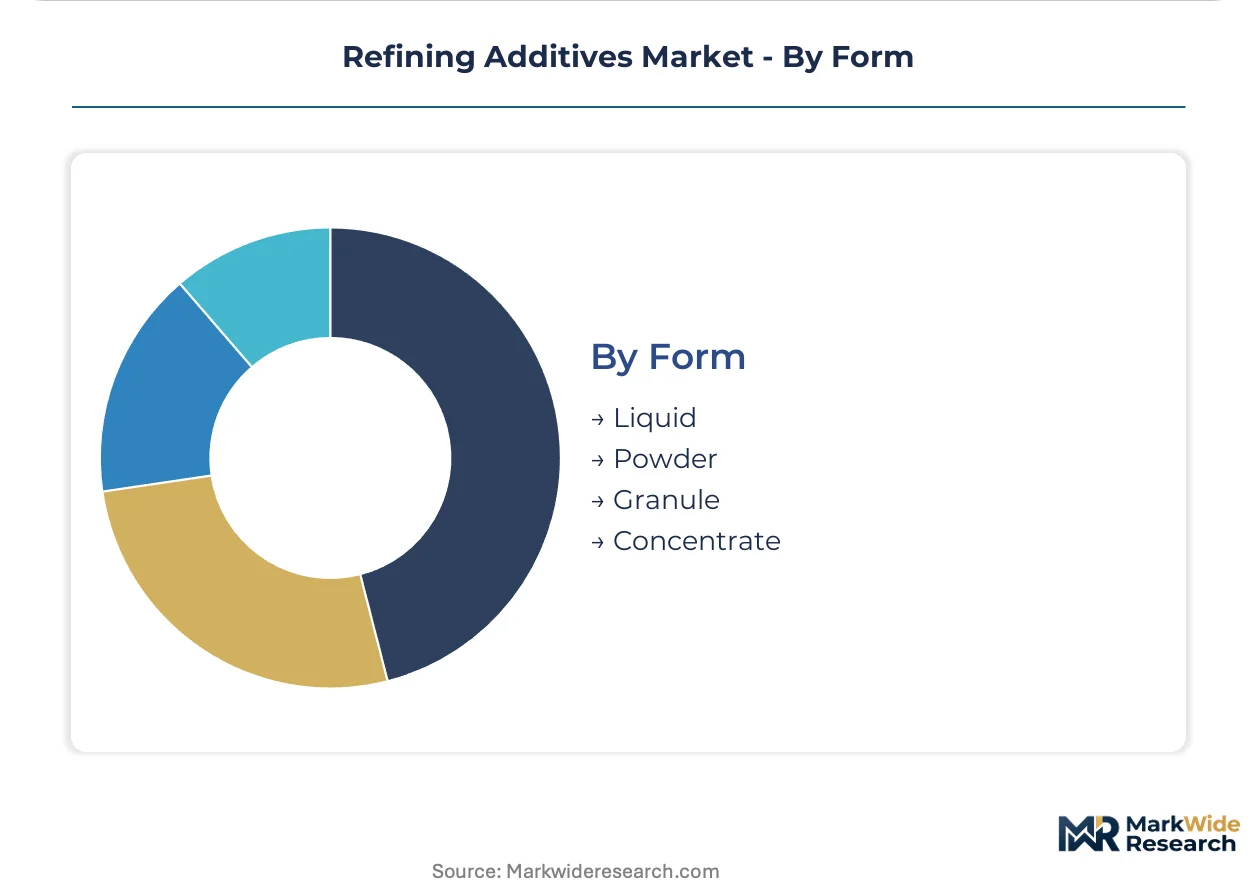
Liquid formulations dominate continuous injection systems. Powder and granule forms serve batch operations with lower capital intensity. Concentrates enable dilution economics for high-volume consumers with in-house blending capability.
- Liquid:Pumpable solutions integrate directly into refinery additive injection skids and automated blending systems. US and EU refiners prefer liquid delivery for gasoline detergent and diesel cold-flow packages where dosing precision affects regulatory compliance.
- Powder:Solid antioxidants and defoamers serve smaller refineries and chemical processors without liquid handling infrastructure.
- Granule:Free-flowing solid pour point reducers suit remote asphalt terminals and seasonal blending operations.
- Concentrate:High-potency formulations dilute at point of use, reducing freight costs for high-volume consumers with captive blending capacity.
Liquid formulations dominate installed dosing infrastructure. Concentrate adoption is where logistics cost reduction efforts concentrate as freight rates fluctuate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit the highest price elasticity as state-owned refiners negotiate multi-year additive supply contracts, while US and European purchasers prioritize formulation performance over unit cost due to EPA and ECHA compliance liability.
United States
Marathon Petroleum and Valero Energy drive antioxidant demand for Tier 3 gasoline sulfur compliance across Gulf Coast refineries. EPA enforcement of ultra-low sulfur standards forces continuous reformulation of storage stability packages. The Houston Ship Channel cluster concentrates additive blending operations where hydrotreater throughput determines treat rate economics.
China
Sinopec and PetroChina expand Group II/III base oil capacity in Zhejiang and Guangdong provinces, requiring elevated dispersant treat rates. MEE chemical inventory regulations filter non-compliant antioxidant suppliers from domestic procurement. The Yangtze River Delta anchors lubricant additive formulation as automotive OEM specifications tighten drain intervals.
India
Reliance Industries and Indian Oil Corporation scale octane booster consumption for BS-VI gasoline production at Jamnagar and Paradip refineries. BIS emission standard enforcement accelerates deposit control additive qualification cycles. The Gujarat refinery corridor represents the fastest-growing demand concentration for cold-flow improvers in domestic diesel blending.
Germany
BASF SE and Evonik Industries leverage integrated Ludwigshafen production complexes to supply pour point reducers for arctic marine fuel blends. REACH registration requirements concentrate antioxidant supply among ECHA-compliant formulators. The Rhine-Ruhr industrial basin maintains Europe's densest network of refinery technical service operations.
Saudi Arabia
Saudi Aramco deploys demulsifier packages for heavy crude processing at Ras Tanura and Yanbu facilities. The country's national petroleum regulator mandates additive performance standards for domestic refined product export. The Eastern Province refinery cluster integrates specialty chemical production with hydrotreating catalyst supply chains.
Refining Additives Market Competitive Landscape
Capability concentration sits with integrated chemical majors possessing captive precursor supply; scale advantage sits with refinery-facing distributors managing inventory logistics. The market structures around three tiers: multinational formulators with backward integration into organometallic intermediates, regional blenders serving single-refinery accounts, and technology licensors monetizing proprietary molecular architectures. Dominant competitive moves include capacity consolidation through specialty chemical acquisitions and long-term offtake agreements locking in refinery additive volumes.
Within the integrated formulator tier, BASF SE, Evonik Industries, and Albemarle occupy positions defined by upstream control over bromine and phosphorus derivative production. Dorf Ketal Chemicals and Nalco Company exemplify the refinery service archetype, embedding technical staff directly at customer facilities. Arkema and Clariant sit within the performance materials segment where polymer architecture differentiation commands formulation premiums. Grace Catalysts Technologies represents the technology licensing model, monetizing proprietary additive delivery systems rather than bulk chemical volumes.
| Leading Market Players |
|---|
| Dorf Ketal Chemicals |
| Grace Catalysts Technologies |
| BASF SE |
| Arkema |
| Nalco Company |
| Clariant |
| Albemarle |
| Evonik Industries |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
US Gulf Coast and Dead Sea bromine derivative production concentrates precursor supply for organometallic antioxidant intermediates, anchoring margin capture with integrated formulators while compressing standalone distributors. Refinery procurement consolidation into multi-year framework agreements redistributes value toward technical service bundling and inventory management guarantees.
Pricing Analysis
Aftermarket formulation services and technical support contracts drive lifetime value beyond base chemical sales. Pricing stratifies across premium, standard, and economy tiers differentiated by treat rate precision, REACH compliance certification, and bundled field engineering support. Cost compression in standard-grade antioxidants is intensifying because Asian state-owned refiners negotiate volume offtakes with thin service margins. National oil companies in India and China exhibit highest price elasticity, while US and EU integrated refiners prioritize EPA and ECHA compliance liability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for phosphorus derivative intermediates. Manufacturing concentration rests on Germany, the United States, and China for methacrylate comb polymers and ethylene-vinyl acetate copolymers. Raw material dependencies center on bromine from the Dead Sea, phosphorus from US Gulf Coast operations, and specialty amines from German chemical complexes. Single-source vulnerability persists for arctic-grade pour point reducers where Evonik's Ludwigshafen complex feeds multiple downstream formulators. Distribution runs through refinery-embedded technical service teams and regional blending facilities near Houston, Rotterdam, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refining additive procurement is consolidating under platform-economics logic as integrated oil companies demand interoperability between digital dosing systems and predictive inventory management. The shift rewards suppliers embedding proprietary molecular architectures within automated refinery control architectures.
For Market Incumbents: Entrench position through captive bromine and phosphorus derivative production in the US Gulf Coast and Dead Sea regions. Lock in multi-year offtake agreements with Reliance Industries and Saudi Aramco that bundle antioxidant packages with real-time dosing system integration. The threat of digital-native dosing vendors displacing standalone chemical supply necessitates backward integration into refinery automation interfaces. Certification investment in China's MEE chemical inventory and India's BIS emission standards is the priority lever for sequential market access. For New Entrants and Emerging Players: Mid-tier independent refiners in Southeast Asia represent the most penetrable entry point where technical service gaps persist in hydrotreater additive optimization. Arctic fuel logistics operators in Canada and Scandinavia offer white-space demand for methacrylate comb polymers with lower cold-flow treat rates than incumbent EVA copolymers. The go-to-market angle centers on precision dosing system partnerships with refinery automation vendors rather than direct chemical supply competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional blenders serving single-refinery accounts in the US Midwest and European periphery. Long-term viability hinges on five-to-ten year visibility into IMO marine sulfur enforcement and SAF co-processing additive requirements. Acquisition targets with ECHA REACH registration and EPA PMN approval pathways command premium positioning. The signal to watch is refinery automation vendor consolidation that could displace standalone additive distributors from procurement workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | BASF's Ludwigshafen complex secures bromine-derived antioxidant intermediate supply against Dead Sea sourcing volatility. |
| Long-term Supply Agreement | Marathon Petroleum's bundled framework contracts compress distributor margins while locking in Gulf Coast refinery volumes. |
| Joint Venture | Sinopec's Zhejiang base oil expansion partnerships embed dispersant treat rate specifications into Group II/III production planning. |
| Capacity Expansion | Evonik's methacrylate comb polymer scale-up targets arctic diesel and marine residual fuel specification tightening. |
| Green Manufacturing Transition | REACH-compliant phenolic antioxidant reformulation addresses EPA Tier 3 storage stability demands in ultra-low sulfur gasoline. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with refinery procurement directors, additive formulation chemists, and hydrotreater operations managers; and secondary validation through customs trade data, American Chemistry Council reports, SEC 10-K filings from integrated chemical majors, and EPA fuel additive registration databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators refined volume and value estimates across the projection horizon.
Forecast inputs considered crude slate volatility, regulatory enforcement timelines for IMO marine sulfur and EPA Tier 3 standards, and Group II/III base oil capacity expansion trajectories. Segmentation dimensions modeled include product chemistry tier, application channel regulatory exposure, end-user scale and contract duration, and physical form logistics compatibility. CAGRs were derived from regression analysis of historical additive treat rate trends against fuel specification tightening schedules. Industry-specific forecast inputs encompassed hydrotreater throughput economics and arctic logistics demand patterns.
Stress conditions across bromine supply disruption, REACH registration timeline delays, and refinery automation adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and crude quality variance within historical ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Anti Crystallizing Agents Market
Additives
Anti-Creasing Agent Market
Additives
Binding Agents Market
Additives
Disodium Guanylate Market
Additives
Global Scale Inhibitors Market
Additives
North America Fuel Additives Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Allura Red AC Market
Additives
United Kingdom Feed Additives Market
Additives
Ammonium Acetate Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Alginic Acid Market
Additives
Middle East Feed Additives Market
Additives
Low Melt Inclusions Market