
 Double Sided Tape Market | 2026-2036
Double Sided Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Double Sided Tape Market Analysis
Multi-source procurement among tier-one automotive suppliers is expanding as OEMs diversify adhesive tape vendors to mitigate supply risk. 3M leverages its materials science heritage to sustain premium positioning in acrylic foam tapes for exterior vehicle bonding. Nitto Denko anchors its competitive stance through deep specialization in electronics-grade thin films for display lamination. Tesa SE differentiates via controlled distribution networks serving European industrial manufacturers with customized die-cut solutions.
Double sided tape consists of pressure-sensitive adhesive coated on both faces of a carrier substrate, typically ranging from 0.1 mm to 2.0 mm in caliper, engineered to bond dissimilar surfaces without mechanical fastening. Acrylic formulations deliver superior UV resistance and long-term aging performance for outdoor construction and automotive applications, while rubber-based variants retain aggressive initial tack for indoor packaging and temporary holding operations. Foam tapes command structural load-bearing roles in glazing and panel attachment, whereas paper-backed grades occupy cost-sensitive packaging and print finishing segments where removability matters. Water-based technology lines are gaining production share as environmental compliance tightens, though solvent-based systems still dominate high-performance electronics lamination where outgassing control is critical.
EPA regulations under TSCA constrain volatile organic compound emissions in US tape manufacturing, while REACH registration requirements in Europe mandate full chemical substance disclosure across adhesive supply chains. OSHA workplace exposure limits further shape plant-level formulation choices and application equipment investments. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to another, complicating capital allocation for multinational production footprints.
Market Dynamics
Automotive OEMs in Germany and Japan are systematically replacing mechanical fasteners with bonded assemblies to achieve lightweighting targets, compressing demand for traditional fastening hardware while expanding specification volumes for structural acrylic foam tapes. This transition is redrawing supplier qualification criteria and tightening performance validation protocols across tier-one supply chains.
Growth Catalysts
- REACH chemical disclosure mandates:European ECHA registration requirements are accelerating solvent-to-water formulation conversions, expanding addressable market for compliant adhesive producers.
- Smartphone display lamination:East Asian electronics corridors in South Korea and Taiwan are consuming precision die-cut tapes for OLED panel assembly at intensifying specification frequencies.
- Lightweighting programs:German and Japanese automotive OEMs are expanding bonded glazing and panel attachment programs to eliminate rivets and welds.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and synthetic rubber input costs fluctuate with crude oil derivatives, compressing formulation margin predictability.
- East Asian supply concentration:Specialty release liner and thin PET carrier substrate production clusters heavily in China and South Korea, creating geographic vulnerability.
- Outgassing limitations:Water-based adhesives face technical ceilings in high-vacuum electronics lamination where solvent-based systems retain performance dominance.
Strategic Opportunities
- Indian industrial manufacturing:BIS standardization and PLI scheme incentives are opening specification windows for imported die-cut tape solutions in automotive and appliance sectors.
- Building-integrated photovoltaics:Solar module frame bonding and facade attachment applications are emerging as structural load-bearing use cases for UV-stable acrylic foam tapes.
- Digital die-cutting integration:Laser and rotary die-cutting automation converging with ERP-linked inventory systems is enabling mass-customization at automotive tier-one contract volumes.
Industry Challenges
- Adhesive formulation chemistry expertise:Shortage of polymer scientists capable of balancing tack, peel, and shear properties across temperature extremes constrains R&D throughput.
- Multijurisdictional compliance synchronization:Divergent EPA TSCA, REACH, and emerging Chinese MEE chemical notification timelines force parallel certification investments without cross-credit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Sided Tape Market |
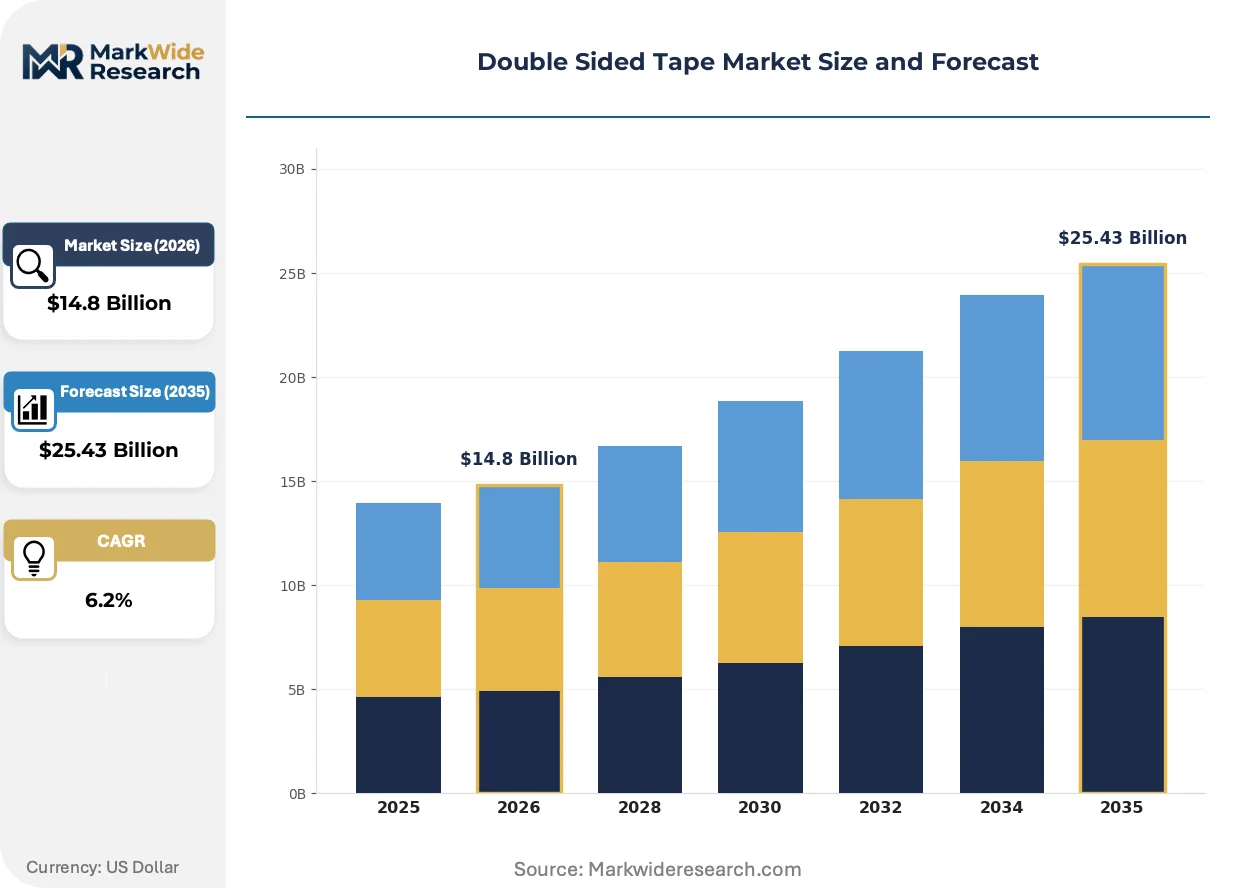
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Acrylic, Rubber, Paper Application: Packaging, Automotive, Construction, Electronics End User: Manufacturers, Retailers, DIY Enthusiasts, Contractors Technology: Hot Melt, Solvent-Based, Water-Based, Silicone |
| Companies Covered | 3M, Nitto Denko Corporation, Tesa SE, Avery Dennison Corporation, Lintec Corporation, Lohmann GmbH & Co. KG, Shurtape Technologies, Intertape Polymer Group, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Sided Tape Market Emerging Trajectories
Formulation chemistry and application automation are converging to redefine performance benchmarks and procurement specifications. Water-based adhesive platforms are displacing solvent systems in outdoor construction and automotive exterior bonding, while precision die-cutting integration with digital workflow systems is compressing order-to-delivery cycles for customized industrial solutions.
Hot-melt reactive polyurethane adhesive technology is integrating into automotive structural bonding lines to deliver cure-on-demand strength without clamping fixtures. BMW and Mercedes-Benz assembly plants in Germany are adopting these systems for aluminum-intensive vehicle platforms. The technology is integrating load-bearing performance previously reserved for mechanical fasteners, compressing cycle times and reducing assembly line capital intensity.
REACH SVHC candidate list expansions under ECHA jurisdiction are forcing full supply chain substance disclosure for adhesive raw materials. Tape manufacturers must now document monomer origins and additive compositions across multi-tier chemical sourcing. European automotive and construction specification holders are most affected, responding by consolidating supplier bases to reduce audit burden and traceability cost.
Consolidated procurement through tier-one automotive and electronics contract manufacturers is compressing vendor counts and lengthening qualification timelines. Buyers in South Korea and Taiwan are unbundling tape specification from broader MRO supply agreements to secure direct technical support and inventory flexibility. This pattern is most visible in smartphone and display panel supply chains where die-cut precision tolerances require collaborative engineering relationships rather than transactional purchasing.
Double Sided Tape Market Segmentation
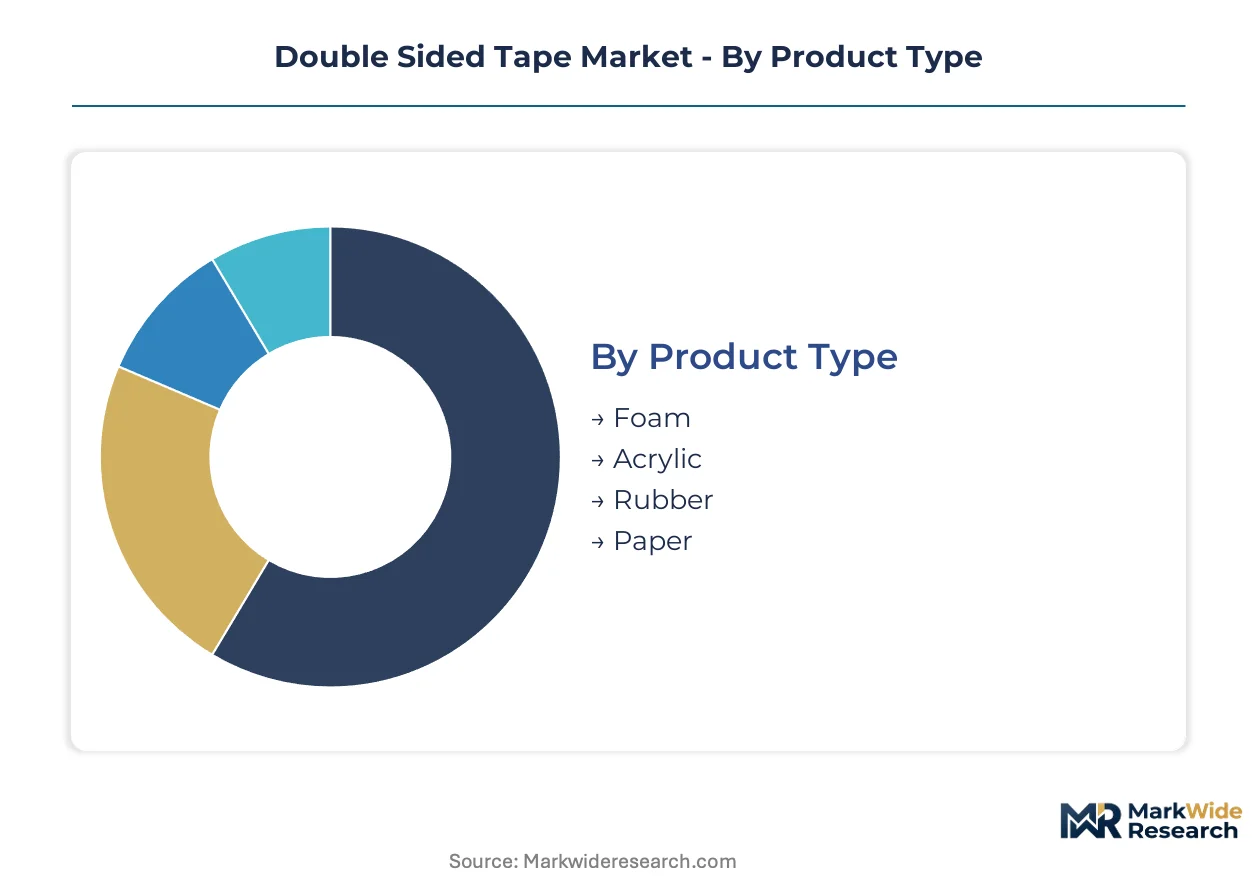
Double sided tape segmentation reveals divergent performance requirements across bonding applications. Product chemistry and application environment dictate specification choices, creating distinct procurement patterns between structural load-bearing and temporary holding use cases.
Product Type:
Volume concentrates in commodity substrates while premium pricing accrues to engineered foam and acrylic formulations with structural certification.
- Foam:Closed-cell polyethylene and polyurethane carriers deliver compressibility and gap-filling for glazing and panel attachment. German and Japanese automotive OEMs specify structural acrylic foam tapes for aluminum bonding programs, displacing mechanical fasteners in lightweighting initiatives.
- Acrylic:UV-stable formulations bond exterior construction and automotive applications with decades-long aging resistance. East Asian solar module manufacturers specify acrylic foam for frame bonding in building-integrated photovoltaic installations, opening new load-bearing use cases beyond traditional glazing.
- Rubber:Natural and synthetic rubber adhesives provide aggressive initial tack for indoor packaging and temporary holding where removability matters.
- Paper:Thin caliper kraft and tissue backings serve cost-sensitive print finishing and carton sealing with clean removal characteristics.
Today's leader: Acrylic. Tomorrow's challenger: Foam.
Application:
End-use concentration follows manufacturing geography, with automotive specification in Germany and electronics lamination in East Asian corridors driving premium demand.
- Automotive:Structural bonding of aluminum panels, glazing systems, and trim attachment replaces welds and rivets. BMW and Mercedes-Benz assembly plants specify hot-melt reactive polyurethane systems for cure-on-demand strength without clamping fixtures.
- Electronics:Precision die-cut tapes laminate OLED display panels and smartphone components in South Korean and Taiwanese manufacturing corridors. Specification frequencies intensify as display technology transitions to foldable form factors.
- Construction:Exterior facade bonding and window glazing consume UV-stable acrylic foam for structural load-bearing in European and North American building envelopes.
- Packaging:Carton sealing and print finishing utilize cost-optimized paper and thin film tapes where temporary adhesion suffices.
Construction maintains volume dominance. Electronics delivers margin expansion.
End User:
Procurement sophistication separates industrial contract manufacturers from fragmented retail and contractor channels.
- Manufacturers:Tier-one automotive and electronics contract manufacturers consolidate vendor counts and demand collaborative engineering relationships. South Korean smartphone assemblers unbundle tape specification from MRO agreements to secure direct technical support.
- Contractors:Construction installers specify project-grade acrylic foam for glazing and facade attachment, balancing performance against installed cost.
- Retailers:Big-box and specialty distributors stock consumer-grade paper and thin film tapes for DIY and light industrial applications.
- DIY Enthusiasts:Home improvement purchasers drive demand for removable mounting tapes and general-purpose bonding solutions.
Manufacturers command specification authority. Contractors represent channel expansion opportunity.
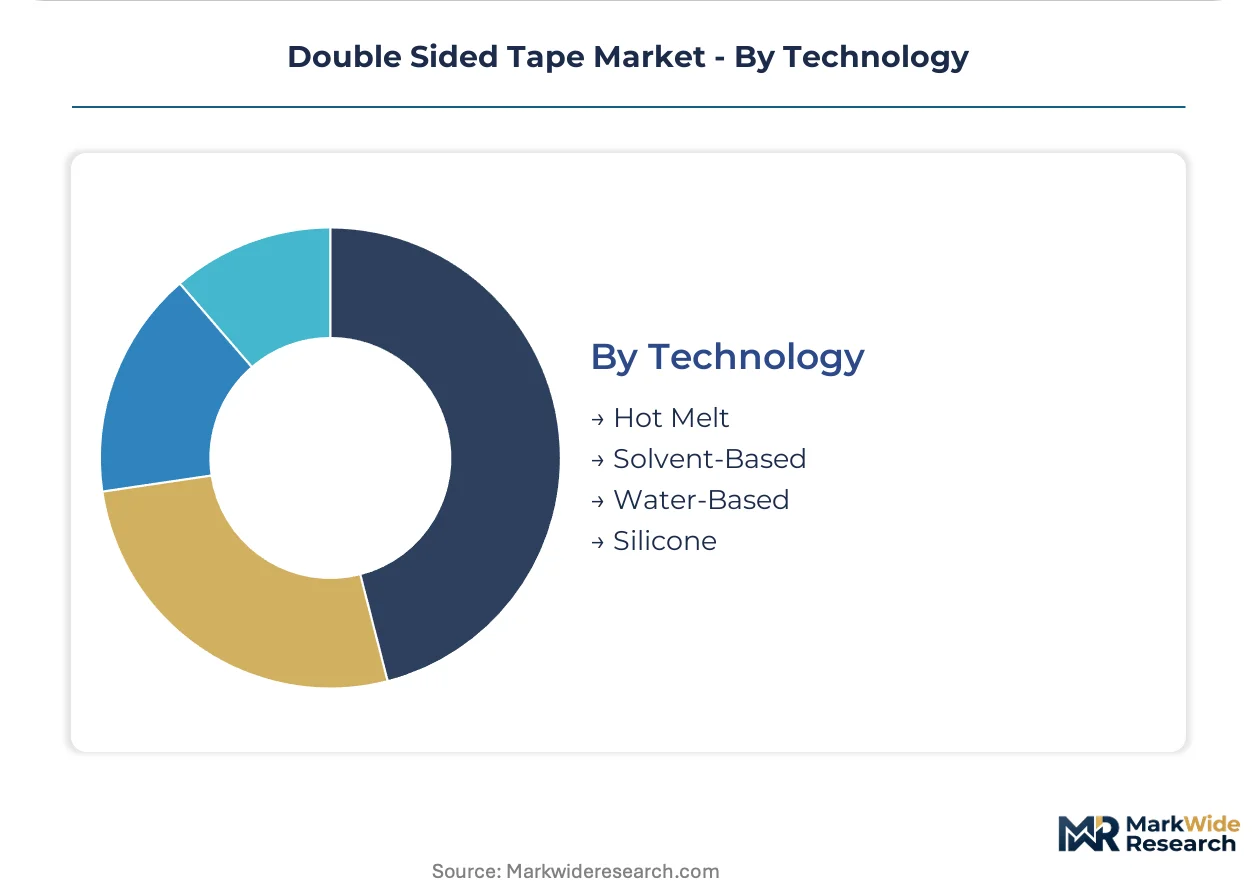
Technology:
Regulatory pressure is accelerating formulation conversion timelines, though performance ceilings preserve solvent-based dominance in select electronics applications.
- Water-Based:Acrylic emulsion adhesives displace solvent systems in outdoor construction and automotive exterior bonding as REACH and EPA TSCA compliance tightens. Formulation advances close performance gaps on UV resistance and aging.
- Solvent-Based:High-solids acrylic and rubber solutions retain specification in high-vacuum electronics lamination where outgassing control is critical. East Asian display panel manufacturers specify solvent systems for OLED bonding despite environmental compliance costs.
- Hot Melt:Reactive polyurethane systems integrate into automotive structural lines for cure-on-demand performance without clamping capital. German OEM adoption is compressing cycle times in aluminum-intensive vehicle platforms.
- Silicone:High-temperature stable formulations serve aerospace and industrial applications requiring performance across thermal extremes.
Water-based platforms gain regulatory tailwinds. Hot-melt reactive systems capture automotive structural share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics manufacturing corridors concentrate precision die-cut tape demand for smartphone and display panel production, while German and Japanese automotive OEMs drive structural acrylic foam specifications for bonded assembly programs.
United States
Automotive lightweighting programs at Detroit-area OEMs and construction glazing contractors in Sun Belt states consume UV-stable acrylic foam tapes. EPA TSCA regulations constrain volatile organic compound emissions in adhesive manufacturing, pushing formulation conversions toward water-based platforms. Tape fabricators in Ohio and Michigan serve tier-one automotive supply chains with hot-melt reactive polyurethane systems for aluminum panel bonding.
Germany
BMW and Mercedes-Benz assembly plants specify structural bonding tapes to eliminate mechanical fasteners in aluminum-intensive vehicle platforms. REACH SVHC candidate list expansions under ECHA jurisdiction mandate full supply chain substance disclosure for adhesive raw materials. Industrial tape specialists in North Rhine-Westphalia deliver customized die-cut solutions to European automotive and construction specification holders.
Japan
Precision die-cut tapes for OLED display lamination flow through manufacturing clusters in Osaka and Nagoya corridors. METI industrial standards shape adhesive performance validation protocols for electronics-grade thin films. Automotive OEMs in Toyota City and Yokohama expand bonded glazing and panel attachment programs to achieve corporate lightweighting targets.
South Korea
Smartphone assemblers in Seoul Capital Area and Busan-Ulsan corridor consume precision die-cut tapes at intensifying specification frequencies for foldable display form factors. Korean MFDS chemical notification requirements parallel REACH disclosure mandates for adhesive substance traceability. Display panel manufacturers specify solvent-based systems for high-vacuum OLED lamination despite environmental compliance costs.
China
Specialty release liner and thin PET carrier substrate production clusters in Yangtze River Delta and Pearl River Delta feed global tape supply chains. Emerging MEE chemical notification timelines force parallel certification investments without cross-credit to REACH or EPA regimes. Domestic automotive OEMs in Shanghai and Guangdong accelerate bonded assembly adoption to match German and Japanese lightweighting benchmarks.
Double Sided Tape Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electronics-grade specialization and regional customization services. The vendor base stratifies across three capability levels: multinational materials science conglomerates with full formulation control, regional die-cutting specialists with deep customer engineering relationships, and commodity converters competing on price in packaging and general industrial segments. Dominant competitive moves include backward integration into adhesive polymer production and geographic expansion through distributor network acquisition in underpenetrated industrial corridors.
Among diversified materials science conglomerates, 3M anchors premium positioning through acrylic foam tape heritage for exterior vehicle bonding. Nitto Denko Corporation exemplifies deep electronics specialization, occupying a position in precision thin-film lamination for display manufacturing corridors. Tesa SE represents European industrial customization, serving specification holders through controlled distribution networks and collaborative die-cut engineering.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| Tesa SE |
| Avery Dennison Corporation |
| Lintec Corporation |
| Lohmann GmbH & Co. KG |
| Shurtape Technologies |
| Intertape Polymer Group |
| Berry Global |
| Others |
Supply Flow & Price Mechanics
Acrylic monomer and synthetic rubber feedstock costs transmit directly from petrochemical derivatives through formulation tiers to end-product pricing, with German automotive OEMs absorbing premium structural foam grades while Asian electronics assemblers negotiate precision die-cut specifications on contract cycles.
Pricing Analysis
Input-cost pass-through from crude-linked petrochemicals governs margin predictability across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates structural acrylic foam tapes certified for automotive exterior bonding from commodity paper-backed grades serving packaging applications. Price differentiation rests on REACH compliance certification and volume scale, with tier-one automotive contract manufacturers leveraging procurement consolidation to compress supplier margins. Price erosion runs through commodity substrates as Chinese converters expand capacity, while electronics-grade precision tapes retain pricing power due to collaborative engineering relationships.
Supply Chain Analysis
Container freight rates and specialized cold-chain logistics for adhesive raw materials amplify working capital intensity for European and North American tape fabricators sourcing from East Asian chemical clusters. Specialty release liner and thin PET carrier substrate production concentrates in China and South Korea, creating geographic vulnerability for global tape assemblers. The supply chain draws from acrylic monomer producers in the US Gulf Coast, synthetic rubber processors in Southeast Asia, and silicone feedstock from German chemical complexes. Single-source vulnerability in precision die-cutting equipment constrains capacity expansion timelines. Distribution runs through tier-one automotive and electronics contract manufacturers with direct vendor-managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Double Sided Tape Market compounds steadily as bonded assembly adoption in automotive lightweighting programs generates recurring specification demand with long contract durations.
For Market Incumbents: Acquire precision die-cutting automation assets to defend against Asian electronics specialists encroaching on automotive tier-one relationships. Consolidate backward integration into acrylic polymer production to secure margin control as petrochemical feedstock volatility intensifies. Lock in REACH-compliant water-based formulation capacity before regulatory deadlines tighten in European specification chains. For New Entrants and Emerging Players: Capture Indian automotive and appliance manufacturing corridors where BIS standardization and PLI scheme incentives are opening specification windows for imported die-cut solutions. Building-integrated photovoltaics represents the most penetrable growth vector, with solar module frame bonding applications underserved by incumbent glazing specialists. Lead with UV-stable acrylic foam technical validation and localized inventory positioning rather than price competition. For Investors and Strategic Acquirers: Consolidation pressure builds where regional die-cutting specialists hold deep customer engineering relationships but lack formulation control or geographic scale. The five-to-ten year viability window favors materials science conglomerates with captive adhesive polymer production and multi-jurisdictional compliance infrastructure. Watch for inflection when German and Japanese OEMs accelerate aluminum-intensive platform launches, triggering step-change demand for structural bonding tape qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Production | Captive supply of UV-stable formulations insulates margin from petrochemical volatility and secures REACH compliance. |
| Precision Die-Cutting Automation Investment | Laser and rotary systems compress order-to-delivery cycles for automotive tier-one contract volumes. |
| Water-Based Formulation Conversion | Solvent-free platforms satisfy EPA TSCA and ECHA mandates while closing performance gaps on outdoor aging. |
| Indian Manufacturing Corridor Expansion | BIS certification and PLI alignment open specification windows in automotive and appliance bonding applications. |
| Building-Integrated Photovoltaics Partnership | Structural acrylic foam qualification for solar module frame bonding diversifies beyond traditional glazing demand. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with adhesive formulation directors, tier-one automotive procurement leads, electronics contract manufacturer supply chain managers, and regional die-cutting specialists with secondary validation from customs trade data, ECHA REACH registration databases, EPA TSCA filings, and automotive production registries.
Input-output matrices mapping acrylic monomer and synthetic rubber feedstock availability against automotive lightweighting program timelines and electronics display technology transitions anchor the projection framework. Segmentation dimensions span product chemistry, application environment, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves across the analysis window, incorporating OEM platform standardization roadmaps and solar module installation forecasts as industry-specific demand drivers.
Petrochemical feedstock volatility, REACH SVHC list expansion timing, and East Asian supply concentration are the dominant revision risks. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM bonded assembly adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Edge Band Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Twist Tube Market
Tapes
Flatback Tapes Market
Tapes
Automotive Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Strapping Supplies Market
Tapes
Pre-Printed Tape Market
Tapes
Reflective Tape Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Unidirectional Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Foam Tape Market