
 3D Printed Brain Model Market | 2026-2036
3D Printed Brain Model Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Brain Model Market Intelligence
EU MDR is expanding documentation requirements for patient-specific anatomical models, which raises compliance costs for new entrants while favoring incumbents with established quality systems. Materialise NV leverages its certified manufacturing infrastructure to sustain European hospital contracts. Stratasys Ltd. anchors the North American installed base through its J850 Digital Anatomy printer deployments at major academic centers. 3D Systems Corporation differentiates via its bioprinting division's vascularized tissue capabilities.
A 3D printed brain model is a patient-specific or generic cranial replica fabricated through additive manufacturing, typically using photopolymer resins or hydrogels at layer resolutions between 16 and 50 microns to replicate cortical gyri, white matter tracts, and vascular architecture for preoperative planning or trainee rehearsal. Surgical training models command premium pricing due to their haptic fidelity requirements and validated skill-transfer protocols. Among technologies, PolyJet dominates the high-detail segment for neurovascular replication, while FDM occupies the educational tier where cost per model drives procurement decisions.
FDA's 510(k) clearance framework for 3D-printed anatomical guides shapes product development roadmaps, particularly when manufacturers seek claims for patient-matched dimensions. The EU AI Act's risk classification rules for diagnostic decision-support tools will intersect with software-generated segmentation workflows used to convert DICOM data into printable files. Stakeholders must monitor whether reimbursement codes for preoperative 3D modeling expand beyond CMS's current procedural terminology pilot programs into permanent Category III status.
Market Dynamics
Patient-specific surgical rehearsal is displacing generic anatomical phantoms in neurosurgical training programs, compressing procurement cycles and forcing manufacturers to reconfigure production workflows around DICOM-to-print pipelines.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined regulatory framework for 3D-printed anatomical guides accelerates clinical validation timelines, enabling faster commercialization of patient-matched cranial replicas.
- Photopolymer Resin Advances:Next-generation materials with Shore hardness matching cortical bone enable haptic fidelity previously unattainable in synthetic brain models.
- Boston-Cleveland-Minneapolis Hospital Cluster:Geographic concentration of academic medical centers creates dense reference sites that validate training protocols and drive institutional purchasing decisions.
Market Restraints
- EU MDR Documentation Burden:Expanded quality system requirements for patient-specific anatomical models raise compliance costs disproportionately for smaller manufacturers seeking European hospital contracts.
- Digital Segmentation Bottleneck:Shortage of radiologists trained in DICOM-to-mesh conversion creates throughput constraints in model production pipelines.
- Silicone Phantom Substitution:Conventional molding techniques retain cost advantages for high-volume educational applications where patient specificity offers marginal value.
Strategic Opportunities
- Bioprinting Convergence:Integration of vascularized tissue printing with structural brain models opens preoperative rehearsal for tumor resection with blood flow simulation.
- India's CDSCO Emerging Framework:Early regulatory clarity for 3D-printed medical devices positions domestic manufacturers to serve South Asian neurosurgical training institutes.
- Subscription-Based Model Libraries:Cloud repositories of validated pathological anatomies enable teaching hospitals to access rare case variations without per-model fabrication costs.
Industry Challenges
- ISO 13485 Certification Timelines:Medical device quality management system implementation delays market entry for additive manufacturing specialists transitioning from industrial prototyping.
- Interoperability Friction:Proprietary file formats between segmentation software and printer control systems force manual translation steps that introduce dimensional errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Brain Model Market |
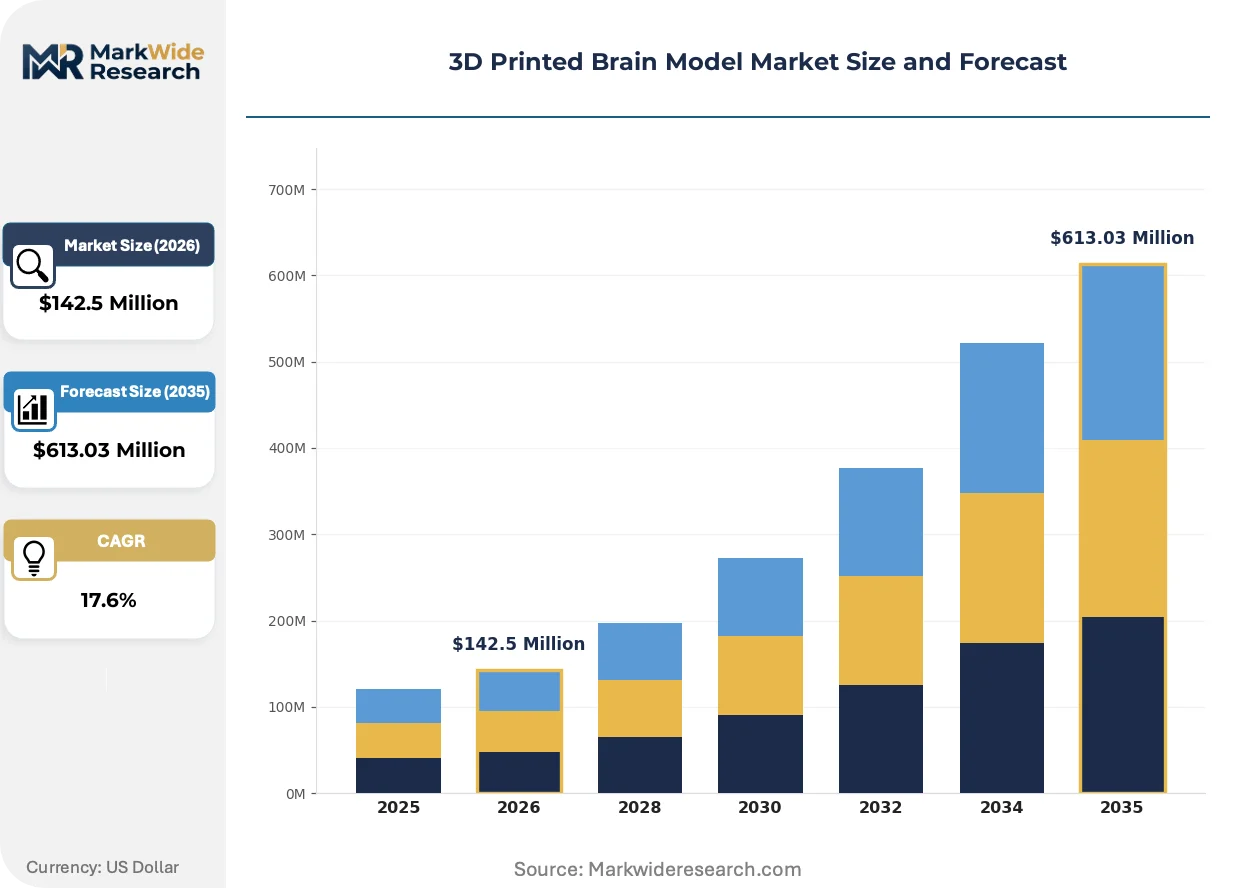
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $613.03 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anatomical Models, Functional Models, Educational Models, Surgical Training Models Application: Medical Education, Surgical Simulation, Research, Patient Consultation End User: Hospitals, Universities, Research Institutes, Medical Device Companies Technology: SLA, SLS, FDM, PolyJet |
| Companies Covered | 3D Systems Corporation, Stratasys Ltd., Materialise NV, Axial3D Ltd., Anatomage, Formlabs, CELLINK, ROKIT HEALTHCARE, INC., MedPrin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Brain Model Market Strategic Shifts & Innovations
Digital anatomy workflows are collapsing the traditional separation between radiological diagnosis and surgical preparation, embedding additive manufacturing directly into preoperative planning sequences.
PolyJet multi-material jetting is overtaking stereolithography for neurovascular model production. This technology deposits distinct photopolymers in single print jobs to replicate vessel walls, thrombus, and surrounding parenchyma. Academic medical centers in the United States are adopting these systems for aneurysm clipping rehearsal. The shift is compressing model production time from days to hours while raising fidelity standards that exclude single-material alternatives.
EU MDR's expanded technical documentation requirements for custom-made devices are restructuring competitive positioning in European markets. Manufacturers must now maintain design dossiers traceable to individual patient imaging data. German and French teaching hospitals are prioritizing suppliers with notified body partnerships, filtering out vendors lacking established quality infrastructure.
Teaching hospitals are unbundling after-sales technical support from hardware procurement, treating segmentation training and maintenance as separate purchasing decisions. This pattern concentrates service revenue with specialized software firms while commoditizing printer hardware. The United Kingdom's National Health Service has formalized this split through distinct tender categories, accelerating vendor specialization.
3D Printed Brain Model Market Segmentation
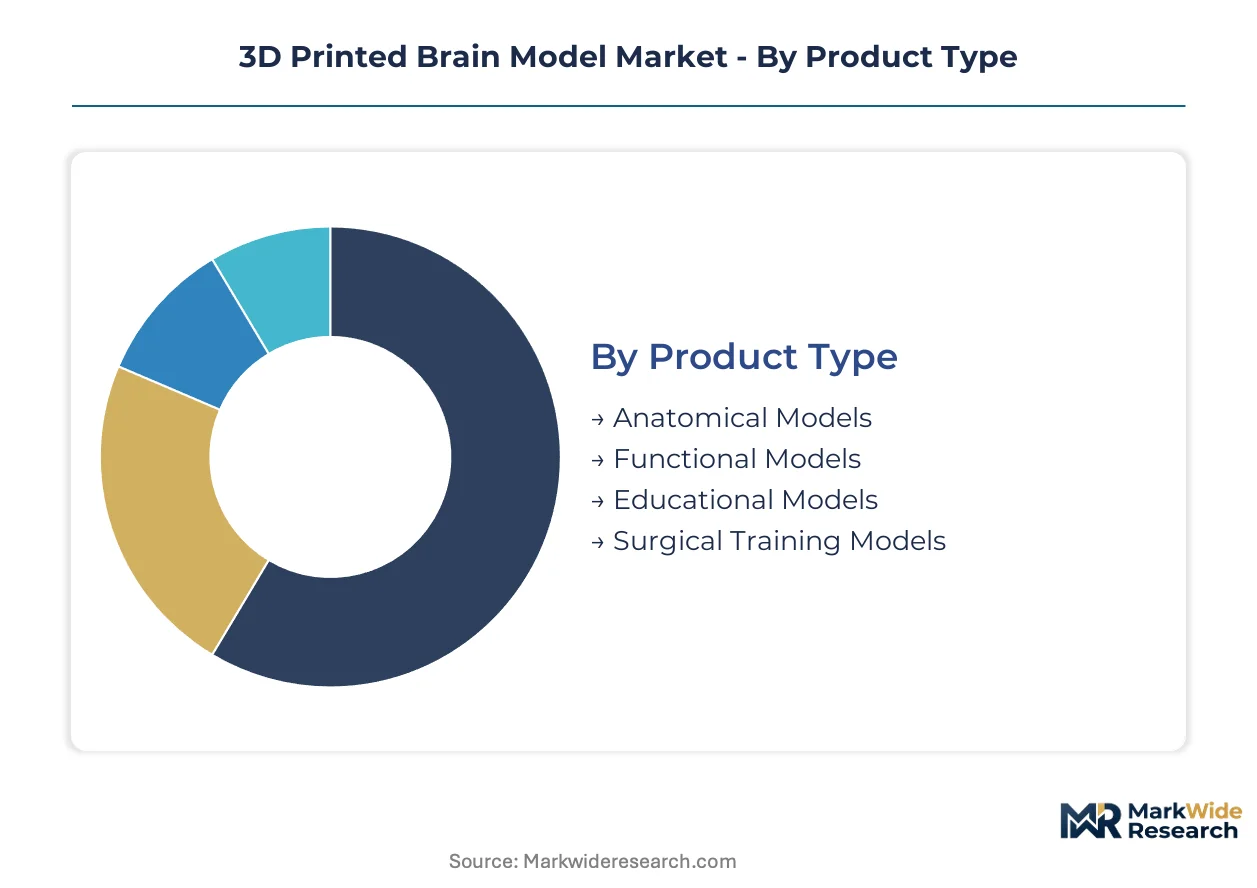
Segmentation in the 3D printed brain model market reveals distinct procurement patterns across clinical, educational, and industrial use cases. Each dimension—product fidelity, application intensity, buyer sophistication, and manufacturing precision—creates separate competitive arenas with divergent margin structures and validation requirements.
Product Type:
Standalone display models occupy a separate procurement channel from embedded systems integrated into surgical workflows, with integration depth determining price premiums and regulatory scrutiny.
- Anatomical Models:Static cranial replicas replicate cortical surface topology and ventricular architecture for patient education and basic anatomical reference. Demand clusters in US academic medical centers where patient consent protocols favor physical visualization aids over screen-based alternatives.
- Surgical Training Models:Haptic-enabled replicas with tissue-mimicking mechanical properties support validated skill-transfer protocols for resident education. Cleveland Clinic and Massachusetts General Hospital anchor North American procurement volumes through centralized simulation center budgets.
- Functional Models:Dynamic systems incorporating fluidic channels or electrical conductivity simulate cerebrospinal fluid dynamics or neural activation patterns. Device manufacturers in Minneapolis-St. Paul purchase these for catheter and stimulator development testing.
- Educational Models:Simplified, cost-optimized replicas target undergraduate anatomy curricula where patient specificity offers minimal pedagogical value. Procurement concentrates in state university systems with standardized laboratory equipment budgets.
Anatomical models lead volumes today; surgical training models are gaining share fastest.
Application:
Cost tier stratification separates capital-intensive institutional deployments from consumable-like per-case utilization models.
- Surgical Simulation:Preoperative rehearsal applications command premium pricing through validated outcome correlations and malpractice risk reduction claims. Boston's hospital cluster drives procurement through bundled neurosurgery residency program contracts.
- Medical Education:Curriculum-integrated training employs lower-cost generic phantoms where pathological variety matters more than patient-matched fidelity. US medical school accreditation requirements sustain baseline demand regardless of reimbursement fluctuations.
- Research:Experimental applications including traumatic brain injury modeling and pharmaceutical delivery testing utilize customized geometries outside standard clinical specifications. NIH grant funding cycles create lumpy demand patterns distinct from hospital procurement.
- Patient Consultation:Informed consent enhancement through physical model visualization carries reimbursement ambiguity that limits penetration to self-pay and concierge practice segments.
Medical education leads volumes today; surgical simulation is expanding most quickly.
End User:
Customer type determines whether procurement flows through centralized supply chains or decentralized principal investigator budgets.
- Hospitals:Integrated delivery networks consolidate purchasing through value analysis committees that weigh clinical utility against capital allocation constraints. Major US teaching hospitals maintain dedicated 3D printing labs with in-house segmentation capabilities.
- Universities:Anatomy and biomedical engineering departments operate on academic procurement cycles tied to fiscal year equipment budgets rather than clinical revenue generation.
- Research Institutes:Grant-funded investigators prioritize customization flexibility and rapid turnaround over per-unit cost optimization.
- Medical Device Companies:Product development and regulatory submission applications demand ISO 13485-compliant manufacturing documentation that filters supplier pools.
Hospitals lead volumes today; medical device companies are climbing the fastest.
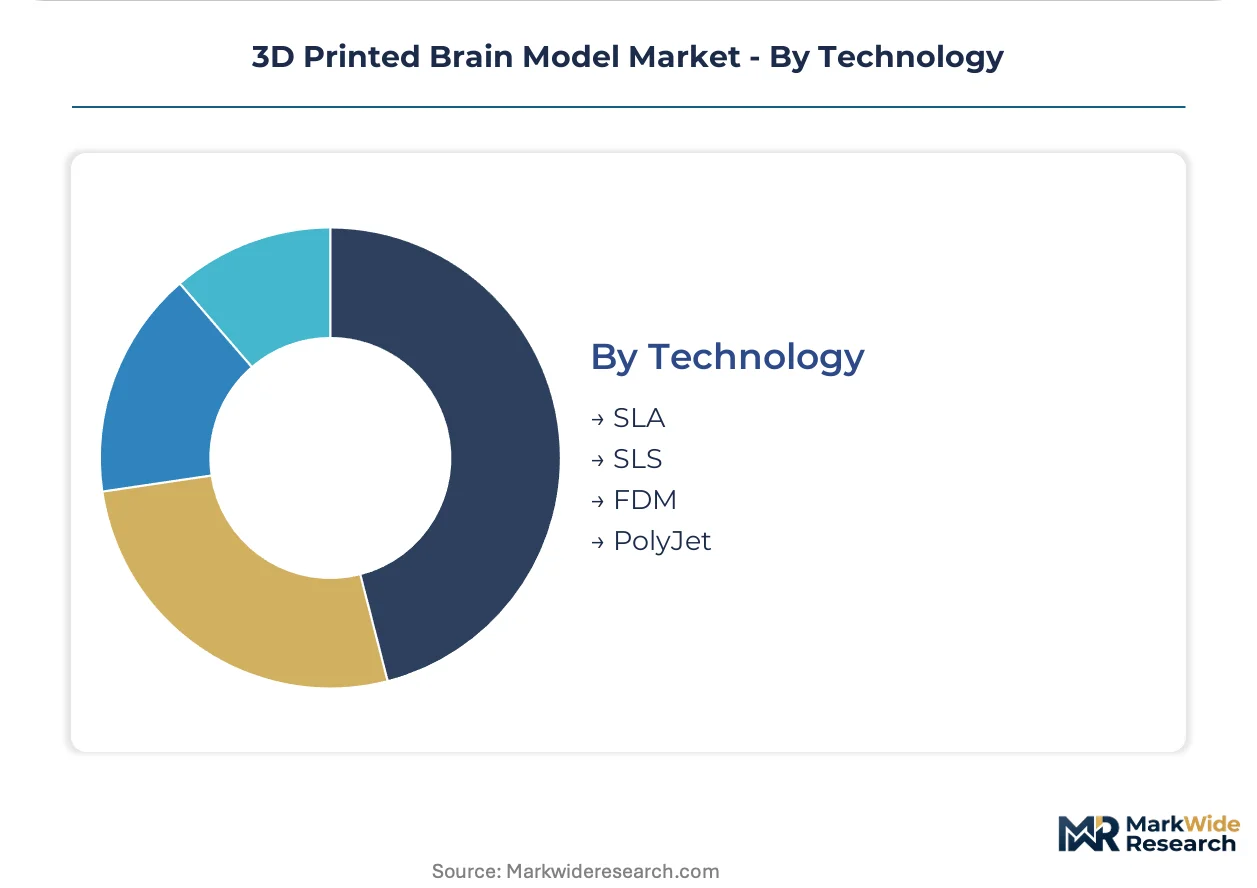
Technology:
Maturity gradients separate established industrial methods from emerging clinical-grade platforms still navigating validation protocols.
- PolyJet:Multi-material jetting deposits distinct photopolymers in single print jobs to replicate vessel walls, thrombus, and surrounding parenchyma with layer resolutions down to 16 microns. Academic medical centers in the United States adopt these systems for aneurysm clipping rehearsal despite elevated capital costs.
- SLA:Stereolithography delivers sub-25-micron precision for detailed cortical surface reproduction at lower equipment cost than PolyJet, though single-material constraints limit vascular replication fidelity.
- FDM:Fused deposition modeling occupies the educational tier where cost per model drives procurement decisions and layer visibility is acceptable.
- SLS:Selective laser sintering of nylon powders produces durable handling models but struggles with the translucent tissue visualization requirements of neurosurgical applications.
SLA leads volumes today; PolyJet is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 3D printed brain model industry traces its commercial roots to Belgian software-to-manufacturing integration in the 1990s, later scaling through North American academic medical center adoption. Geographic demand patterns now reflect regulatory pathway maturity and neurosurgical training infrastructure concentration.
United States
FDA's 510(k) clearance framework accelerates patient-matched model commercialization, with breakthrough device designations streamlining clinical validation. Major teaching hospitals cluster around Boston, Minneapolis, and Cleveland, where centralized simulation center budgets drive institutional procurement. Massachusetts General Hospital and Cleveland Clinic anchor validation protocols that diffuse through residency program networks.
Germany
Notified body partnerships under EU MDR filter supplier pools toward established quality infrastructure, favoring incumbents with ISO 13485 certification. German teaching hospitals prioritize suppliers maintaining design dossiers traceable to individual patient imaging data. The Baden-Württemberg and Bavaria medical technology corridors concentrate polymer research and hospital system purchasing power.
Japan
PMDA's structured review pathways for 3D-printed anatomical guides shape product development timelines for manufacturers seeking reimbursement eligibility. Tokyo and Osaka academic medical centers integrate additive manufacturing into neurosurgical residency curricula. METI funding for medical device innovation supports domestic printer deployment and materials research.
United Kingdom
NHS tender categories formally separate hardware procurement from segmentation training and maintenance services, accelerating vendor specialization. London teaching hospitals unbundle after-sales technical support from capital equipment purchasing. The National Institute for Health and Care Excellence evaluates preoperative modeling cost-effectiveness for potential commissioning guidance.
India
CDSCO's emerging regulatory clarity for 3D-printed medical devices positions domestic manufacturers to serve South Asian neurosurgical training institutes. Mumbai and Delhi academic centers expand simulation lab infrastructure with grant-funded equipment purchases. State medical university systems standardize anatomy curricula that incorporate physical model-based instruction.
3D Printed Brain Model Market Key Industry Players
The competitive structure tilts toward diversified industrial printer manufacturers with medical-grade certifications. Tiered positioning separates premium multi-material systems from cost-optimized educational alternatives. Three archetypes dominate: diversified additive manufacturing conglomerates, specialized medical modeling software firms, and bioprinting technology developers. Capacity expansion in certified manufacturing infrastructure and strategic partnerships with academic medical centers constitute the primary competitive moves.
Among diversified additive manufacturing conglomerates, 3D Systems Corporation and Stratasys Ltd. occupy positions spanning hardware and materials portfolios, while Materialise NV exemplifies the software-to-manufacturing workflow specialist archetype. These three entities represent distinct strategic postures—capital equipment scale, integrated digital anatomy platforms, and certified European manufacturing infrastructure—without direct overlap in core competitive emphasis.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Stratasys Ltd. |
| Materialise NV |
| Axial3D Ltd. |
| Anatomage |
| Formlabs |
| CELLINK |
| ROKIT HEALTHCARE, INC. |
| MedPrin |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees' unbundling of after-sales technical support from hardware capital expenditure is forcing manufacturers to restructure revenue models around segmented service tiers, compressing equipment margins while elevating recurring revenue streams. This shift concentrates pricing power with specialized segmentation software firms and fragments margin capture across the value chain.
Pricing Analysis
Bundled hardware-and-service contracts are giving way to unbundled procurement structures where teaching hospitals purchase printers, segmentation training, and maintenance through separate tender categories. Three-tier pricing structure across premium, standard, and economy levels separates PolyJet multi-material systems from SLA workstations and FDM educational units, with FDA 510(k) clearance status commanding measurable premiums. Pricing pressure stems from silicone phantom substitution in high-volume training applications where patient specificity offers marginal pedagogical value. Medical education buyers exhibit highest price sensitivity, while surgical simulation centers prioritize haptic fidelity over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with photopolymer resin feedstock concentrated among specialty chemical producers in Germany, Japan, and the United States. Manufacturing draws from imported digital light processing components, certified biocompatible photopolymers, and precision motion control systems. Tariff exposure on optical engines and print heads creates margin volatility for equipment assemblers lacking captive component supply. Distribution runs through direct hospital sales forces in North America and notified body-certified manufacturing partners in European Union markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D printed brain model market functions as a stable compounder anchored by irreversible substitution of patient-specific rehearsal for generic phantom training in neurosurgical residency curricula. This structural demand shift insulates baseline volumes from reimbursement cyclicality.
For Market Incumbents: Hedge against software commoditization by deepening in-house production of photopolymer formulations and securing exclusive segmentation training partnerships with Boston-Cleveland-Minneapolis hospital clusters. ISO 13485 certification investments and notified body relationships in Germany and France defend European positioning against emerging domestic manufacturers.
For New Entrants and Emerging Players: Capture white-space opportunity in India's CDSCO-regulated market where domestic production cost structures undercut imported equipment landed costs. Target state medical university systems with standardized anatomy curricula requiring economy-tier educational models. Lead with subscription-based model libraries that eliminate per-fabrication cost barriers for teaching hospitals seeking rare pathological variations.
For Investors and Strategic Acquirers: Asymmetric upside sits with bioprinting technology developers integrating vascularized tissue capabilities with structural brain models for blood flow simulation applications. Long-term viability rests on convergence of regulatory validation timelines with reimbursement code expansion from CMS pilot programs into permanent Category III status. Monitor FDA breakthrough device designation velocity as inflection indicator for clinical adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Centralized simulation center budgets at Massachusetts General Hospital and Cleveland Clinic validate training protocols that diffuse through residency networks. |
| FDA 510(k) Submission | Breakthrough device designation streamlines clinical validation timelines for patient-matched cranial replicas seeking specific dimensional claims. |
| CE Marking Pathway | EU MDR technical documentation requirements filter supplier pools toward incumbents with notified body partnerships and traceable design dossiers. |
| Software Companion Development | Cloud repositories of validated pathological anatomies enable teaching hospitals to access rare case variations without per-model fabrication costs. |
| Reimbursement Strategy | CMS procedural terminology pilot program expansion into permanent Category III status would unlock institutional purchasing at integrated delivery networks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with neurosurgical residency program directors, hospital biomedical engineers, GPO contracts managers, and medical device regulatory affairs specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, CMS reimbursement code filings, and hospital procurement system records. Bottom-up model fabrication volume estimates and top-down additive manufacturing equipment installed base analysis were triangulated to constrain forecast variance.
Segment-weighting across product type, application intensity, end-user procurement channel, and manufacturing technology dimensions structured the analytical framework. CAGRs were derived from fitted adoption curves calibrated against academic medical center expansion rates and neurosurgical training program accreditation requirements. Forecast inputs incorporated photopolymer resin formulation advancement timelines and digital segmentation software penetration rates across radiology departments.
Regulatory pathway delays, reimbursement code stagnation, and silicone phantom cost competition are the dominant revision risks that could compress projected adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Global Ventilators Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Hi-Tech Medical Devices Market