
 Global Programming Software Market | 2026-2036
Global Programming Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Programming Software Market Foresight
The chronic shortage of advanced systems programmers is unwinding traditional hiring models across the Global Programming Software Market. Microsoft Corporation leverages its Visual Studio ecosystem to dominate enterprise accounts with deep Azure integration. JetBrains sustains loyalty among professional developers through specialized IDE architectures for Kotlin and Rust. Amazon Web Services anchors cloud-native development workflows with embedded tooling inside its broader infrastructure stack.
Programming software encompasses integrated development environments, code editors, version control systems, debuggers, and profilers that translate human-readable source code into executable machine instructions through compilation, interpretation, or transpilation processes. These tools serve the fundamental commercial purpose of reducing defect rates and accelerating release cycles across software-intensive industries. Cloud-based deployment now leads solution type adoption as enterprises abandon capital-intensive on-premises maintenance, while version control systems represent the fastest-expanding segment due to distributed team proliferation and regulatory audit requirements. Integrated development environments retain the deepest margin pools through subscription bundling with adjacent collaboration and security modules.
The EU AI Act imposes documentation and traceability mandates that reshape tool requirements for European developers, while FDA software-as-a-medical-device guidance in the United States elevates validation standards for healthcare programming environments. China's MIIT enforces domestic cryptography standards that condition market access for foreign debugging and profiling tools. Stakeholders must monitor divergent compliance architectures across jurisdictions to determine whether localized product variants or unified global platforms offer superior returns.
Market Dynamics
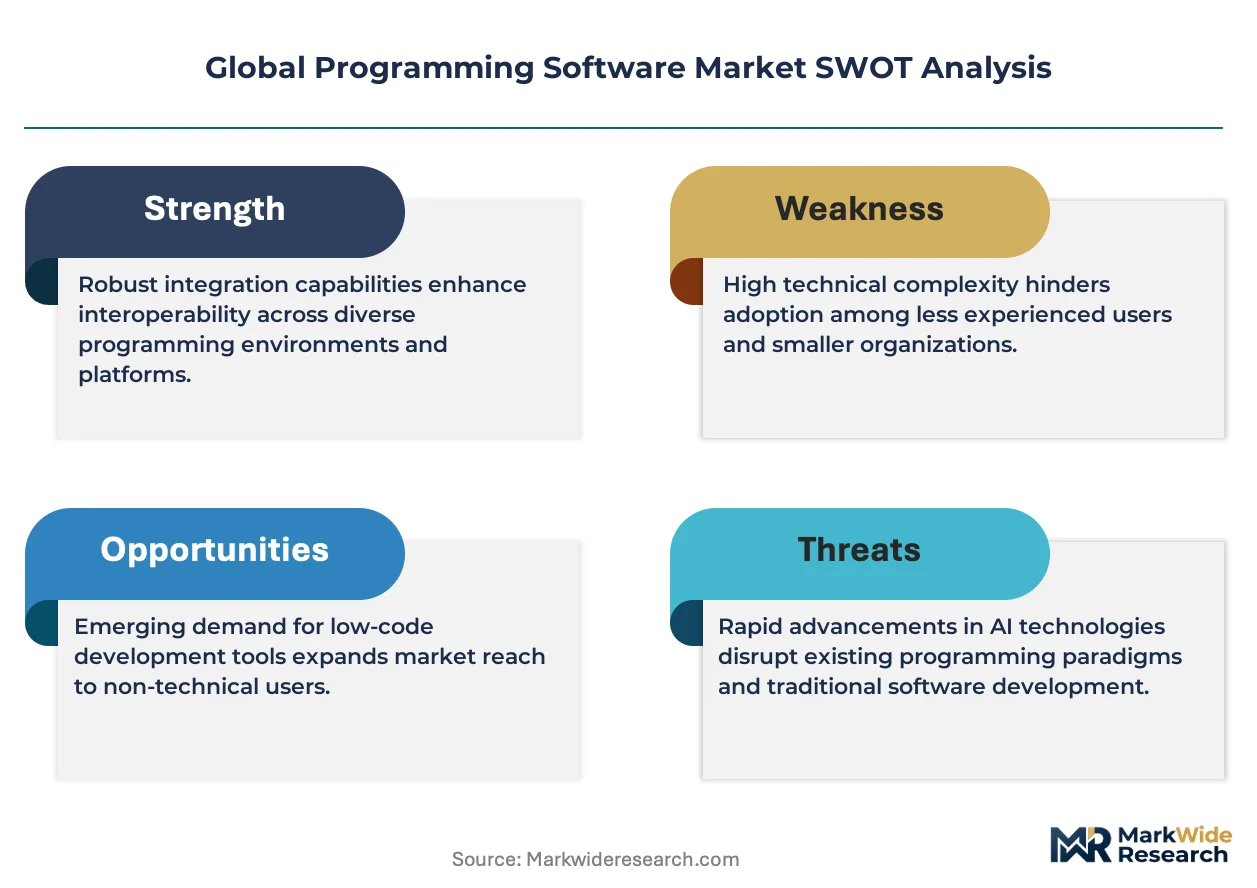
The migration of development workflows to cloud-native architectures is compressing traditional IDE licensing models while amplifying demand for embedded security and compliance modules within programming toolchains.
Growth Catalysts
- EU AI Act documentation mandates:European developers now require automated traceability tooling, expanding procurement of integrated compliance modules within IDEs.
- Defense modernization programs:United States federal contractors are replacing legacy codebases, generating sustained demand for refactoring and migration tooling.
- Kotlin and Rust adoption:Specialized language support is driving subscription renewals among professional developers seeking performance-critical systems programming capabilities.
Market Restraints
- Cloud infrastructure concentration:Three hyperscalers control the underlying compute layer, creating vendor lock-in risks for development environment portability.
- Domestic cryptography requirements:China's MIIT standards fragment debugging tool distribution, forcing costly localization or market exclusion.
- Subscription fatigue:Enterprise buyers face accumulated SaaS costs across overlapping toolchain categories, pressuring consolidation decisions.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic software manufacturing incentives are creating localized demand for indigenous development tooling ecosystems.
- FDA software-as-medical-device guidance:Healthcare programming environments require elevated validation standards, opening premium pricing tiers for compliant toolchains.
- Edge-AI development convergence:The intersection of embedded systems and machine learning inference is spawning new tooling categories for resource-constrained deployment targets.
Industry Challenges
- Advanced systems programmer scarcity:The talent pipeline for kernel-level and compiler engineering has collapsed, forcing reliance on expensive contract specialists.
- Multi-jurisdiction compliance stacking:Simultaneous EU AI Act, FDA, and MIIT obligations create architectural complexity for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Programming Software Market |
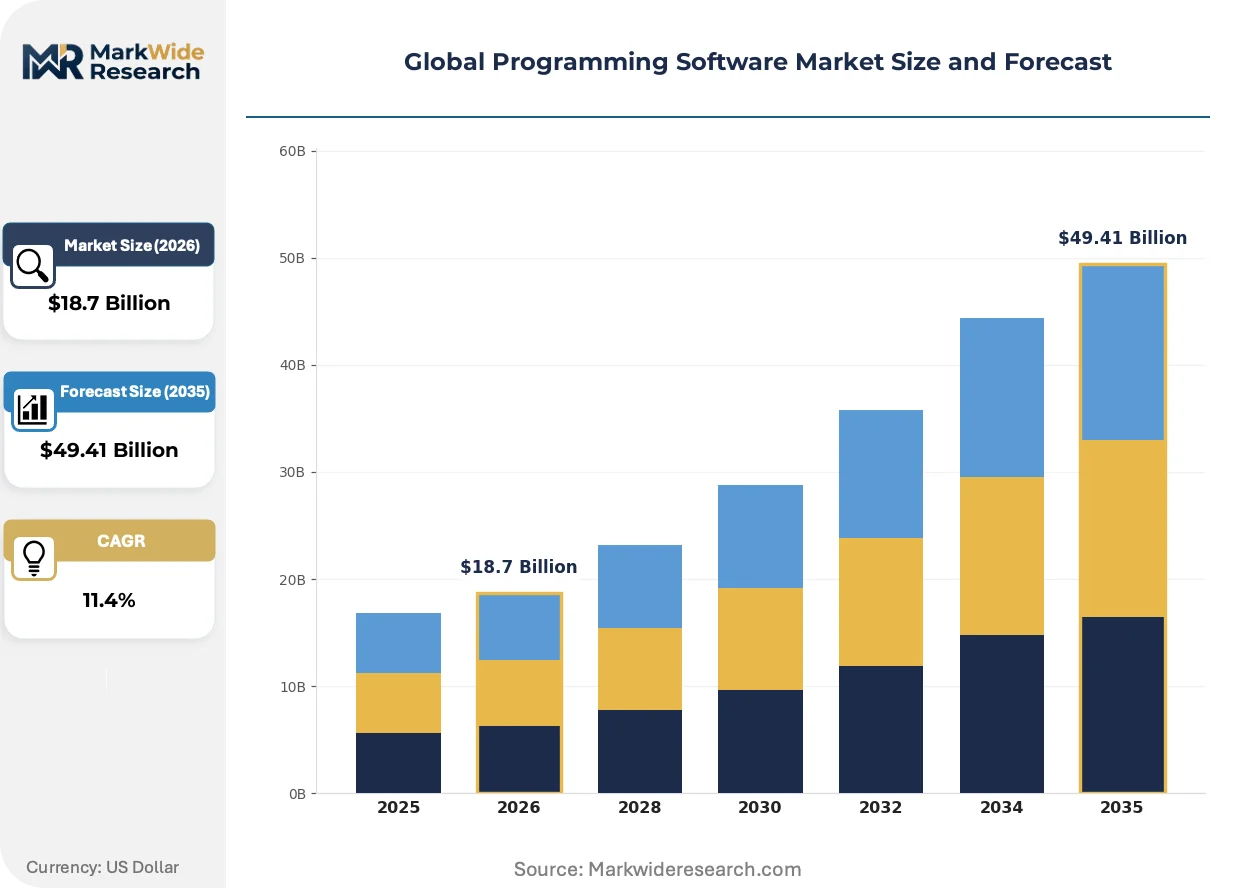
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Machines, Containerized Solution Type: Integrated Development Environment, Code Editors, Version Control Systems, Debuggers, Profilers Application: Enterprise Software, Embedded Systems, Mobile Applications, Web Development, Game Development End User: Software Developers, IT Consultancies, System Integrators, Independent Freelancers, Educational Institutions |
| Companies Covered | Microsoft Corporation, JetBrains, Atlassian, Oracle Corporation, Amazon Web Services, GitHub, IBM, SAP, IntelliJ IDEA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Programming Software Market Shifts & Advancements
Agentic coding assistants are restructuring how software teams compose, test, and maintain codebases. These systems are compressing junior developer onboarding cycles while elevating architectural oversight requirements.
Large language model pair-programming is decomposing traditional IDE feature hierarchies. Financial services development teams in London and Singapore are deploying these systems for automated test generation and legacy code translation. The technology is decomposing established pricing bundles by unbundling autocomplete, refactoring, and documentation generation into separately metered capabilities.
The EU AI Act's algorithmic accountability provisions are mandating immutable audit trails for training data and model versioning. European pharmaceutical and automotive developers must now embed provenance tracking directly into their programming environments. German automotive suppliers are retrofitting existing toolchains with automated documentation pipelines to satisfy regulator inspection protocols.
Consumption-based licensing for development tooling is displacing seat-based subscriptions among mid-market software vendors. Buyers in Brazil and South Korea are negotiating usage-tiered contracts that scale with build minutes and deployment frequency. This pattern is most visible among Series B and C technology companies optimizing burn rates against engineering headcount volatility.
Global Programming Software Market Segmentation
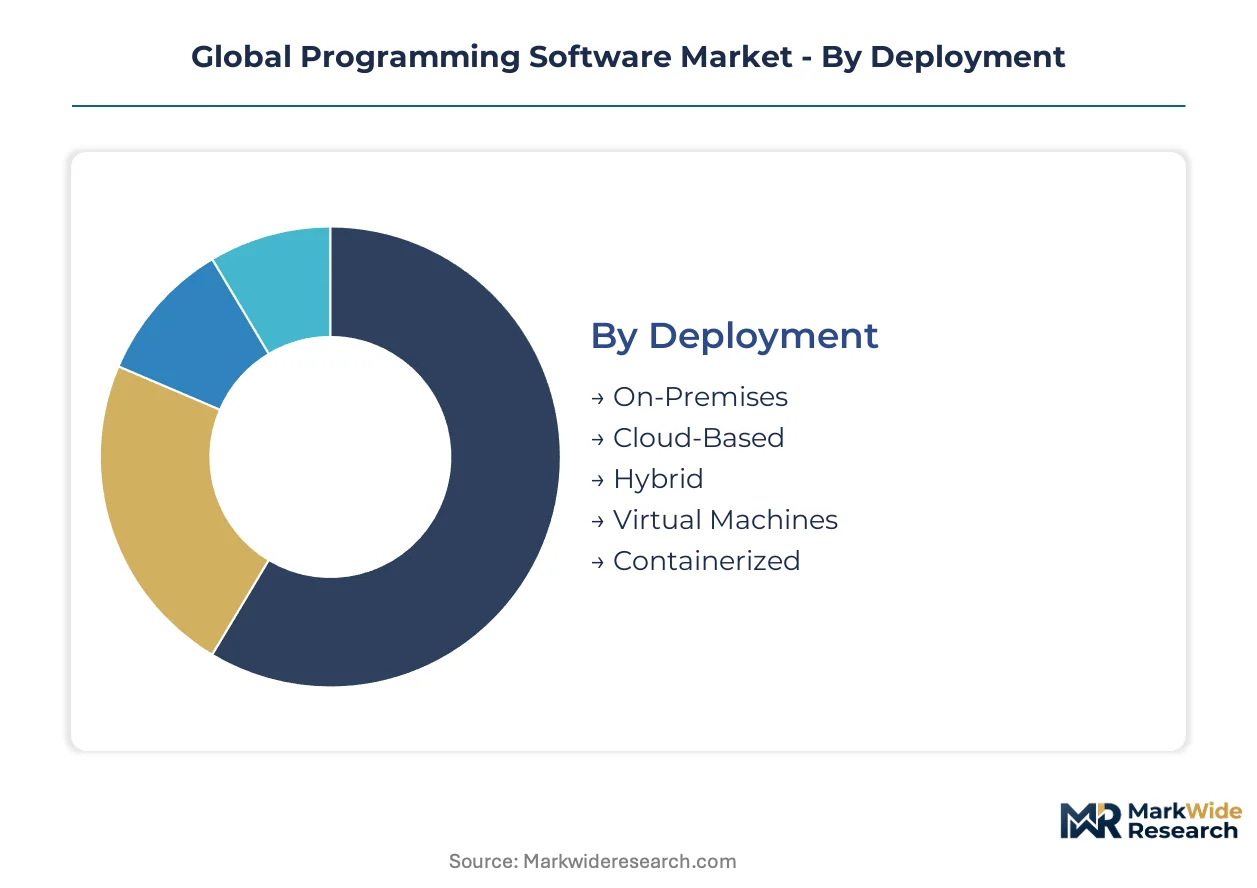
Programming software procurement patterns diverge sharply across deployment architectures, solution categories, and end-user sophistication levels. Segmentation reveals where pricing power concentrates and which customer cohorts drive technology roadmaps for toolchain vendors.
Deployment:
Cloud-based configurations dominate export-led procurement from multinational enterprises, while on-premises installations persist in domestic-sensitive sectors across Germany, Japan, and Saudi Arabia.
- Cloud-Based:Fully managed development environments provisioned through hyperscaler infrastructure eliminate capital expenditure for compute resources. United States defense contractors and Singaporean fintech clusters are standardizing on FedRAMP-authorized and MAS-regulated cloud IDEs respectively to satisfy data residency mandates without maintaining physical hardware.
- On-Premises:Self-hosted toolchains running within organizational data centers preserve complete operational control over source code and build artifacts. German automotive suppliers and Japanese semiconductor manufacturers retain these configurations to satisfy internal security audits and prevent intellectual property exposure during advanced systems programming.
- Hybrid:Split architectures combining local development workstations with cloud-based CI/CD pipelines. Brazilian enterprise software vendors deploy this model to optimize latency for daily coding while leveraging scalable build infrastructure.
- Virtual Machines:Isolated execution environments for consistent development-to-production parity. South Korean gaming studios standardize on VM-based toolchains to replicate target console architectures.
- Containerized:Docker and Kubernetes-orchestrated development environments ensuring reproducible builds. Indian IT consultancies serving North American clients adopt containerization to normalize dependencies across distributed engineering teams.
Cloud-based configurations hold the largest share; momentum sits with containerized deployments.
Solution Type:
Margin structures vary dramatically across this category, with subscription bundling concentrating profitability in integrated suites while specialized tools compete on technical depth.
- Integrated Development Environment:Comprehensive coding platforms combining editors, debuggers, build automation, and project management in unified interfaces. Microsoft Visual Studio and JetBrains IntelliJ anchor enterprise procurement in the United States and Eastern Europe through deep language ecosystem integration and plugin marketplaces.
- Version Control Systems:Distributed and centralized repositories tracking source code evolution with branching, merging, and audit trail capabilities. Git-based platforms are expanding most quickly among pharmaceutical developers in Switzerland and medical device manufacturers in the United States responding to FDA software-as-medical-device traceability requirements.
- Code Editors:Lightweight text-optimized environments emphasizing speed and extensibility over integrated tooling. Visual Studio Code dominates individual developer preference in Canada and Australia through Microsoft's zero-cost distribution model.
- Debuggers:Runtime inspection tools enabling breakpoint analysis, memory examination, and execution flow tracing. Specialized debuggers for embedded ARM architectures command premium pricing from automotive suppliers in Stuttgart and Munich.
- Profilers:Performance analysis utilities identifying computational bottlenecks and memory allocation patterns. Financial services developers in London and New York deploy these tools to satisfy latency budgets for high-frequency trading systems.
Integrated Development Environments capture the deepest margin pools; Version Control Systems are climbing the fastest.
Application:
End-use differentiation determines feature prioritization, with safety-critical domains demanding formal verification capabilities absent from consumer-facing development workflows.
- Enterprise Software:Large-scale business application development requiring multi-team coordination, legacy integration, and regulatory compliance modules. German insurance conglomerates and Dutch banking groups prioritize IDEs with embedded GDPR and EU AI Act documentation pipelines.
- Embedded Systems:Resource-constrained programming for microcontrollers, real-time operating systems, and IoT endpoints. Automotive suppliers in Nagoya and Detroit drive demand for Rust and MISRA-C compliant toolchains as software-defined vehicle architectures proliferate.
- Mobile Applications:iOS and Android development utilizing platform-specific SDKs and simulator integration. Indian mobile studios in Bangalore and Hyderabad standardize on cross-platform frameworks with hot-reload capabilities.
- Web Development:Browser-targeted application construction spanning frontend frameworks, backend APIs, and infrastructure-as-code. Brazilian SaaS vendors and Indonesian e-commerce platforms favor cloud-native IDEs with integrated deployment pipelines.
- Game Development:Real-time graphics programming, physics simulation, and asset pipeline management. Polish and Canadian studios cluster around Unreal Engine and Unity-integrated tooling with specialized profiling for GPU optimization.
Enterprise Software holds the largest share; Embedded Systems are gaining share fastest.
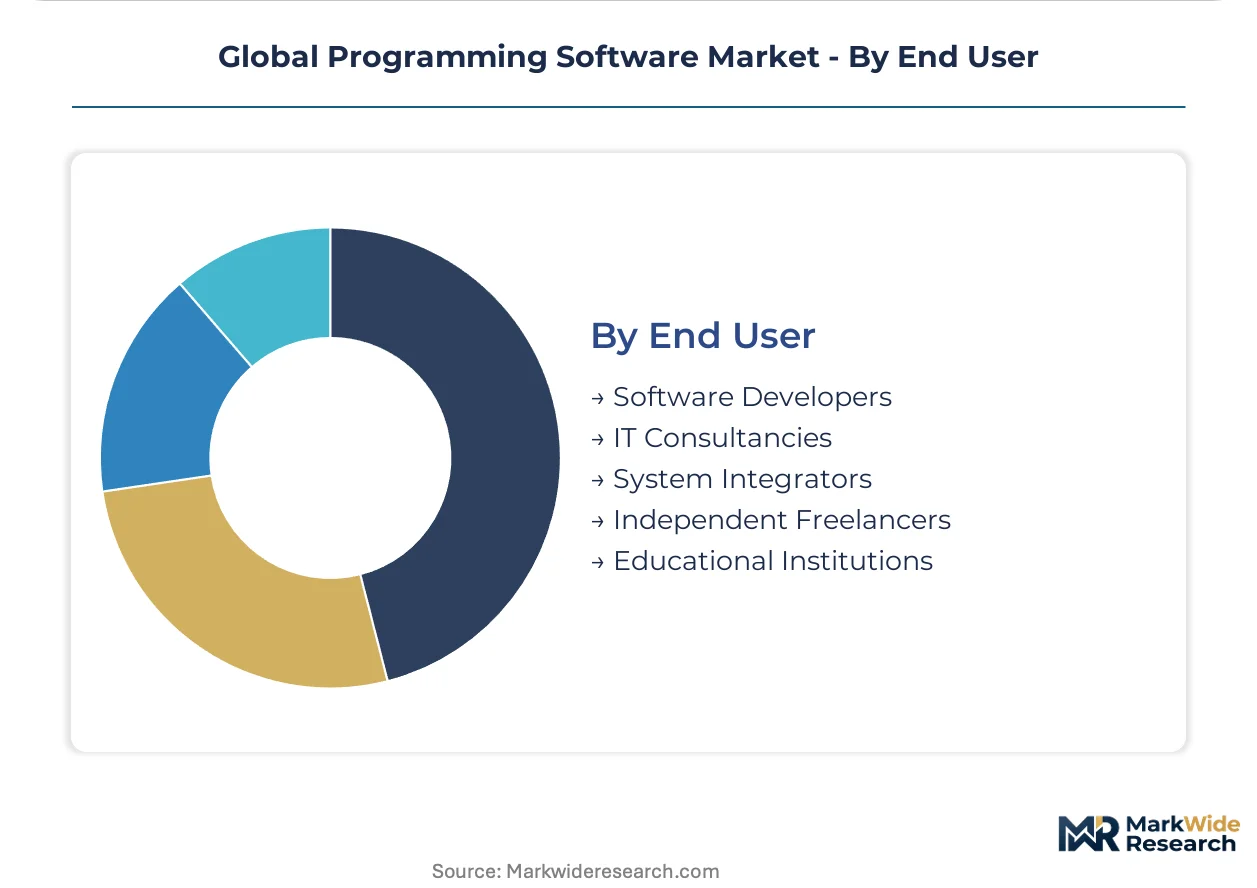
End User:
Purchasing authority and budget scale diverge substantially across this category, from individual subscription decisions to centralized enterprise procurement functions.
- Software Developers:Individual practitioners and team leads selecting personal productivity tools and influencing departmental standards. United States-based developers at Series B technology companies drive consumption-based licensing negotiations.
- IT Consultancies:Service organizations delivering custom development for external clients with standardized toolchains ensuring delivery consistency. Indian firms serving Fortune 500 accounts maintain approved vendor lists with security certification requirements.
- System Integrators:Complex enterprise implementation specialists requiring multi-vendor interoperability and government clearance compatibility. Federal contractors in Virginia and Maryland prioritize CMMI-compliant toolchains for Department of Defense engagements.
- Independent Freelancers:Self-employed developers purchasing individual licenses without enterprise support entitlements. Portuguese and Romanian freelancers cluster around open-source editors with minimal recurring costs.
- Educational Institutions:Universities and coding bootcamps training emerging developers with discounted or donated software licenses. South Korean technical institutes and German Fachhochschulen negotiate campus-wide agreements with JetBrains and GitHub.
IT Consultancies hold the largest share; momentum sits with System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-medical-device guidance is elevating validation requirements for healthcare programming environments in the United States, while the EU AI Act imposes documentation mandates that reshape European developer tooling procurement.
United States
Defense contractors in Virginia and Maryland are modernizing legacy codebases under federal modernization programs, generating sustained demand for refactoring and migration tooling. CMMI compliance requirements from the Department of Defense condition vendor selection for system integrators. The Washington-Baltimore corridor concentrates procurement authority among federal system integrators seeking FedRAMP-authorized cloud development environments.
Germany
Automotive suppliers in Stuttgart and Munich require Rust and MISRA-C compliant toolchains as software-defined vehicle architectures proliferate. The EU AI Act's algorithmic accountability provisions mandate immutable audit trails for training data and model versioning. Bavarian automotive clusters are retrofitting existing toolchains with automated documentation pipelines to satisfy regulator inspection protocols.
China
Domestic software manufacturing incentives under MIIT schemes are creating localized demand for indigenous development tooling ecosystems. National cryptography standards enforced by MIIT fragment debugging tool distribution, forcing costly localization or market exclusion. Shenzhen and Hangzhou technology corridors are incubating domestic IDE alternatives to foreign platforms.
India
IT consultancies in Bangalore and Hyderabad serving Fortune 500 accounts maintain approved vendor lists with security certification requirements. The PLI scheme for electronics manufacturing is stimulating indigenous development tooling procurement. Karnataka and Telangana technology clusters are standardizing on containerized development environments to normalize dependencies across distributed engineering teams.
United Kingdom
Financial services development teams in London are deploying large language model pair-programming systems for automated test generation and legacy code translation. GDPR documentation requirements intersect with emerging EU AI Act obligations for algorithmic traceability. The London-Singapore fintech corridor is standardizing on cloud-native IDEs with embedded compliance modules.
Global Programming Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Global Programming Software Market. Hyperscalers with cloud infrastructure dominance control the underlying compute layer, while specialized IDE vendors compete on language-specific technical depth. Three strategic archetypes have emerged: platform-integrated suites, language-specialized toolchains, and open-source ecosystem anchors. Competitive moves center on subscription bundling with adjacent collaboration modules and geographic localization to satisfy domestic cryptography requirements.
Within the integrated platform tier, Microsoft Corporation and Amazon Web Services exemplify hyperscaler dominance through deep infrastructure embedding. JetBrains occupies a specialist position among professional developers through purpose-built IDE architectures. These three anchors represent divergent strategic vectors: cloud-native workflow integration, language ecosystem depth, and developer community loyalty cultivation.
| Leading Market Players |
|---|
| Microsoft Corporation |
| JetBrains |
| Atlassian |
| Oracle Corporation |
| Amazon Web Services |
| GitHub |
| IBM |
| SAP |
| IntelliJ IDEA |
| Others |
Supply & Pricing Matrix
Containerized deployment architectures displacing traditional on-premises IDE licensing simultaneously redistribute supply geography toward hyperscaler data centers and compress pricing power for standalone toolchain vendors. This substitution dynamic forces incumbent providers to rebundle core editors with compliance modules and consumption-based metering to preserve margin extraction.
Pricing Analysis
Seat-based subscription contracts dominate enterprise procurement, though consumption-based metering is displacing fixed licensing among mid-market software vendors in Brazil and South Korea. Price differentiation hinges on FedRAMP authorization tier and embedded EU AI Act documentation capabilities, with certified compliance modules commanding substantial premiums. Pricing pressure stems from accumulated SaaS fatigue across overlapping toolchain categories, pressuring vendor consolidation. Independent freelancers exhibit highest price sensitivity, gravitating toward zero-cost open-source editors, while defense contractors demonstrate lowest sensitivity given CMMI compliance mandates.
Supply Chain Analysis
Inventory cycles for physical development hardware have collapsed to near-zero as cloud-based provisioning eliminates component lead times entirely. Supply concentration rests in United States hyperscaler infrastructure, German automotive tooling clusters, and Chinese domestic IDE alternatives incubating in Shenzhen and Hangzhou. Raw material dependencies include silicon for ARM-based debugging hardware, rare earth elements for server-grade compute, and specialized ASICs for GPU-accelerated profiling. Single-source vulnerability permeates cloud infrastructure concentration among three dominant hyperscalers. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Programming Software Market sits at a platform-economics inflection where interoperability standards and language ecosystem depth determine competitive survival. JetBrains' Kotlin-centric architecture and Microsoft's Azure-embedded tooling exemplify divergent ecosystem lock-in strategies reshaping procurement authority.
For Market Incumbents: Shield core subscription revenue by embedding compliance modules for EU AI Act and FDA software-as-medical-device traceability requirements before emerging specialists capture regulatory premium tiers. Accelerate backward integration into cloud infrastructure layers to reduce hyperscaler dependency and preserve development environment portability for enterprise buyers. For New Entrants and Emerging Players: Anchor in India's PLI-scheme stimulated indigenous tooling demand and Germany's automotive Rust toolchain migration as white-space targets with limited incumbent saturation. Target containerized deployment segments among Indian IT consultancies serving North American Fortune 500 accounts through security certification-first go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists holding FDA-validated healthcare programming environments and automotive MISRA-C compliance toolchains. Long-term viability across the analysis window favors platforms with embedded AI assistant architectures over standalone editors. Watch hyperscaler marketplace revenue share negotiations as the signal indicating platform power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Azure embedding enables Microsoft to capture federal modernization procurement in Virginia and Maryland. |
| Acquisition of Specialist Firm | Consolidation of Rust-focused IDE capabilities addresses automotive supplier demand in Stuttgart and Munich. |
| Geographic Expansion | Localization for China's MIIT cryptography standards unlocks domestic market access versus exclusion. |
| Product Launch | Agentic coding assistants with immutable audit trails satisfy EU AI Act mandates for German pharmaceutical developers. |
| Strategic Partnership | FedRAMP-authorized cloud IDE alliances position vendors for Department of Defense contractor procurement. |
Research Methodology
Operator-level perspectives from CTOs at Series B technology companies, IT procurement officers at German insurance conglomerates, platform engineers at Indian IT consultancies, and federal system integrators in the Washington-Baltimore corridor anchored the qualitative base. Secondary validation drew from SEC filings of publicly traded toolchain vendors, hyperscaler capex disclosures, EU AI Act regulatory documentation, and FDA software-as-medical-device guidance repositories. Bottom-up deployment model sizing and top-down enterprise software spend allocation provided triangulation across the analysis window.
Sensitivity analysis around cloud adoption velocity and compliance module attach rates framed the forecast envelope. Segmentation dimensions modeled encompass deployment architecture, solution type, application vertical, and end-user sophistication tier. CAGRs were derived from weighted scenario probabilities across the projection horizon. Industry-specific inputs included Git repository growth metrics, IDE plugin marketplace transaction velocity, and federal IT modernization budget allocations.
Material uncertainties — abrupt regulatory fragmentation between EU AI Act, FDA, and MIIT jurisdictions, hyperscaler marketplace term renegotiations, and generative AI capability disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interoperability standard adoption and compliance automation penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Africa Sports Management Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Payroll and HR Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Staffing Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Data Visualization Software Market
Software & Services
Warranty Management Software Market