
 Global Embedded Database Management Systems Market | 2026-2036
Global Embedded Database Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embedded Database Management Systems Market Foresight
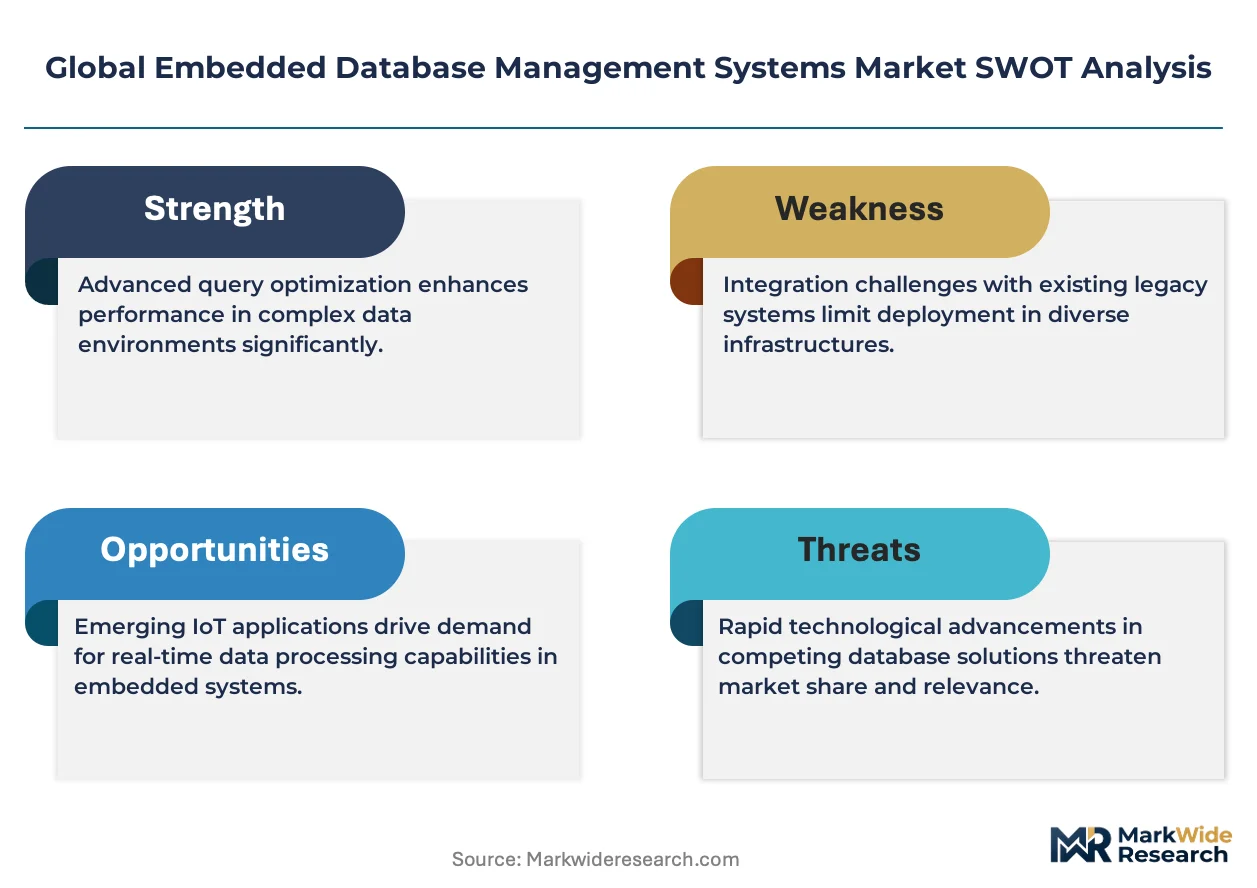
Edge-grade reliability certification is unwinding legacy assumptions about embedded database fitness for autonomous systems. Microsoft leverages its Azure Sphere integration to sustain hybrid edge-to-cloud data synchronization across industrial IoT deployments. Oracle anchors high-availability embedded configurations in telecommunications infrastructure where sub-millisecond failover tolerances apply. SAP SE differentiates through in-memory compression algorithms that reduce footprint in resource-constrained robotics controllers.
Embedded database management systems are lightweight, zero-administration data engines designed to operate within firmware or application binaries without external server dependencies, typically supporting ACID compliance or BASE consistency models with memory footprints under 50 MB. These systems serve real-time data persistence, query processing, and transactional logging in devices where network connectivity is intermittent or latency budgets are measured in microseconds. NoSQL deployments are capturing the fastest expansion as time-series and document stores displace relational schemas in telematics and sensor-heavy industrial automation workloads. Edge computing deployment models are concentrating margin pools where semiconductor companies and device manufacturers demand pre-certified, hardware-integrated database libraries.
FDA software validation guidelines and the EU AI Act are elevating traceability and deterministic behavior requirements for embedded databases in aerospace and medical-adjacent applications. ETSI cybersecurity standards and ISO 26262 functional safety mandates are reshaping vendor qualification criteria across European and Japanese automotive supply chains. Stakeholders must monitor how NHTSA autonomous vehicle guidance and China's MIIT data localization rules will bifurcate certification pathways for cross-border embedded software shipments.
Market Dynamics
Edge-native data engines are forcing embedded database vendors to recertify entire product lines for deterministic latency guarantees, compressing development cycles and fragmenting competitive tiers.
Growth Catalysts
- EU AI Act traceability mandates:Aerospace and medical device manufacturers are procuring deterministic embedded databases with immutable audit logs for algorithmic decision tracking.
- Time-series sensor fusion:Autonomous vehicle programs in Germany, Japan, and the United States are demanding sub-microsecond write latency for LiDAR and camera data correlation.
- Industrial automation clusters:Manufacturing hubs in Stuttgart, Nagoya, and Detroit are standardizing on pre-certified embedded database libraries bundled with semiconductor reference designs.
Market Restraints
- Silicon supply concentration:Foundry capacity constraints in Taiwan are delaying hardware-integrated database certifications for automotive Tier-1 suppliers.
- ISO 26262 functional safety costs:ASIL-D compliance testing for embedded databases in braking and steering systems requires 18-24 month validation cycles.
- Memory footprint limitations:Sub-50 MB operational constraints prevent relational schema adoption in resource-constrained robotics controllers.
Strategic Opportunities
- India's industrial corridor expansion:PLI scheme incentives for semiconductor packaging are creating localized demand for embedded databases in smart manufacturing equipment.
- Telecommunications edge infrastructure:5G Open RAN deployments require zero-administration data persistence for distributed radio units with intermittent backhaul connectivity.
- FDA software validation harmonization:Pre-certified embedded database modules are reducing time-to-market for connected medical devices requiring 21 CFR Part 11 compliance.
Industry Challenges
- Deterministic behavior engineering:Talent scarcity in hard real-time systems programming is constraining vendor capacity to deliver WCET-guaranteed database engines.
- Cross-certification complexity:ETSI cybersecurity standards and ISO 26262 functional safety mandates require parallel validation tracks for European automotive shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embedded Database Management Systems Market |
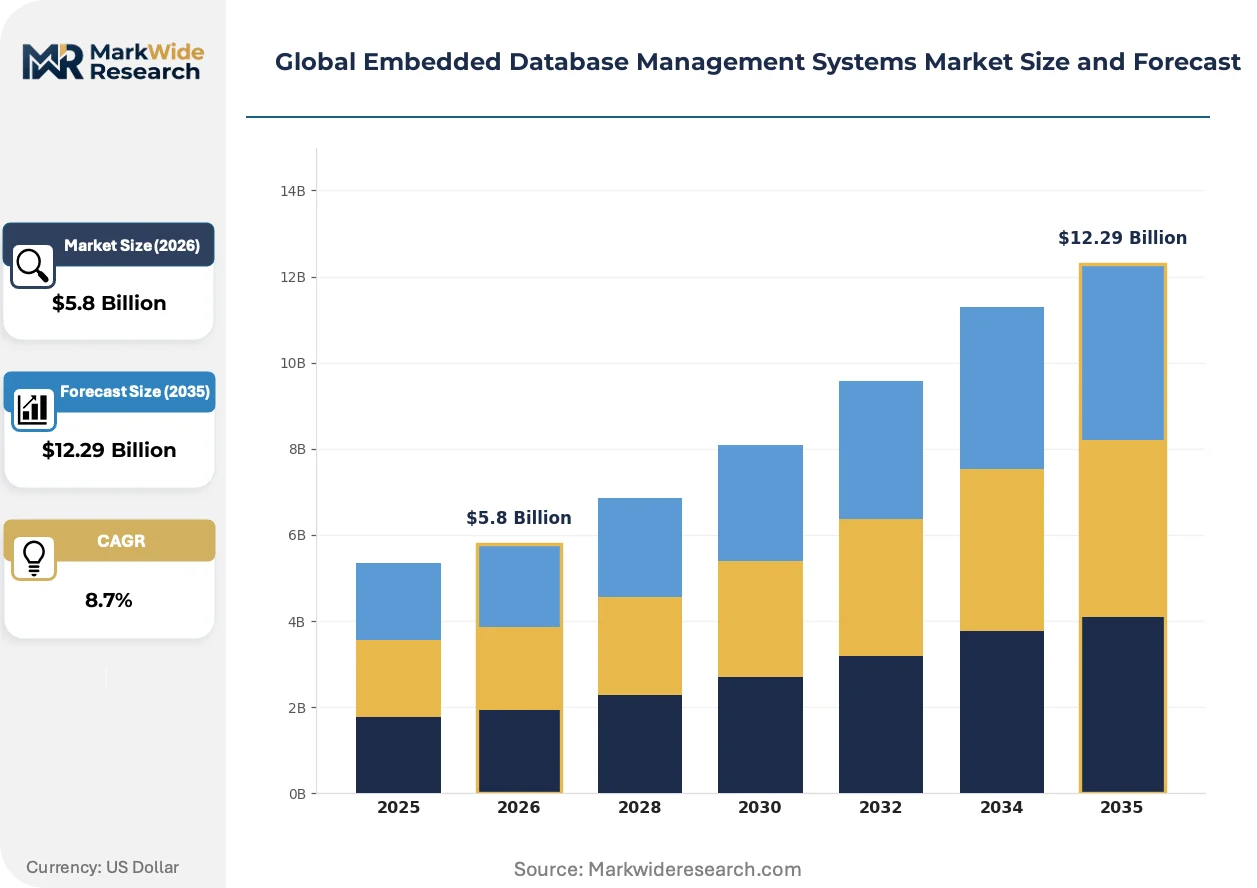
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Relational, NoSQL, Time-Series, Object-Oriented, XML, Multi-Model Deployment: On-Premise, Cloud-Based, Hybrid Cloud, Edge Computing Application: Telematics, Robotics, Consumer Electronics, Industrial Automation, Aerospace, Telecommunications End User: Software Vendors, System Integrators, Semiconductor Companies, Device Manufacturers, Research Institutes |
| Companies Covered | Microsoft, Oracle, IBM, SAP SE, McObject LLC, Raima, Inc., SQLite, HSQL Development Group, PostgreSQL Global Development Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embedded Database Management Systems Market Shifts & Advancements
NoSQL document and time-series stores are actively restructuring embedded database procurement patterns, with buyers prioritizing schema flexibility over ACID guarantees in sensor-heavy workloads.
In-memory compression algorithms are supplanting traditional page-based storage managers in robotics controllers. Automotive OEMs in Japan and Germany are adopting these engines for kinematic data logging. The shift is compressing database footprints by half, enabling single-chip deployments that previously required external DRAM.
The EU AI Act and FDA software validation guidelines are mandating immutable audit trails for algorithmic decisions in safety-critical systems. Medical device manufacturers are embedding append-only database engines for training data provenance. European aerospace suppliers are responding with deterministic logging modes that disable garbage collection during inference operations.
Semiconductor vendors are unbundling database libraries from reference design kits and offering them as subscription-licensed IP cores. Industrial automation buyers in the United States are accepting recurring fees for continuous security patches. This model is displacing perpetual license structures in factory automation procurement, with German automotive clusters showing parallel adoption.
Global Embedded Database Management Systems Market Segmentation
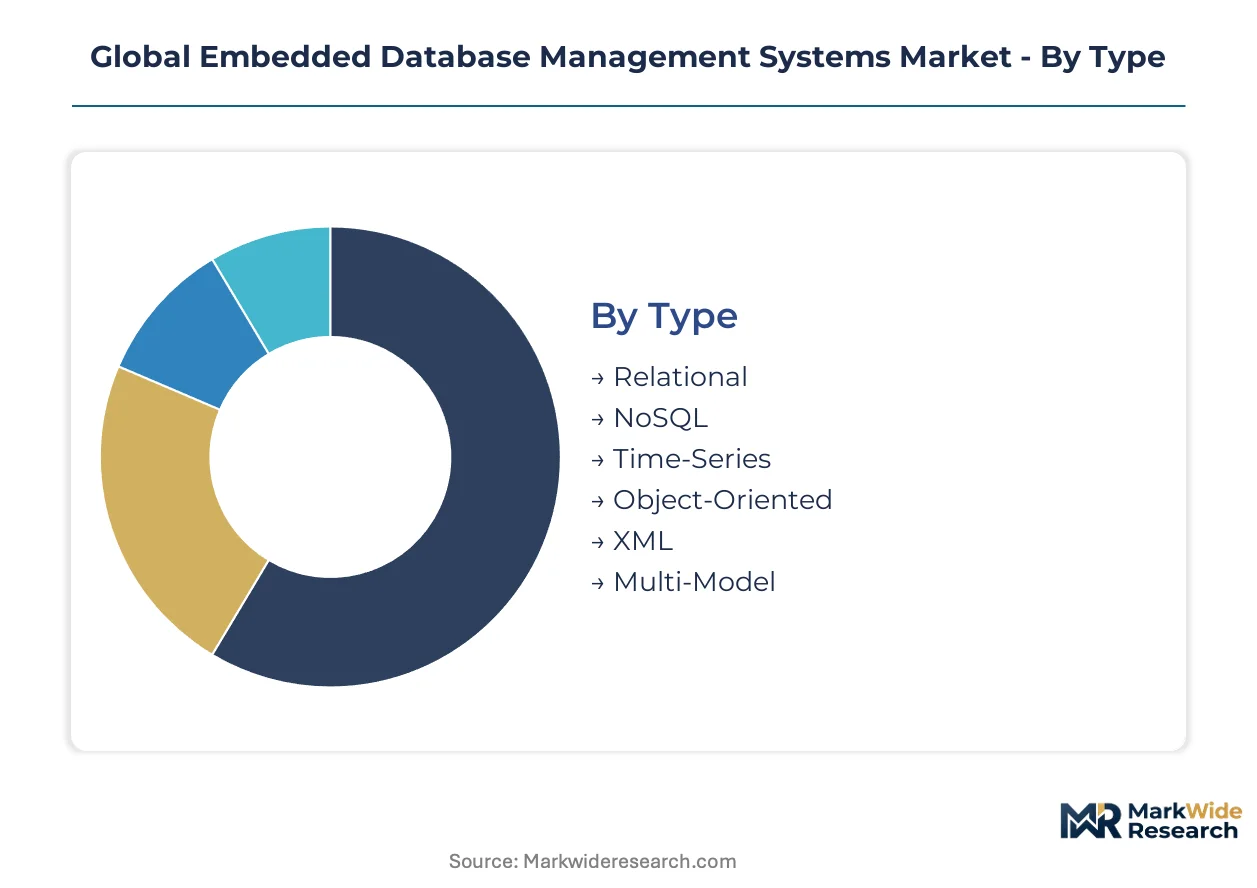
Embedded database architectures fragment sharply across workload types and deployment constraints, with each segment demanding distinct certification rigor and latency guarantees. Procurement patterns diverge between automotive OEMs seeking deterministic engines and industrial buyers prioritizing schema flexibility for sensor fusion pipelines.
Type:
NoSQL and time-series engines dominate export-led procurement from Germany and Japan, while relational and XML variants serve domestic-heavy medical device validation in the United States.
- NoSQL:Document and key-value stores enable schema evolution in robotics controllers without migration downtime. German automotive clusters in Stuttgart procure these engines for LiDAR data ingestion where structure varies by sensor generation.
- Time-Series:Specialized compression algorithms handle high-velocity telemetry with sub-microsecond write guarantees. Japanese OEMs in Nagoya embed these for powertrain monitoring under METI efficiency mandates.
- Relational:ACID-compliant engines persist in FDA-regulated medical devices requiring 21 CFR Part 11 audit trails.
- Object-Oriented:Complex data type support suits aerospace simulation workloads with nested geometric models.
- XML:Document-centric storage persists in legacy telecommunications configuration management.
- Multi-Model:Unified query engines reduce footprint in resource-constrained consumer electronics.
NoSQL holds the largest share; momentum sits with time-series as autonomous vehicle programs scale.
Deployment:
Cost tiering separates premium edge-native certifications from standard cloud-hybrid configurations, with semiconductor vendors bundling the former at 3-4x license multiples.
- Edge Computing:Zero-administration engines with deterministic WCET guarantees operate without external DRAM. Detroit automation clusters standardize on these for welding robot controllers where backhaul latency exceeds cycle budgets.
- Hybrid Cloud:Synchronization protocols maintain consistency across intermittent connectivity. Telecommunications infrastructure in the United States deploys these for Open RAN distributed units.
- On-Premise:Air-gapped deployments persist in defense-adjacent aerospace applications.
- Cloud-Based:Managed instances serve research institutes with elastic compute requirements.
Edge computing commands premium pricing; hybrid cloud is expanding most quickly as 5G infrastructure deploys.
Application:
Volume concentration tracks semiconductor ecosystem density, with telematics and industrial automation anchoring procurement in manufacturing corridors.
- Industrial Automation:Pre-certified database libraries ship with reference designs from semiconductor vendors. Stuttgart, Nagoya, and Detroit factories standardize on these for programmable logic controller data logging.
- Telematics:Time-series engines correlate GPS, accelerometer, and engine telemetry for fleet optimization. German logistics operators embed these under EU AI Act traceability requirements.
- Robotics:Kinematic data logging demands sub-50 MB footprints with deterministic garbage collection.
- Aerospace:ASIL-D equivalent reliability applies to flight control data persistence.
- Telecommunications:Subscriber data management requires five-nines availability in base station controllers.
- Consumer Electronics:Wearables prioritize power efficiency over query complexity.
Industrial automation holds the largest share; robotics shows the steepest expansion trajectory as kinematic logging demands intensify.
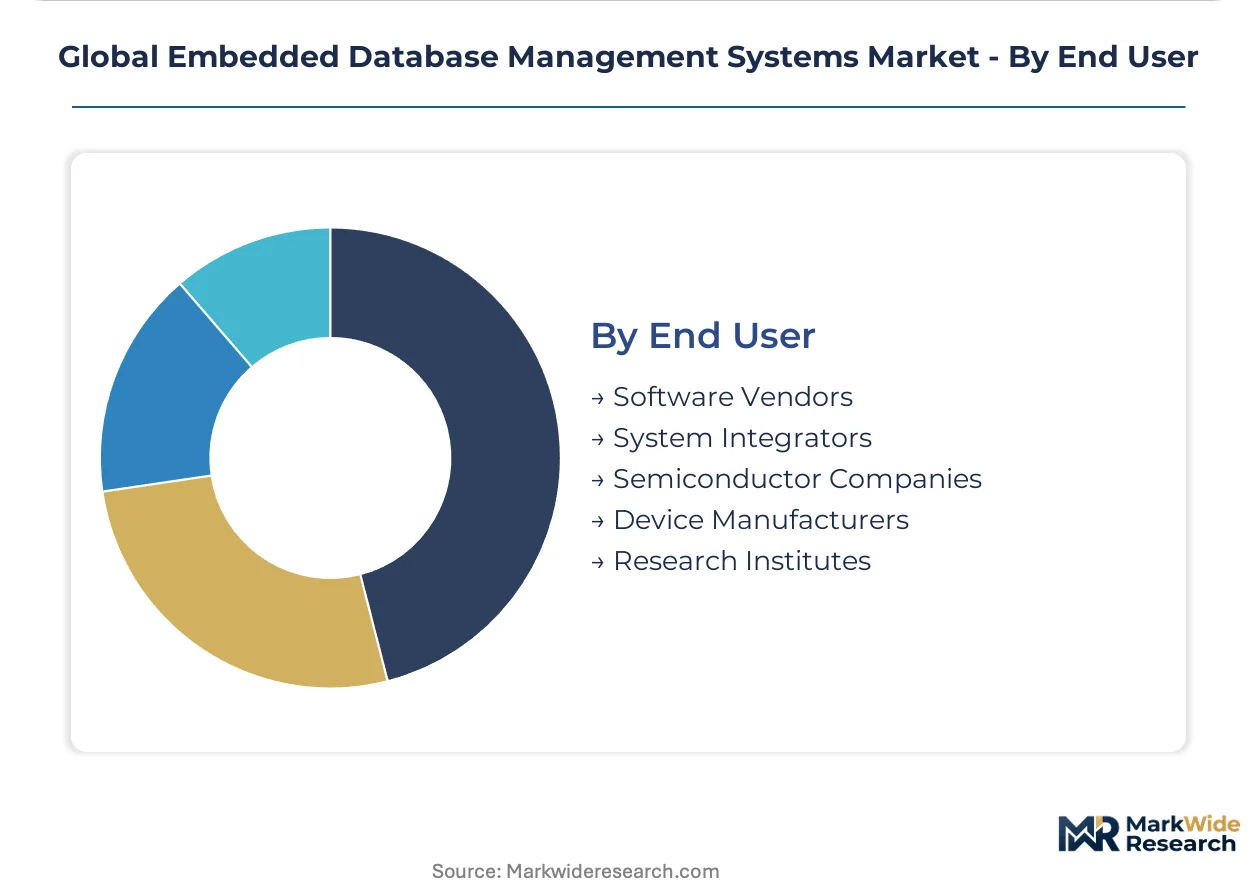
End User:
Customer type determines procurement modality, with semiconductor companies driving hardware-integrated licensing and system integrators managing multi-vendor certification complexity.
- Semiconductor Companies:Subscription-licensed IP cores replace perpetual structures in reference design kits. United States industrial buyers accept recurring fees for continuous security patches.
- Device Manufacturers:Vertical integration demands span automotive Tier-1 suppliers to medical device OEMs facing FDA validation cycles.
- System Integrators:Cross-certification management for ETSI and ISO 26262 parallel tracks.
- Software Vendors:White-label embedded engines for vertical application suites.
- Research Institutes:Experimental deployments with relaxed determinism requirements.
Semiconductor companies hold the largest share; device manufacturers are gaining share fastest as automotive OEMs internalize database selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in embedded database IP cores track semiconductor ecosystem density, with net exporters concentrated in Germany, Japan, and the United States while import-dependent manufacturing clusters in India and China drive localization mandates.
United States
FDA software validation requirements and NHTSA autonomous vehicle guidance are accelerating deterministic database procurement for medical devices and automotive Tier-1 suppliers. Detroit's industrial automation corridor standardizes on pre-certified embedded libraries for welding robot controllers where sub-millisecond latency tolerances apply. Domestic semiconductor vendors bundle subscription-licensed database IP cores with reference designs, displacing perpetual licensing structures in factory automation procurement.
Germany
EU AI Act traceability mandates and ISO 26262 functional safety requirements are reshaping vendor qualification criteria across automotive supply chains. Stuttgart's manufacturing hub demands schema-flexible NoSQL engines for LiDAR data ingestion where sensor structures vary by generation. KBA certification timelines of 18-24 months for ASIL-D compliance are compressing development cycles and fragmenting competitive tiers among embedded database vendors.
Japan
METI efficiency mandates for powertrain monitoring and ETSI cybersecurity standards are concentrating procurement in time-series engines with specialized compression algorithms. Nagoya's automotive OEMs embed sub-microsecond write guarantee databases for telemetry correlation under deterministic latency requirements. Domestic semiconductor ecosystems anchor hardware-integrated database library shipments across robotics and industrial controller applications.
India
PLI scheme incentives for semiconductor packaging and smart manufacturing equipment are creating localized demand for embedded databases in industrial corridors. The country's national electronics regulator is tightening data localization requirements for cross-border embedded software shipments. Gujarat and Karnataka industrial zones are standardizing on edge-native data engines for programmable logic controller deployments in export-oriented manufacturing facilities.
China
MIIT data localization rules and dual carbon goals are bifurcating certification pathways for foreign embedded database vendors while accelerating domestic substitution. Yangtze River Delta semiconductor foundries are integrating hardware-optimized database libraries with reference design kits for robotics and telecommunications infrastructure. State-backed industrial automation programs in Shenzhen and Shanghai are prioritizing zero-administration engines with deterministic garbage collection for kinematic data logging applications.
Global Embedded Database Management Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and licensing modality, with public technology conglomerates leveraging cloud integration ecosystems against focused embedded engine developers. The vendor base stratifies into three tiers: diversified platform providers with hybrid edge-to-cloud synchronization capabilities, deterministic database specialists pursuing ASIL-D and FDA pre-certification, and open-source communities monetizing through support subscriptions. Consolidation pressure intensifies as automotive OEMs internalize database selection and demand end-to-end liability chains. Dominant competitive moves include strategic partnerships with semiconductor reference design programs and geographic expansion into India's PLI-subsidized industrial corridors.
Within the diversified platform tier, Microsoft and Oracle occupy positions anchoring hybrid synchronization and high-availability configurations respectively, while SAP SE exemplifies the in-memory compression specialization vector for resource-constrained robotics controllers. Among focused embedded engine developers, McObject LLC and Raima, Inc. represent the deterministic certification depth archetype, sitting within vendor pools pre-qualified for ISO 26262 and FDA validation cycles. SQLite occupies a unique position as the open-source anchor, with its public-domain licensing model displacing commercial alternatives in consumer electronics and telecommunications edge infrastructure where zero procurement friction outweighs enterprise support requirements.
| Leading Market Players |
|---|
| Microsoft |
| Oracle |
| IBM |
| SAP SE |
| McObject LLC |
| Raima, Inc. |
| SQLite |
| HSQL Development Group |
| PostgreSQL Global Development Group |
| Others |
Supply & Pricing Matrix
ISO 26262 ASIL-D certification gates both supply qualification and price differentiation simultaneously, compressing vendor margins through extended validation cycles while enabling premium positioning for pre-certified embedded database libraries in automotive braking and steering systems. Industrial OEM buyers anchor pricing stratification across three certification tiers, with edge-native engines commanding multiples over standard cloud-hybrid configurations due to deterministic WCET guarantees and zero-administration operational requirements. Price differentiation rests on ASIL-D pre-certification status and semiconductor reference design bundling, with cost compression in mid-tier offerings intensifying as Taiwanese foundry constraints delay hardware-integrated certifications. Tier-1 automotive suppliers exhibit lowest price sensitivity given liability chain requirements, while consumer electronics manufacturers drive pricing softness through volume procurement of open-source alternatives.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across three certification tiers, with edge-native engines commanding multiples over standard cloud-hybrid configurations due to deterministic WCET guarantees and zero-administration operational requirements. Price differentiation rests on ASIL-D pre-certification status and semiconductor reference design bundling, with cost compression in mid-tier offerings intensifying as Taiwanese foundry constraints delay hardware-integrated certifications. Tier-1 automotive suppliers exhibit lowest price sensitivity given liability chain requirements, while consumer electronics manufacturers drive pricing softness through volume procurement of open-source alternatives.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication capacity for automotive-grade microcontrollers that host embedded database engines, with Germany and Japan supplying specialized semiconductor IP for deterministic data persistence. The supply chain draws from silicon wafers, automotive-grade DRAM, and pre-certified software libraries, with single-source vulnerability concentrated in advanced node foundry capacity. Distribution runs through semiconductor reference design kits and direct licensing to automotive Tier-1 suppliers, with subscription models displacing perpetual structures in factory automation procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded database market rewards vendors with proven hard real-time systems engineering capabilities, a skill pool concentrated among legacy aerospace and automotive software suppliers with decades of deterministic programming experience. Talent scarcity in WCET-guaranteed database engine development constrains competitive entry and sustains incumbent positioning.
For Market Incumbents: Shield certification depth advantages by accelerating ASIL-D pre-validation for entire product portfolios before automotive OEMs internalize database selection, while deepening backward integration into semiconductor reference design partnerships to lock in distribution channels against emerging IP-core competitors. For New Entrants and Emerging Players: Differentiate on deterministic garbage collection engineering for kinematic data logging in robotics controllers, where sub-50 MB footprint requirements and METI efficiency mandates create white-space opportunity absent from saturated automotive telematics segments, leveraging India's PLI-subsidized industrial corridors as beachhead geography. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge-native certification programs as 18-24 month validation cycles and parallel ETSI cybersecurity tracks demand sustained R&D commitment, favoring acquisition targets with existing ISO 26262 and FDA 21 CFR Part 11 pre-certifications over greenfield development plays, with the signal to watch being NHTSA autonomous vehicle guidance harmonization with EU AI Act traceability mandates.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Pre-Certification Acceleration | Reduces automotive OEM procurement friction under KBA and NHTSA timelines. |
| Semiconductor IP Core Licensing | Locks in recurring revenue through reference design bundling with Qualcomm and NXP. |
| India PLI Corridor Expansion | Captures localized demand in Gujarat and Karnataka smart manufacturing zones. |
| Time-Series Compression R&D | Enables single-chip deployments for Japanese powertrain monitoring mandates. |
| Open-Source Support Monetization | Converts SQLite displacement risk into enterprise subscription revenue streams. |
Research Methodology
Cross-validation between primary interviews with automotive platform engineers, embedded software architects, semiconductor product managers, and Tier-1 supplier procurement leads anchors the qualitative findings, with secondary validation drawing from SEC 10-K filings, ETSI cybersecurity standard drafts, FDA 510(k) submission databases, and METI efficiency mandate disclosures. Bottom-up triangulation across deployment model, database architecture type, application vertical, and regional regulatory cluster dimensions integrates with top-down macroeconomic anchoring.
Sensitivity analysis across the projection horizon tests forecast robustness to foundry capacity constraints, EU AI Act implementation timelines, and NHTSA guidance evolution, with segmentation modeling spanning edge-hybrid-cloud deployment tiers, NoSQL-time-series-relational architecture types, and automotive-industrial-telecommunications application clusters. CAGRs derive from unit economics modeling of semiconductor reference design attach rates and subscription license conversion patterns.
Forecasts assume regulatory continuity in EU AI Act traceability mandates, FDA software validation guidelines, and ISO 26262 functional safety regimes; material policy shifts in NHTSA autonomous vehicle guidance or MIIT data localization rules would require re-modeling. Recalibration cycles align with material shifts in semiconductor foundry capacity allocation and automotive OEM internalization of database selection authority.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Accounts Receivable Software Market
Software & Services
Programming Language Market
Software & Services
Video Server Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Global User Interface Service Market
Software & Services
Freight Forwarding Software Market
Software & Services
Cemetery Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Sales Gamification Software Market
Software & Services
Quote Management Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Global OKR Software Market