
 Service Scheduling Software Market | 2026-2036
Service Scheduling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Service Scheduling Software Market Insights
API-first architecture is hardening as the default integration layer for service scheduling platforms, displacing legacy middleware stacks that once dominated enterprise deployments. ServiceTitan leverages native payment processing and financing tools to deepen contractor retention. Jobber anchors its position among small-to-mid-sized trade businesses through intuitive mobile-first design. SAP Field Service Management competes on industrial-scale asset management integrations for manufacturing and utilities.
Service scheduling software coordinates workforce dispatch, customer appointment booking, and resource allocation through real-time calendar synchronization and GPS-enabled routing algorithms, typically deployed via cloud infrastructure with sub-second update latency. Its primary commercial purpose is minimizing technician idle time and customer no-shows while maximizing daily job completion rates. Cloud-based deployment now leads the deployment model segment as SMBs abandon on-premises servers for zero-maintenance SaaS consumption. Field service management commands the largest service type segment due to its complexity and higher per-seat pricing. Subscription-based pricing dominates revenue models by locking in predictable recurring streams and lowering upfront adoption barriers.
FCC guidelines on telecommunications reliability shape how cloud-hosted scheduling platforms architect failover systems, while state-level contractor licensing boards in the US increasingly mandate digital record-keeping that scheduling software satisfies. HIPAA compliance requirements extend into healthcare provider deployments, restricting how patient appointment data flows through third-party APIs. Stakeholders must weigh data residency obligations against multi-tenant cloud economics when selecting vendors.
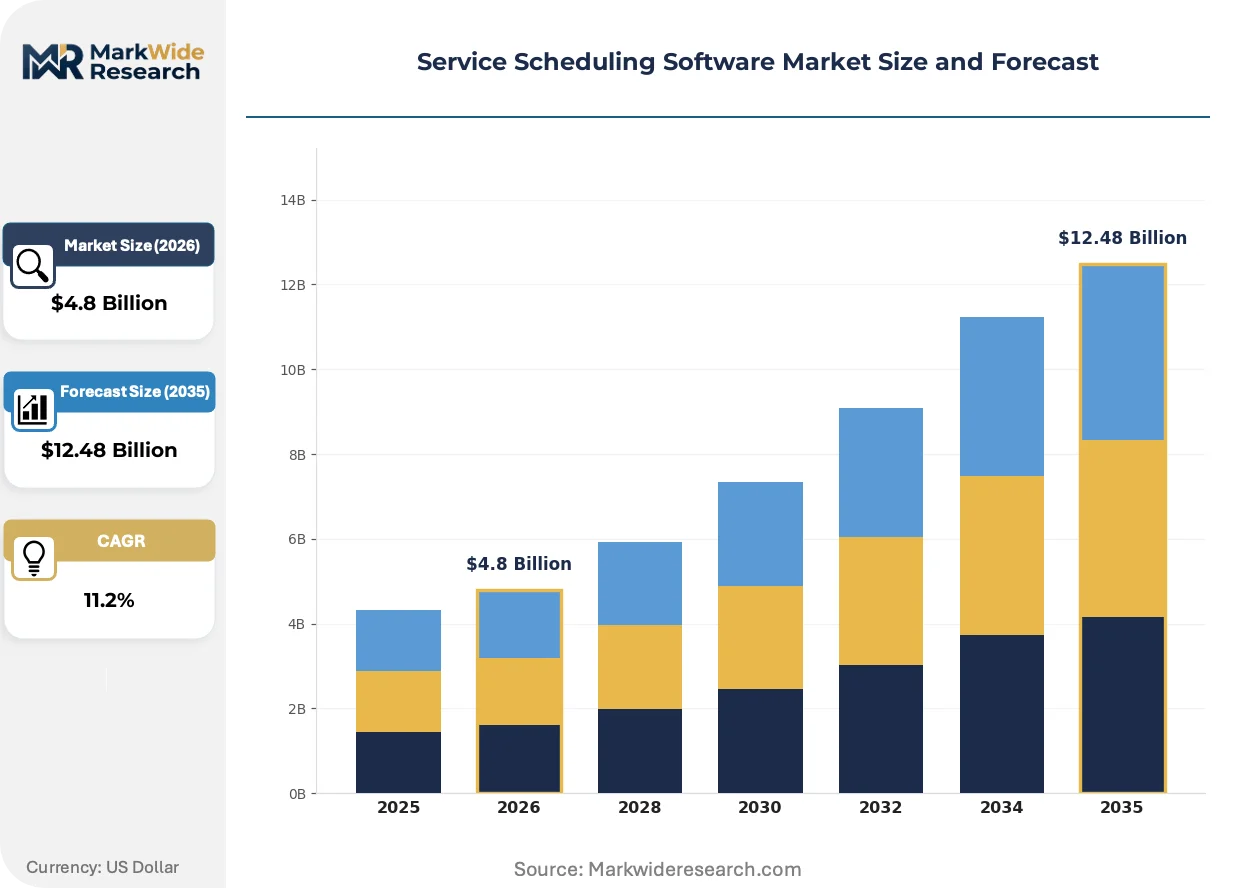
Market Dynamics
API-first architecture is compressing deployment cycles from months to weeks, forcing legacy middleware vendors to restructure integration layers or lose enterprise accounts to cloud-native competitors.
Growth Catalysts
- Telecommunications Reliability Mandates:FCC guidelines on failover systems push cloud-hosted platforms to architect redundant infrastructure, accelerating enterprise adoption of SaaS scheduling stacks over on-premises alternatives.
- Healthcare Digital Record Requirements:HIPAA compliance mandates for patient appointment data flows drive healthcare providers toward certified scheduling platforms with encrypted API gateways and audit-ready logging.
- Mobile-First Workforce Expectations:Field technicians now demand real-time calendar synchronization and GPS-enabled routing through native iOS and Android applications, forcing platform vendors to prioritize mobile UX in development roadmaps.
Market Restraints
- Data Residency Compliance Costs:Multi-tenant cloud economics clash with state-level contractor licensing board mandates for localized record storage, forcing vendors to maintain redundant regional data centers.
- Legacy System Integration Friction:On-premises ERP and accounting systems in established trades resist API connectivity, requiring expensive middleware bridges that erode SaaS margin structures.
- Skilled Implementation Labor Scarcity:Certified deployment specialists for field service management platforms concentrate in urban technology hubs, extending rollout timelines for rural contractor markets.
Strategic Opportunities
- Underpenetrated Specialty Trades:Pool maintenance, landscaping, and pest control segments in the United States lack vertical-specific scheduling tools, presenting white space for purpose-built workflow modules.
- Embedded Financing Convergence:Native payment processing and consumer financing tools integrated directly into scheduling platforms capture contractor transaction revenue streams previously lost to third-party processors.
- Industrial Asset Management Expansion:Manufacturing and utilities sectors require scheduling software that synchronizes with predictive maintenance systems, opening premium pricing tiers for IoT-enabled dispatch platforms.
Industry Challenges
- Technician Onboarding Complexity:Field workers unfamiliar with digital tools require sustained training investments, increasing customer success costs and extending time-to-value metrics for vendor sales teams.
- Cross-Platform Data Synchronization:Real-time calendar updates across Google, Microsoft, and proprietary systems demand continuous API maintenance, consuming engineering resources that could advance core routing algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Scheduling Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Appointment Management, Field Service Management, Resource Scheduling, Calendar Management Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Healthcare Providers, Educational Institutions, Building Maintenance, Organizations Pricing Model: Subscription-Based, Pay-Per-Use, One-Time License, Freemium |
| Companies Covered | ServiceTitan, Jobber, Housecall Pro, Zendesk, ServiceNow Field Service Management, SAP Field Service Management, ServiceMax, Oracle Field Service Cloud, monday service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Scheduling Software Market Trends and Innovations
Artificial intelligence is restructuring how service scheduling platforms predict technician availability, customer cancellation probability, and optimal route sequencing, compressing the gap between data ingestion and dispatch decision.
Machine learning models trained on historical job completion times and traffic patterns are electrifying predictive dispatch capabilities, enabling platforms to auto-assign appointments before customers finish booking flows. Mid-sized HVAC and plumbing contractors in Texas and Florida are piloting these systems during peak summer seasons. The technology is compressing average response windows from same-day to within-two-hour guarantees, reshaping competitive differentiation around speed rather than price.
GDPR data portability requirements and the EU AI Act's risk classification framework are forcing scheduling vendors serving European markets to implement explainable algorithms for automated technician assignments. Industrial consequences include mandatory human-in-the-loop overrides for high-stakes dispatch decisions in healthcare and critical infrastructure. German and French facility management firms now demand algorithmic audit trails as standard procurement criteria, filtering out black-box systems from vendor shortlists.
Subscription fatigue among small contractors is driving preference for usage-based pricing models that scale with active job volume rather than fixed seat counts. Independent tradespeople in California and New York are abandoning annual contracts for month-to-month platforms with zero onboarding fees. This behavioral shift pressures incumbent vendors to unbundle implementation and training services, transforming revenue recognition from upfront to ratable patterns.
Service Scheduling Software Market Segmentation
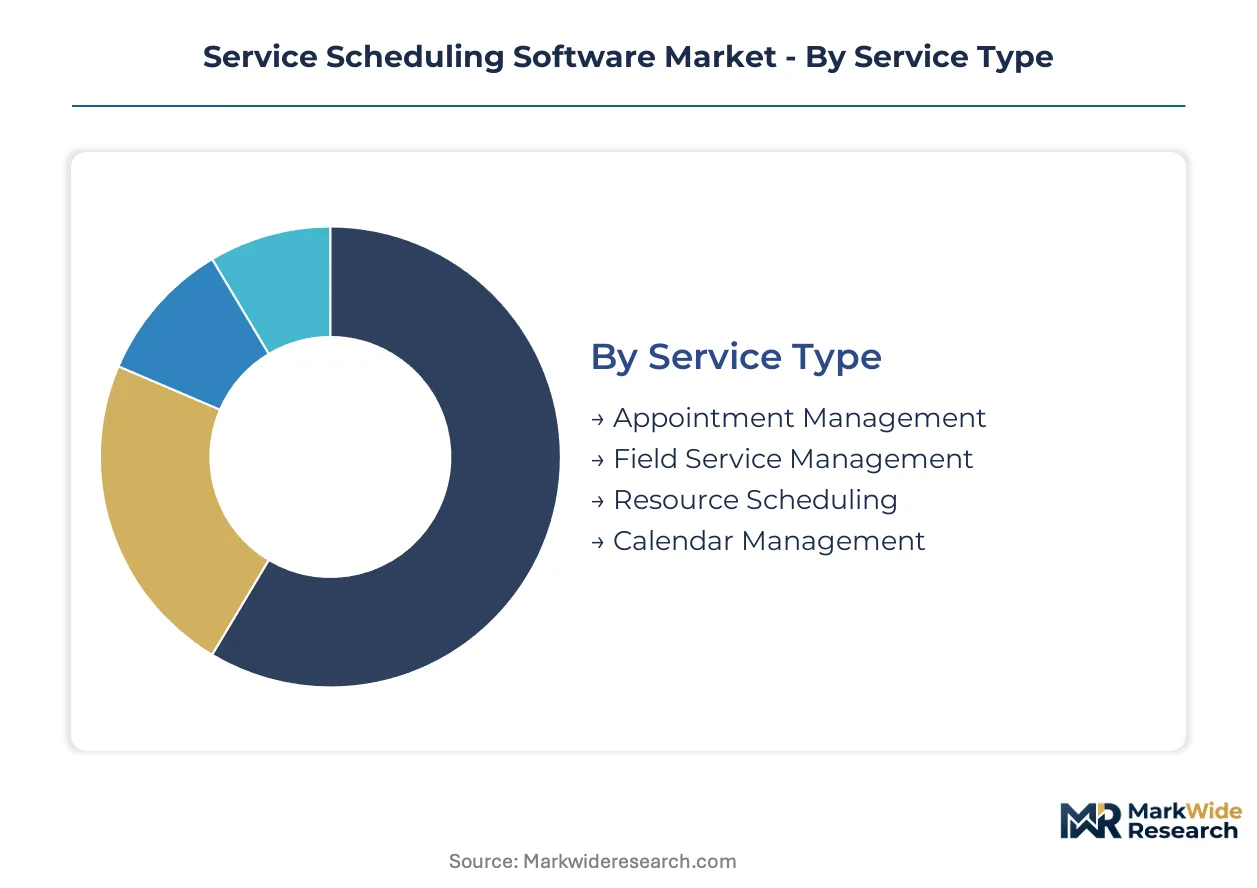
Service scheduling software segments diverge sharply on compliance burden and integration complexity. HIPAA mandates reshape healthcare deployments while FCC reliability standards govern telecommunications-integrated platforms. Procurement decisions hinge on which certification pathways each segment demands.
Service Type:
HIPAA compliance requirements concentrate heavily in appointment management and field service management segments, while resource scheduling and calendar management face lighter regulatory loads in most jurisdictions.
- Appointment Management:Patient booking workflows with encrypted API gateways and audit-ready logging satisfy HIPAA mandates for healthcare providers. Demand concentrates in United States hospital systems and specialty clinics where digital record-keeping is now mandatory. German facility management firms increasingly require explainable algorithms for automated scheduling under EU AI Act risk classifications.
- Field Service Management:Workforce dispatch platforms synchronize technician availability, GPS-enabled routing, and real-time job status updates through cloud infrastructure. HVAC contractors in Texas and Florida pilot predictive dispatch systems during peak summer seasons, compressing response windows to within-two-hour guarantees. FCC failover system guidelines push enterprise adoption toward redundant SaaS architectures over on-premises alternatives.
- Resource Scheduling:Equipment and facility allocation tools optimize utilization across shared assets and multi-location operations.
- Calendar Management:Cross-platform synchronization engines maintain real-time updates across Google, Microsoft, and proprietary systems.
Field Service Management sits at the top of the volume ranking, with Appointment Management climbing the fastest.
Deployment Model:
Cost tier stratification separates enterprise-grade on-premises installations from zero-maintenance SaaS consumption patterns among SMBs.
- On-Premises:Self-hosted installations on customer-controlled servers with full data sovereignty and customization flexibility. Manufacturing and utilities sectors in Germany and France demand localized record storage under GDPR data residency obligations, forcing redundant regional data center investments from vendors.
- Cloud-Based:Multi-tenant SaaS platforms deliver sub-second update latency through distributed edge infrastructure. Independent tradespeople in California and New York abandon annual contracts for month-to-month platforms with zero onboarding fees, pressuring vendors toward ratable revenue recognition.
- Hybrid:Split architectures maintaining sensitive data on-premises while leveraging cloud scalability for compute-intensive routing algorithms.
- SaaS:Pure subscription consumption with API-first integration layers compressing deployment cycles from months to weeks.
Cloud-Based commands the dominant share by customer count, with SaaS expanding most quickly among new entrants.
End User:
Application intensity varies by sector complexity, with healthcare and building maintenance demanding the deepest feature integration.
- Healthcare Providers:Patient appointment platforms with encrypted data flows and human-in-the-loop overrides for high-stakes dispatch decisions. HIPAA restrictions on third-party API data sharing filter black-box systems from vendor shortlists.
- Building Maintenance:Facility management scheduling synchronized with predictive maintenance systems and IoT-enabled asset tracking. German and French procurement teams now mandate algorithmic audit trails as standard criteria.
- Educational Institutions:Campus resource allocation and staff scheduling across distributed facilities with semester-driven demand spikes.
- Organizations:Cross-functional corporate scheduling spanning meeting rooms, travel coordination, and project timelines.
Healthcare Providers anchor premium pricing tiers, with Building Maintenance gaining share fastest through IoT convergence.
Pricing Model:
Customer maturity and scale determine preference between predictable recurring streams and variable usage-based structures.
- Subscription-Based:Fixed monthly or annual fees per seat with locked-in recurring revenue and lower upfront adoption barriers. Dominates vendor income by locking in predictable streams, though subscription fatigue among small contractors drives experimentation with alternatives.
- Pay-Per-Use:Variable billing scaled to active job volume rather than fixed seat counts. Pool maintenance, landscaping, and pest control segments in the United States favor this model for seasonal demand fluctuations.
- One-Time License:Perpetual software ownership with maintenance contracts, persisting in legacy ERP-integrated trades resistant to SaaS migration.
- Freemium:Zero-cost entry tiers with feature-gated upgrades, capturing solo tradespeople before scaling to paid modules.
Subscription-Based holds the revenue concentration, with Pay-Per-Use showing the steepest expansion trajectory among specialty trades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley software clusters anchor service scheduling innovation, with venture capital flows concentrating platform development in metropolitan technology corridors across multiple continents.
United States
HVAC contractor density and residential service trade penetration drive SaaS scheduling adoption across Texas and Florida markets. FCC telecommunications reliability guidelines mandate redundant failover architectures for cloud-hosted platforms serving enterprise accounts. Dallas-Fort Worth and Miami metropolitan areas pilot predictive dispatch systems during peak summer cooling demand, compressing technician response windows to under two hours.
Germany
Industrial facility management firms demand algorithmic audit trails for automated scheduling decisions under EU AI Act risk classifications. GDPR data residency obligations force vendors to maintain localized record storage in redundant regional data centers. Munich and Frankfurt procurement teams now exclude black-box systems from vendor shortlists, prioritizing explainable dispatch algorithms with human-in-the-loop overrides.
United Kingdom
Building maintenance sectors synchronize scheduling platforms with predictive maintenance systems and IoT-enabled asset tracking. CSRD sustainability reporting requirements extend into facility management software procurement criteria. London metropolitan contractors lead adoption of embedded financing tools integrated directly into dispatch platforms, capturing transaction revenue previously lost to third-party processors.
India
Urban technology hubs concentrate certified deployment specialists for field service management platforms, extending rollout timelines for rural contractor markets. BIS standards for software interoperability shape API-first architecture requirements for domestic vendors. Bangalore and Hyderabad software development centers engineer mobile-first scheduling applications targeting SMB tradespeople with month-to-month subscription preferences.
Japan
Manufacturing and utilities sectors require scheduling software that integrates with predictive maintenance systems, opening premium pricing tiers for IoT-enabled dispatch platforms. METI industrial digitalization initiatives subsidize cloud migration for established trades resistant to SaaS adoption. Osaka and Nagoya industrial corridors deploy hybrid architectures maintaining sensitive asset data on-premises while leveraging cloud scalability for routing algorithms.
Service Scheduling Software Market Competitive Landscape
Global majors compete with regional champions across integration depth and vertical specialization, producing a tiered structure where enterprise-grade asset management platforms sit above SMB-focused mobile-first applications. Consolidation pressures concentrate around API-first architectures that compress deployment cycles from months to weeks. Two strategic archetypes dominate: vertical specialists embedding native payment processing and financing tools, and horizontal platforms competing on cross-industry workflow flexibility. Dominant competitive moves include M&A activity targeting predictive maintenance capabilities and strategic partnerships with IoT sensor manufacturers.
Within the vertical specialist tier, ServiceTitan and Jobber occupy positions representing contrasting scale segments, with ServiceTitan anchoring enterprise contractor workflows and Jobber exemplifying intuitive mobile-first design for small-to-mid-sized trade businesses. SAP Field Service Management sits within the industrial-scale archetype, competing on manufacturing and utilities sector integrations. ServiceNow Field Service Management represents the IT service management convergence vector, extending platform capabilities beyond traditional field service boundaries.
| Leading Market Players |
|---|
| ServiceTitan |
| Jobber |
| Housecall Pro |
| Zendesk |
| ServiceNow Field Service Management |
| SAP Field Service Management |
| ServiceMax |
| Oracle Field Service Cloud |
| monday service |
| Others |
Pricing and Supply Chain Analysis
API-first integration patterns anchor both supply positioning and pricing power for service scheduling vendors, compressing deployment cycles from months to weeks while locking in recurring subscription streams. Cloud-native architectures draw from distributed edge infrastructure investments in the United States, Germany, and India, creating tiered cost structures that separate enterprise-grade platforms from zero-maintenance SaaS consumption.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and certified compliance specialists shapes vendor margin structures across deployment tiers. Subscription-based pricing dominates revenue recognition, with differentiation resting on HIPAA certification grade and API integration depth. Pricing pressure stems from subscription fatigue among independent tradespeople in California and New York, who favor month-to-month platforms with zero onboarding fees. Small-to-mid-sized contractors exhibit highest price sensitivity, while healthcare providers and industrial facility managers accept premium tiers for audit-ready logging and human-in-the-loop override capabilities.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Germany, and Japan, anchoring sub-second latency guarantees for field service dispatch platforms. Software development draws from Bangalore and Hyderabad engineering clusters, while compliance certification rests on HIPAA auditors in Dallas-Fort Worth and EU AI Act assessors in Munich. Single-source vulnerability runs through hyperscaler concentration for compute resources. Distribution runs through direct vendor sales teams for enterprise accounts and self-service digital channels for SMB adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
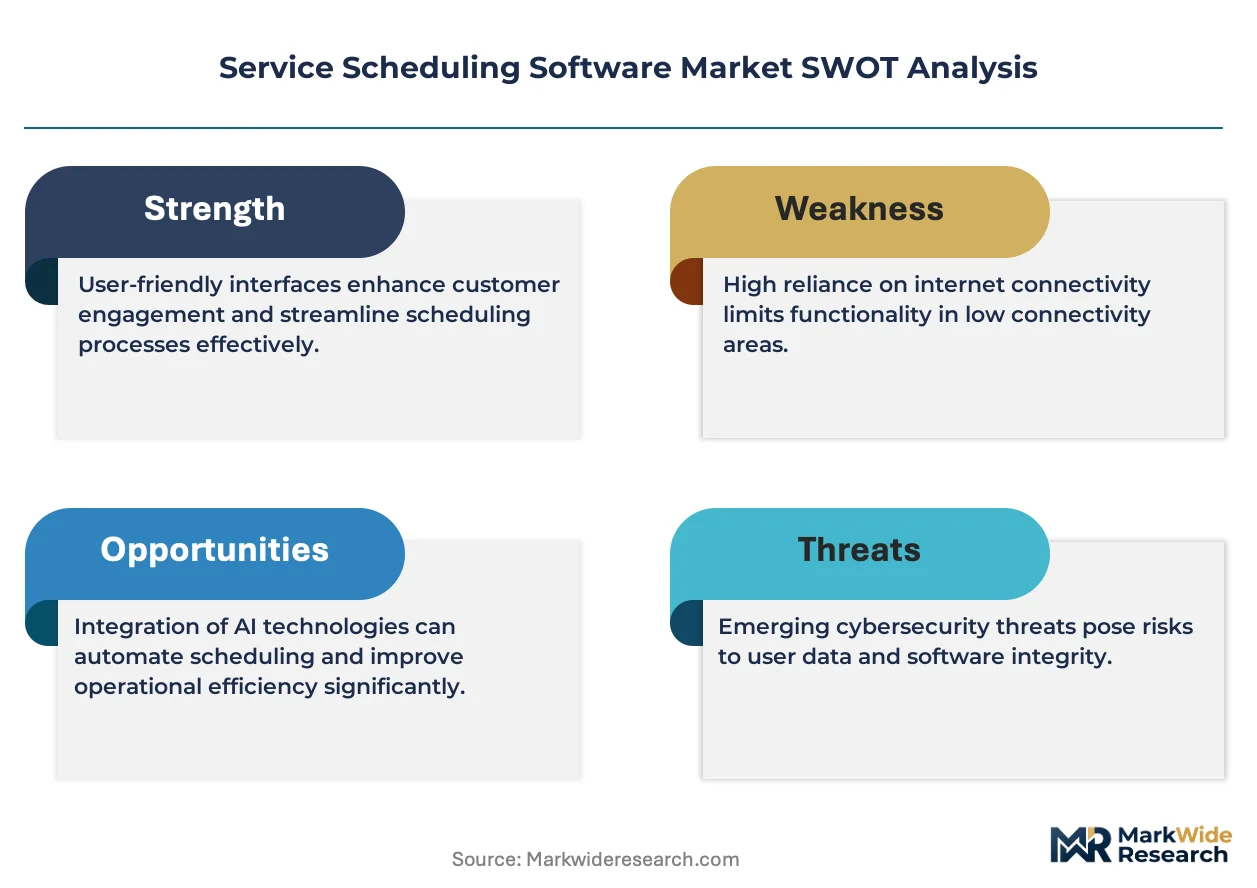
Service scheduling software functions as a geographic-arbitrage play between United States contractor density and European compliance premiums, where German facility management firms pay algorithmic audit trail premiums that Texas HVAC contractors reject.
For Market Incumbents: To counter subscription fatigue among small contractors, ServiceTitan and Jobber should unbundle implementation services from core platform fees, shifting revenue recognition to ratable patterns. Backward integration into native payment processing captures transaction revenue streams previously lost to third-party processors, deepening retention through embedded financing convergence. For New Entrants and Emerging Players: Launch via vertical-specific workflow modules targeting pool maintenance, landscaping, and pest control segments in the United States, where white space persists for purpose-built tools. Specialty trades favor pay-per-use models scaled to seasonal job volume, presenting the most penetrable entry point against incumbent seat-based pricing. For Investors and Strategic Acquirers: Roll-up economics work for predictive maintenance capability aggregators because industrial asset management expansion demands IoT-enabled dispatch platforms that synchronize with manufacturing systems. Target mid-sized platforms with API-first architectures and mobile-first design DNA. Watch technician onboarding complexity metrics as the inflection signal—vendors with compressed time-to-value curves outperform customer success cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures compress deployment cycles from months to weeks for enterprise accounts. |
| Acquisition of Specialist Firm | Predictive maintenance capabilities open premium pricing tiers in manufacturing and utilities sectors. |
| Strategic Partnership | IoT sensor manufacturer alliances enable real-time asset tracking for facility management clients. |
| Product Launch | Vertical-specific workflow modules capture underpenetrated pool and landscaping contractor segments. |
| Geographic Expansion | German and French procurement mandates for algorithmic audit trails create compliance-premium markets. |
Research Methodology
Bottom-up contractor deployment modeling reconciled against top-down cloud infrastructure tracking forms the analytical core of this study. Primary interviews with HVAC operations managers, healthcare IT procurement officers, facility management directors, and SaaS platform engineers combined with secondary validation from SEC filings, hyperscaler capex disclosures, and FCC reliability guidelines. Triangulation across these sources anchors volume estimates against actual seat deployment patterns.
Input-output matrices map technician job completion rates to platform pricing tiers across deployment model, organization size, vertical specialization, and regional adoption pattern segments. CAGRs derive from fitted growth curves applied to historical cloud migration velocity and API penetration trajectories. Forecast inputs include contractor density ratios by metropolitan statistical area and seasonal demand fluctuation patterns in Texas and Florida cooling markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid FCC regulatory shifts or EU AI Act enforcement accelerations. Outputs reflect documented assumptions around SMB SaaS abandonment rates and enterprise on-premises legacy persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Bug Tracking Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Relational Database Management System Market
Software & Services
Customs Declaration Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Codeless Testing Market
Software & Services
Service Dispatch Software Market
Software & Services
Software Testing Company Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Professional Service Automation Market
Software & Services
Website Translation Software Market
Software & Services
HACCP Software Market
Software & Services
HVAC Solution Software Market