
 Global Managed File Transfer (MFT) Software and Service Market | 2026-2036
Global Managed File Transfer (MFT) Software and Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed File Transfer (MFT) Software and Service Market Foresight
The EU AI Act is realigning enterprise procurement criteria for data movement infrastructure across European banking and financial services. Fortra leverages its consolidated cybersecurity portfolio to anchor hybrid deployment capabilities for regulated industries. Axway differentiates through API-augmented file transfer architectures that sustain long-term integration roadmaps for government agencies.
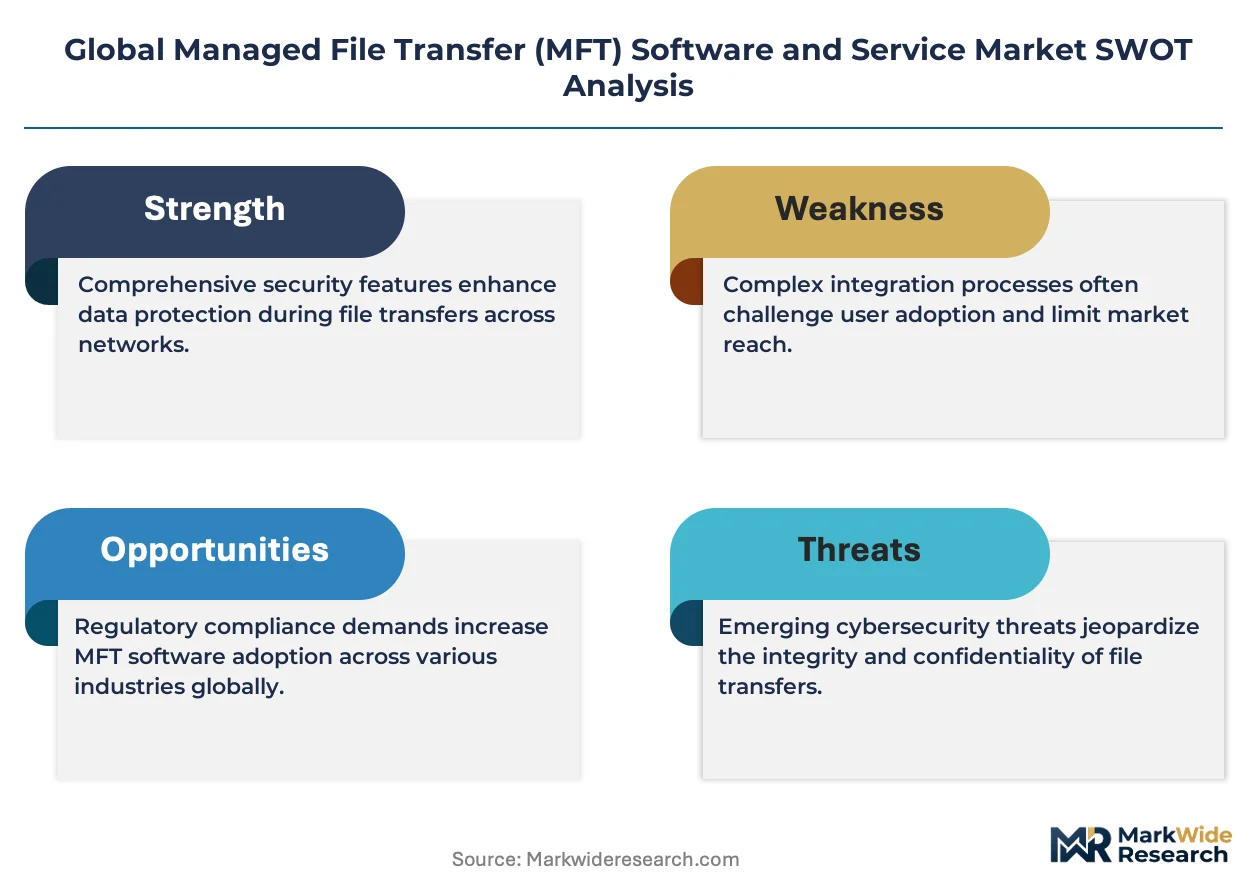
Managed File Transfer (MFT) Software and Service encompasses enterprise-grade platforms that encrypt, schedule, track, and audit file movements across heterogeneous networks using protocols such as SFTP, FTPS, and AS4 with end-to-end checksum verification. These systems serve primary commercial purposes in automated workflows and compliance reporting where data integrity and non-repudiation carry regulatory weight. Cloud-based deployment is capturing the fastest expansion as organizations exit capital-intensive on-premises maintenance, while support and maintenance services retain the deepest margin pools due to sticky enterprise contracts and certification dependencies. Banking and financial services dominates end-user demand given SWIFT messaging requirements and Basel III data retention mandates.
FDA 21 CFR Part 11 in the United States, EMA GxP guidelines in Europe, and Japan's METI data localization standards collectively shape product roadmaps by mandating immutable audit trails and geographic data residency. HIPAA and GDPR enforcement actions have elevated MFT from IT utility to board-level risk infrastructure. Stakeholders must monitor the divergence between EU AI Act algorithmic transparency rules and sector-specific data sovereignty laws as they calibrate platform investment and partnership strategies.
Market Dynamics
EU AI Act algorithmic transparency mandates are forcing banking and financial services firms to re-architect data movement infrastructure with immutable audit trails and geographic data residency controls.
Growth Catalysts
- GDPR enforcement actions:HIPAA and GDPR penalty regimes have elevated MFT from IT utility to board-level risk infrastructure, accelerating procurement cycles for auditable file transfer platforms.
- Cloud migration waves:Organizations exiting capital-intensive on-premises maintenance are driving fastest expansion in cloud-based MFT deployment models.
- SWIFT messaging requirements:Banking and financial services dominate end-user demand given cross-border transaction processing needs and Basel III data retention mandates.
Market Restraints
- Certification dependency costs:Support and maintenance services retain sticky enterprise contracts with deep margin pools, creating high switching costs for buyers.
- Technical protocol fragmentation:Heterogeneous network environments require simultaneous support for SFTP, FTPS, and AS4 protocols, complicating platform standardization.
- Substitution by API-first integration:API-augmented file transfer architectures present alternative integration pathways for government agencies with long-term roadmap requirements.
Strategic Opportunities
- Japan METI data localization:Japan's geographic data residency standards create demand for sovereign cloud MFT deployments with end-to-end checksum verification.
- EMA GxP guideline alignment:European pharmaceutical regulators mandate immutable audit trails, opening specialized compliance modules for life sciences file transfer.
- Hybrid deployment convergence:Integration of on-premises security controls with cloud scalability addresses regulated industries requiring workload portability.
Industry Challenges
- Legacy system integration friction:Enterprise workflows dependent on heterogeneous legacy infrastructure face complex migration paths to modern MFT platforms.
- Cross-border regulatory divergence:FDA 21 CFR Part 11, EMA GxP, and METI standards create conflicting compliance timelines for multinational deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed File Transfer (MFT) Software and Service Market |
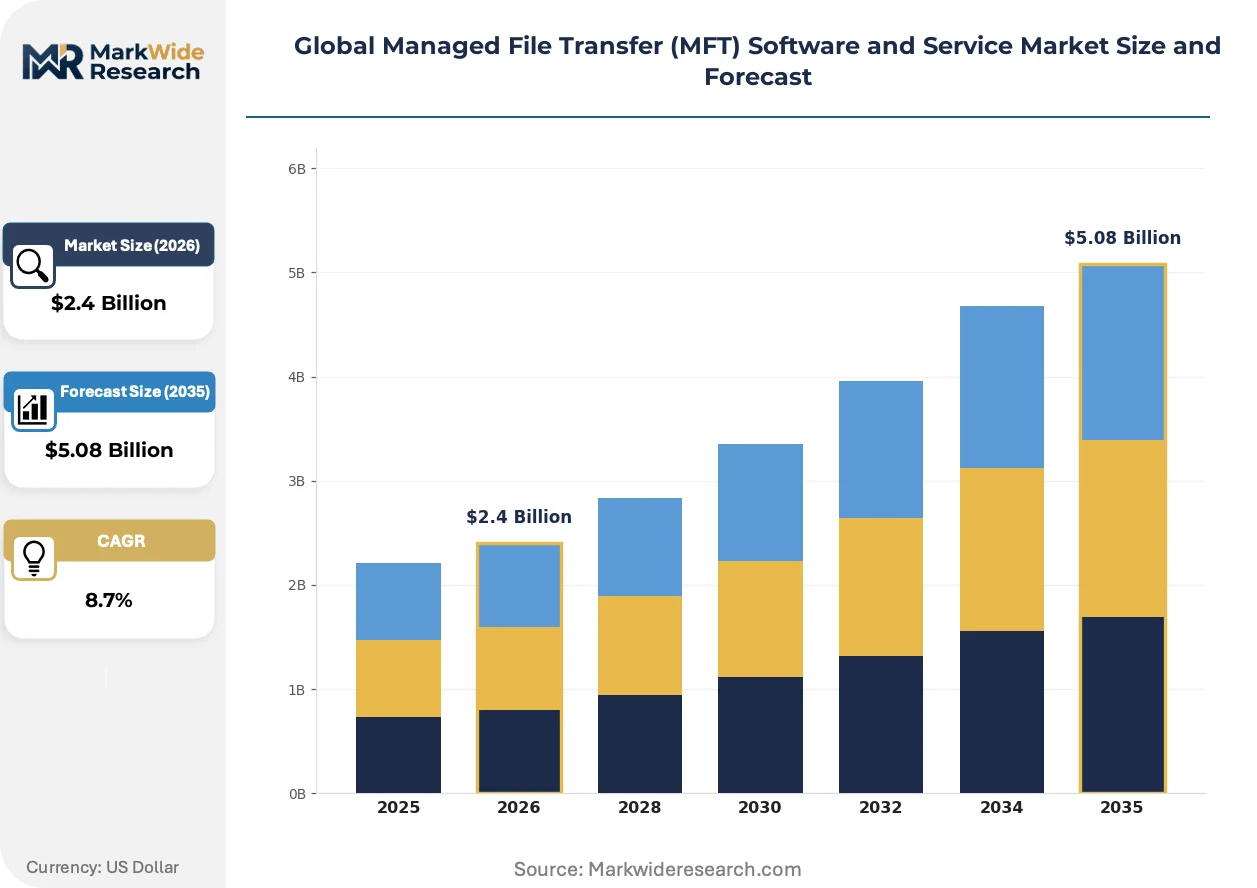
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Private Cloud, Public Cloud Service Type: Implementation, Consulting, Support & Maintenance, Training, Managed Services Application: Secure Data Transfer, Compliance Reporting, Automated Workflows, Data Integration, Business Process Automation End User Industry: Banking & Financial Services, Government Agencies, Telecommunications, Information Technology Firms, Logistics Providers |
| Companies Covered | Fortra, Axway, GoAnywhere MFT, IBM Aspera, Coviant Software, JSCAPE, Cerberus FTP Server, Files.com, Kiteworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed File Transfer (MFT) Software and Service Market Shifts & Advancements
Active transformation in enterprise data movement centers on protocol modernization, regulatory algorithmic governance, and procurement model restructuring away from perpetual licenses.
Zero-trust architecture integration is rewriting how MFT platforms authenticate file movements. Financial services institutions in Germany and the United States are adopting continuous verification models at accelerated procurement cycles. This technology is compressing the attack surface for cross-border transaction infrastructure while raising baseline security spend.
EU AI Act algorithmic transparency rules are mandating explainable audit trails for automated file routing decisions. Industrial consequence includes mandatory documentation of decision logic in machine learning-based transfer optimization. Banking sectors across France, Germany, and the Netherlands are responding with dedicated compliance modules that capture model training data lineage.
Consumption-based pricing models are displacing traditional perpetual license structures in enterprise MFT procurement. System integrators and managed security service providers are capturing buyer preference with bundled transfer capacity and support tiers. This shift is most visible in United States healthcare and financial services verticals where capital expenditure constraints favor operational expenditure treatment.
Global Managed File Transfer (MFT) Software and Service Market Segmentation
MFT procurement patterns diverge sharply across deployment architectures, service tiers, and compliance intensity. Buyers calibrate platform selection against data sovereignty mandates, legacy infrastructure debt, and sector-specific audit requirements.
Deployment:
Standardization decreases from fully managed cloud to self-hosted on-premises environments across this spectrum.
- Cloud-Based:Multi-tenant platforms with elastic compute allocation eliminate capital expenditure for data movement infrastructure. Healthcare providers in the United States and Germany are migrating here fastest as HIPAA and GDPR enforcement actions compress procurement cycles for auditable transfer platforms.
- Hybrid:Workload portability between on-premises security controls and cloud scalability addresses regulated industries with mixed compliance timelines. Banking and financial services firms in Japan leverage hybrid deployments to satisfy METI data localization standards while maintaining cross-border transaction connectivity.
- On-Premises:Self-managed infrastructure with dedicated hardware stacks persists in defense and classified government workflows.
- Private Cloud:Single-tenant dedicated environments with sovereign data residency controls serve European pharmaceutical manufacturers under EMA GxP guidelines.
- Public Cloud:Shared infrastructure with consumption-based metering attracts mid-market information technology firms seeking operational expenditure treatment.
Most installed capacity flows through On-Premises legacy estates. Expansion is steepest in Cloud-Based configurations.
Service Type:
Margin depth inversely correlates with standardization across this service hierarchy.
- Support & Maintenance:Sticky enterprise contracts with certification dependencies generate recurring revenue through security patch management, protocol updates, and compliance attestation documentation. Banking and financial services institutions in France and the Netherlands prioritize these tiers for EU AI Act algorithmic transparency readiness.
- Managed Services:Fully outsourced transfer operations with SLA-backed availability commitments reduce internal security operations center burden. United States healthcare systems adopt managed services to address FDA 21 CFR Part 11 audit trail requirements without expanding dedicated MFT engineering teams.
- Implementation:Platform deployment and legacy system integration services with customized workflow configuration.
- Consulting:Architecture assessment and regulatory alignment advisory for multinational data residency strategies.
- Training:Administrator certification and end-user security awareness programs for enterprise adoption.
Revenue concentrates in Support & Maintenance renewals. Managed Services is climbing the fastest as outsourcing preference hardens.
Application:
Regulatory weight escalates from internal automation to externally auditable compliance functions.
- Compliance Reporting:Immutable audit trail generation with non-repudiation documentation for regulatory examination. European banking sectors deploy specialized modules capturing model training data lineage under EU AI Act algorithmic transparency mandates.
- Secure Data Transfer:End-to-end encrypted file movement with checksum verification across heterogeneous network protocols. Logistics providers in Germany and Japan prioritize this application for cross-border shipment documentation integrity.
- Automated Workflows:Scheduled transfer orchestration with exception handling and retry logic for operational efficiency.
- Data Integration:Protocol bridging between ERP, CRM, and data warehouse systems with format transformation.
- Business Process Automation:File-triggered workflow initiation across supply chain and procurement operations.
Deployment volume skews toward Secure Data Transfer. Compliance Reporting is gaining share fastest as penalty regimes intensify.
End User Industry:
Procurement sophistication and security budget scale vary dramatically across these verticals.
- Banking & Financial Services:SWIFT messaging infrastructure with Basel III data retention mandates drives highest platform investment intensity. Institutions across the United States, Germany, and Japan anchor demand for zero-trust authentication and geographic data residency controls.
- Government Agencies:Classified and unclassified network separation with FedRAMP or equivalent certification requirements. French and Dutch agencies adopt API-augmented architectures for long-term integration roadmap sustainability.
- Telecommunications:Subscriber data portability and inter-carrier billing file exchange with high-volume throughput requirements.
- Information Technology Firms:Internal DevOps pipeline automation and customer data migration services with consumption-based pricing preference.
- Logistics Providers:Customs documentation and shipment tracking data exchange with trading partner ecosystem connectivity.
Revenue generation centers on Banking & Financial Services. Government Agencies are expanding most quickly as digital sovereignty agendas accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFT infrastructure originated in US financial technology hubs during the 1990s SWIFT standardization era, then diffused to European banking centers under Basel II pressure. Geographic expansion now tracks regulatory enforcement intensity rather than pure IT modernization cycles.
United States
FDA 21 CFR Part 11 and HIPAA penalty regimes drive pharmaceutical and healthcare procurement of immutable audit trail systems. The SEC's cybersecurity disclosure rules are compressing upgrade timelines for listed financial institutions. Boston's health-tech cluster and New York's fintech corridor anchor domestic platform deployment density.
Germany
BaFin's operational resilience requirements and the EU AI Act's algorithmic transparency mandates force banking infrastructure re-architecture. Industrial manufacturers in the Ruhr region adopt MFT for supply chain documentation integrity under REACH chemical tracking obligations. Frankfurt's financial services density sustains premium-tier solution demand.
Japan
METI data localization standards compel sovereign cloud deployments for cross-border transaction processing. The FSA's enhanced cybersecurity framework for financial institutions elevates zero-trust authentication requirements. Tokyo's banking headquarters and Osaka's manufacturing networks concentrate hybrid deployment adoption.
United Kingdom
FCA operational resilience deadlines and post-Brexit data adequacy negotiations drive financial services procurement. The NHS's patient data sharing mandates accelerate healthcare sector migration to auditable transfer platforms. London's fintech ecosystem and Manchester's public sector digitalization sustain implementation service demand.
France
CNIL GDPR enforcement actions and ANSM pharmaceutical traceability requirements shape procurement criteria. The country's nuclear and defense industrial base maintains on-premises deployment preference for classified workflows. Paris-Saclay's research institutions and Lyon-Basel pharmaceutical corridor drive specialized compliance module adoption.
Global Managed File Transfer (MFT) Software and Service Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light SaaS specialists across deployment architecture segments. Market structure tilts toward consolidation at the enterprise tier while fragmenting among mid-market cloud-native entrants. Three archetypes dominate: cybersecurity-anchored platform consolidators, API-centric integration specialists, and protocol-focused pure-plays. M&A activity concentrates on zero-trust capability acquisition and geographic data residency expansion.
Within the cybersecurity-anchored tier, Fortra occupies a position exemplifying portfolio consolidation strategy across adjacent data protection domains. Axway represents the API-augmented architecture approach that government agencies favor for long-term integration sustainability. Among protocol-focused specialists, JSCAPE and Cerberus FTP Server sit within the deployment-flexibility archetype serving heterogeneous legacy infrastructure environments.
| Leading Market Players |
|---|
| Fortra |
| Axway |
| GoAnywhere MFT |
| IBM Aspera |
| Coviant Software |
| JSCAPE |
| Cerberus FTP Server |
| Files.com |
| Kiteworks |
| Others |
Supply & Pricing Matrix
Banking and financial services procurement concentration in Germany, the United States, and Japan anchors subscription-based SaaS pricing as the dominant commercial model for MFT platforms. This buyer archetype's preference for consumption-based operational expenditure treatment compresses perpetual license viability while elevating recurring revenue structures.
Pricing Analysis
Consumption-based subscription tiers with elastic transfer capacity metering dominate enterprise MFT procurement, displacing perpetual licenses across United States healthcare and financial services verticals. Price differentiation rests on certification grade—FedRAMP, ISO 27001, and SOC 2 tiers command substantial premiums—and deployment complexity spanning hybrid to fully managed cloud configurations. Pricing pressure stems from API-first integration alternatives that commoditize basic file transfer functionality. Mid-market information technology firms exhibit highest price sensitivity, while banking institutions under Basel III mandates demonstrate lowest elasticity due to non-negotiable audit trail requirements.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor MFT platform delivery through hub-and-spoke patterns serving sovereign cloud deployments. Software development draws from concentrated engineering talent pools in North America and Western Europe, with customer success operations sourcing from technical certification programs in India and Eastern Europe. Single-source vulnerability in specialized cryptographic module suppliers presents structural risk under export control restrictions. Distribution runs through direct enterprise sales organizations supplemented by systems integrator and managed security service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Managed File Transfer Software and Service Market functions as a stable compounder, with regulatory enforcement intensity across GDPR, EU AI Act, and HIPAA providing durable demand tailwinds irrespective of macroeconomic cycles.
For Market Incumbents: To counter API-first integration substitution, Fortra and Axway should deepen zero-trust capability acquisition and expand geographic data residency certifications across METI-aligned Japanese deployments. Certification investment in EU AI Act algorithmic transparency modules represents the critical defensive lever for European banking retention. For New Entrants and Emerging Players: Launch via consumption-based SaaS models targeting mid-market United States healthcare systems seeking HIPAA-compliant transfer platforms without dedicated MFT engineering overhead. White-space concentration sits in pharmaceutical compliance reporting modules for EMA GxP-aligned European manufacturers, with channel partnerships through life sciences systems integrators as the optimal go-to-market angle. For Investors and Strategic Acquirers: Cybersecurity platform consolidators represent the most active acquirer category in this space, seeking protocol-focused specialists with deployment-flexibility architectures. Long-term viability centers on sticky support and maintenance revenue pools with certification dependency moats. Watch for divergence between EU AI Act enforcement timelines and sector-specific data sovereignty laws as the inflection signal for platform investment recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Integration | Continuous verification models at German financial institutions compress attack surfaces for cross-border infrastructure. |
| EU AI Act Compliance Module Development | Explainable audit trail capture for automated routing decisions addresses French and Dutch banking procurement criteria. |
| Sovereign Cloud Partnership Expansion | METI-aligned deployments in Japan satisfy data localization while maintaining transaction connectivity. |
| API-Augmented Platform Convergence | Long-term integration sustainability attracts government agency buyers in France and the Netherlands. |
| Managed Services Capacity Buildout | SLA-backed availability commitments reduce internal security operations burden for United States healthcare systems. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with chief information security officers, IT procurement directors, platform integration specialists, and managed security service provider executives combined with secondary validation from SEC filings, hyperscaler capex disclosures, and regulatory enforcement databases. Triangulation across these sources ensures segmentation integrity across deployment architecture, service tier, and end-user industry dimensions.
Historical trendline analysis of MFT procurement cycles under HIPAA, GDPR, and Basel III enforcement waves established baseline growth parameters across the projection horizon. The analytical framework models deployment model, organization size, vertical compliance intensity, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs derive from regression-weighted scenario outputs incorporating SWIFT messaging volume trajectories and cloud migration velocity indices as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged capital expenditure constraints in United States healthcare. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Calorie Metering Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Acoustic Simulation Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Expense Management Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Push Notifications Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Global OKR Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Creative Software Market