
 Construction Estimating Software Market | 2026-2036
Construction Estimating Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Estimating Software Market Intelligence
A capital-intensity divergence between well-funded platform providers and lean point-solution vendors is rotating competitive dynamics toward integrated suites. Autodesk Inc. leverages its design-to-construction workflow continuity to anchor premium positioning among enterprise general contractors. Trimble Inc. sustains field-hardware connectivity advantages that differentiate its estimating modules for civil and infrastructure verticals. Procore Technologies, Inc. competes through cloud-native architecture that extends collaboration layers beyond estimation into project execution.
Construction estimating software automates quantity takeoff, cost aggregation, and bid compilation through rule-based engines and integrated material databases, typically processing unit-price and lump-sum calculations against regional cost indices. Cloud-based Solutions now dominate new deployments as general contractors prioritize real-time collaboration and remote access across distributed project teams, while On-premises Software retains share among defense and critical infrastructure clients with stringent data sovereignty requirements. Bid Management features command premium pricing due to workflow complexity and stakeholder coordination demands, whereas Reporting Tools function as commoditized table-stakes modules.
The US Department of Commerce infrastructure standards, EU Green Deal building performance benchmarks, and China's GB standards for construction informatization collectively elevate compliance requirements that software vendors must embed. OSHA and EPA reporting integration in North America shapes feature roadmaps, while REACH and CSRD disclosure obligations in Europe drive carbon-cost estimation module development. Stakeholders must monitor how BIM mandate expansion and embodied-carbon accounting standards will redefine the boundary between estimating software and broader construction management platforms.
Market Dynamics
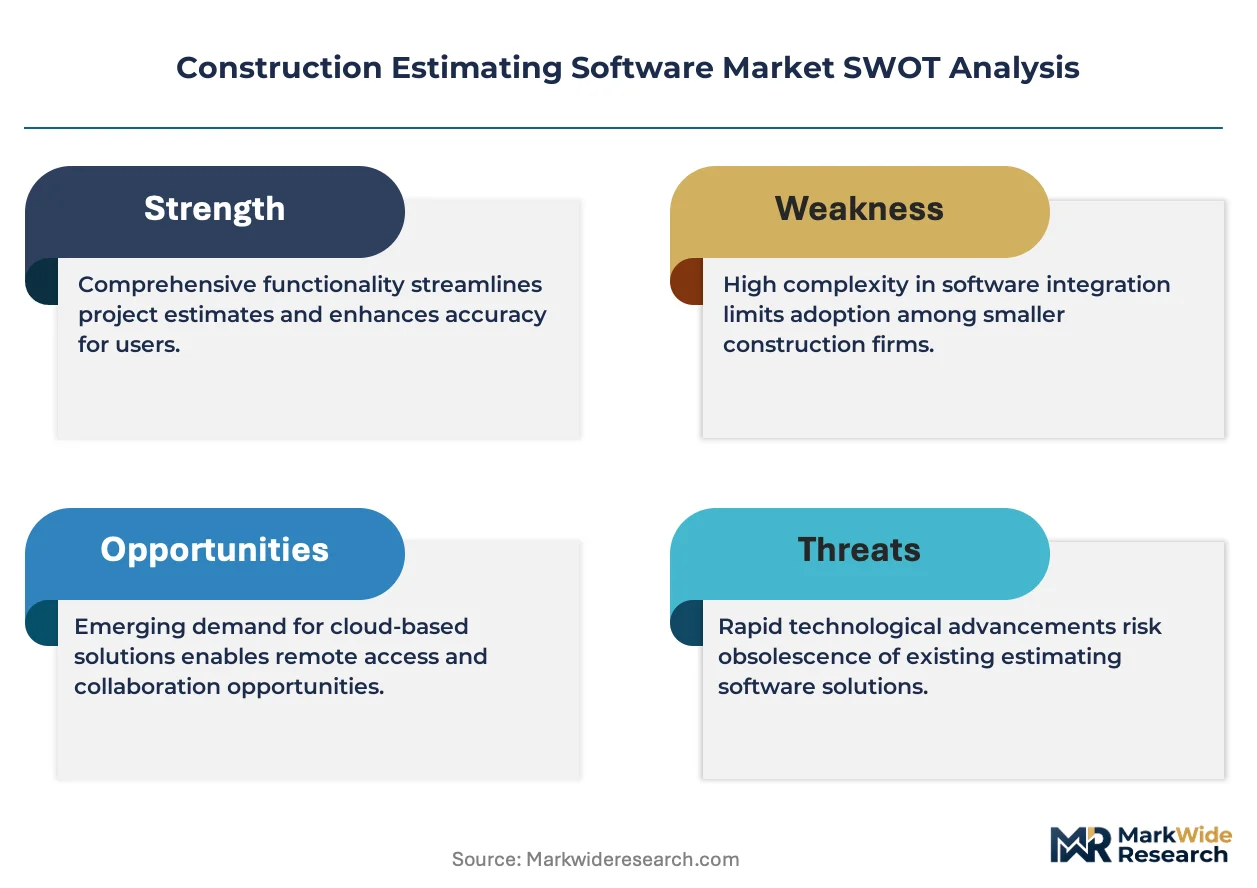
Cloud migration and BIM interoperability mandates are compressing renewal cycles as contractors replace legacy desktop tools with connected platforms that integrate quantity takeoff, cost databases, and bid management into unified workflows.
Growth Catalysts
- OSHA and EPA Reporting Integration:North American contractors face escalating compliance documentation requirements that automated estimation platforms streamline through embedded regulatory templates and audit trails.
- Green Building Mandates:Embodied-carbon accounting modules are becoming procurement prerequisites as LEED certification and EU Green Deal performance benchmarks reshape material selection protocols.
- Civil Infrastructure Modernization:Transportation and utility verticals in the United States are driving specialized estimating tool adoption for heavy-construction cost forecasting and risk-adjusted bidding.
Market Restraints
- Data Sovereignty Requirements:Defense and critical infrastructure clients in the United States enforce on-premises deployment mandates that constrain cloud-native vendor addressable markets.
- Legacy System Integration Friction:Decades-old ERP and accounting platforms in established construction firms resist API connectivity, prolonging implementation timelines and elevating professional services costs.
- Specialized Talent Scarcity:Shortages of estimators proficient in both construction methodology and software configuration limit deployment velocity for mid-market contractors.
Strategic Opportunities
- Small Contractor Digitization:Residential and specialty trade contractors in India represent an underpenetrated segment where mobile-first estimating applications can displace spreadsheet-based bidding.
- Digital Twin Convergence:Integration between estimating engines and real-time project telemetry creates predictive cost variance alerts that differentiate premium platform positioning.
- Carbon-Cost Module Development:REACH and CSRD disclosure obligations in Europe are accelerating procurement of embodied-carbon estimation capabilities that vendors can productize across jurisdictions.
Industry Challenges
- Cross-Platform Data Standardization:Inconsistent BIM file formats and proprietary cost database schemas force vendors to maintain expensive mapping layers that degrade interoperability.
- Estimator Workforce Transition:Veteran professionals accustomed to manual quantity takeoff methods resist workflow automation, necessitating change-management investments that compress implementation margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Estimating Software Market |
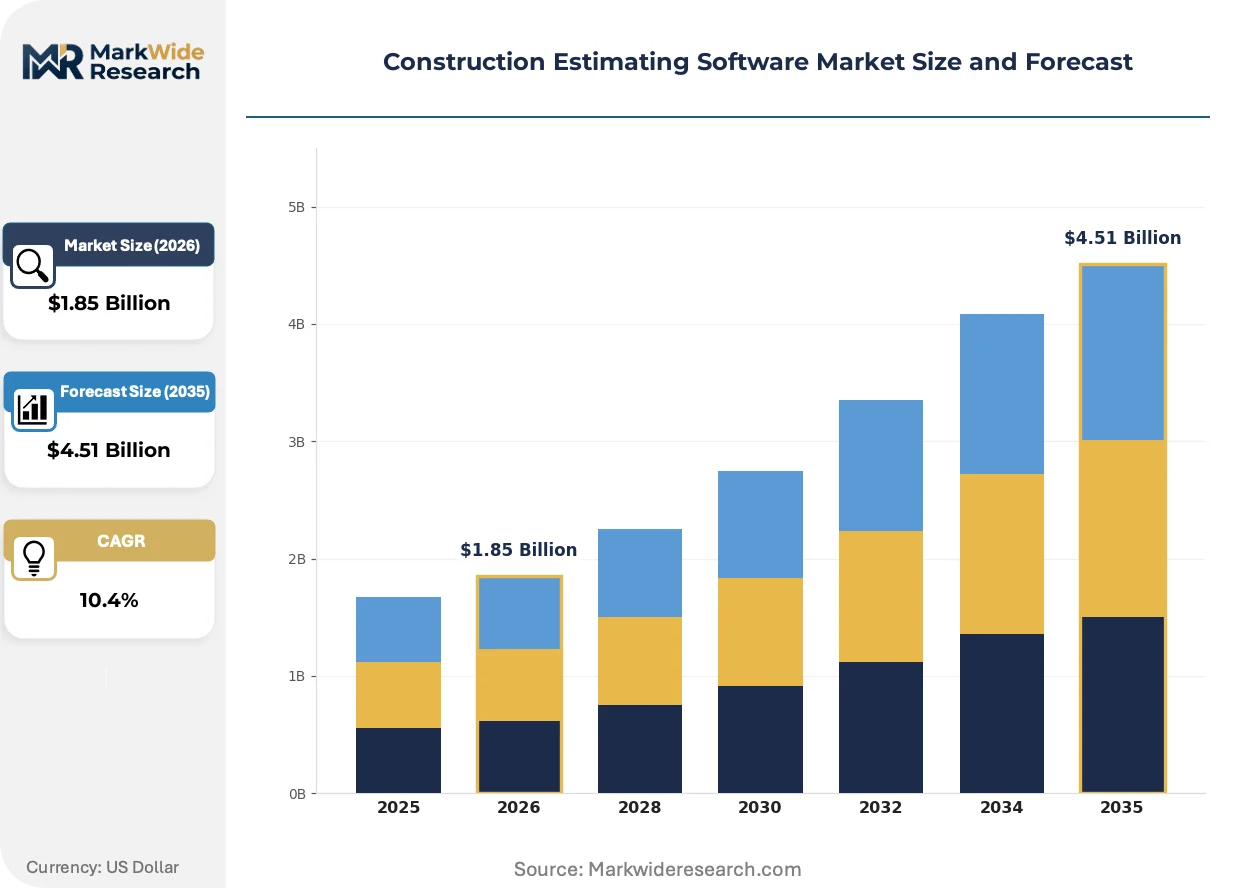
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premises Software, Desktop Applications, Mobile Applications End User: General Contractors, Subcontractors, Estimators, Engineers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Feature: Cost Database Integration, Bid Management, Reporting Tools, Project Tracking |
| Companies Covered | Autodesk Inc., Trimble Inc., Procore Technologies, Inc., Oracle Corporation, RIB Software SE, Sage Group plc, Bluebeam Software Inc., STACK Construction Technologies, Glodon Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Estimating Software Market Strategic Shifts & Innovations
Artificial intelligence and machine learning architectures are embedding predictive capabilities directly into estimation engines, shifting competitive advantage from static cost libraries toward dynamic risk modeling and automated bid optimization.
Generative AI is supplanting rule-based quantity takeoff engines by parsing unstructured construction documents and extracting material specifications without manual blueprint markup. Mid-sized general contractors in the United States are piloting these tools for preliminary estimates, compressing bid preparation timelines from weeks to days while reducing estimator headcount requirements.
EU Green Deal building performance benchmarks and CSRD corporate sustainability disclosure rules are mandating embodied-carbon calculations as standard estimate outputs. Software vendors must now integrate lifecycle assessment databases and regional emission factors or face exclusion from public procurement frameworks in Germany, France, and the Netherlands.
Subscription pricing models are displacing perpetual license structures as dominant commercial terms, particularly among cloud-native platforms targeting distributed project teams. This shift compresses upfront customer acquisition costs while extending lifetime value capture, though it pressures cash flow management for vendors transitioning from license-heavy revenue recognition.
Construction Estimating Software Market Segmentation
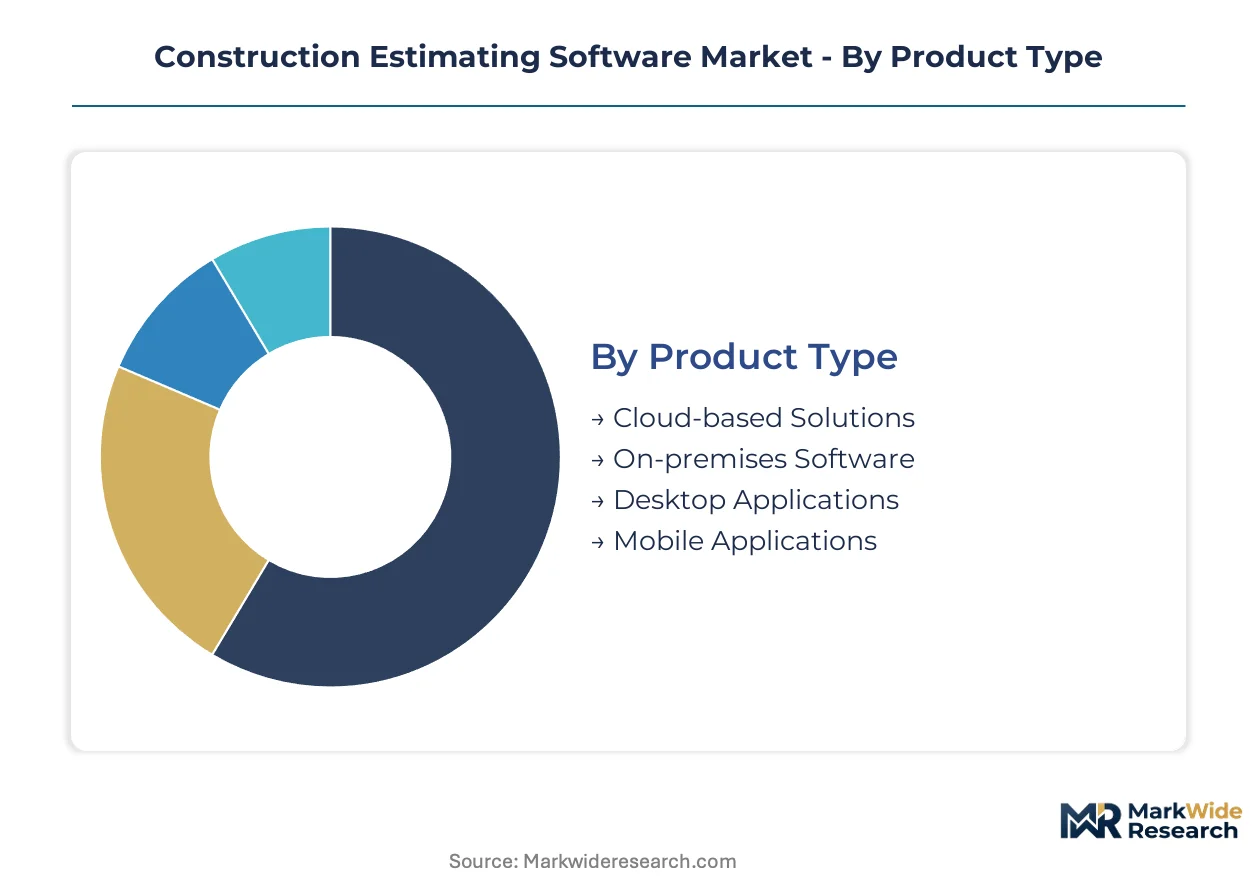
Segmentation reveals how substitution pressures reshape procurement across the construction estimating software landscape. Cloud-native architectures displace legacy desktop installations while mobile-first tools encroach on traditional estimator workflows.
Product Type:
Cloud-based Solutions face the most intense substitution pressure as on-premises vendors retrofit web connectivity and mobile applications absorb lightweight estimation tasks.
- Cloud-based Solutions:Multi-tenant SaaS architectures enable real-time collaboration across distributed project teams with automatic cost database updates. General contractors in the United States prioritize these platforms for bid coordination with remote estimators and subcontractor portals.
- On-premises Software:Single-tenant deployments maintain data sovereignty for defense infrastructure and classified government projects requiring air-gapped environments. Stringent security protocols in critical infrastructure verticals sustain demand despite higher total cost of ownership.
- Desktop Applications:Perpetual-license tools persist among small residential contractors with limited IT infrastructure and intermittent internet connectivity.
- Mobile Applications:Smartphone-native estimation tools serve field supervisors performing rapid preliminary takeoffs and change order pricing.
Cloud-based Solutions retain volume leadership; Mobile Applications hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade platforms serving general contractors from point solutions targeting specialty trades with narrower functional requirements.
- General Contractors:Full-suite platforms integrating quantity takeoff, cost aggregation, and bid management across multiple project types. These users demand BIM interoperability and ERP connectivity for consolidated financial reporting.
- Subcontractors:Trade-specific estimation tools for mechanical, electrical, and concrete specialists requiring material databases calibrated to regional supplier pricing.
- Estimators:Dedicated professionals seeking advanced risk-adjusted bidding algorithms and scenario modeling for competitive tender preparation.
- Engineers:Design-phase cost consultants needing preliminary budget validation linked to schematic design iterations.
General Contractors command the largest addressable spend; Subcontractors are climbing the fastest as digitization penetrates specialty trades.
Deployment Model:
Application criticality determines whether contractors prioritize scalability, control, or compromise architectures balancing both objectives.
- Public Cloud:Shared infrastructure delivering elastic compute for peak bidding periods without capital expenditure. Mid-market contractors favor this model for rapid deployment and zero maintenance overhead.
- Private Cloud:Dedicated tenant environments isolating sensitive project data while retaining remote accessibility. Large infrastructure firms deploy these for transportation and utility projects with proprietary cost methodologies.
- Hybrid Cloud:Split architectures keeping core estimation engines on-premises while extending collaboration layers to public cloud endpoints.
- On-premises:Fully captive infrastructure satisfying data residency mandates in defense and nuclear construction sectors.
Public Cloud captures the broadest user base; Private Cloud gains share fastest among security-conscious infrastructure verticals.
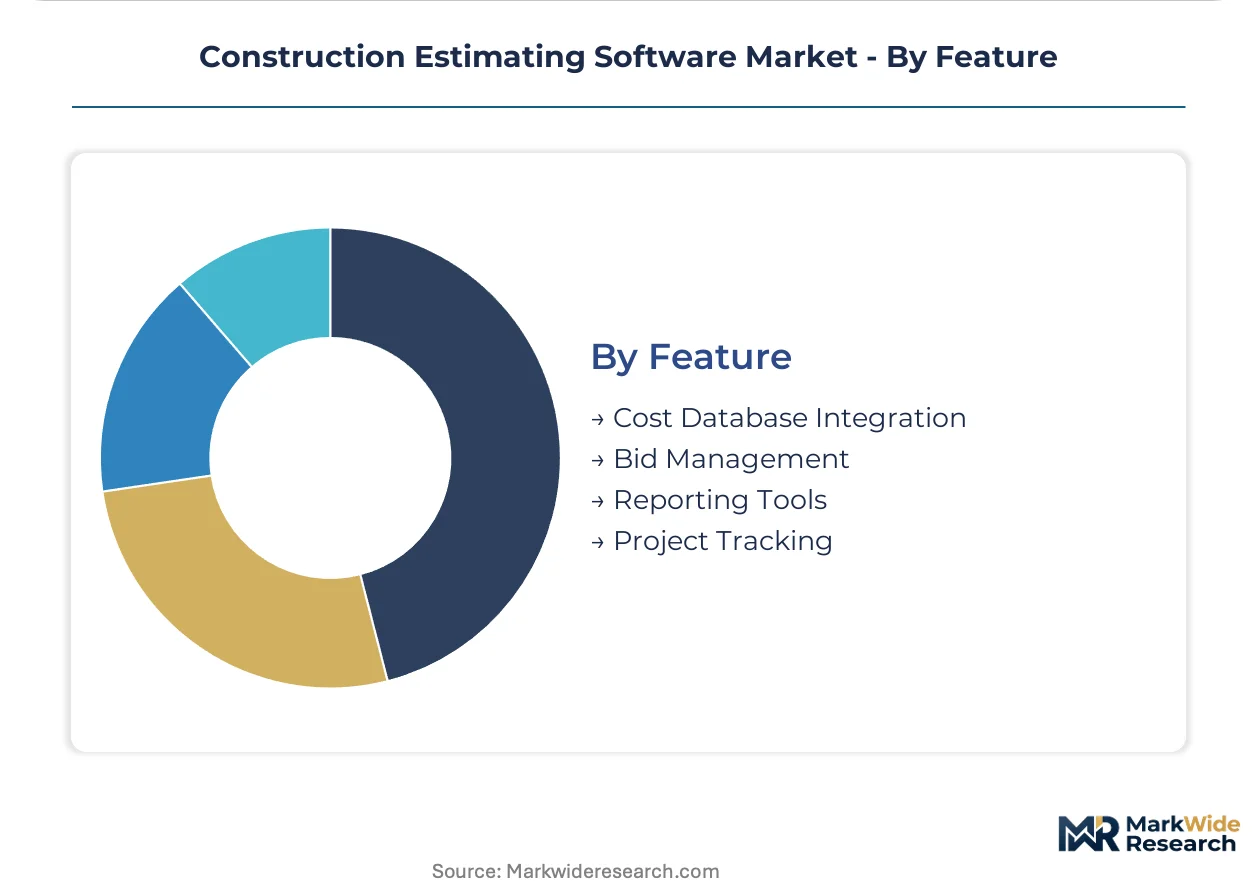
Feature:
Margin concentration clusters around workflow-complexity modules while commoditized reporting functions face pricing compression from bundled alternatives.
- Cost Database Integration:Regional material and labor indices updated through publisher partnerships or crowdsourced contractor submissions. Accuracy of localized pricing distinguishes premium platforms from generic alternatives.
- Bid Management:Multi-stakeholder coordination tools automating subcontractor outreach, quote comparison, and proposal assembly. These modules command premium pricing due to workflow complexity and time savings.
- Reporting Tools:Standardized output generation for client presentations and internal variance analysis increasingly bundled as table-stakes functionality.
- Project Tracking:Post-award cost monitoring bridging estimation with field execution through budget-to-actual comparisons.
Cost Database Integration anchors platform value; Bid Management shows the steepest expansion trajectory as competitive pressure intensifies tender sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia demonstrate acute price sensitivity toward construction estimating software, while United States and German contractors prioritize BIM interoperability and compliance depth over licensing costs.
United States
Transportation and utility infrastructure modernization drives specialized estimating tool procurement among heavy-construction firms. OSHA and EPA reporting integration requirements compress vendor qualification timelines. Dallas-Fort Worth and Houston metropolitan clusters concentrate demand from energy sector contractors deploying risk-adjusted bidding platforms.
Germany
EU Green Deal building performance benchmarks mandate embodied-carbon calculation modules in public procurement frameworks. REACH compliance documentation obligations shape feature roadmaps for construction software vendors. Munich and Stuttgart industrial corridors anchor adoption among precision engineering contractors serving automotive factory construction.
China
GB standards for construction informatization accelerate domestic software substitution in state-funded infrastructure projects. Dual carbon goals elevate carbon-cost estimation requirements in municipal tender specifications. Yangtze River Delta megacity clusters concentrate demand from state-owned construction enterprises modernizing cost forecasting systems.
India
Residential and specialty trade contractors in Tier-2 cities represent underpenetrated demand for mobile-first estimating applications displacing spreadsheet workflows. BIS certification requirements for construction software gain traction in government building projects. Bengaluru and Hyderabad technology corridors incubate domestic SaaS vendors targeting mid-market general contractors.
United Arab Emirates
Mega-project developments in NEOM and Red Sea tourism infrastructure drive premium platform adoption among international joint-venture contractors. MOHAP building safety regulations intersect with construction documentation standards. Dubai construction clusters prioritize cloud-native estimating tools enabling real-time collaboration across multinational project teams.
Construction Estimating Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the construction estimating software landscape. The market exhibits tiered consolidation with dominant design-to-construction workflow platforms anchoring enterprise segments while point-solution vendors compete on trade-specific functionality. Two strategic archetypes define competitive positioning: integrated suite providers leveraging design software continuity, and field-hardware connectivity specialists serving civil infrastructure verticals. M&A activity concentrates on cloud-native architecture acquisitions and regional cost database expansions.
Within the integrated workflow tier, Autodesk Inc. and Trimble Inc. exemplify divergent technology anchoring strategies, with the former representing design-origin platform extension and the latter embodying field-data capture integration. Procore Technologies, Inc. occupies a position among cloud-native challengers extending collaboration layers beyond estimation into project execution. These three companies collectively illustrate how vendor origin—design software, field hardware, or SaaS-native architecture—determines competitive differentiation vectors in procurement decisions.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Trimble Inc. |
| Procore Technologies, Inc. |
| Oracle Corporation |
| RIB Software SE |
| Sage Group plc |
| Bluebeam Software Inc. |
| STACK Construction Technologies |
| Glodon Company Limited |
| Others |
Cost & Logistics Intelligence
Ninety-day implementation timelines for enterprise estimating platforms compress vendor cash conversion cycles while amplifying pricing power for those with proven BIM interoperability. Cloud-native providers capture recurring revenue streams that offset upfront professional services costs, whereas on-premises vendors face margin erosion from extended deployment schedules. Procurement officers at mid-market general contractors now weight total cost of ownership against speed-to-bid metrics.
Pricing Analysis
Professional services and extended implementation contracts drive lifetime value for construction estimating software vendors. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and cost database granularity. Price differentiation hinges on BIM certification tier and regional cost index accuracy. Cost compression in the mid-market tier is intensifying because mobile-first challengers displace spreadsheet workflows with freemium entry points. Residential contractors in India exhibit acute price sensitivity, while United States infrastructure firms prioritize compliance depth over licensing expenditure.
Supply Chain Analysis
Just-in-time cost database updates dominate cloud-native architectures, though strategic stockpiles of localized material indices persist among vendors serving remote geographies. Software development concentrates in the United States, Germany, and China, with cloud infrastructure provisioning anchored in hyperscaler regions across these jurisdictions. The supply chain draws from specialized BIM engine licensors, regional cost data publishers, and API connectivity specialists. Single-source vulnerability concentrates around proprietary geometry kernels licensed from design software incumbents. Distribution runs through direct enterprise sales teams supplemented by regional implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction estimating software exhibits defensive moat characteristics rooted in switching costs: contractors face substantial workflow reconfiguration and estimator retraining investments when migrating platforms. This entrenchment sustains incumbent pricing power despite competitive pressure from adjacent construction management suites.
For Market Incumbents: Secure cloud-native architecture parity through acquisition of mobile-first estimation tools, as generative AI challengers erode quantity takeoff margins. Defend against Autodesk's design-to-construction workflow continuity by deepening vertical integration into field hardware telemetry. Prioritize carbon-cost module certification under EU Green Deal benchmarks to lock out unqualified competitors from European public procurement. For New Entrants and Emerging Players: Lead with AI-native quantity takeoff engines targeting United States mid-sized general contractors burdened by estimator talent scarcity. The most penetrable white space sits among Indian residential contractors in Tier-2 cities where spreadsheet workflows dominate bidding. Deploy freemium mobile applications calibrated to regional BIS certification requirements, then monetize through cost database subscriptions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified construction software conglomerates with underinvested estimating modules. Long-term viability favors vendors with demonstrated BIM mandate compliance across multiple jurisdictions. Watch for inflection signals in embodied-carbon accounting standard adoption rates, as REACH and CSRD enforcement timelines will separate compliant platforms from obsolete alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies quantity takeoff, bid management, and project tracking into single vendor relationships. |
| Acquisition of Specialist Firm | Adds regional cost database depth or trade-specific estimation algorithms to core platforms. |
| Geographic Expansion | Establishes local implementation capacity in Indian Tier-2 cities or Middle Eastern mega-project corridors. |
| Strategic Partnership | Secures BIM engine interoperability certifications from design software incumbents. |
| Product Launch | Introduces embodied-carbon estimation modules aligned with EU Green Deal procurement mandates. |
Research Approach
A spread of perspectives from chief estimators at general contractors, software procurement officers, BIM implementation specialists, and regional cost data publishers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU tender documentation databases, hyperscaler partnership announcements, and construction industry association technology adoption surveys. Bottom-up deployment counts triangulated against top-down software spend estimates from national construction output data.
Segmentation dimensions modeled include deployment architecture, organization size tier, construction vertical, integration complexity level, and regional regulatory cluster. CAGRs were derived from fitted growth curves across the projection horizon, with cross-checks against historical replacement cycle data for legacy desktop tools. Forecast inputs incorporated BIM mandate expansion schedules, infrastructure appropriation trajectories, and estimator workforce demographic projections.
Forecasts assume regulatory continuity in OSHA reporting requirements, EU Green Deal building performance benchmarks, and China's GB standards for construction informatization; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as embodied-carbon accounting standard enforcement timelines and cloud data sovereignty rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Web Scraper Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Global Continuous Testing Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Employee Referral Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Global Reporting Software Market
Software & Services
Ad Creation Software Market
Software & Services
Global OKR Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Movie Editing Software Market