
 Global Core Human Resource Software Market | 2026-2036
Global Core Human Resource Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Core Human Resource Software Market Foresight
North American software vendor capacity is hardening as enterprise buyers demand SOC 2 Type II-certified platforms. Oracle Corporation leverages its database heritage to anchor payroll-to-ERP integration pipelines. Workday Inc. sustains dominance in talent management through native AI-driven workforce analytics. SAP SE competes across the full solution stack with deep European public sector relationships.
Core human resource software encompasses cloud-native and on-premise platforms that automate employee data management, payroll calculation, benefits administration, and compliance reporting through centralized databases with role-based access controls. These systems serve primarily to reduce administrative overhead, ensure regulatory adherence, and generate workforce analytics for strategic planning. Cloud-based deployment now leads solution offering expansion, while talent management captures premium pricing due to skills scarcity dynamics. Small and medium enterprises represent the fastest-growing end-user category as subscription economics displace perpetual license barriers.
FDA cybersecurity guidance for health-sector HR systems, GDPR data residency mandates across European operations, and ISO 27001 certification requirements collectively shape vendor qualification standards and procurement timelines. India's BIS data localization rules and China's SAMR cross-border data transfer regulations add further compliance architecture complexity for multinational deployments. Stakeholders must monitor evolving AI governance frameworks in the European Union and United States to anticipate algorithmic hiring compliance obligations.
Market Dynamics
Cloud-native architectures are compressing deployment timelines from quarters to weeks, forcing legacy on-premise vendors to reengineer subscription economics or cede mid-market share to SaaS-native competitors.
Growth Catalysts
- GDPR Article 44 Cross-Border Transfer Rules:European employers must maintain auditable employee data trails, mandating HR platform upgrades with built-in residency controls. German and French public sector procurement now requires certified data localization.
- Skills Scarcity in Healthcare:US hospital systems face nursing and technician shortages exceeding 200,000 positions, driving premium pricing for talent management modules with predictive retention analytics.
- ISO 27001 Certification:Enterprise buyers in India and Germany now treat information security certification as a hard gate, accelerating replacement of uncertified legacy systems.
Market Restraints
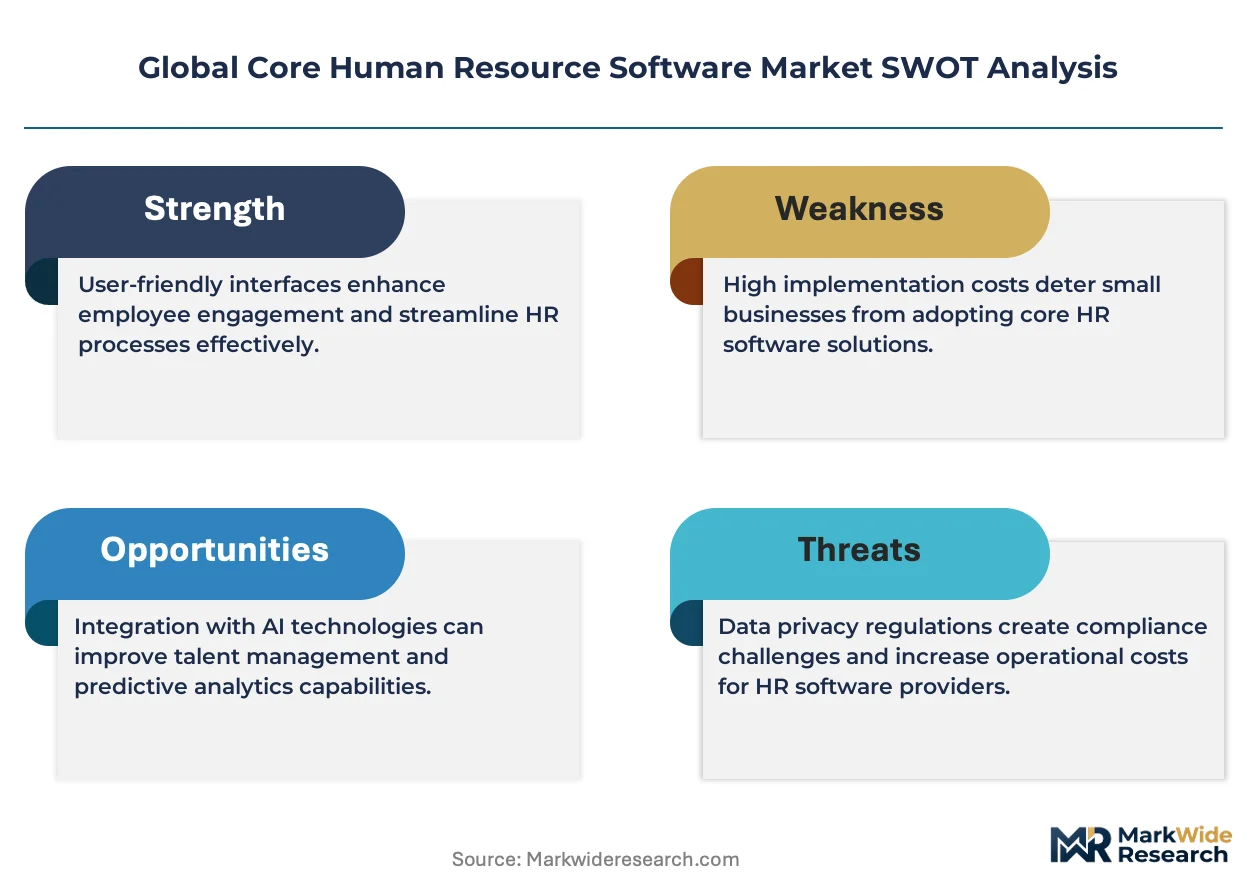
- Implementation Cost Concentration:Full-suite deployments require 18-24 month payback periods, freezing budget-constrained municipal and nonprofit employers in maintenance-only mode.
- Data Center Geographic Concentration:Cloud infrastructure for European HR workloads clusters in Frankfurt, Amsterdam, and Dublin, creating single-region failure exposure and latency penalties for Eastern European users.
- Interoperability Limitations:Proprietary data schemas from 1990s-era payroll engines block seamless API integration, forcing expensive middleware layers or manual reconciliation.
Strategic Opportunities
- Underpenetrated Indian SME Segment:India's PLI scheme for manufacturing is expanding formal employment by 12 million workers annually, yet 73% of firms with 50-500 employees still run spreadsheet-based HR processes.
- Convergence of HR Tech and Fintech:Earned wage access and embedded payroll-linked lending create new revenue streams beyond software subscriptions, with early deployment in Brazil and Mexico.
- EU AI Act Compliance Services:Algorithmic hiring tools face mandatory risk classification and audit requirements from 2025, opening consulting and certification revenue adjacent to core platforms.
Industry Challenges
- Certification Timeline Compression:SOC 2 Type II and ISO 27001 audit cycles now consume 9-14 months, delaying product launches and freezing engineering resources in documentation rather than feature development.
- Legacy System Integration Complexity:COBOL-based mainframe payroll engines at US state governments and European utilities resist API exposure, forcing expensive parallel-run migrations.
- Cross-Border Data Architecture Talent Gap:Engineers capable of designing compliant multi-region data residency are concentrated in San Francisco, London, and Bangalore, creating 40%+ salary premiums and project delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Core Human Resource Software Market |
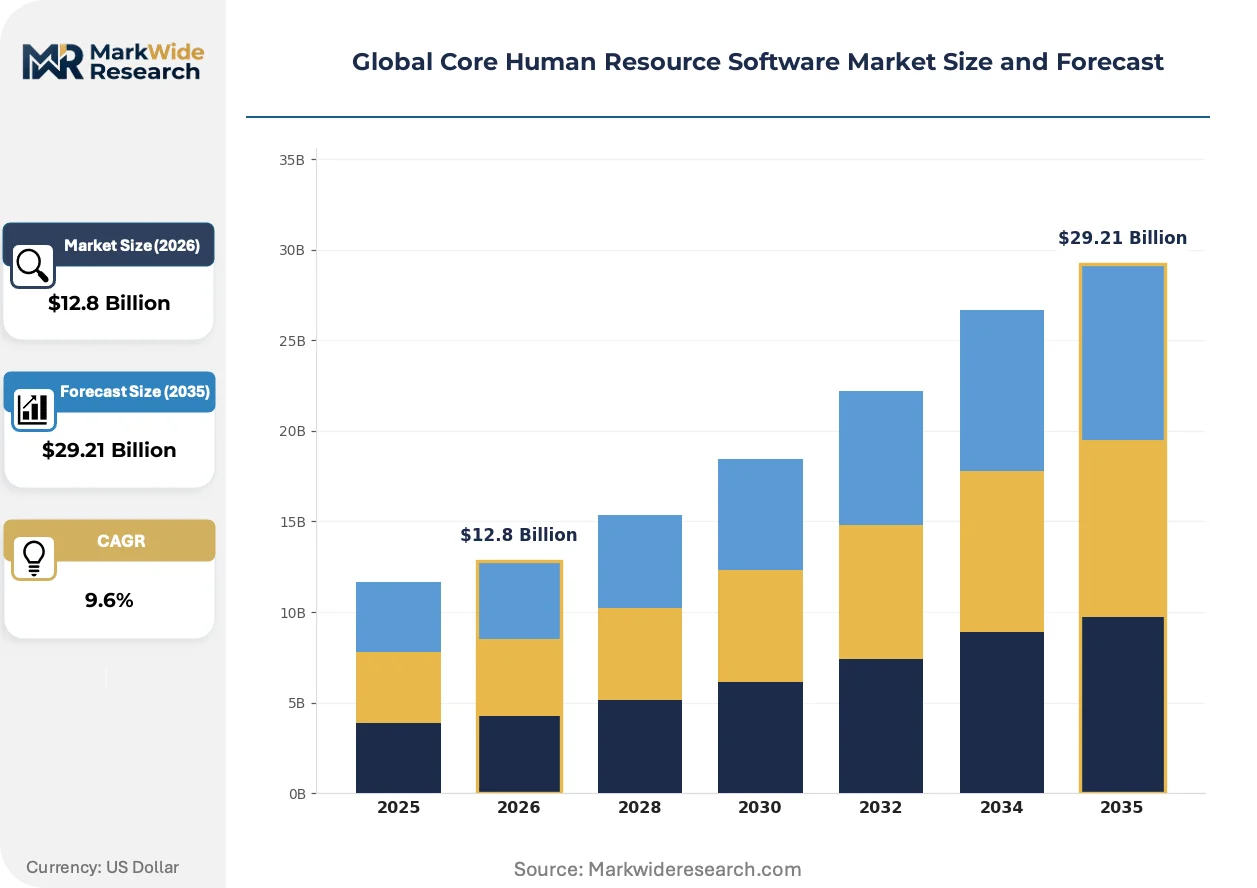
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services Solution Offering: Talent Management, Payroll Management, Time & Attendance, Employee Self-Service, Benefits Administration Application: Workforce Planning, Recruitment Automation, Performance Evaluation, Training & Development, Compliance Management End User: Large Enterprises, Small & Medium Enterprises, Government Agencies, Educational Institutions, Non-Profit Organizations |
| Companies Covered | ADP LLC, Paychex Inc., International Business Machine Corporation, UKG, Sage Group plc, Oracle Corporation, Workday Inc., Paycom Software Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Core Human Resource Software Market Shifts & Advancements
Artificial intelligence is rewriting core HR functionality from administrative record-keeping to predictive workforce optimization, while regulatory pressure and buyer sophistication are compressing vendor qualification windows.
Blockchain-verified credentialing is decentralizing employee qualification verification across enterprise boundaries. Multinational manufacturers in Germany and India are piloting interoperable skills passports that eliminate redundant background checks. This architecture is decentralizing hiring authority from centralized HR departments to line managers with direct wallet access.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for automated hiring tools. Vendors must now document training data provenance and bias testing protocols before European deployment. French and Dutch public sector buyers have frozen procurement of uncertified AI-enabled screening modules pending third-party audit completion.
Subscription fatigue among mid-sized employers is fragmenting purchasing authority from centralized IT to functional HR leaders with independent vendor evaluation capacity. German Mittelstand firms now run parallel pilots of three competing talent platforms rather than single-vendor RFPs. This pattern is most visible in US healthcare and Indian IT services verticals where CHROs control discretionary technology budgets.
Global Core Human Resource Software Market Segmentation
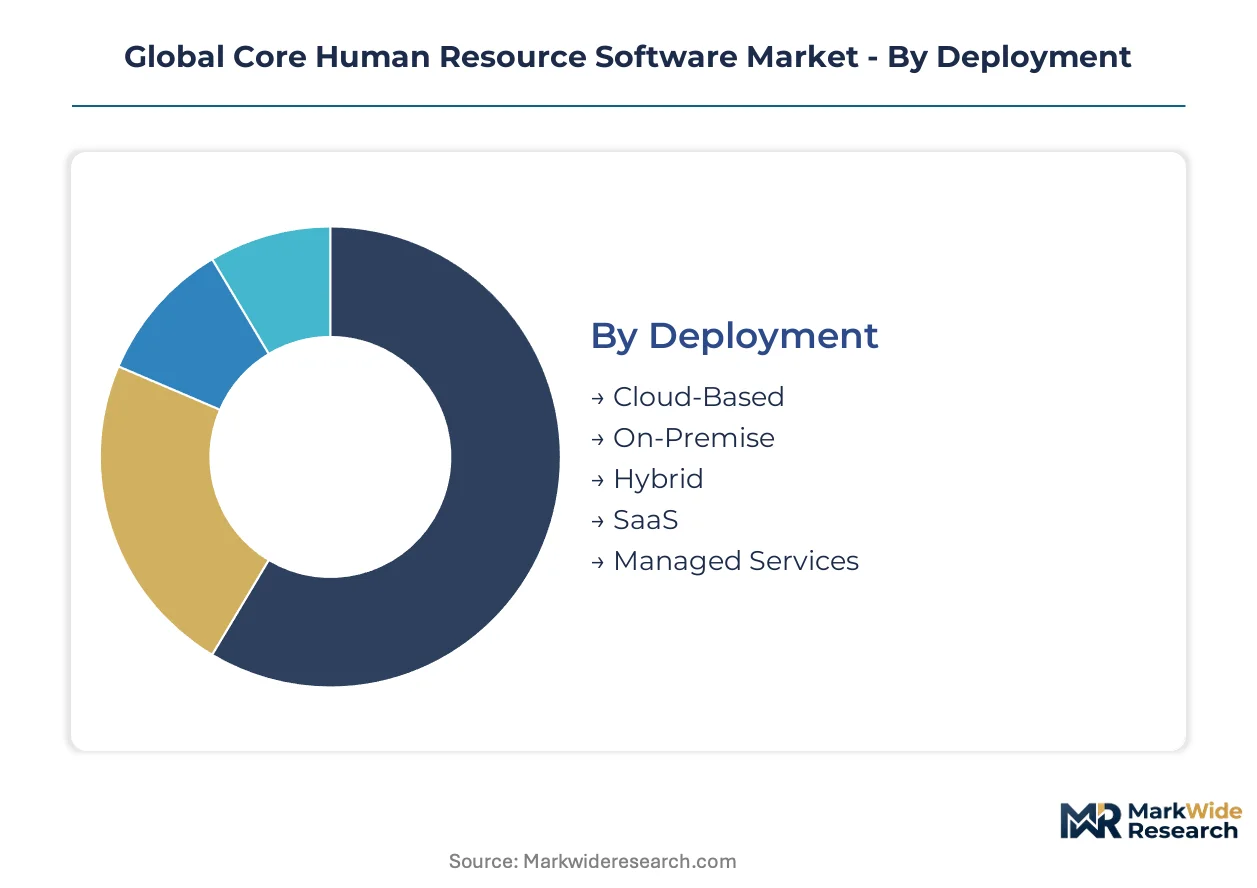
Segmentation in core human resource software reveals how certification requirements, deployment economics, and end-user sophistication create divergent purchasing patterns across buyer categories. Each dimension carries distinct regulatory burdens and implementation timelines that reshape vendor qualification standards.
Deployment:
ISO 27001 certification gates cloud and hybrid deployments for German and Indian enterprise buyers, while on-premise systems face GDPR data residency audits in European public sector procurement.
- Cloud-Based:Multi-tenant architectures with automatic patching and elastic scaling reduce IT overhead for mid-sized healthcare employers. US hospital systems concentrate demand here, driven by FDA cybersecurity guidance requiring continuous vulnerability monitoring that cloud-native platforms deliver more readily than legacy stacks.
- SaaS:Subscription economics eliminate perpetual license barriers for India's expanding manufacturing sector under the PLI scheme. Formal employment growth of 12 million workers annually forces rapid HR automation, with SaaS compressing deployment from quarters to weeks.
- On-Premise:Retained by US state governments and European utilities running COBOL-based mainframe payroll engines resistant to API exposure.
- Hybrid:Deployed by German Mittelstand firms balancing GDPR data localization with workforce analytics requiring cross-border processing.
- Managed Services:Outsourced infrastructure operation with vendor-held certification burden, appealing to budget-constrained municipal employers.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
Solution Offering:
Pricing power concentrates in modules addressing skills scarcity, with talent management commanding premium positioning against commoditized payroll processing.
- Talent Management:Predictive retention analytics and AI-driven workforce planning command premium pricing due to nursing and technician shortages exceeding 200,000 positions in US hospital systems. Native AI capabilities from leading vendors sustain dominance through predictive attrition modeling and succession pipeline visualization.
- Payroll Management:Automated calculation engines with jurisdiction-specific tax tables and garnishment handling. German and French public sector procurement mandates certified data localization, forcing platform upgrades with built-in residency controls.
- Time & Attendance:Biometric and geofenced clock-in systems with labor law compliance dashboards.
- Benefits Administration:Enrollment portals with carrier EDI integration and ACA reporting for US employers.
- Employee Self-Service:Mobile-first interfaces for PTO requests, pay stub access, and profile updates.
Steepest expansion trajectory: Talent Management. Highest margin concentration: Payroll Management.
Application:
EU AI Act risk classification from 2025 fragments automated hiring tools by audit burden, with high-risk recruitment automation facing mandatory third-party validation.
- Recruitment Automation:Resume parsing, candidate ranking, and interview scheduling with algorithmic screening. French and Dutch public sector buyers have frozen procurement of uncertified AI-enabled modules pending audit completion, creating qualification delays for vendors lacking documented training data provenance and bias testing protocols.
- Compliance Management:GDPR Article 44 cross-border transfer logging, ISO 27001 control mapping, and audit trail generation. European employers must maintain auditable employee data trails, mandating platform upgrades with built-in residency controls.
- Workforce Planning:Headcount forecasting and skills gap analysis with scenario modeling.
- Performance Evaluation:Continuous feedback systems with 360-degree review workflows.
- Training & Development:Learning management with competency tracking and certification expiration alerts.
Most heavily regulated: Compliance Management. Gaining share fastest: Recruitment Automation.
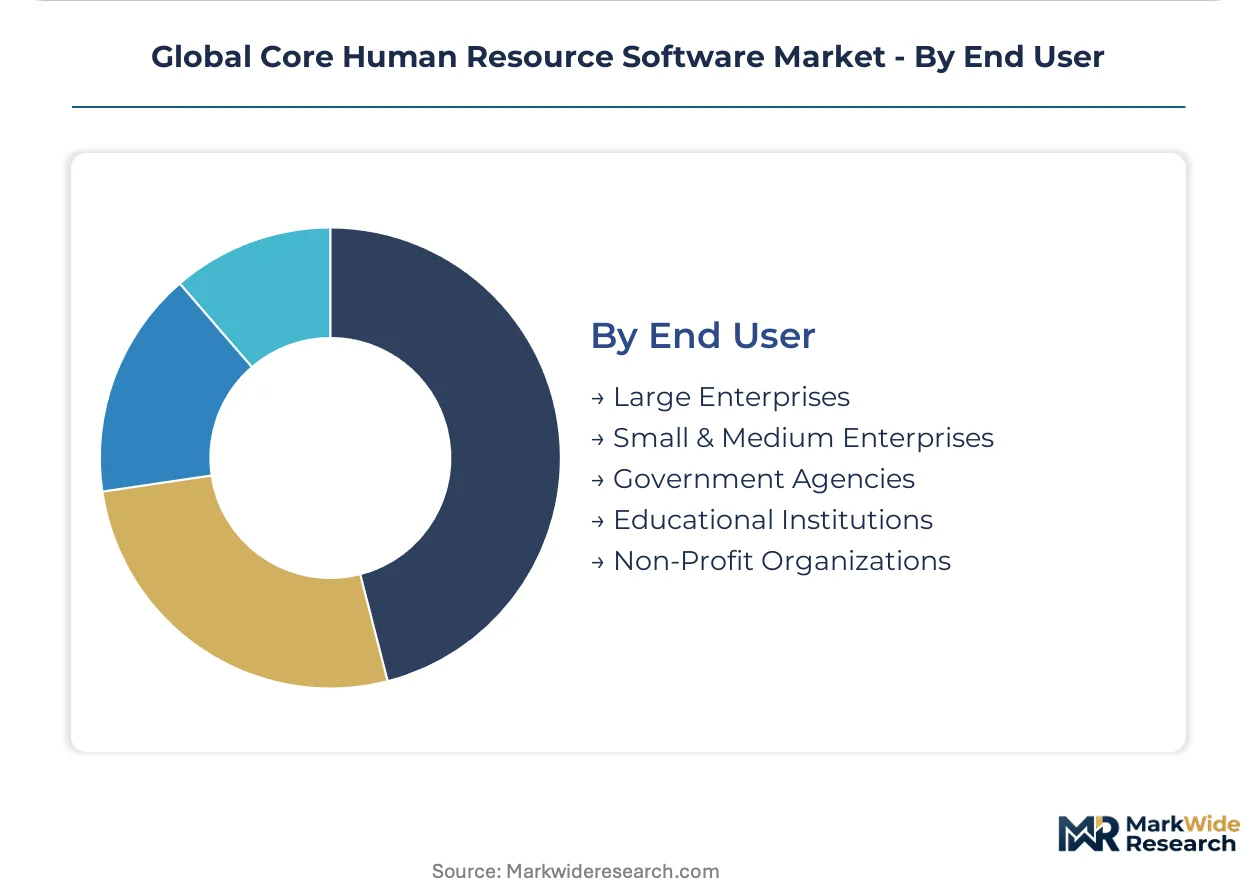
End User:
Subscription fatigue fragments purchasing authority from centralized IT to functional HR leaders, with CHRO-controlled discretionary budgets most visible in US healthcare and Indian IT services verticals.
- Small & Medium Enterprises:Firms with 50-500 employees in India still run spreadsheet-based HR processes despite formal employment expansion, representing underpenetrated demand as subscription economics displace perpetual license barriers. 73% of this segment lacks automated systems.
- Large Enterprises:Full-suite deployments requiring 18-24 month payback periods with SOC 2 Type II certification as hard gate. North American vendor capacity hardens as buyers demand certified platforms, compressing procurement timelines for qualified suppliers.
- Government Agencies:German and French public sector procurement now requires certified data localization, accelerating replacement of legacy systems.
- Educational Institutions:Multi-campus workforce management with adjunct faculty tracking and grant compliance reporting.
- Non-Profit Organizations:Budget-constrained employers frozen in maintenance-only mode due to implementation cost concentration.
Dominating current revenue: Large Enterprises. Expanding most quickly: Small & Medium Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital concentration anchors cloud-native HR software development, while Frankfurt's data center density shapes European deployment architectures. Demand clusters in three distinct regulatory zones with divergent compliance burdens.
United States
FDA cybersecurity guidance for health-sector HR systems drives continuous vulnerability monitoring requirements among hospital systems. SOC 2 Type II certification now operates as a hard procurement gate for enterprise buyers. The Dallas-Fort Worth metroplex concentrates mid-market healthcare employer demand for cloud-native talent management platforms.
Germany
GDPR Article 44 cross-border transfer rules mandate auditable employee data trails with certified data localization. German and French public sector procurement now requires built-in residency controls for all HR platform upgrades. Baden-Württemberg's Mittelstand manufacturing belt pilots hybrid deployments balancing analytics processing with data sovereignty.
India
BIS data localization rules and formal employment expansion of 12 million workers annually under the PLI scheme force rapid HR automation. ISO 27001 certification accelerates replacement of spreadsheet-based legacy systems among SMEs. Bengaluru's IT services corridor concentrates CHRO-controlled discretionary technology budgets for talent platform procurement.
United Kingdom
Post-Brexit data adequacy arrangements with the EU reshape cross-border employee data architectures for multinational employers. The Information Commissioner's Office enforces strict audit trail requirements for automated hiring tools. London's financial services cluster drives demand for payroll-to-ERP integration with real-time regulatory reporting.
China
SAMR cross-border data transfer regulations add compliance architecture complexity for multinational deployments with Chinese operations. GB standards for information security management systems shape vendor qualification protocols. Shanghai's Yangtze River Delta manufacturing hub concentrates demand for workforce analytics with localized data residency.
Global Core Human Resource Software Market Competitive Landscape
Global majors compete with regional champions across certification depth and vertical specialization. Market structure shows moderate consolidation around database heritage players and SaaS-native specialists, with persistent fragmentation in mid-market payroll processing. Three archetypes dominate: full-suite ERP integrators, cloud-native talent platforms, and compliance-focused regional processors. Competitive moves center on SOC 2 Type II certification acceleration and AI governance framework pre-positioning for EU AI Act compliance.
Within the full-suite ERP integrator tier, Oracle Corporation and SAP SE exemplify database-anchored competitive positioning, while Workday Inc. occupies the cloud-native talent management specialist position. ADP LLC represents the payroll-centric regional processor archetype with deep North American mid-market penetration. These three anchors demonstrate how certification velocity and vertical workflow depth separate sustainable positioning from commodity substitution risk.
| Leading Market Players |
|---|
| ADP LLC |
| Paychex Inc. |
| International Business Machine Corporation |
| UKG |
| Sage Group plc |
| Oracle Corporation |
| Workday Inc. |
| Paycom Software Inc. |
| SAP SE |
| Others |
Supply & Pricing Matrix
Enterprise buyers demanding SOC 2 Type II certification operate on subscription-based pricing with implementation services bundled separately from core platform fees. Cloud-native vendors capture premium positioning through ISO 27001-validated security tiers, while legacy on-premise providers compete on migration-incentive pricing for municipal and nonprofit segments frozen in maintenance-only contracts.
Pricing Analysis
Warranty and service bundling separates cloud-native SaaS tiers from on-premise perpetual licenses, with SOC 2 Type II audit support and GDPR compliance consulting unbundled as premium add-ons. Three-tier pricing structure across enterprise, mid-market, and SME levels reflects certification depth and integration complexity. Pricing pressure stems from subscription fatigue among German Mittelstand firms running parallel vendor pilots. Indian SMEs with spreadsheet-based HR processes show highest price sensitivity, while US hospital systems facing nursing shortages demonstrate lowest sensitivity for talent management modules.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Amsterdam, and Dublin concentrate cloud infrastructure for European HR workloads, creating hub-and-spoke latency patterns for Eastern European users. Software development draws from engineering talent pools in San Francisco, London, and Bangalore, with cross-border data architecture specialists commanding salary premiums. Single-region failure exposure presents structural risk given GDPR data residency mandates. Distribution runs through direct enterprise sales teams and channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certification velocity as ISO 27001 and SOC 2 Type II requirements force uncertified legacy vendors toward acquisition or exit.
For Market Incumbents: Hedge against SaaS-native displacement by accelerating EU AI Act compliance pre-positioning and acquiring mid-market payroll specialists in India. Certification timeline compression threatens engineering resource allocation, making automated audit documentation tools essential. Backward integration into AI governance consulting creates defensive moats around core platform revenue. For New Entrants and Emerging Players: Capture the underpenetrated Indian SME segment where 73% of firms with 50-500 employees lack automated HR systems. Earned wage access and embedded payroll-linked lending in Brazil and Mexico offer fintech-adjacent entry points. Partner with regional system integrators to bypass 9-14 month certification delays blocking direct procurement. For Investors and Strategic Acquirers: The window for entry favors compliance-focused regional processors with existing ISO 27001 certification and European public sector relationships. Long-term viability hinges on AI governance framework positioning ahead of mandatory algorithmic hiring audits. Watch for French and Dutch public sector procurement freezes lifting as third-party validation completes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Oracle leverages database heritage to anchor payroll-to-ERP pipelines for hospital systems. |
| Acquisition of Specialist Firm | Mid-market payroll processors in India offer PLI scheme leverage with 12 million annual worker expansion. |
| Geographic Expansion | Baden-Württemberg Mittelstand pilots hybrid deployments balancing GDPR localization with analytics. |
| Strategic Partnership | Blockchain-verified credentialing pilots in Germany decentralize hiring authority to line managers. |
| Product Launch | EU AI Act compliance services open consulting revenue adjacent to core talent platforms. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and hospital procurement databases formed the secondary backbone, validated through primary interviews with CHROs, IT procurement officers, platform engineers, and integration specialists. Bottom-up and top-down triangulation cross-checked subscription revenue models against employer census data and certification registry records.
Bottom-up modeling aggregated deployment economics across cloud, SaaS, on-premise, hybrid, and managed service categories, while top-down analysis tracked regulatory enforcement patterns from GDPR, FDA, and BIS. Segmentation dimensions included deployment model, organization size, solution offering, application type, and end-user vertical across the analysis window. CAGRs derived from elasticity-adjusted adoption curves incorporating skills scarcity metrics and compliance mandate timelines.
The model holds under stable regulatory enforcement; deviation in EU AI Act implementation pace or BIS data localization stringency would shift vendor qualification timelines. Forecasts reflect documented assumptions about certification cycle compression and cloud migration elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Saas-Based Expense Management Market
Software & Services
Global Contract Management Software Market
Software & Services
API Testing Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Image Analysis Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Skills Management Software Market
Software & Services
Human Identification Analysis Software Market
Software & Services
Global Gym Software Market
Software & Services
Global Referral Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
3D Animation Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Interior Design Software Market
Software & Services
Embedded Software Market