
 Electronic Discovery Market | 2026-2036
Electronic Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Discovery Market Analysis
Cloud infrastructure is restructuring cost economics across electronic discovery as on-premises data centers yield to elastic compute models. Relativity leverages its proprietary platform architecture to dominate enterprise legal workflows. OpenText Corporation sustains competitive positioning through deep integration with enterprise content management systems. FTI Consulting Inc. anchors its market presence via consulting-led implementation services that bind clients to long-term engagements.
Electronic discovery encompasses the identification, preservation, collection, processing, review, and production of electronically stored information for legal proceedings, typically handling terabyte-scale datasets with metadata integrity requirements and chain-of-custody protocols. The technology segment shows predictive coding maturing as a baseline capability while AI-based analytics captures expanding margin pools from premium-tier deployments. Cloud-based deployment models are displacing on-premises installations among mid-market law firms seeking operational flexibility without capital intensity.
The Federal Rules of Civil Procedure in the United States mandate proportionality standards that directly shape data collection scope and platform selection criteria. EMA documentation requirements and GDPR data subject access requests in Europe impose cross-border transfer constraints that complicate multi-jurisdictional litigation support. Stakeholders must monitor how generative AI capabilities reshape document review accuracy benchmarks and professional liability frameworks.
Market Dynamics
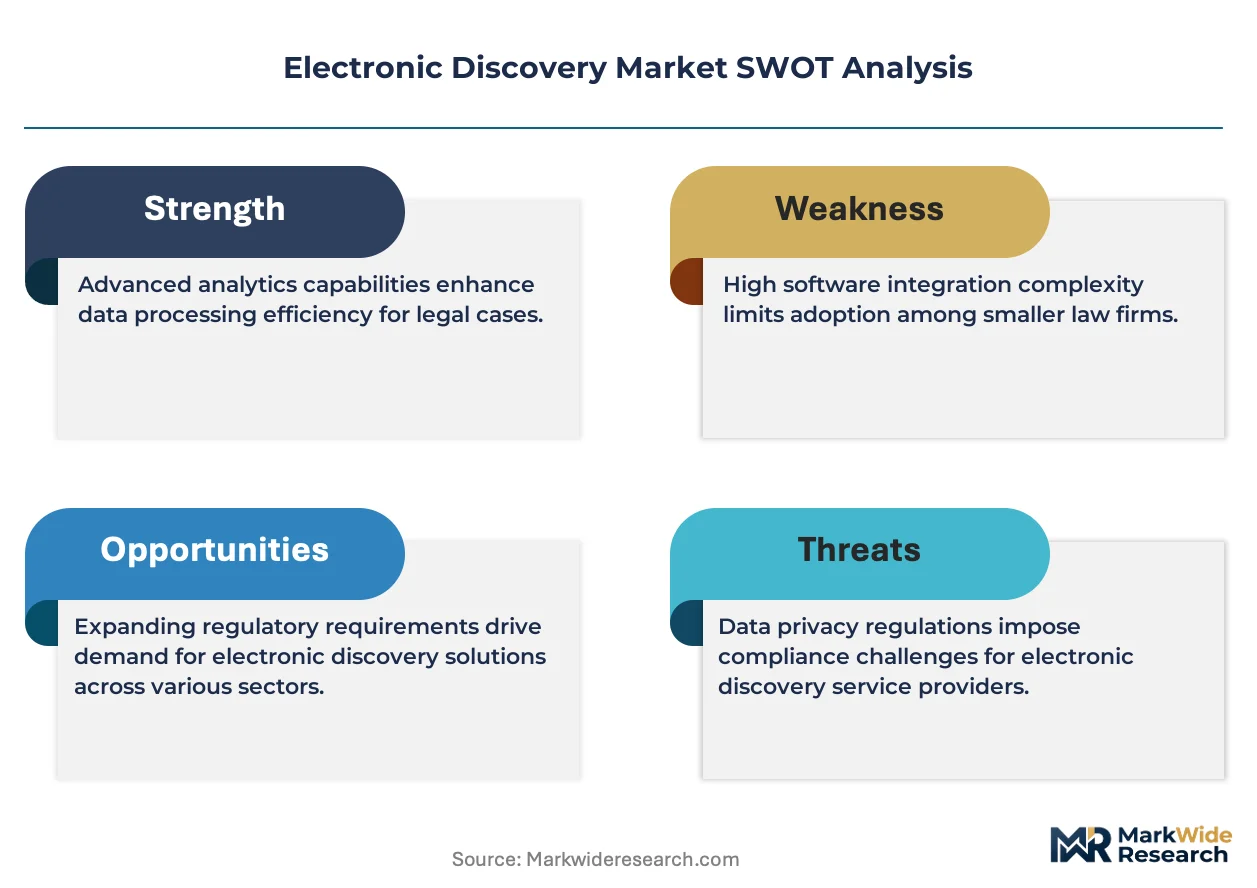
The EU AI Act is restructuring compliance requirements for automated document review systems, forcing platform providers to redesign algorithmic transparency features and audit trails that legal departments now mandate in procurement specifications.
Growth Catalysts
- Terabyte-scale litigation datasets:Federal agencies and corporate legal departments in the United States are modernizing platforms to handle exponential data volumes from cloud collaboration tools and mobile communications.
- GDPR data subject access requests:European enterprises require cross-border litigation support capabilities that preserve chain-of-custody protocols across multiple jurisdictions.
- Predictive coding maturation:Mid-market law firms are adopting AI-based analytics as baseline capabilities to reduce manual document review hours without proportional staff expansion.
Market Restraints
- Elastic compute cost volatility:Cloud infrastructure pricing fluctuations create unpredictable operational expenditure for firms processing petabyte-scale discovery matters.
- Professional liability framework uncertainty:Generative AI hallucination risks in document classification expose law firms to malpractice exposure without established precedent.
- Metadata integrity technical limitations:Native file format preservation across diverse enterprise collaboration platforms remains incompletely solved.
Strategic Opportunities
- Underpenetrated mid-market segment:Small and medium law firms in Germany and France lack capital intensity for on-premises deployment but require enterprise-grade review capabilities.
- Technology convergence of large language models and predictive coding:Hybrid architectures combining established statistical methods with generative AI offer accuracy improvements in privilege determination workflows.
- Outcome-based pricing innovation:Alternative fee arrangements tied to document reduction rates or review velocity metrics are displacing traditional per-gigabyte hosting models.
Industry Challenges
- Forensic data collection skill scarcity:Certified examiners capable of preserving ephemeral data from Slack, Teams, and mobile applications command premium compensation that stretches regional firm budgets.
- Legacy on-premises system integration friction:Hybrid environments combining retained physical archives with cloud-native review platforms create authentication and synchronization failures.
- EU AI Act compliance timeline compression:Automated decision-making documentation requirements must be operationalized before enforcement deadlines without mature vendor tooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Discovery Market |
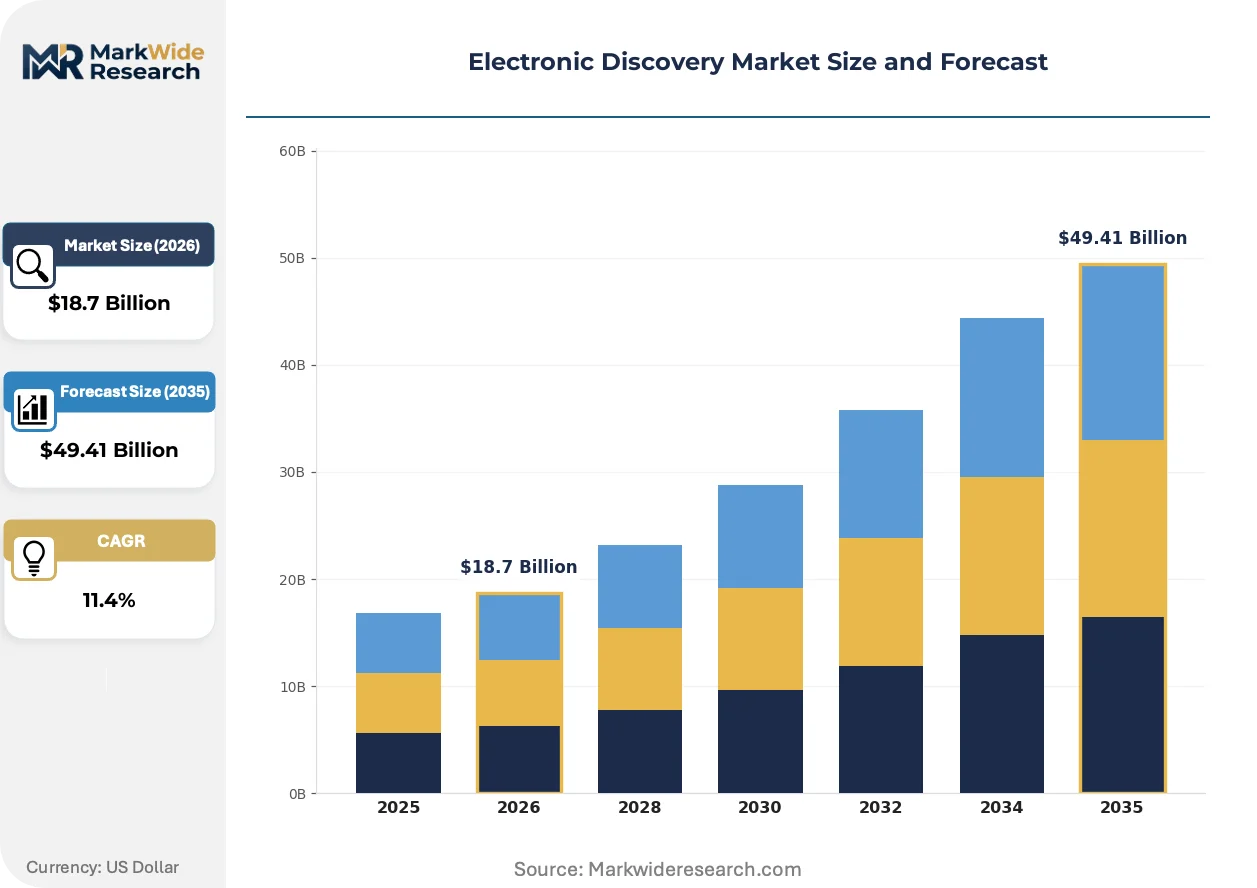
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Litigation Support, Document Review, Data Processing, Digital Forensics Deployment Model: Cloud-Based, On-Premises, Hybrid, Remote Access End User: Law Firms, Corporations, Government Agencies, Compliance Officers Technology: Predictive Coding, AI-Based Analytics, Data Visualization, Workflow Automation |
| Companies Covered | Relativity, OpenText Corporation, Microsoft Corporation, Exterro Inc., Nuix Limited, FTI Consulting Inc., Epiq Systems Inc., Veritas Technologies, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Discovery Market Emerging Trajectories
Generative AI capabilities are compressing document review timelines while simultaneously introducing new verification requirements that reshape platform architecture priorities across vendor roadmaps.
Continuous active learning algorithms are converging with transformer-based language models to enable real-time model refinement during review. AmLaw 100 firms are deploying these hybrid systems in privilege identification workflows. This convergence is compressing the traditional linear review model into iterative feedback loops that reduce attorney hour requirements.
The EU AI Act's risk classification framework for automated decision-making systems is mandating algorithmic impact assessments for high-risk ediscovery deployments. Platform providers must now document training data provenance and model performance metrics. European corporate legal departments are prioritizing vendors with pre-certified compliance documentation.
Corporate legal departments are consolidating vendor relationships and demanding unified platforms that span preservation through production. Regional law firms are responding by abandoning point solutions for integrated suites. This concentration is most visible in United States federal litigation practices where matter complexity justifies platform standardization investments.
Electronic Discovery Market Segmentation
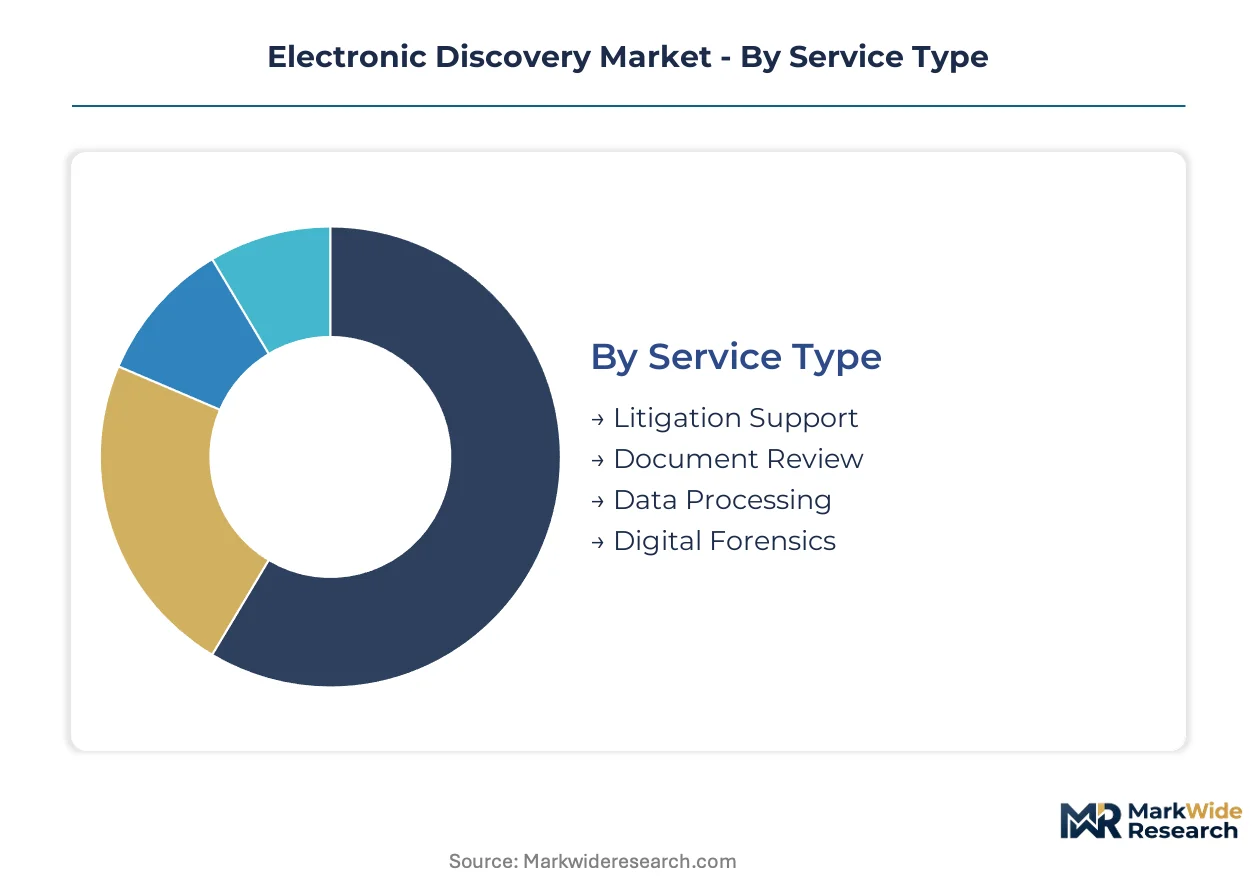
Electronic discovery procurement decisions hinge on data volume thresholds, regulatory exposure, and capital availability. Buyers select service configurations based on matter complexity and jurisdictional requirements rather than one-size-fits-all platform capabilities.
Service Type:
Law firms and corporate legal departments prioritize service bundles that compress time-to-production while preserving defensible chain-of-custody documentation.
- Litigation Support:Encompasses project management, case strategy consulting, and expert witness coordination. AmLaw 100 firms in the United States drive demand for integrated support teams that span preservation through trial preparation. Federal agency litigation mandates accelerate procurement of bundled services with established security clearances.
- Document Review:Attorney-led examination of collected materials for relevance, privilege, and responsiveness. Corporate legal departments in Germany and France are expanding managed review engagements to control personnel costs without sacrificing quality benchmarks. GDPR cross-border transfer requirements complicate reviewer location decisions.
- Data Processing:Conversion of native files to review-ready formats with metadata preservation.
- Digital Forensics:Collection and authentication of evidence from mobile devices and cloud collaboration platforms.
Litigation Support leads on scale; Digital Forensics leads on momentum.
Deployment Model:
Capital intensity and data sovereignty requirements shape infrastructure decisions across buyer segments with divergent risk tolerances.
- Cloud-Based:Elastic compute resources accessed via subscription models. Mid-market law firms in the United States favor this model to avoid data center capital expenditure while accessing enterprise-grade processing power. EU AI Act compliance documentation is becoming a mandatory procurement filter for European deployments.
- On-Premises:Physical infrastructure maintained within client-controlled facilities. Government agencies with classified matter requirements mandate air-gapped environments that exclude external network connectivity. High fixed costs limit expansion to matters with national security implications.
- Hybrid:Split architectures preserving sensitive data on-premises while pushing bulk processing to cloud environments.
- Remote Access:Browser-based review platforms enabling distributed attorney teams.
Cloud-Based deployment commands the largest installed base; Hybrid architectures are gaining share fastest as compliance complexity rises.
End User:
Procurement authority and budget accountability vary sharply across organizational types with distinct governance structures.
- Law Firms:Partnership-owned practices billing discovery costs to client matters. Boutique litigation boutiques in London and New York are consolidating vendor relationships to secure volume discounts and standardized workflows. Malpractice exposure drives conservative technology adoption timelines.
- Corporations:In-house legal departments managing regulatory investigations and employment disputes. Multinational enterprises subject to SEC enforcement prioritize platforms with pre-configured reporting templates. Cost allocation between legal and IT budgets creates internal friction.
- Government Agencies:Federal and state entities with public procurement constraints.
- Compliance Officers:Risk management functions conducting proactive data audits.
Law Firms generate the highest transaction velocity; Corporations are expanding internal capabilities most aggressively.
Technology:
Platform differentiation increasingly depends on algorithmic sophistication rather than storage capacity or processing speed.
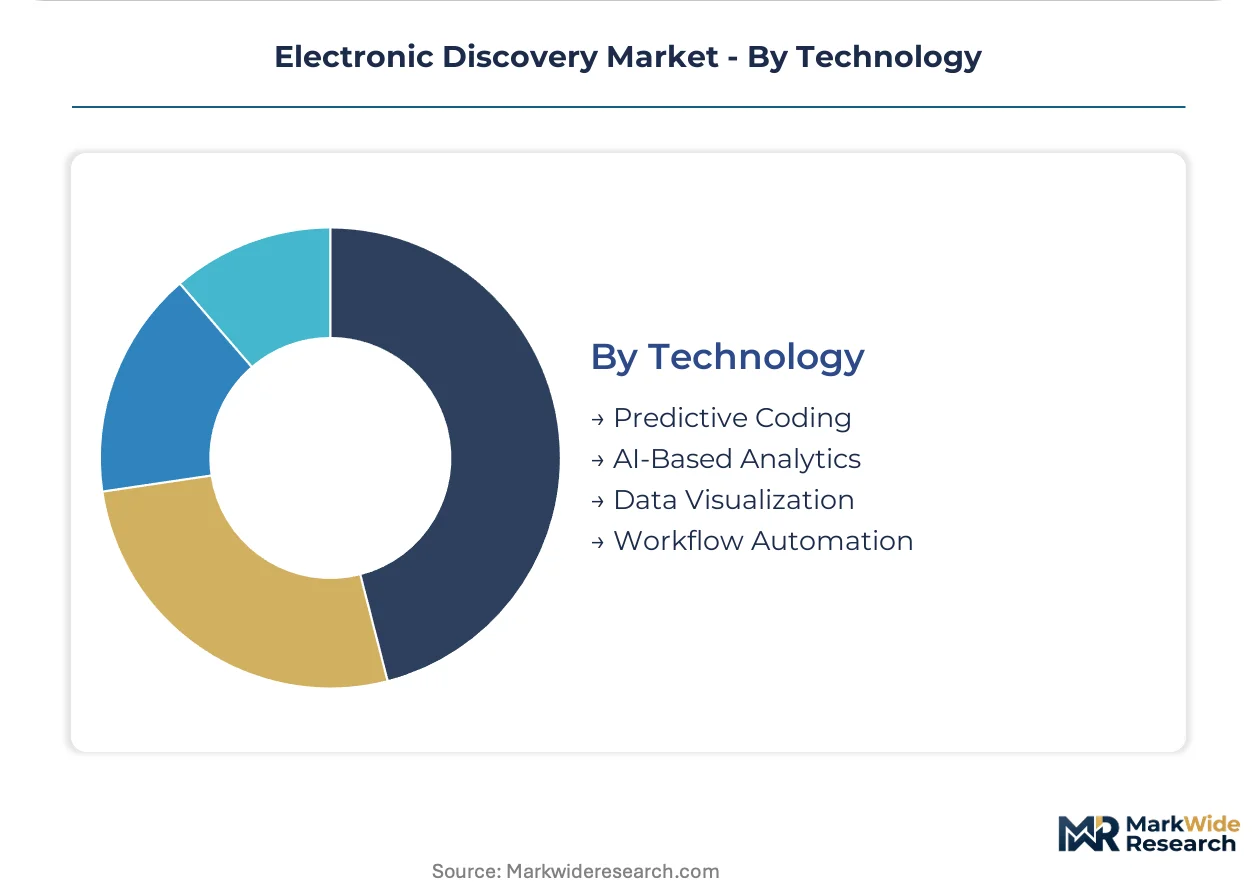
- AI-Based Analytics:Machine learning models identifying patterns across unstructured data populations. Federal Rules of Civil Procedure proportionality standards in the United States incentivize early case assessment tools that reduce collection scope. Continuous active learning algorithms now refine models in real-time during review.
- Predictive Coding:Statistical sampling methods prioritizing document populations for attorney examination. Mature implementations have achieved judicial acceptance in major commercial litigation venues. Baseline capability status is compressing pricing premiums.
- Data Visualization:Interactive dashboards mapping communication networks and temporal relationships.
- Workflow Automation:Rules-based routing and quality control mechanisms.
Predictive Coding retains the broadest adoption footprint; AI-Based Analytics shows the steepest expansion trajectory as generative capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of cloud infrastructure providers and legal technology vendors anchors the Electronic Discovery Market's innovation pipeline. Federal litigation volumes and enterprise cloud adoption drive platform modernization across distinct national markets. Regulatory fragmentation around AI governance and data sovereignty is reshaping vendor deployment strategies.
United States
Federal agencies and AmLaw 100 firms drive demand for terabyte-scale processing capabilities. The Federal Rules of Civil Procedure proportionality standards directly shape collection scope decisions. New York and Washington DC legal clusters concentrate managed review services and consulting-led implementations.
Germany
Corporate legal departments in Frankfurt and Munich seek GDPR-compliant cross-border litigation support. The EU AI Act's automated decision-making documentation requirements compress vendor compliance timelines. Bavaria's industrial conglomerates anchor demand for hybrid deployment models balancing sovereignty with elastic compute.
United Kingdom
London's litigation finance ecosystem and Magic Circle firms generate complex multi-jurisdictional discovery matters. The Information Commissioner's Office guidance on automated processing shapes procurement specifications. The City of London's financial services sector drives demand for real-time communication platform forensics.
France
CNIL enforcement priorities and data localization mandates constrain cloud-native platform selection. Paris-based multinational enterprises require privilege identification workflows compliant with French blocking statutes. Île-de-France's corporate headquarters cluster sustains demand for integrated preservation-to-production suites.
Japan
METI's data governance frameworks and cross-border discovery treaty limitations structure market entry barriers. Tokyo's financial institutions and trading houses invest in predictive coding for regulatory investigation preparedness. Osaka's manufacturing conglomerates anchor demand for supply chain litigation support capabilities.
Electronic Discovery Market Vendor Landscape
Platform consolidation dominates the current landscape as enterprise legal departments demand unified preservation-through-production workflows. The vendor base stratifies across three tiers: cloud-native specialists, legacy enterprise software incumbents, and consulting-led service integrators. M&A activity concentrates on AI analytics capabilities, while geographic expansion targets underpenetrated European mid-market segments.
Within the platform-specialist tier, Relativity and OpenText Corporation occupy positions defined by proprietary architecture depth and enterprise content management integration respectively. FTI Consulting Inc. exemplifies the consulting-led archetype where implementation services bind clients to long-term engagements. Microsoft Corporation represents the cloud infrastructure entrant leveraging existing enterprise relationships to displace point solutions.
| Leading Market Players |
|---|
| Relativity |
| OpenText Corporation |
| Microsoft Corporation |
| Exterro Inc. |
| Nuix Limited |
| FTI Consulting Inc. |
| Epiq Systems Inc. |
| Veritas Technologies |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Certified forensic examiners concentrated in Silicon Valley and New York legal corridors command compensation premiums that widen pricing spreads between premium-tier managed review engagements and commoditized processing services. Labor-cost differentials between these talent clusters and emerging delivery locations in Germany and France directly shape three-tier pricing structures across the electronic discovery value chain.
Pricing Analysis
Input-cost pass-through from elastic cloud infrastructure dominates pricing models, with subscription-based SaaS tiers replacing per-gigabyte hosting arrangements. Price differentiation rests on AI analytics sophistication and EU AI Act compliance certification levels. Pricing pressure stems from generative AI capabilities compressing manual review hours. Mid-market law firms exhibit highest price sensitivity; federal agencies with security clearance requirements show lowest.
Supply Chain Analysis
Certification and qualification gating through ISO 27001 and SOC 2 Type II audits concentrates vendor eligibility among established platform providers. Geographic supply concentration centers on the United States, Ireland, and Germany for cloud infrastructure and data processing capacity. Raw material dependencies include GPU compute clusters, enterprise storage arrays, and specialized forensic collection hardware. Supply chain risk manifests as single-source vulnerability for certified examiners capable of mobile and ephemeral data preservation. Distribution runs through direct enterprise sales with consulting-led implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic discovery market represents a late-cycle quality story as corporate legal departments consolidate vendor relationships and prioritize platforms with pre-certified EU AI Act compliance documentation.
For Market Incumbents: Anchor market position through backward integration into AI model training data pipelines and captive forensic examiner certification programs. Relativity and OpenText Corporation face emerging threat from Microsoft Corporation's enterprise cloud relationships. Vertical integration into continuous active learning algorithm development offers defensive moat against generative AI entrants. For New Entrants and Emerging Players: Large language model-powered privilege identification tools offer technology-first wedge into underpenetrated mid-market segments in Germany and France. Most penetrable target: small litigation boutiques lacking capital intensity for on-premises deployment. Go-to-market angle: outcome-based pricing tied to document reduction rates displacing traditional hosting models. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking legal technology capabilities to deepen enterprise workflow penetration. Long-term viability favors vendors with hybrid AI-statistical architectures and pre-built compliance documentation. Signal to watch: EU AI Act enforcement actions creating vendor disqualification events.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified preservation-through-production workflows reduce client vendor consolidation costs and switching friction. |
| Acquisition of Specialist Firm | AI analytics boutiques with continuous active learning expertise accelerate generative AI roadmap execution. |
| Geographic Expansion | Mid-market penetration in Frankfurt and Munich captures GDPR-compliant cross-border litigation demand. |
| Strategic Partnership | Cloud infrastructure alliances with hyperscalers secure elastic compute pricing advantages for petabyte-scale matters. |
| Product Launch | EU AI Act pre-certified compliance documentation modules become mandatory procurement filters in European RFPs. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, France, and Japan, with primary inputs from each market cluster. Primary interviews combined insights from ediscovery platform engineers, corporate legal department procurement officers, federal agency litigation support directors, and managed review service operations managers. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, EU regulatory documentation, and federal procurement databases. Bottom-up and top-down triangulation cross-checked service revenue estimates against platform deployment metrics.
Granularity-level modeling addressed deployment model, organization size, service type bundle complexity, and regional regulatory framework variations across the projection horizon. Segmentation dimensions included technology tier, end-user organizational type, and jurisdictional compliance requirements. CAGRs were derived from trend extrapolation of platform adoption curves and service pricing trajectories. Industry-specific forecast inputs encompassed federal litigation volume trends and EU AI Act implementation timelines.
The model holds under stable regulatory enforcement timelines; deviation in EU AI Act penalty severity or generative AI malpractice precedent would shift enterprise adoption curves. Forecasts reflect assumptions regarding cloud infrastructure cost trajectories and certified examiner supply expansion. A model refresh is warranted upon material change in federal proportionality standard interpretations or hyperscaler pricing architecture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Product As a Service Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Chile ICT Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Revops Platform Market
Digital Solutions
Latin America IT Market
Digital Solutions
Social Networking App Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Load Balancer Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Online Hyper-Local Services Market
Digital Solutions
Legal Transcription Market