
 User Interface Software Market | 2026-2036
User Interface Software Market Size, Share, and Industry Trends Forecast 2026-2036
User Interface Software Market Analytics
Enterprise IT departments is bifurcating from freelance designers as the dominant procurement archetype for interface tooling. Adobe leverages its Creative Cloud ecosystem to sustain recurring revenue across large organizations. Figma competes through real-time collaboration infrastructure that dominates product-team workflows. Sketch anchors its position among Mac-native design specialists who prioritize native performance over cross-platform flexibility.
User interface software encompasses platforms for designing, prototyping, and validating digital interaction surfaces through vector-based canvas engines, component libraries, and interactive state mapping. These systems render specifications in code-exportable formats to bridge design and engineering handoffs across web, mobile, and embedded display targets. Cloud-based deployment leads segment economics by converting perpetual licenses into recurring revenue streams with lower churn than on-premises alternatives. Gaming and healthcare applications represent the fastest-expanding demand pools, as surgical simulation interfaces and immersive HUD systems require specialized prototyping tools with haptic feedback integration. Embedded technology remains the most margin-constrained segment due to hardware-specific certification cycles and fragmented OEM procurement.
The EU AI Act imposes explainability requirements on adaptive interfaces, compelling vendors to document decision pathways in dynamically personalized UIs. FDA scrutiny of human factors engineering in medical device software elevates validation standards for healthcare application developers. ISO 9241 ergonomics standards govern workstation interface compliance across European and North American enterprise deployments. Stakeholders must decide whether to build in-house accessibility compliance engines or outsource certification to specialized testing laboratories as regulatory fragmentation deepens.
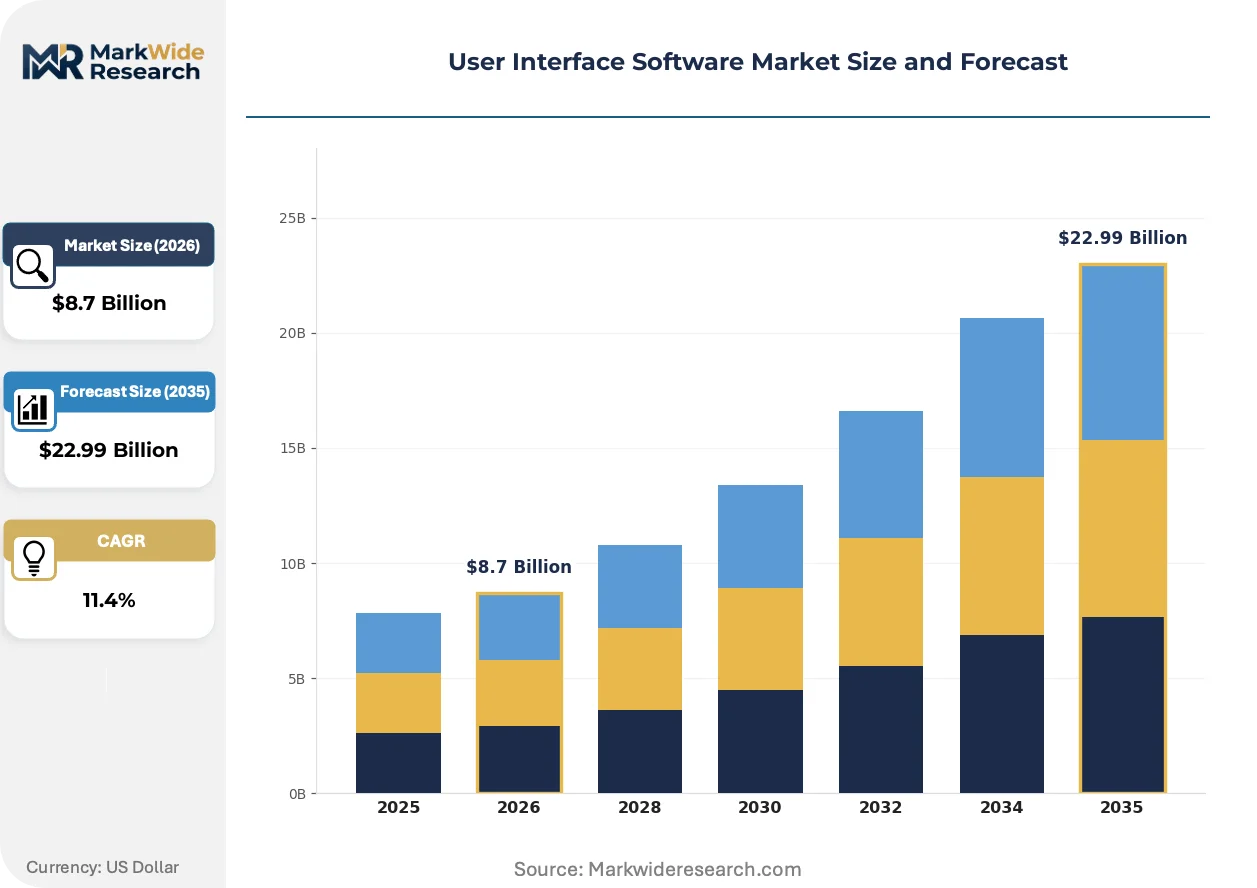
Market Dynamics
Enterprise procurement of interface tooling is splitting between centralized IT departments and decentralized product teams, creating parallel buying channels with conflicting vendor selection criteria. This structural bifurcation forces vendors to maintain dual go-to-market architectures.
Growth Catalysts
- EU AI Act mandates:Explainability requirements for adaptive interfaces compel healthcare and financial services firms to upgrade design systems with documented decision pathways.
- Haptic feedback integration:Surgical simulation and automotive HUD prototyping require specialized tooling that standard design platforms cannot deliver.
- Germany's automotive cluster:Stuttgart and Munich host concentrated OEM design centers driving demand for embedded interface validation tools.
Market Restraints
- Hardware certification cycles:Embedded interface tools face 18-24 month validation timelines with automotive and medical device OEMs, compressing margins.
- Cloud infrastructure concentration:Three hyperscalers control the substrate for real-time collaboration features, creating supplier power asymmetry.
- Open-source substitution:Penpot and GIMP-based workflows displace paid seats in cost-conscious public sector and education deployments.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives attract smartphone and appliance OEMs needing localized UX validation capabilities.
- ISO 9241 ergonomics compliance:European workstation mandates create recurring certification revenue streams for accessibility testing modules.
- Voice-to-code convergence:Natural language interface generation merges with traditional canvas tools, opening non-designer user bases.
Industry Challenges
- Design-systems engineering talent:Shortage of specialists who bridge component architecture and front-end implementation slows enterprise rollouts.
- FDA human factors documentation:Medical device software requires traceable validation artifacts that extend sales cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | User Interface Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: Enterprises, Small Businesses, Educational Institutions, Freelancers Technology: Web, Mobile, Desktop, Embedded Application: Gaming, E-commerce, Healthcare, Social Media |
| Companies Covered | Figma, Adobe, Sketch, InVision Studio, Axure, Balsamiq, Webflow, ProtoPie, Pidoco GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
User Interface Software Market Evolving Landscape
Interface tooling is fragmenting into specialized layers as real-time collaboration becomes table stakes and differentiation shifts toward vertical-specific validation capabilities.
Component-based design architecture is decomposing monolithic canvas tools into interoperable primitives. Automotive and healthcare product teams are adopting modular systems at twice the rate of general enterprise users. This decomposition enables specialized vendors to capture value at the validation layer without competing on raw canvas performance.
REACH substance restrictions and the EU AI Act's algorithmic transparency mandates are forcing design tool vendors to document data flows in AI-assisted features. Vendors must now maintain audit trails for generative UI suggestions. Healthcare application developers face the steepest compliance burden as FDA human factors guidance overlaps with European requirements.
Centralized IT procurement of design tooling is losing ground to product-team self-selection. Engineering-led organizations are bypassing traditional vendor-of-record agreements to adopt browser-based collaboration platforms. This pattern is most pronounced in software-centric verticals across the United States and United Kingdom.
User Interface Software Market Segmentation
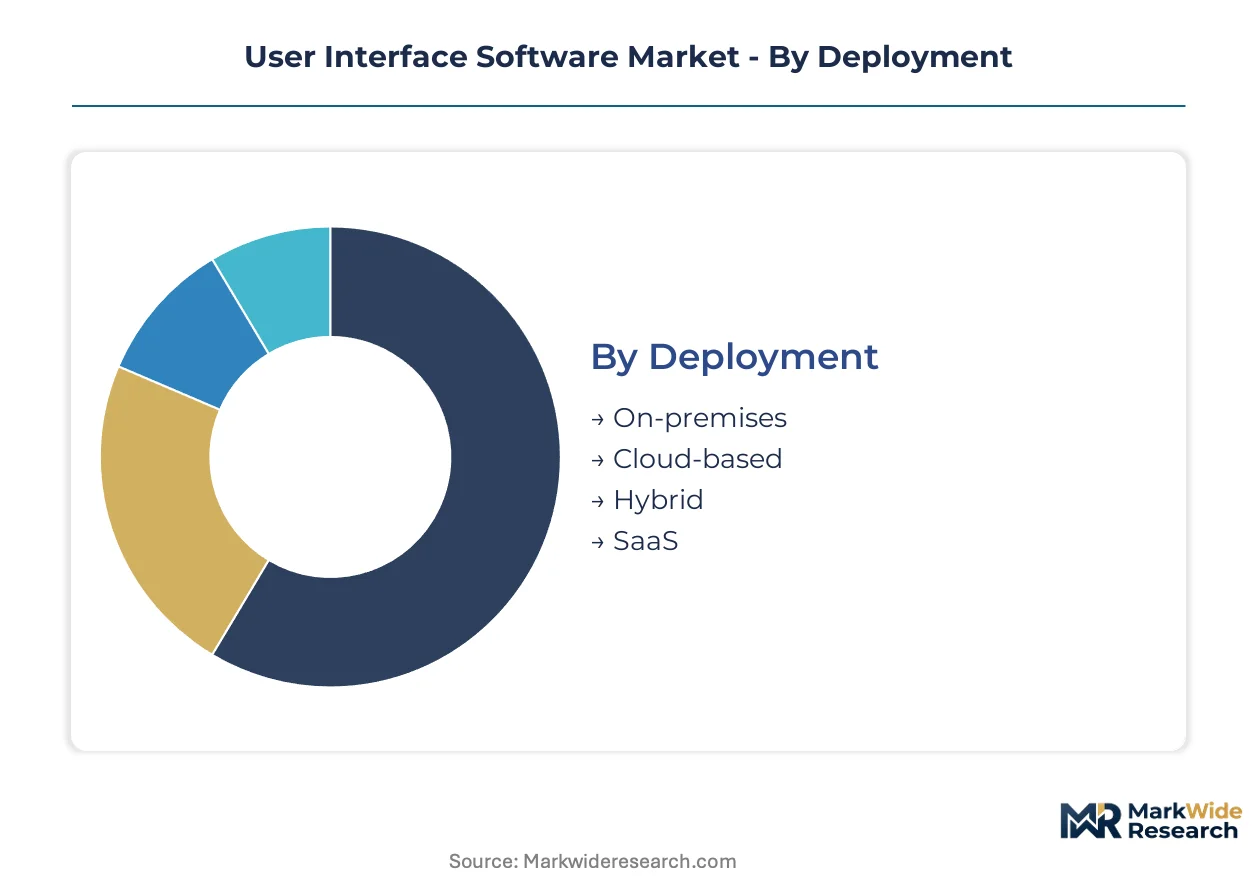
Deployment mode determines recurring revenue predictability for interface software vendors. End-user archetypes drive divergent feature requirements and sales cycle lengths. Technology platforms and application verticals shape validation standards and margin profiles.
Deployment:
Margin pools concentrate in cloud-native delivery models that convert perpetual licenses into recurring revenue streams.
- Cloud-based:Browser-accessible platforms with real-time collaboration engines dominate product-team procurement. Healthcare providers in Germany's Stuttgart cluster favor these systems for touch-screen diagnostic interface development due to rapid iteration cycles.
- SaaS:Subscription tiers bundle component libraries with automated version control. Enterprise IT departments in the United States negotiate multi-year agreements that embed accessibility compliance modules.
- On-premises:Air-gapped installations serve defense contractors and financial institutions with data sovereignty requirements.
- Hybrid:Split architectures allow sensitive asset storage locally while leveraging cloud rendering for collaboration.
The dominant share belongs to Cloud-based deployment, while SaaS is closing the gap fastest as procurement centralization loses ground to product-team self-selection.
End User:
Volume concentrates among organizations with formal design operations budgets exceeding six figures annually.
- Enterprises:Centralized IT departments and decentralized product teams create parallel buying channels with conflicting vendor selection criteria. Adobe and Figma compete through distinct go-to-market architectures targeting these splits.
- Freelancers:Individual practitioners prioritize subscription flexibility and cross-platform portability. Mac-native performance anchors loyalty among design specialists who reject browser-based latency.
- Small Businesses:Cost-conscious teams adopt open-source alternatives like Penpot for component library management.
- Educational Institutions:Volume licensing agreements with verification requirements displace individual seat purchases.
Enterprises command the largest revenue pool, though Freelancers are expanding most quickly as gig-economy design labor fragments traditional employment structures.
Technology:
Application complexity and certification burden determine pricing power across platform types.
- Mobile:Touch-optimized prototyping tools with gesture libraries dominate smartphone OEM design centers. India's PLI scheme for electronics manufacturing attracts appliance makers needing localized UX validation capabilities.
- Embedded:Hardware-specific tooling for automotive HUD and surgical simulation interfaces requires haptic feedback integration. FDA human factors documentation extends sales cycles by 8-14 months.
- Web:Responsive canvas engines with CSS export capabilities bridge design-to-engineering handoffs.
- Desktop:Native performance optimization retains specialist users prioritizing vector manipulation speed over collaboration features.
Mobile technology holds the dominant position, while Embedded is gaining share fastest as automotive and medical device OEMs invest in specialized validation tooling.
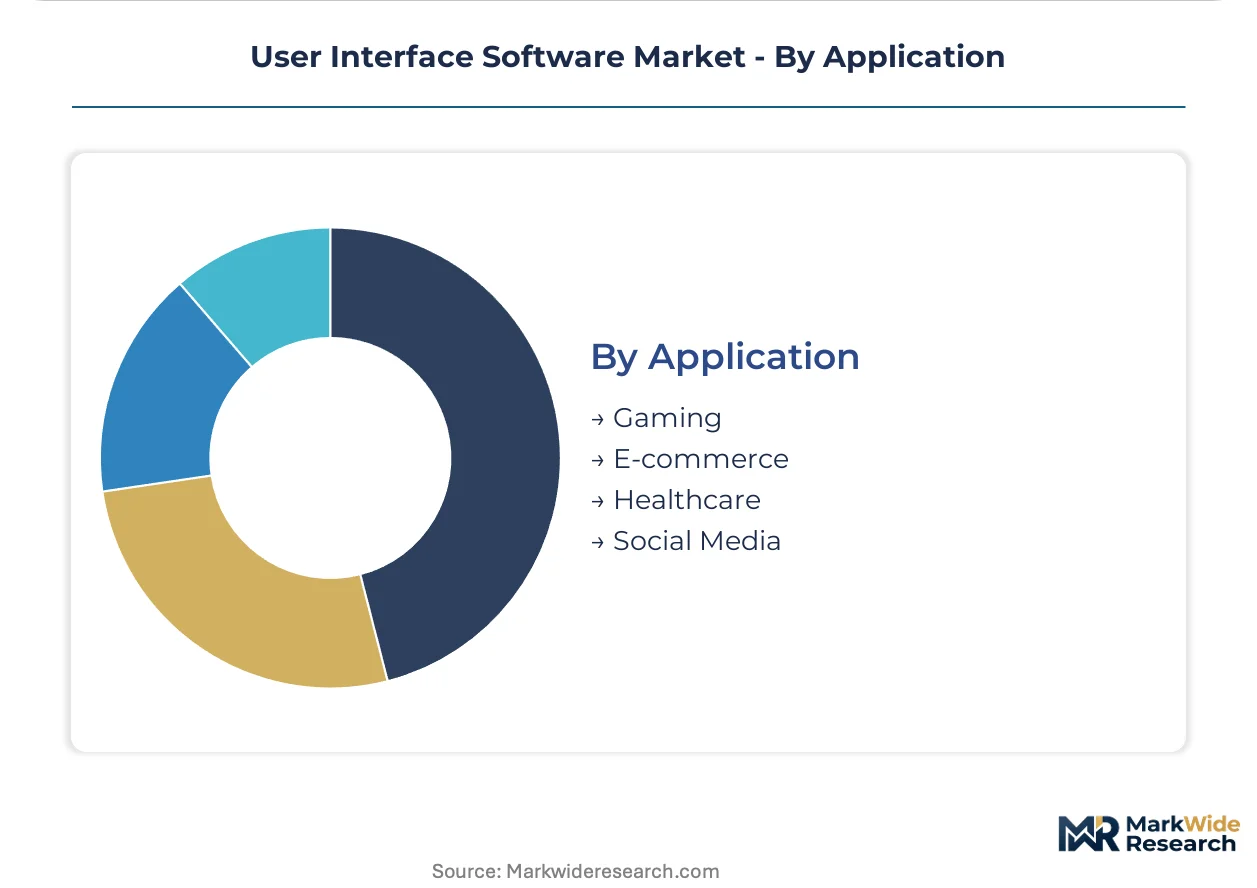
Application:
Regulatory intensity varies dramatically across verticals, creating tiered compliance service opportunities.
- Healthcare:Surgical simulation interfaces and diagnostic touch-screen systems demand ISO 9241 ergonomics compliance and FDA traceable validation artifacts. EU AI Act explainability requirements overlap with European mandates.
- Gaming:Immersive HUD prototyping drives demand for specialized tools with real-time rendering performance. Haptic feedback integration distinguishes premium offerings.
- E-commerce:Adaptive personalization engines face EU AI Act algorithmic transparency mandates requiring documented decision pathways.
- Social Media:Rapid A/B testing workflows prioritize speed over formal validation standards.
Healthcare commands the dominant application share, with Gaming climbing the fastest as immersive experience investments accelerate across console and VR platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables landing at Cork and Dublin underwrite Ireland's role as a data routing hub for European SaaS platforms. Submarine cable systems connecting Singapore to Mumbai and Chennai anchor Southeast Asia's integration with Indian software development centers.
United States
Defense contractors and financial institutions drive demand for air-gapped on-premises installations with data sovereignty requirements. FDA human factors guidance for medical device software elevates validation standards for healthcare application developers. Engineering-led organizations in San Francisco and New York bypass traditional vendor-of-record agreements to adopt browser-based collaboration platforms.
Germany
Automotive OEM design centers and surgical simulation interface developers require specialized embedded validation tooling with haptic feedback integration. EU AI Act explainability mandates compel healthcare and financial services firms to upgrade design systems with documented decision pathways. Stuttgart and Munich host concentrated demand clusters for touch-screen diagnostic interfaces and automotive HUD prototyping tools.
United Kingdom
Software-centric verticals exhibit the most pronounced shift toward product-team self-selection over centralized IT procurement. GDPR and emerging algorithmic transparency requirements shape vendor selection criteria for adaptive personalization engines. London's fintech cluster drives demand for rapid iteration cycles in cloud-native design platforms.
India
Smartphone and appliance OEMs attracted by the PLI scheme for electronics manufacturing need localized UX validation capabilities. BIS standards and central bank guidelines influence enterprise software procurement patterns. Bengaluru and Hyderabad development centers serve as delivery hubs for global product teams requiring real-time collaboration infrastructure.
Japan
Console gaming studios and automotive electronics divisions invest in immersive HUD prototyping with real-time rendering performance. METI industrial policy supports domestic software tooling capabilities for embedded systems. Tokyo and Osaka house concentrated demand for specialized prototyping tools bridging design and engineering handoffs.
User Interface Software Market Competitive Landscape
Listed leaders compete with private specialists across recurring revenue models and collaboration infrastructure. The vendor landscape organizes around three tiers: cloud-native platforms with real-time engines, native-performance desktop tools for specialist users, and open-source alternatives displacing paid seats in cost-conscious segments. Strategic moves concentrate on dual go-to-market architectures serving both centralized IT departments and decentralized product teams, alongside vertical-specific validation layer acquisitions.
Within the cloud-native tier, Figma and Adobe exemplify contrasting approaches to enterprise penetration. Figma occupies a position defined by browser-accessible real-time collaboration that dominates product-team workflows. Adobe anchors the integrated-creative-suite archetype, leveraging ecosystem lock-in across large organizations. Among European specialists, Pidoco GmbH represents the embedded-validation niche serving automotive and medical device OEMs with hardware-specific certification requirements.
| Leading Market Players |
|---|
| Figma |
| Adobe |
| Sketch |
| InVision Studio |
| Axure |
| Balsamiq |
| Webflow |
| ProtoPie |
| Pidoco GmbH |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month hardware certification cycles for embedded interface tools compress vendor margins and concentrate pricing power among buyers with validated supplier relationships. This elongated validation timeline shapes procurement patterns across automotive and medical device OEMs, forcing tiered pricing structures that separate established certification holders from aspirant vendors.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-year agreements from product-team self-serve subscriptions. Three-tier pricing stratifies across premium compliance-bundled tiers, standard collaboration tiers, and economy single-seat tiers. Price differentiation hinges on certification grade—ISO 9241 ergonomics validation and FDA human factors documentation—and vertical integration depth of accessibility testing modules. Cost compression in the embedded segment intensifies because hardware-specific tooling faces open-source substitution from Penpot and GIMP-based workflows. Public sector and educational buyers exhibit highest price sensitivity; defense contractors with air-gapped requirements show lowest sensitivity due to data sovereignty mandates.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing hubs to European automotive clusters face container availability constraints on Singapore-Mumbai-Chennai trade lanes. Cloud infrastructure supply concentrates in the United States, Ireland, and Germany, with three hyperscalers controlling the substrate for real-time collaboration features. Raw material dependencies span semiconductor components for haptic feedback integration, fiber optic cable capacity for transatlantic data routing, and specialized display hardware for surgical simulation interfaces. Single-source vulnerability in hyperscaler cloud services creates supplier power asymmetry. Distribution runs through direct enterprise sales teams for IT departments and self-serve digital channels for decentralized product teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise software procurement cycles are recovering from pandemic-era budget freezes as product-team self-selection accelerates replacement of centralized IT agreements. This cyclical rebound in design tooling expenditure creates window for strategic repositioning.
For Market Incumbents: Compound ecosystem lock-in through vertical integration into accessibility compliance engines, capturing recurring certification revenue as EU AI Act mandates deepen. Defend against open-source substitution by embedding proprietary haptic feedback integration libraries that standard platforms cannot replicate. Prioritize dual go-to-market architectures serving both centralized IT procurement and decentralized product-team workflows. For New Entrants and Emerging Players: Lead with voice-to-code convergence capabilities that merge natural language interface generation with traditional canvas tools, opening non-designer user bases in engineering-led organizations. Target India's PLI scheme beneficiaries—smartphone and appliance OEMs needing localized UX validation capabilities—as the most penetrable geography. Pursue channel partnerships with Bengaluru and Hyderabad development centers serving global product teams. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive-focused design tool divisions within diversified engineering software conglomerates, where embedded validation capabilities face strategic neglect. Long-term viability over the next decade rests on vertical-specific certification layer dominance rather than raw canvas performance. Watch FDA human factors guidance enforcement intensity as inflection indicator for healthcare application tooling valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Embedded validation capabilities from Pidoco GmbH tier vendors capture automotive HUD certification revenue. |
| Platform Integration | Real-time collaboration engines merging with voice-to-code generation expand non-designer user bases. |
| Strategic Partnership | Hyperscaler alliances secure cloud substrate for browser-accessible diagnostic interface development. |
| Geographic Expansion | Localized UX validation centers in India serve PLI scheme electronics manufacturers. |
| Product Launch | Accessibility compliance modules addressing EU AI Act explainability mandates open recurring revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with design operations leads, IT procurement officers, platform engineers, and biomedical engineers developing surgical simulation interfaces; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie mobile platform data, and FDA human factors guidance documents. Bottom-up triangulation across deployment mode, end-user archetype, technology platform, and application vertical segments was cross-checked against top-down market sizing.
Across the analysis window, the forecasting framework modeled recurring revenue conversion rates from perpetual licenses, cloud infrastructure concentration effects, and regulatory compliance burden trajectories. Segmentation dimensions included deployment mode, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern. CAGRs were derived from elasticity modeling against IT software expenditure cycles and healthcare technology investment waves.
Forecasts assume regulatory continuity in EU AI Act implementation and FDA human factors guidance enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Fitness App Market
Software & Services
Customs Declaration Software Market
Software & Services
Global Decision Making Software Market
Software & Services
API Testing Market
Software & Services
Plant Design Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Courier Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Skills Management Software Market
Software & Services
Stock Footage Software Market
Software & Services
Architectural Rendering Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Global Recruiting Software Market