
 Ad Creation Software Market | 2026-2036
Ad Creation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ad Creation Software Market Insights
Enterprise-grade creative automation is reorganizing competitive dynamics in ad creation software. Adobe leverages deep integration across its creative cloud ecosystem to sustain premium positioning among professional users. Canva anchors the mid-market with template-driven accessibility, while Smartly.io specializes in dynamic creative optimization for paid social campaigns.
Ad creation software encompasses digital tools that generate, edit, and optimize advertising assets across formats including display banners, video commercials, and interactive rich media. These platforms incorporate rendering engines capable of real-time personalization at scale, serving brands and agencies seeking to reduce production cycles from weeks to hours. Cloud-based deployment models now lead structural growth as distributed creative teams require browser-native collaboration without local infrastructure. Video editing software represents the fastest-expanding product category, reflecting platform algorithm shifts favoring motion content. Template library features command disproportionate margin contribution through high-retention subscription tiers.
The Federal Trade Commission enforces truth-in-advertising standards that shape disclosure requirements for AI-generated promotional content in the United States. The EU AI Act imposes transparency obligations on automated creative systems deployed within European markets, affecting product architecture decisions. California's Consumer Privacy Act influences data governance for audience-targeted creative variants. Stakeholders must monitor evolving platform liability frameworks as generative capabilities blur authorship boundaries between human creators and algorithmic systems.
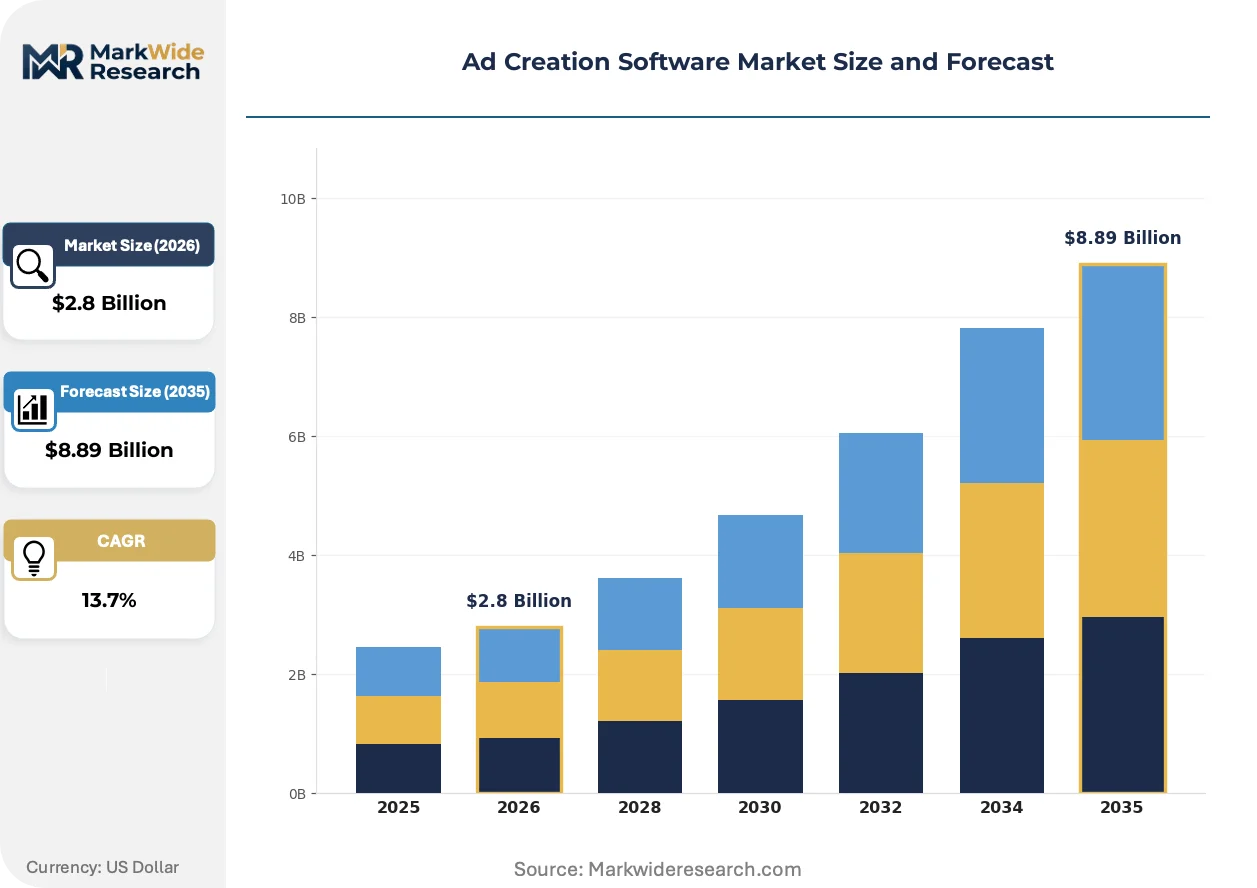
Market Dynamics
Generative AI diffusion is compressing creative production timelines from weeks to hours, forcing incumbent platforms to rearchitect around real-time rendering engines and automated asset variation pipelines.
Growth Catalysts
- EU AI Act transparency mandates:Automated disclosure requirements for AI-generated promotional content are accelerating investment in provenance-tracking infrastructure across European deployments.
- Small business self-service adoption:Template-driven platforms reduce creative agency dependency for retail, hospitality, and professional services advertisers seeking rapid campaign deployment.
- Video-first platform algorithms:Motion content prioritization by major social networks is driving demand for browser-native video editing tools with automated format adaptation.
Market Restraints
- Compute cost volatility:GPU-intensive generative rendering creates margin pressure for cloud-native platforms dependent on hyperscaler pricing.
- Training data licensing friction:Unclear intellectual property boundaries for commercially used generative models expose platforms to downstream liability risk.
- Cross-border data governance fragmentation:Divergent privacy requirements between California's Consumer Privacy Act and EU GDPR complicate audience-targeted creative variant deployment.
Strategic Opportunities
- India's PLI scheme for digital infrastructure:Localized cloud regions and reduced data sovereignty friction create entry pathways for mid-market creative automation vendors.
- Interactive rich media convergence:Integration of 3D rendering engines with commerce platforms enables shoppable ad units for direct-to-consumer verticals.
- Outcome-based creative pricing models:Performance-linked subscription tiers align vendor revenue with customer campaign effectiveness metrics.
Industry Challenges
- Prompt engineering talent scarcity:Shortage of specialists capable of optimizing generative model outputs for brand-compliant commercial assets.
- Legacy creative workflow integration:Established agencies face friction embedding automated tools into existing approval hierarchies and client relationship structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ad Creation Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphic Design Tool, Video Editing Software, Social Media Management, Copywriting Assistant End User: Small Businesses, Advertising Agencies, Freelancers, Corporates Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS Feature Set: Template Library, Collaboration Tools, Analytics Dashboard, Brand Management |
| Companies Covered | Adobe, Canva, Celtra, Smartly.io, The Trade Desk, Google, Meta Platforms, Amazon.com, Visme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ad Creation Software Market Trends and Innovations
Real-time personalization engines are redefining competitive differentiation, compressing the gap between creative conception and live deployment while fragmenting traditional agency-client relationships.
Diffusion-based image generation is supplanting template libraries as the primary asset creation method for mid-market advertisers. E-commerce and direct-to-consumer brands are adopting these tools at accelerating velocity, bypassing conventional design bottlenecks. This shift is compressing creative production costs and enabling hourly campaign refreshes previously requiring dedicated studio resources.
The EU AI Act's transparency obligations for automated creative systems are reshaping product architecture decisions across European deployments. Platform developers must now embed provenance metadata and human oversight checkpoints into generative workflows. Video advertising categories face the steepest compliance burden, with regulators scrutinizing deepfake-adjacent synthetic media applications most intensively.
Subscription unbundling is fragmenting how creative teams procure specialized tools. Mid-sized agencies are abandoning monolithic suites in favor of best-of-breed point solutions for specific formats—dedicated video editors, static asset generators, and dynamic optimization layers. This pattern is most pronounced in the United States, where procurement autonomy and cloud-native infrastructure reduce switching costs.
Ad Creation Software Market Segmentation
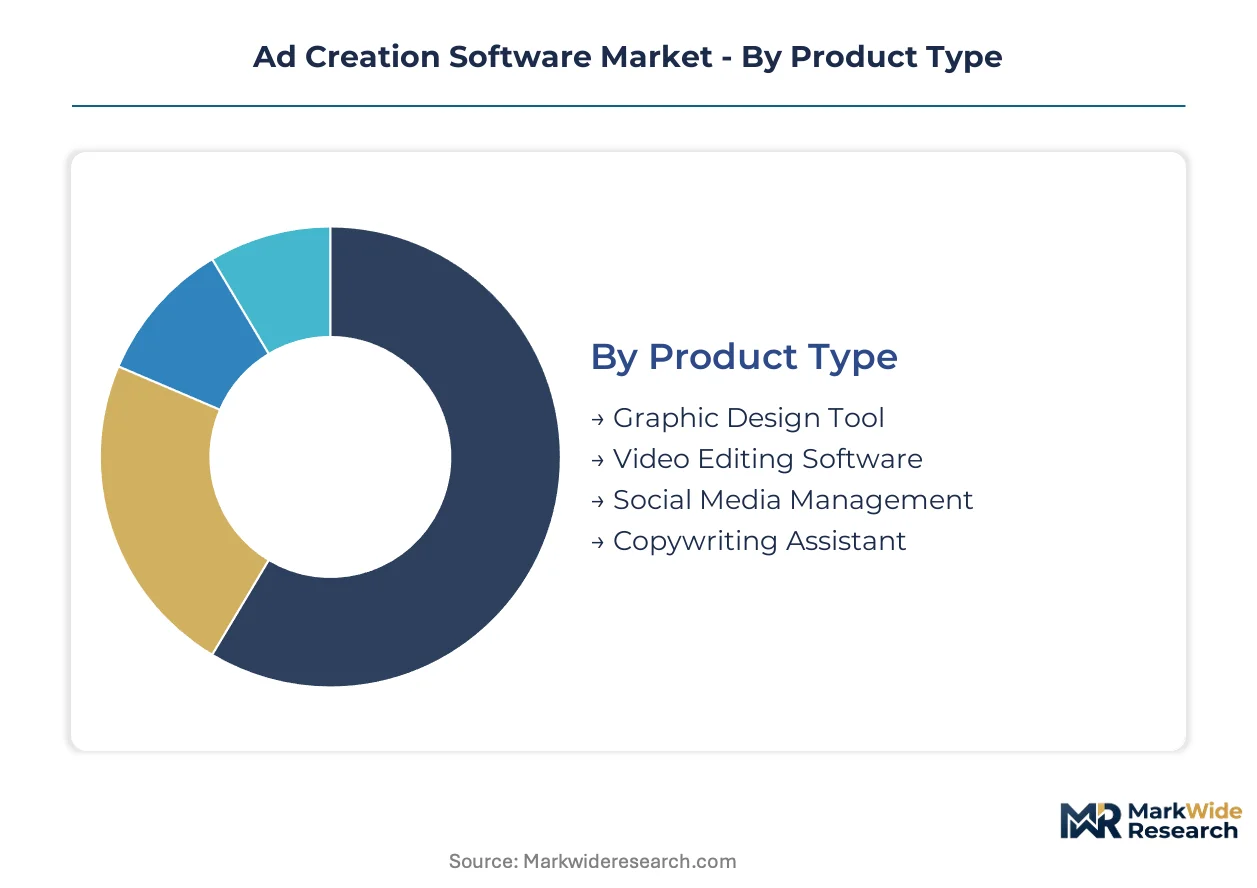
Segmentation in ad creation software reveals how production workflows fragment across technical capabilities and organizational maturity. Channel strategies differ sharply between self-serve template platforms and enterprise creative automation suites.
Product Type:
Channel-mix dynamics separate browser-native tools reaching small businesses through direct-to-customer routes from enterprise suites deployed via agency partnerships and systems integrators.
- Graphic Design Tool:Vector and raster editing engines power static asset creation for display advertising and social feed content. Demand clusters among retail and hospitality small businesses in the United States seeking rapid campaign turnaround without agency overhead. Template-driven subscription tiers dominate revenue contribution.
- Video Editing Software:Browser-native timeline editors with automated format adaptation serve motion-first platform algorithms. E-commerce and direct-to-consumer brands in California and New York deploy these tools for hourly creative refreshes previously requiring studio resources. GPU-intensive rendering creates margin pressure for cloud-native vendors.
- Social Media Management:Cross-platform scheduling and asset optimization tools streamline paid social workflows.
- Copywriting Assistant:Natural language generation modules produce promotional text variants for programmatic creative testing.
Graphic design tools dominate installed base. Video editing software is where expansion concentrates.
End User:
Cost-tier stratification separates freemium-ad-supported offerings for price-sensitive users from premium enterprise contracts with dedicated success management.
- Small Businesses:Self-serve platforms with template libraries reduce creative production from weeks to hours. Restaurant chains, dental practices, and local retailers in Texas and Florida adopt these tools for seasonal campaign deployment without agency retainers.
- Advertising Agencies:Multi-seat licenses with approval workflows and client-facing collaboration portals sustain higher average contract values. Creative shops in Los Angeles and Chicago embed automation into existing production pipelines.
- Freelancers:Individual subscriptions with project-based billing support gig-economy creative workers.
- Corporates:Enterprise-wide deployments with brand governance controls and API integrations serve Fortune 500 marketing operations.
Small businesses drive volume expansion. Advertising agencies sustain margin concentration.
Deployment Model:
Volume concentration in cloud-native delivery reflects distributed creative team requirements and hyperscaler infrastructure investments.
- Cloud-Based:Browser-native architectures enable real-time collaboration across distributed teams without local GPU investment. European deployments face EU AI Act compliance requirements for provenance tracking and human oversight checkpoints.
- On-Premises:Air-gapped installations serve financial services and healthcare advertisers with strict data residency requirements in Germany and Switzerland.
- Hybrid:Mixed deployments balance sensitive asset storage on local infrastructure with cloud-based rendering for compute-intensive generative tasks.
- SaaS:Multi-tenant subscription models with tiered feature gates dominate mid-market procurement patterns.
Cloud-based deployments dominate new customer acquisition. Hybrid architectures are climbing fastest among regulated verticals.
Feature Set:
Application-specific bundling determines switching costs and expansion revenue potential across creative workflows.
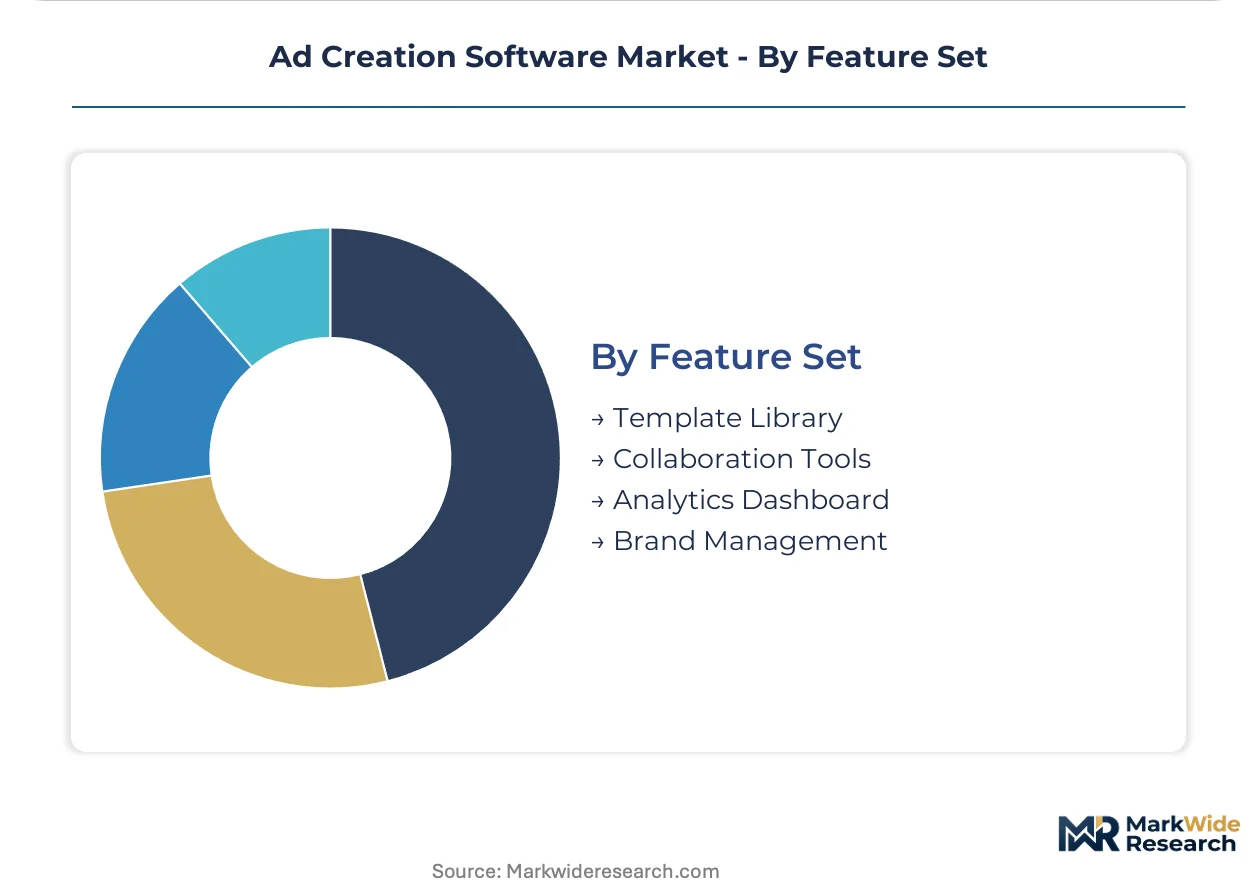
- Template Library:Pre-built asset collections with vertical-specific customization drive self-serve adoption and reduce time-to-first-campaign. High-retention subscription tiers command disproportionate margin contribution.
- Collaboration Tools:Comment threading, version control, and approval routing embed platforms into agency-client relationship structures. Real-time co-editing capabilities differentiate mid-market offerings.
- Analytics Dashboard:Creative performance attribution links asset variants to downstream conversion metrics.
- Brand Management:Asset governance controls enforce logo usage, color palette compliance, and typography standards across distributed teams.
Template libraries anchor customer acquisition. Brand management features are gaining share fastest in enterprise expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border software licensing flows heavily favor the United States as a net exporter of creative automation platforms, while import-dependent markets in Europe and Asia absorb these cloud-native tools under divergent compliance regimes. The EU AI Act and India's PLI scheme for digital infrastructure are reshaping where vendors localize rendering capacity versus ship from centralized hyperscaler regions.
United States
California and New York anchor platform development for video-first creative automation, with Los Angeles agencies driving enterprise adoption of browser-native editing tools. The FTC enforces truth-in-advertising standards that shape disclosure requirements for AI-generated promotional content. Seattle and San Francisco Bay Area clusters concentrate cloud infrastructure investments supporting real-time personalization engines.
Germany
Industrial marketing verticals in Bavaria and Baden-Württemberg demand on-premises creative suites with strict data residency controls for automotive and machinery advertisers. The EU AI Act imposes transparency obligations on automated creative systems, forcing provenance metadata embedding into generative workflows. Frankfurt's financial services sector drives hybrid deployment architectures balancing local storage with cloud rendering.
United Kingdom
London's advertising agency ecosystem sustains premium subscription tiers for multi-seat collaboration platforms with client-facing approval portals. The UK Information Commissioner's Office applies GDPR-aligned scrutiny to audience-targeted creative variant deployment. Manchester and Birmingham creative clusters are adopting self-serve template tools to reduce agency retainer dependency for mid-market brands.
India
Maharashtra and Karnataka small businesses are accelerating adoption of freemium graphic design platforms for retail and hospitality seasonal campaigns. The PLI scheme for digital infrastructure incentivizes localized cloud regions that reduce data sovereignty friction for mid-market vendors. Mumbai and Bangalore agency networks are embedding automated tools into existing production pipelines for e-commerce clients.
Japan
Tokyo's corporate marketing operations prioritize brand governance controls and API-integrated enterprise deployments for Fortune 500 advertising budgets. METI guidelines influence software procurement standards for creative automation in regulated industries. Osaka's manufacturing marketing teams are adopting template-driven platforms for rapid B2B campaign deployment without dedicated studio resources.
Ad Creation Software Market Competitive Landscape
Concentration sits with cloud-native platforms that have achieved escape velocity through template library scale and browser-native rendering infrastructure. The vendor base stratifies into three tiers: legacy creative suite incumbents with deep enterprise integration, mid-market accessibility platforms with freemium acquisition funnels, and specialized dynamic optimization tools for paid social workflows. M&A activity targets generative AI capabilities and regional compliance infrastructure, while strategic partnerships with hyperscalers secure preferential GPU pricing for real-time asset variation pipelines.
Within the enterprise integration tier, Adobe exemplifies ecosystem-lock-in strategies through creative cloud bundling. Canva occupies the mid-market accessibility position with template-driven self-serve adoption. Smartly.io represents the specialized optimization archetype for paid social campaign automation. These three anchors illustrate how competitive positioning fragments across technical sophistication, pricing accessibility, and channel-specific workflow depth.
| Leading Market Players |
|---|
| Adobe |
| Canva |
| Celtra |
| Smartly.io |
| The Trade Desk |
| Meta Platforms |
| Amazon.com |
| Visme |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler GPU capacity utilization rates above eighty percent compress margin buffers for cloud-native rendering vendors and establish price floors that self-serve platforms struggle to undercut without quality degradation. Adobe and Canva sustain premium positioning through captive infrastructure investments, while mid-market competitors face margin erosion from spot-priced compute dependencies.
Pricing Analysis
Enterprise buyers anchor subscription pricing through multi-year SaaS contracts with tiered feature gates separating creative teams by seat volume and rendering priority. Price differentiation hinges on API access depth and brand governance certification tiers, with FTC disclosure compliance for AI-generated assets commanding modest premiums. Pricing pressure intensifies as diffusion-based tools commoditize template libraries, eroding mid-market margins. Small businesses exhibit highest price sensitivity, while Fortune 500 marketing operations absorb premium tiers for dedicated success management.
Supply Chain Analysis
Just-in-time rendering capacity dominates procurement patterns, with vendors eschewing strategic stockpiles in favor of elastic hyperscaler contracts that scale with campaign volume spikes. Supply concentrates in United States, Ireland, and Singapore cloud regions where AWS, Azure, and GCP maintain dense GPU clusters. Raw material dependencies center on NVIDIA H100 accelerators, high-bandwidth memory modules, and proprietary training datasets licensed from stock photography archives. Single-source vulnerability to Taiwan Semiconductor Manufacturing for advanced logic chips threatens capacity expansion timelines. Distribution runs through direct-to-customer digital channels for self-serve tiers and agency systems integrators for enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prompt engineering proficiency scarcity constrains platform differentiation, with vendors competing for specialists capable of optimizing generative outputs for brand-compliant commercial assets. This capability gap separates incumbents with embedded talent pipelines from challengers dependent on contractor networks.
For Market Incumbents: Secure exclusive licensing arrangements with premium stock photography archives to differentiate training data provenance and reduce downstream IP liability exposure. Invest in backward integration into proprietary GPU clusters within India PLI-subsidized regions to escape hyperscaler pricing volatility. Defend against template-library commoditization by embedding real-time collaboration features into client approval workflows that increase switching costs. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Karnataka small business clusters where freemium acquisition costs remain below saturated North American markets. Target hospitality and retail verticals with seasonal campaign velocity needs underserved by agency-dependent incumbents. Pursue white-label partnerships with regional telecom operators bundling creative tools into small business software suites. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized dynamic optimization vendors over horizontal creative suites facing generative AI disruption. Long-term viability rests on provenance-tracking infrastructure investments ahead of EU AI Act enforcement expansion. Acquisition targets should demonstrate embedded workflow integrations with paid social platforms. The signal to watch is regulatory scrutiny intensity on synthetic media disclosures, which would accelerate consolidation toward compliance-ready platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Provenance Infrastructure Investment | EU AI Act transparency mandates require embedded metadata tracking for AI-generated assets deployed in European markets. |
| Hyperscaler Partnership Negotiation | Preferential GPU pricing agreements with AWS or Azure secure margin buffers against spot market volatility for rendering-intensive workloads. |
| Vertical Specialist Acquisition | Dynamic creative optimization capabilities for paid social campaigns command premium valuations as platform algorithms prioritize motion content. |
| India Cloud Region Localization | PLI scheme incentives reduce data sovereignty friction and establish cost-competitive rendering capacity for Asia-Pacific expansion. |
| Brand Governance Platform Integration | API connections with enterprise DAM systems embed vendor tools into Fortune 500 marketing operations with high switching costs. |
Research Methodology
Initial hypotheses were tested against primary input from creative operations directors, agency production heads, platform engineering leads, and brand compliance officers and refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, App Annie mobile adoption metrics, and EU regulatory implementation guidance. Bottom-up estimates of seat-level pricing and churn rates were triangulated against top-down market size assessments derived from digital advertising spend allocations.
Variance decomposition across the projection horizon isolates growth contributions from small business self-serve adoption, enterprise creative automation expansion, and video-first platform algorithm shifts. Segmentation modeling incorporates deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster dimensions. CAGRs were derived from logistic diffusion curves fitted to historical SaaS penetration patterns, with sensitivity testing against GPU cost trajectories and training data licensing friction scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained digital advertising spend growth and stable hyperscaler pricing; material deviation would warrant model refresh. Specific risks include EU AI Act enforcement intensity exceeding baseline scenarios, NVIDIA supply constraints extending GPU procurement timelines, and generative model IP litigation creating platform liability exposure. Revision becomes warranted when cloud rendering cost inflation crosses thresholds that compress mid-market vendor margins below sustainable operating levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Restaurant Management Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Lighting Control Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Web Scraping Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Architect Software Market
Software & Services
Asia-Pacific Text to Speech (TTS) Software Market
Software & Services
MCAD Software Market
Software & Services
India Sports Management Software Market