
 Europe Database Management Software Market | 2026-2036
Europe Database Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Database Management Software Market Analytics
Subscription-based financing and usage-based leasing is fragmenting competitive barriers in European database management, allowing mid-sized enterprises to access enterprise-grade capabilities without capital-intensive licensing. Oracle Corporation leverages its established relational database footprint across continental banking networks. SAP SE anchors its competitive position through deep integration with ERP workflows in German manufacturing. Snowflake Inc. differentiates via cloud-native architectures that appeal to asset-light fintech startups seeking elastic compute.
Database management software encompasses systems that organize, store, retrieve, and manipulate structured and unstructured data through SQL and NoSQL query engines, ACID compliance protocols, and distributed consensus algorithms such as Raft or Paxos for transaction integrity across nodes. Its primary purpose is to ensure data availability, consistency, and security for mission-critical business operations. Relational database deployments still occupy the largest revenue share among European enterprises with legacy mainframe dependencies, while cloud database adoption is accelerating fastest among retail and digital-native sectors seeking elastic scaling. Hybrid cloud configurations are emerging as the dominant deployment architecture where data sovereignty requirements under GDPR restrict pure public cloud migration for sensitive records.
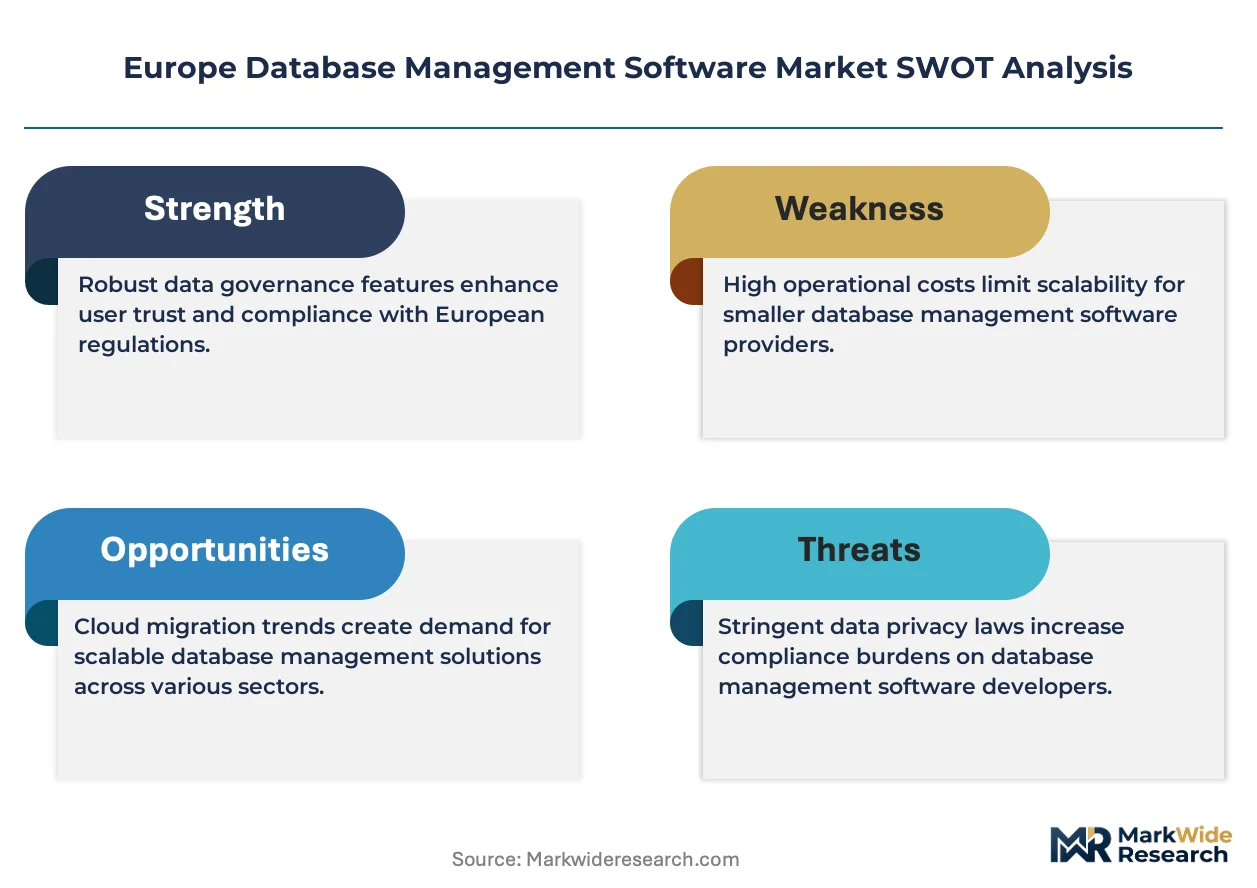
The EU AI Act and GDPR impose strict requirements on data provenance, auditability, and cross-border transfer mechanisms, compelling vendors to embed governance tooling directly into database platforms. EMA guidelines for pharmaceutical data integrity and ESMA rules on financial record retention further shape product roadmaps for healthcare and BFSI deployments. Stakeholders must evaluate how forthcoming EU cybersecurity certification schemes for cloud services will alter procurement criteria and vendor qualification timelines.
Market Dynamics
GDPR data sovereignty mandates and the EU AI Act are forcing European enterprises toward hybrid database architectures that keep sensitive records on-premises while bursting analytics workloads to cloud infrastructure.
Growth Catalysts
- GDPR Article 44-49 cross-border transfer restrictions:Enterprises must maintain EU-resident data copies, driving demand for geo-distributed database clusters with automated residency tagging.
- Automotive data lakes:German OEMs are consolidating vehicle telemetry, supply chain, and manufacturing quality data into unified lakehouse architectures.
- Real-time payment infrastructure:The European Central Bank's TARGET Instant Payment Settlement system requires sub-second transaction consistency across distributed SQL nodes.
Market Restraints
- Specialized SRE talent scarcity:Distributed systems engineers with Raft/Paxos consensus expertise command premium compensation in Frankfurt and Amsterdam tech corridors.
- Cloud egress cost volatility:Cross-availability-zone data replication for high-availability configurations consumes unpredictable bandwidth budgets.
- Legacy mainframe COBOL dependencies:French and Italian banking networks retain critical transaction logic on IBM zSystems, constraining migration velocity.
Strategic Opportunities
- Polish and Romanian enterprise digitization:EU cohesion fund subsidies are financing first-generation ERP deployments in manufacturing SMEs previously reliant on spreadsheets.
- Edge-to-cloud data pipelines:Convergence of 5G MEC infrastructure with serverless query engines enables predictive maintenance for Nordic wind farm operators.
- CSRD sustainability reporting mandates:Environmental data traceability requirements are creating new product categories for carbon-accounting-integrated database platforms.
Industry Challenges
- Schema migration complexity:Decades of accumulated stored procedures and trigger logic in Oracle and SQL Server estates resist automated refactoring tools.
- EMA pharmaceutical data integrity audits:ALCOA+ compliance for clinical trial databases demands immutable audit trails with cryptographic verification, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Database Management Software Market |
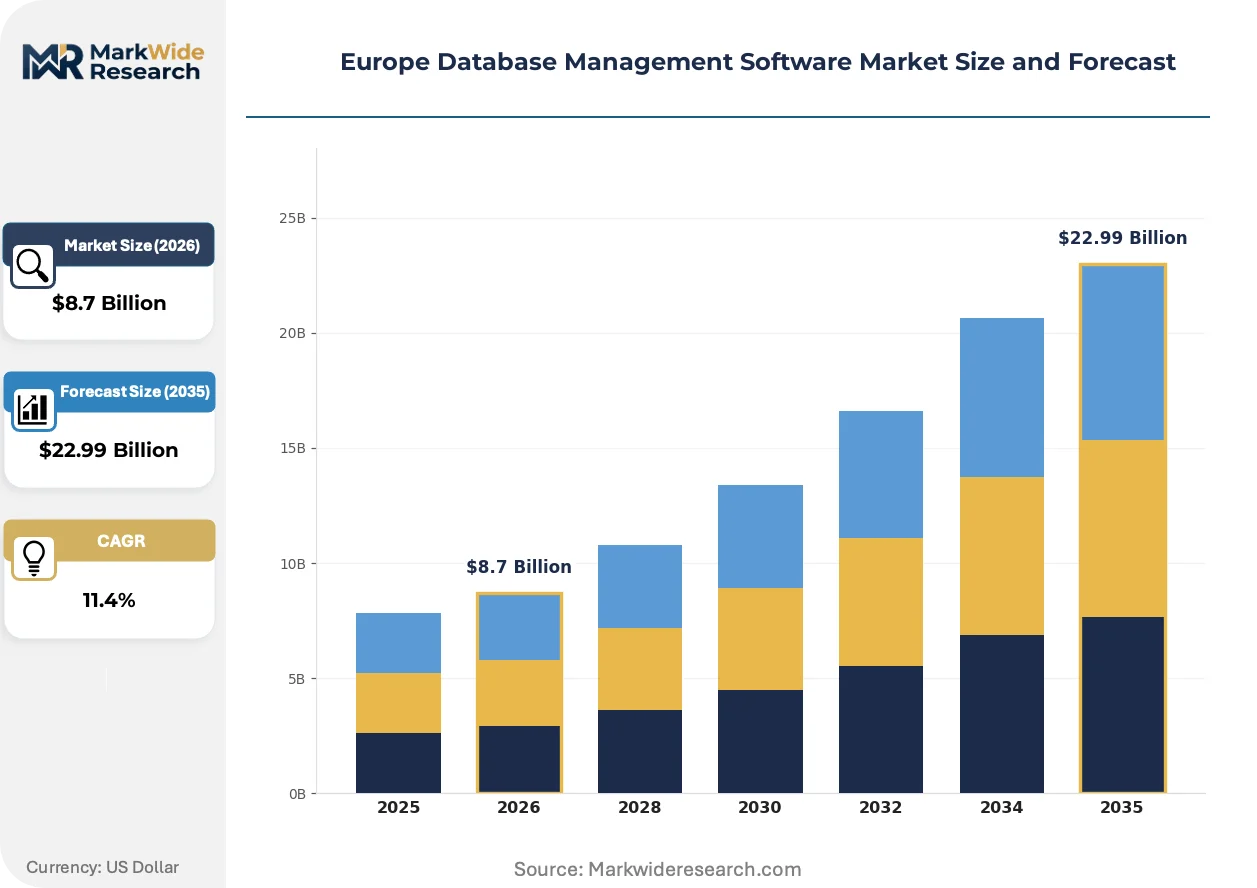
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relational Database, NoSQL Database, Cloud Database, In-Memory Database Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud End User: Healthcare, BFSI, Retail, Education Application: Data Analytics, Transaction Processing, Backup & Recovery, Reporting |
| Companies Covered | Oracle Corporation, IBM Corporation, SAP SE, Microsoft Corporation, Amazon Web Services, Snowflake Inc., Informatica Inc., Teradata Corporation, Atos, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Database Management Software Market Evolving Landscape
Database architectures are fragmenting into specialized engines optimized for specific workload patterns rather than monolithic platforms serving all use cases.
Vector database extensions are hybridizing with traditional relational engines to support retrieval-augmented generation workloads. Pharmaceutical researchers at EMA-regulated institutions are deploying these hybrid systems for adverse event signal detection. The structural consequence is compression of the standalone vector database category as incumbents embed similarity search directly into existing query optimizers.
EU AI Act risk classification tiers are mandating deterministic query explainability for high-risk AI training data pipelines. Financial services firms in Paris and Milan must now maintain complete provenance records for model training datasets. Healthcare AI developers are responding by adopting immutable ledger-backed database schemas that satisfy both GDPR rectification rights and audit immutability requirements.
Consumption-based pricing models are displacing perpetual licensing for mid-market deployments. Dutch and Belgian software resellers are unbundling professional services from core platform fees. This shift is most visible among asset-light fintech startups in Lisbon and Barcelona that prefer operational expenditure alignment with transaction volume fluctuations.
Europe Database Management Software Market Segmentation
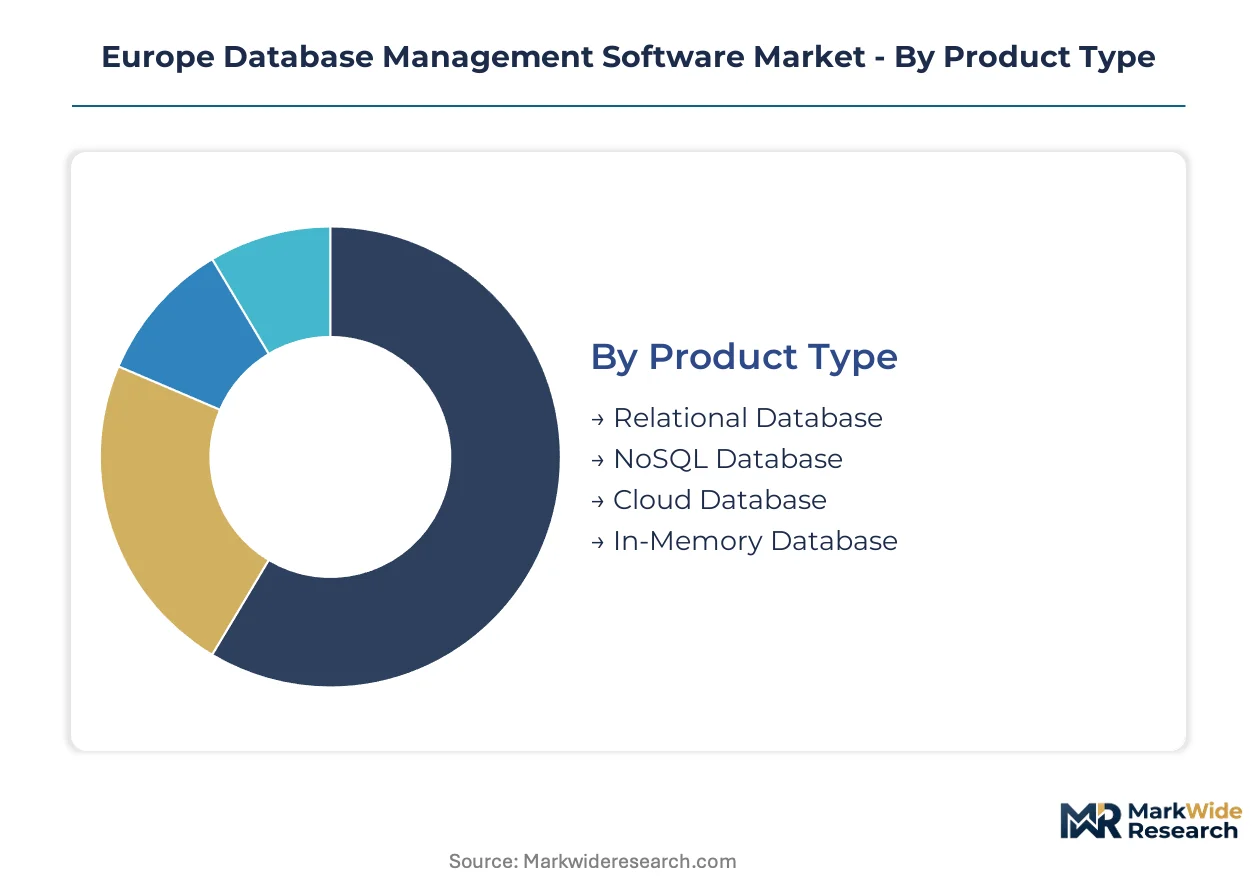
Database management software segments diverge sharply across Europe based on data sovereignty mandates, legacy infrastructure depth, and workload elasticity requirements. Procurement patterns in Frankfurt, Paris, and Amsterdam reveal distinct preferences for deployment architectures and query engine types.
Product Type:
European enterprises span mission-critical transaction systems to experimental AI pipelines, driving heterogeneous engine procurement.
- Relational Database:ACID-compliant SQL engines with mature stored procedure ecosystems dominate French and Italian banking networks where COBOL mainframe dependencies constrain migration velocity. German automotive suppliers rely on these systems for supply chain traceability under CSRD sustainability reporting mandates.
- NoSQL Database:Document and wide-column stores handle unstructured vehicle telemetry streams from German OEM data lakes, offering schema flexibility for evolving sensor formats. EMA-regulated pharmaceutical researchers deploy these for adverse event signal detection where rigid relational schemas impede iterative analysis.
- Cloud Database:Managed PostgreSQL and MySQL services attract Dutch and Belgian fintech startups seeking operational expenditure alignment with transaction fluctuations.
- In-Memory Database:SAP HANA deployments accelerate real-time inventory optimization for Nordic retail distribution networks.
Established volume favors relational systems; emerging adoption favors cloud-native engines.
Deployment Model:
GDPR Article 44-49 cross-border restrictions and EU AI Act auditability requirements shape infrastructure location decisions.
- On-Premises:Sovereign data centers in Frankfurt and Paris retain sensitive financial records where GDPR restricts public cloud residency. French banking networks maintain IBM zSystem estates for transaction logic that resists containerization.
- Public Cloud:AWS RDS and Azure SQL Database capture Spanish and Portuguese digital-native retailers with elastic scaling requirements and limited legacy baggage.
- Private Cloud:OpenStack-based deployments serve Polish and Romanian manufacturing SMEs receiving EU cohesion fund subsidies for first-generation ERP modernization.
- Hybrid Cloud:Sensitive records remain on-premises while analytics workloads burst to cloud infrastructure, emerging as the dominant architecture where data sovereignty intersects with compute elasticity needs.
Regulatory pressure sustains on-premises footprints; cost optimization accelerates hybrid configurations.
End User:
Sector-specific compliance regimes create divergent vendor qualification timelines and feature requirements.
- Healthcare:EMA ALCOA+ compliance for clinical trial databases demands immutable audit trails with cryptographic verification, extending validation timelines for PostgreSQL and Oracle deployments at research hospitals in Basel and Copenhagen.
- BFSI:The European Central Bank's TARGET Instant Payment Settlement system drives sub-second transaction consistency requirements across distributed SQL nodes in Frankfurt and Milan trading floors.
- Retail:Nordic omnichannel operators prioritize in-memory analytics for real-time inventory positioning across 5G-enabled edge locations.
- Education:Dutch and Belgian universities deploy open-source PostgreSQL clusters for research data management under constrained public sector budgets.
Financial services concentrate premium spending; healthcare extends procurement cycles.
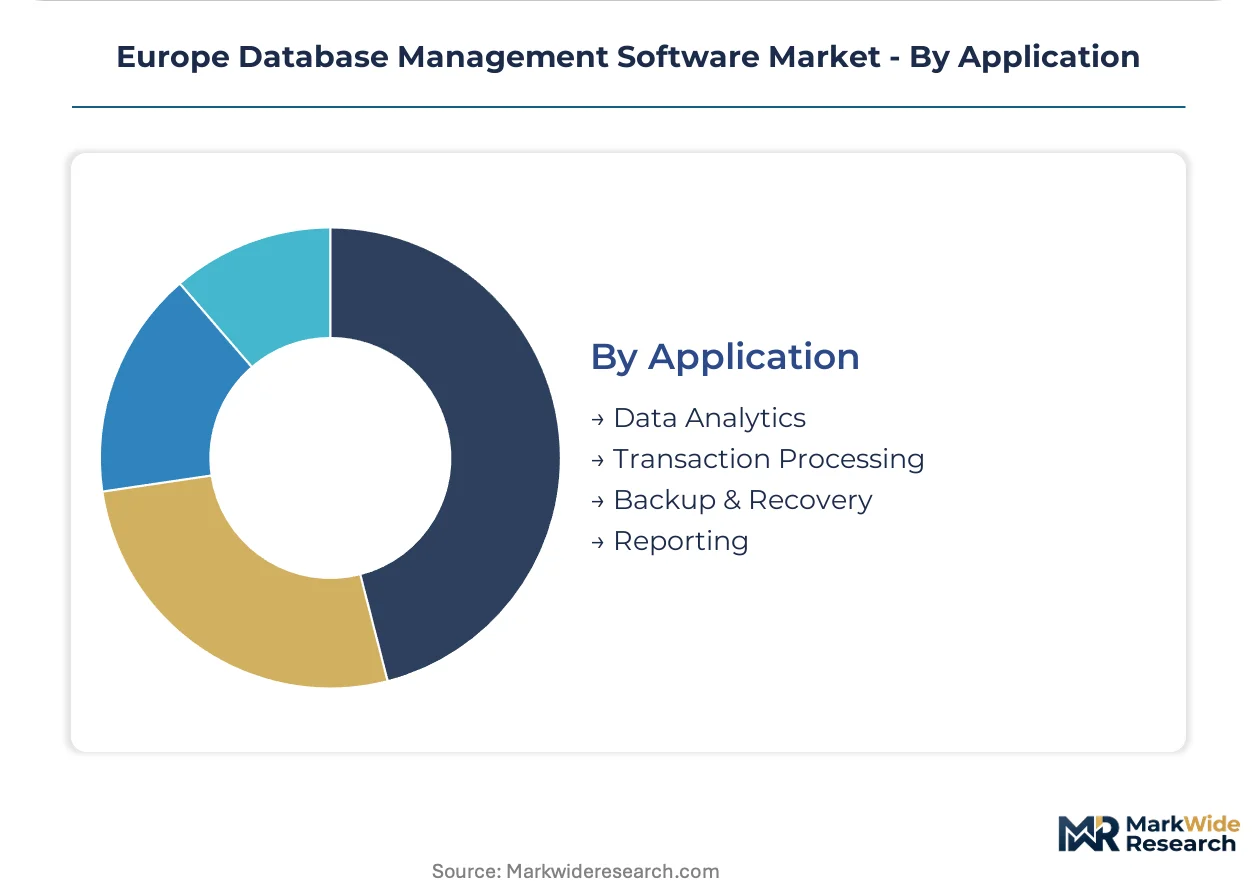
Application:
Workload patterns determine engine selection more than organizational size or sector affiliation.
- Data Analytics:Lakehouse architectures consolidating German automotive telemetry, supply chain, and manufacturing quality data require vector database extensions for retrieval-augmented generation workloads.
- Transaction Processing:Raft and Paxos consensus protocols ensure distributed consistency for real-time payment infrastructure across Frankfurt and Amsterdam clearinghouses.
- Backup & Recovery:Immutable ledger-backed schemas satisfy GDPR rectification rights while preserving audit immutability for healthcare AI training pipelines in Paris and Milan.
- Reporting:Carbon-accounting-integrated platforms emerge under CSRD mandates, embedding environmental data traceability directly into database governance tooling.
Operational workloads anchor relational procurement; analytical expansion drives specialized engine adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU cohesion fund disbursements and national digitization programs are redistributing database procurement across the continent, with regulatory compliance requirements under GDPR and the EU AI Act shaping infrastructure location decisions for sensitive data workloads.
Germany
Industrial digitization subsidies under the Industrie 4.0 framework accelerate ERP modernization across Mittelstand manufacturers. The KBA mandates telemetry data retention for connected vehicles, compelling automotive suppliers to deploy lakehouse architectures. Stuttgart and Munich clusters concentrate SAP HANA deployments for real-time supply chain optimization.
France
CNIL enforcement actions against cross-border data transfers push financial institutions toward sovereign cloud configurations. The ANSM requires ALCOA+ compliance for clinical trial databases, extending validation timelines for research hospitals. Paris banking networks retain IBM zSystem estates while piloting hybrid burst architectures for analytics workloads.
United Kingdom
FCA operational resilience rules mandate sub-second recovery objectives for payment infrastructure, driving distributed SQL adoption. The UK AI Act white paper influences procurement criteria for explainable data pipelines. London fintech clusters favor cloud-native PostgreSQL services with consumption-based pricing models.
Netherlands
Dutch central bank DNB guidelines on cloud outsourcing compel financial institutions to maintain on-premises audit trails. Research data management requirements at Wageningen and Delft universities drive open-source cluster deployments. Amsterdam trading floors prioritize in-memory analytics for real-time risk positioning.
Poland
EU cohesion fund subsidies finance first-generation ERP deployments in manufacturing SMEs previously dependent on spreadsheets. The Polish Financial Supervision Authority mandates data localization for payment service providers. Warsaw and Krakow tech corridors attract distributed systems engineering talent for database administration roles.
Europe Database Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architecture segments. The vendor base organizes into three tiers: legacy relational incumbents with mainframe integration depth, cloud-native challengers with elastic compute positioning, and vertical specialists with sector-specific compliance tooling. Strategic moves concentrate on hybrid cloud partnerships and consumption-based pricing model transitions.
Among established relational database providers, Oracle Corporation and IBM Corporation exemplify the integration-heavy archetype with decades of European banking network penetration. SAP SE occupies a distinct position through ERP workflow anchoring in German manufacturing verticals. Snowflake Inc. represents the cloud-native challenger model with asset-light fintech appeal.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Amazon Web Services |
| Snowflake Inc. |
| Informatica Inc. |
| Teradata Corporation |
| Atos |
| Others |
Value Network & Pricing Analysis
Cloud hyperscaler concentration in Ireland and the Netherlands concentrates infrastructure procurement leverage, pushing margin pools toward specialized compliance tooling vendors who embed GDPR and EU AI Act governance directly into database platforms. German automotive OEMs and French banking networks absorb premium pricing for sovereign data residency guarantees, while Polish and Romanian manufacturing SMEs finance deployments through EU cohesion fund subsidies that compress visible price points.
Pricing Analysis
Certification level for EMA ALCOA+ and ESMA audit trail compliance creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with consumption-based SaaS models displacing perpetual licensing among Dutch and Belgian fintech startups. Pricing pressure stems from open-source PostgreSQL and MySQL alternatives eroding base-tier relational database margins. Asset-light digital-native retailers in Spain and Portugal exhibit highest price sensitivity; EMA-regulated pharmaceutical researchers in Basel and Copenhagen demonstrate lowest sensitivity due to validation timeline costs.
Supply Chain Analysis
Upstream silicon and memory module feedstock draws from Taiwan, South Korea, and USA fabrication facilities. Database software distribution runs through hyperscaler marketplaces, systems integrator channel partners, and direct enterprise sales teams. Raw material dependencies span advanced node semiconductors, high-bandwidth memory stacks, and specialized networking ASICs for distributed consensus protocols. Single-source vulnerability concentrates in Taiwan-based foundry capacity for performance-optimized database appliances. French and Italian banking networks retain IBM zSystem mainframe dependencies that constrain supply chain flexibility for legacy migration workloads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GDPR Article 44-49 cross-border restrictions and EU AI Act risk classification tiers fragment procurement criteria, creating specialized vendor niches around compliance-embedded database platforms. Sovereign cloud configurations and edge-to-cloud data pipelines represent the most penetrable entry vectors for differentiated positioning.
For Market Incumbents: Insulate core banking network relationships through deeper ERP workflow integration and preemptive certification investment for forthcoming EU cybersecurity certification schemes. Oracle and SAP should anchor defensive positioning by embedding immutable ledger-backed audit trails directly into existing relational engines before cloud-native challengers capture EMA-regulated pharmaceutical workloads. Vertical integration into sovereign cloud infrastructure partnerships preserves margin pools against hyperscaler commoditization pressure. For New Entrants and Emerging Players: Mid-market manufacturing SMEs in Poland and Romania receiving EU cohesion fund subsidies represent the most penetrable entry point for first-generation ERP database deployments. Nordic wind farm operators building edge-to-cloud predictive maintenance pipelines offer a second white-space target with limited incumbent saturation. Go-to-market execution should route through Dutch and Belgian software resellers unbundling professional services from platform fees to align with consumption-based buyer preferences. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical specialists holding EMA ALCOA+ compliance tooling for clinical trial databases. Long-term viability hinges on regulatory moat durability rather than pure technology differentiation. Acquisition screening should prioritize targets with embedded governance features satisfying both GDPR rectification rights and EU AI Act auditability mandates. The signal to watch is enforcement action velocity from CNIL and other national data protection authorities accelerating procurement cycle urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Partnership Formation | Combines on-premises sovereignty with burst analytics for German automotive data lakes. |
| Consumption-Based Pricing Transition | Aligns vendor revenue with transaction volume fluctuations at Lisbon and Barcelona fintechs. |
| EMA Compliance Tooling Acquisition | Captures pharmaceutical validation timeline premiums at Basel and Copenhagen research hospitals. |
| Edge-to-Cloud Pipeline Development | Enables predictive maintenance workloads for Nordic wind farm operators via 5G MEC integration. |
| Sovereign Cloud Infrastructure Investment | Satisfies CNIL enforcement actions against cross-border transfers in Paris banking networks. |
Research Methodology
Cross-validation between primary interviews and regulatory filing analysis anchors the qualitative findings. Database procurement officers, distributed systems engineers, and compliance officers at EMA-regulated institutions provided operational perspective. Secondary sources encompassed ESMA rulemaking documents, ECB payment infrastructure specifications, and hyperscaler capex disclosures. Bottom-up deployment sizing across German automotive clusters and French banking networks triangulated against top-down market aggregation.
Calibration against historical adoption curves for cloud database migration shaped the projection framework. Segmentation dimensions spanned deployment model, organization size, vertical compliance intensity, and regional regulatory cluster. CAGR derivation rested on elasticity modeling for consumption-based pricing penetration and mainframe modernization velocity inputs. Analysis window spans across the analysis window with sensitivity testing for EU AI Act implementation timeline variations.
Practitioners should monitor enforcement velocity from national data protection authorities and EU cybersecurity certification scheme finalization for early signals. Forecasts reflect documented assumptions regarding cohesion fund disbursement continuity and mainframe COBOL talent availability. Cross-checking against ECB payment infrastructure upgrade announcements and KBA connected vehicle telemetry mandates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
House Cleaning App Market
Software & Services
Course Authoring Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
SMS Marketing Software Market
Software & Services
ITSM Market
Software & Services
Digital Sculpture Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Batch Management Software Market
Software & Services
Cemetery Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Data Extraction Software Market
Software & Services
India Software Services Export Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Global Call Center Software Market
Software & Services
Open Stack Service Market
Software & Services
Discount Management Software Market