
 Global Healthcare Contract Management Software Market | 2026-2036
Global Healthcare Contract Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Contract Management Software Market Foresight
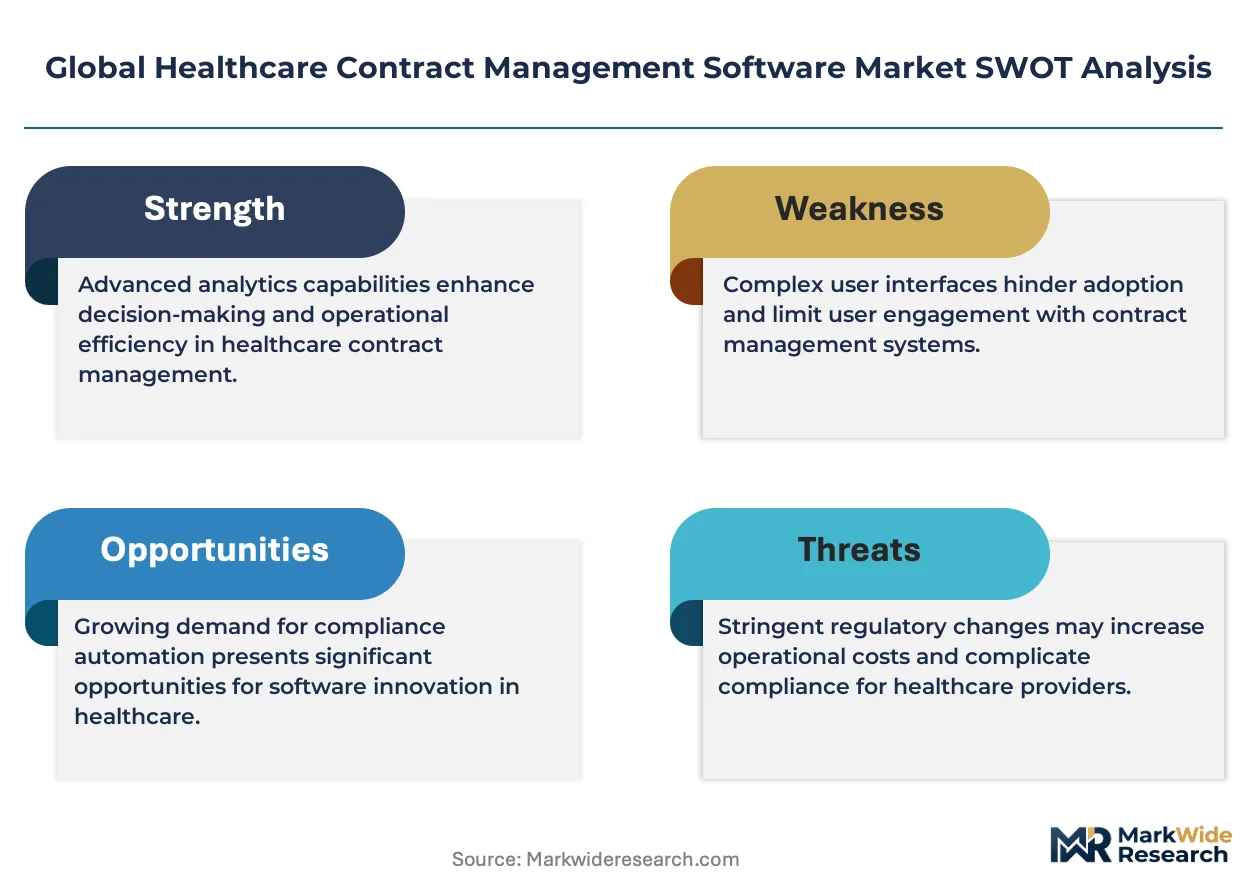
Modular bundling of contract lifecycle management with risk assessment and audit management tools is expanding buyer choice across healthcare delivery networks. Icertis leverages deep configuration capabilities for enterprise hospital systems. CobbleStone Software anchors its position through specialized regulatory compliance modules. Optum Inc. competes by integrating contract management with existing payer-provider workflows.
Healthcare contract management software comprises digital platforms that automate drafting, negotiation, execution, and monitoring of agreements between providers, payers, vendors, and regulators, typically incorporating AI-driven clause extraction, e-signature protocols, and real-time compliance dashboards. Cloud-based solutions lead product type adoption as hospitals prioritize remote accessibility and reduced IT infrastructure overhead, while contract lifecycle management captures the largest application share due to its centrality in reducing administrative drag across multi-party agreements. SaaS platforms represent the fastest-growing deployment architecture as subscription models lower capital barriers for mid-sized clinics and diagnostic laboratories.
FDA oversight of healthcare data integrity and HIPAA privacy requirements shape product development roadmaps for vendors serving US providers, while EMA's Medical Device Regulation and GDPR data handling standards govern European deployment architectures. Japan's PMDA and METI jointly influence contract transparency mandates for pharmaceutical supply agreements. Stakeholders must monitor evolving AI governance frameworks as automated contract analysis tools attract heightened regulatory scrutiny across multiple jurisdictions.
Market Dynamics
HIPAA enforcement escalation and FDA data integrity mandates are forcing hospital networks to replace fragmented contract repositories with unified compliance architectures. Cloud-native platforms now dominate procurement evaluations as IT departments eliminate on-premise infrastructure maintenance.
Growth Catalysts
- HIPAA audit frequency:OCR enforcement actions against covered entities rose sharply, compelling health systems to deploy automated compliance monitoring within contract lifecycle platforms.
- Multi-site hospital consolidation:Integrated delivery networks spanning dozens of facilities require centralized contract visibility, driving enterprise-wide software procurement decisions.
- AI clause extraction:Natural language processing tools now parse regulatory language in pharmaceutical and medical device agreements, reducing legal review cycles.
Market Restraints
- Implementation complexity:Legacy ERP integration with SAP or Oracle systems demands specialized technical expertise, extending deployment timelines.
- Data residency requirements:GDPR Article 44 restrictions on cross-border data transfers constrain cloud hosting architectures for European hospital networks.
- Subscription cost accumulation:Per-user SaaS pricing models create budget pressure for mid-sized diagnostic laboratories with fluctuating staff levels.
Strategic Opportunities
- India's hospital digitization:CDSCO regulatory harmonization with ICH standards creates demand for contract management platforms supporting international clinical trial agreements.
- Payer-provider convergence:Vertical integration between insurers and delivery networks requires unified contract repositories spanning reimbursement and care delivery terms.
- EMA Medical Device Regulation:MDR Article 10 technical documentation mandates drive European medical device manufacturers toward automated supplier contract tracking.
Industry Challenges
- Interoperability fragmentation:FHIR standard implementation varies across EHR vendors, complicating API connections between contract platforms and patient data systems.
- Compliance certification timelines:HITRUST CSF validation processes extend 12-18 months, delaying product launches for emerging software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Contract Management Software Market |
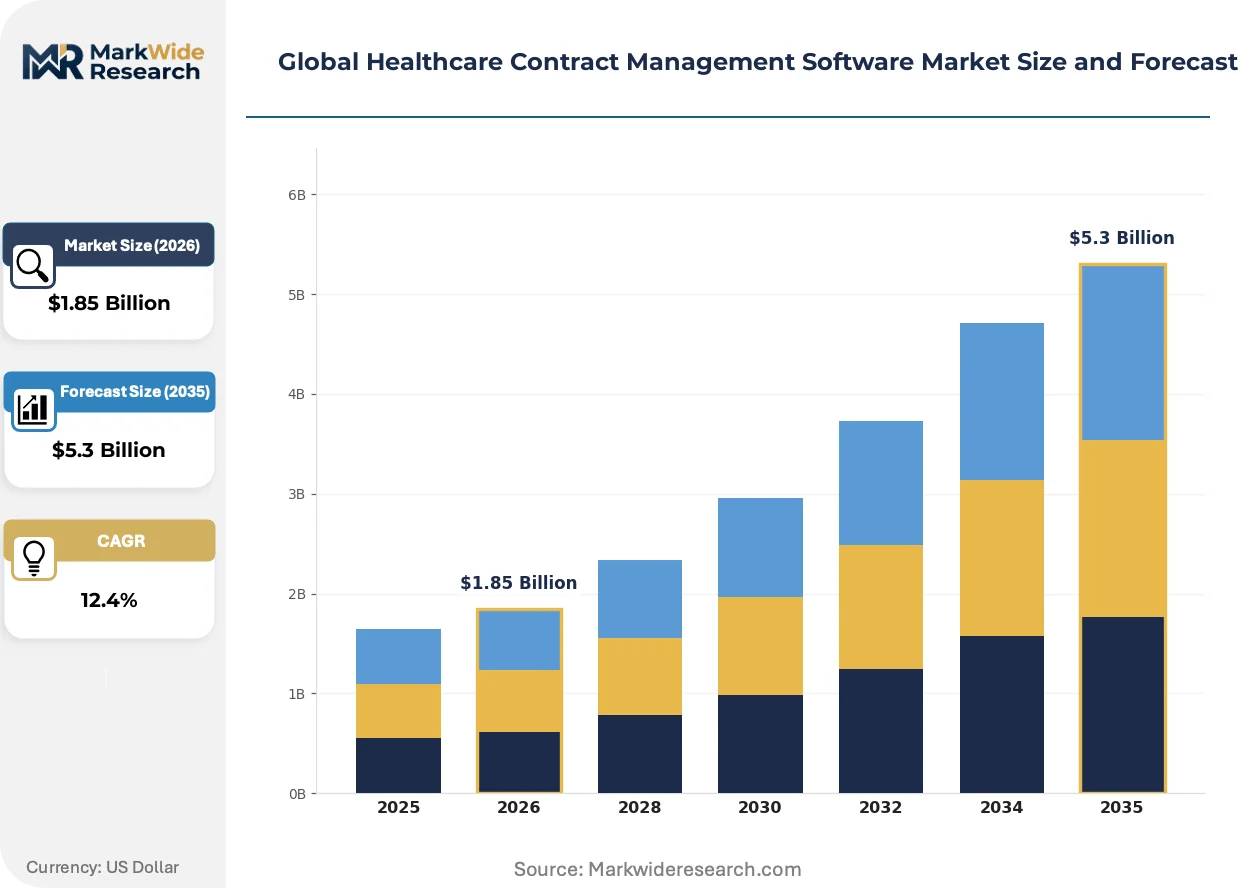
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Software, Hybrid Systems, SaaS Platforms Application: Regulatory Compliance, Contract Lifecycle Management, Risk Assessment, Audit Management, Vendor Management End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Deployment Model: Public Cloud, Private Cloud, Community Cloud, Hosted Services |
| Companies Covered | Icertis, CobbleStone Software, Optum Inc., Experian Plc, Concord, Coupa Software Inc., Contract Logix LLC, Apttus Corporation, Determine Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Contract Management Software Market Shifts & Advancements
Generative AI capabilities are compressing contract drafting cycles while regulatory automation tools embed jurisdiction-specific compliance checks directly into workflow engines. Vendors now compete on configuration depth rather than feature breadth.
Natural language generation is integrating clause libraries with real-time regulatory databases, enabling dynamic contract drafting that reflects current FDA guidance documents. Large health systems in California and Texas are piloting these tools for clinical trial agreements. The technology is integrating previously siloed legal and procurement functions into unified operational workflows.
EMA's Medical Device Regulation imposes unique device identification traceability requirements that cascade into supplier contract terms. European manufacturers must maintain technical documentation links across entire supply chains. German and French medical device firms are restructuring vendor agreements to embed automated UDI compliance verification.
Hospital procurement departments now demand consumption-based pricing models that align software costs with actual contract transaction volumes. Traditional seat-based subscriptions face displacement in favor of outcome-tied arrangements. This pattern is most visible among diagnostic laboratory networks in the United States seeking to match variable caseloads with technology spend.
Global Healthcare Contract Management Software Market Segmentation
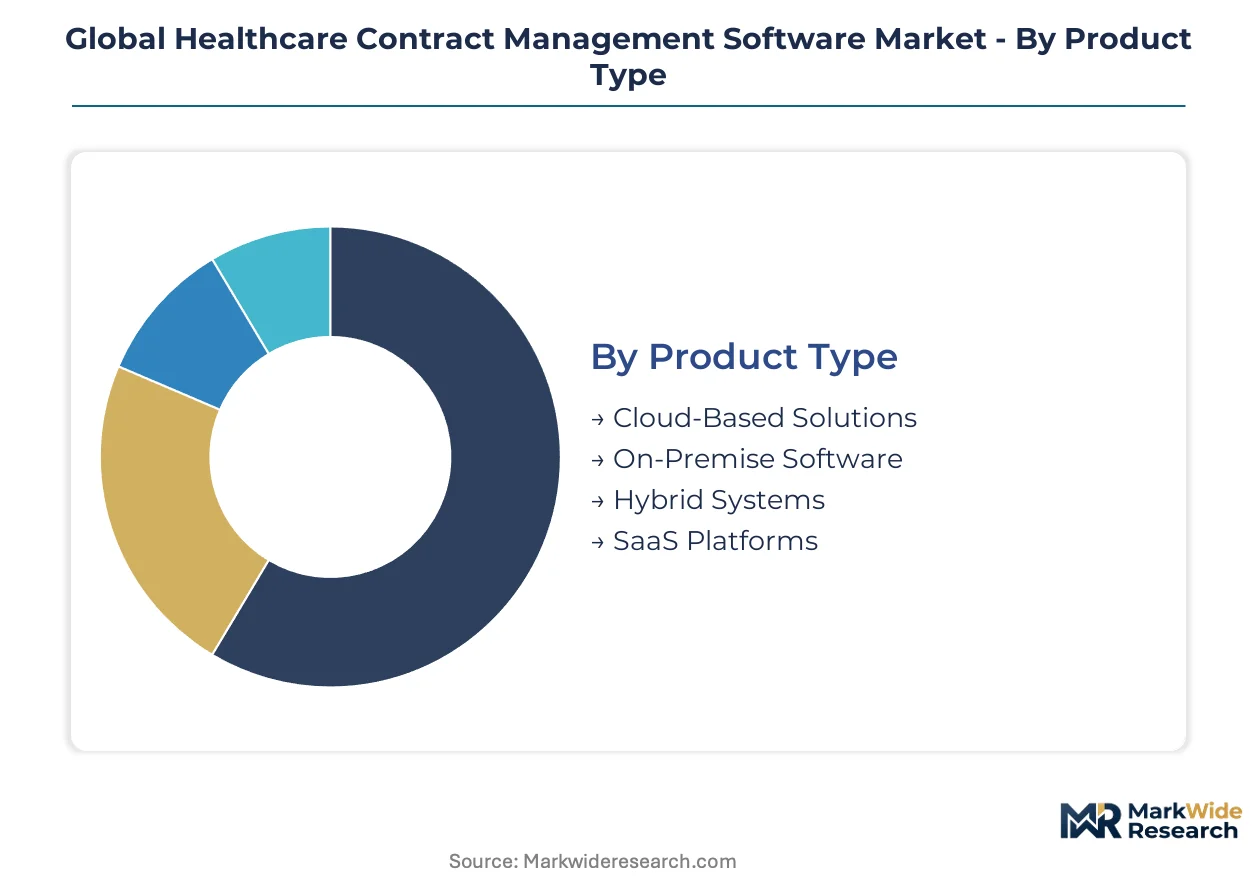
Healthcare contract management software segments reflect divergent IT infrastructure maturity across provider networks. Procurement patterns split between risk-averse institutions favoring controlled environments and agile organizations prioritizing scalability.
Product Type:
Standardization dominates at the infrastructure layer while configuration depth differentiates competitive positioning at the application tier.
- Cloud-Based Solutions:Multi-tenant architectures deliver remote accessibility across distributed hospital networks. United States health systems lead procurement volumes as HIPAA compliance automation becomes non-negotiable for OCR audit readiness.
- SaaS Platforms:Subscription pricing models eliminate capital expenditure barriers for mid-sized diagnostic laboratories. Germany's hospital digitization initiatives accelerate deployment as EMA regulatory complexity demands frequent software updates without on-premise maintenance windows.
- On-Premise Software:Legacy installations persist in Japanese academic medical centers with stringent data sovereignty requirements under METI guidelines.
- Hybrid Systems:Split architectures accommodate pharmaceutical companies navigating cross-border clinical trial data flows under divergent national privacy frameworks.
Most installed capacity flows through Cloud-Based Solutions. Expansion is steepest in SaaS Platforms.
Application:
Functional modules align with organizational risk tolerance and regulatory exposure severity.
- Contract Lifecycle Management:End-to-end automation spans drafting through renewal across multi-party agreements. Integrated delivery networks spanning dozens of facilities require centralized visibility, driving enterprise procurement consolidation.
- Regulatory Compliance:Embedded FDA and EMA rule engines reduce legal review cycles for pharmaceutical supply agreements. European medical device manufacturers deploy these tools to automate MDR Article 10 technical documentation tracking.
- Risk Assessment:Predictive analytics modules quantify counterparty exposure in vendor agreements.
- Audit Management:Workflow engines streamline OCR and HITRUST certification evidence collection.
- Vendor Management:Supplier performance dashboards integrate contract terms with procurement KPIs.
Contract Lifecycle Management commands the largest deployment base. Regulatory Compliance is gaining share fastest as enforcement intensifies.
End User:
Buyer sophistication scales with organizational complexity and regulatory surface area.
- Hospitals:Enterprise-grade platforms manage thousands of active agreements across supply chain, employment, and payer contracts. Multi-site consolidation in Texas and California creates demand for unified repositories spanning dozens of facilities.
- Pharmaceutical Companies:Global contract portfolios require jurisdiction-specific clause libraries and automated regulatory update propagation. CDSCO harmonization with ICH standards in India drives platform adoption for international clinical trial agreements.
- Clinics:Smaller footprint solutions prioritize e-signature integration and basic compliance dashboards.
- Diagnostic Laboratories:Consumption-based pricing models align software costs with variable caseloads.
- Research Institutes:Grant management and intellectual property terms demand specialized workflow configurations.
Hospitals represent the dominant installed base. Pharmaceutical Companies show the steepest expansion trajectory.
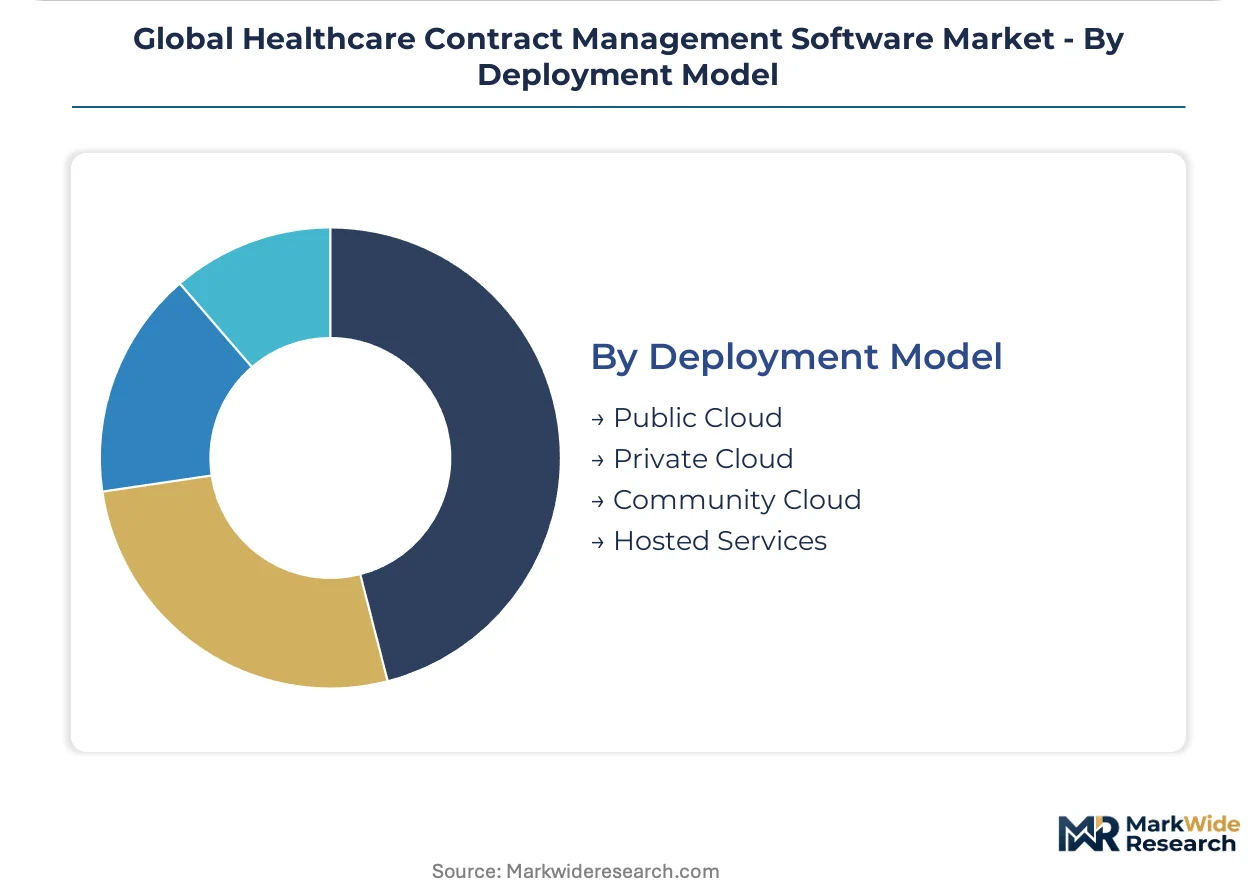
Deployment Model:
Architecture choices reflect data sensitivity classifications and cross-border operational requirements.
- Public Cloud:Shared infrastructure delivers cost efficiency for non-sensitive administrative contracts. United States community hospital networks favor this model for vendor and facilities agreements without protected health information exposure.
- Private Cloud:Dedicated environments satisfy GDPR Article 44 data residency constraints for European hospital networks. German and French providers mandate these deployments for agreements containing patient-identifiable terms.
- Community Cloud:Collaborative platforms serve regional health information exchanges and integrated delivery network consortia.
- Hosted Services:Managed single-tenant deployments bridge legacy system integration requirements.
Private Cloud carries the largest committed capacity. Public Cloud is climbing the fastest as security certifications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare contract management software originated in the United States during the early 2000s as hospital networks sought digital alternatives to paper-based agreement repositories. The industry's expansion followed HIPAA enforcement patterns, spreading first to Germany and Japan as data protection regulations tightened. Today, procurement concentrates in markets with complex multi-payer healthcare financing and stringent audit requirements.
United States
Hospital consolidation across Texas and California drives enterprise platform procurement as integrated delivery networks seek unified contract visibility. OCR enforcement actions against covered entities compel health systems to deploy automated compliance monitoring. The Dallas-Fort Worth metroplex anchors significant vendor deployment activity for multi-site hospital networks.
Germany
Hospital digitization initiatives accelerate SaaS adoption as EMA regulatory complexity demands frequent software updates. GDPR Article 44 data residency constraints mandate private cloud deployments for agreements containing patient-identifiable terms. Baden-Württemberg's medical device manufacturing cluster restructures supplier agreements to embed automated UDI compliance verification.
Japan
Academic medical centers with stringent data sovereignty requirements under METI guidelines maintain legacy on-premise installations. PMDA and METI jointly influence contract transparency mandates for pharmaceutical supply agreements. Tokyo's hospital networks pilot hybrid architectures balancing regulatory compliance with remote accessibility needs.
India
CDSCO regulatory harmonization with ICH standards creates demand for platforms supporting international clinical trial agreements. Hospital digitization programs in Maharashtra and Karnataka prioritize cloud-based solutions with consumption-based pricing. Mumbai's pharmaceutical headquarters drive adoption for global contract portfolio management spanning jurisdiction-specific clause libraries.
United Kingdom
NHS procurement frameworks emphasize interoperability with existing electronic health record systems. GDPR compliance requirements shape cloud hosting decisions for hospital trusts managing cross-border research agreements. London's concentration of pharmaceutical headquarters sustains demand for regulatory automation tools embedding EMA rule engines.
Global Healthcare Contract Management Software Market Competitive Landscape
The competitive structure tilts toward configuration specialists rather than horizontal platform providers. Enterprise hospital systems demand deep customization capabilities for multi-party agreement workflows, while mid-sized diagnostic laboratories prioritize rapid deployment over feature breadth. Two strategic archetypes dominate: regulatory compliance module specialists and payer-provider workflow integrators. M&A activity concentrates on AI clause extraction capabilities, while strategic partnerships target EHR vendor interoperability certification.
Within the configuration-specialist tier, Icertis and CobbleStone Software exemplify divergent approaches to enterprise penetration. Icertis occupies a position emphasizing deep configuration capabilities for complex hospital system deployments. CobbleStone Software anchors the regulatory compliance archetype through specialized module development. Optum Inc. sits within the payer-provider convergence vector, leveraging existing workflow relationships to expand contract management adoption.
| Leading Market Players |
|---|
| Icertis |
| CobbleStone Software |
| Optum Inc. |
| Experian Plc |
| Concord |
| Coupa Software Inc. |
| Contract Logix LLC |
| Apttus Corporation |
| Determine Inc. |
| Others |
Supply & Pricing Matrix
Horizontal integration of AI clause extraction capabilities with legacy ERP systems anchors both supply positioning and pricing power for healthcare contract management vendors. Cloud-native platform providers in the United States and Germany leverage this integration depth to command premium positioning against modular competitors.
Pricing Analysis
Consumption-based pricing models calibrated to contract transaction volumes are displacing per-user SaaS subscriptions across diagnostic laboratory networks. Price differentiation hinges on HITRUST CSF certification tier and embedded regulatory engine sophistication for FDA and EMA compliance automation. Pricing pressure stems from mid-sized clinics demanding outcome-tied arrangements that match variable caseloads with technology spend. Hospitals with enterprise-grade compliance requirements show the least price sensitivity, while independent diagnostic laboratories exhibit the highest.
Supply Chain Analysis
Domestic-content mandates for data residency under GDPR Article 44 and Japan's METI guidelines are reshaping sourcing toward regional cloud infrastructure providers. Software development concentrates in the United States, Germany, and India, with AI training data and regulatory rule engines as critical inputs. Supply chain risk centers on single-source vulnerability for specialized HIPAA compliance modules. Distribution runs through direct enterprise sales teams and certified EHR vendor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in healthcare contract management software rests on automation-driven cost compression in legal review cycles and the shift toward premium-tier regulatory compliance bundles.
For Market Incumbents: Lock in hospital network relationships through HITRUST CSF certification investments that extend deployment switching costs. Deepen configuration capabilities for multi-site integrated delivery networks facing OCR audit pressure. Acquire AI clause extraction specialists to defend against modular entrants attacking the mid-market. For New Entrants and Emerging Players: Cloud-native deployment routes offer the fastest path to penetration in India's hospital digitization programs and European mid-tier diagnostic laboratories. Target consumption-based pricing segments where incumbent seat-based models create budget friction. Pursue CDSCO harmonization positioning for international clinical trial agreement workflows. For Investors and Strategic Acquirers: Roll-up economics work for regulatory compliance module specialists because EMA MDR and FDA data integrity mandates are fragmenting buyer procurement across specialized vendors. Five-to-ten year viability favors platforms with embedded AI governance capabilities. Watch AI regulatory framework developments across multiple jurisdictions as the inflection signal for compliance automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| HITRUST CSF Certification Investment | OCR enforcement escalation makes automated compliance monitoring non-negotiable for hospital procurement. |
| AI Clause Extraction Acquisition | Natural language processing capabilities compress legal review cycles for pharmaceutical supply agreements. |
| Consumption-Based Pricing Launch | Diagnostic laboratories in Texas and California demand cost alignment with variable contract transaction volumes. |
| EHR Vendor Partnership | FHIR interoperability certification unlocks procurement access through existing hospital IT procurement channels. |
| EMA MDR Compliance Module Development | European medical device manufacturers require automated UDI traceability across supplier contract terms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement officers, health system legal directors, GPO contracts managers, and software vendor product strategists with secondary validation against SEC filings, hospital procurement databases, CMS Medicare reimbursement data, and GPO contract repositories. Bottom-up facility-level deployment estimates and top-down vendor revenue analysis provided triangulation anchors.
Historical reference periods anchored the projection horizon across the 2026-2035 window, with segmentation modeling across deployment architecture, organization size tier, application module, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating HIPAA enforcement trajectory, hospital consolidation patterns, and AI governance framework development timelines. Forecast inputs included OCR audit frequency projections and EMA MDR implementation pace assumptions.
The model assumes a particular technology adoption path; alternative pathways for generative AI contract drafting would alter the outlook. Forecasts reflect documented assumptions about regulatory enforcement intensity and cloud security certification maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Talent Management Software Market
Software & Services
Application Virtualization Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Strategy Management Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Lead Mining Software Market
Software & Services
Global Intranet Software Market
Software & Services
System Infrastructure Software Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Referral Marketing Software Market
Software & Services
Subscription Management Software Market