
 Retail Cybersecurity Market | 2026-2036
Retail Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Cybersecurity Market Outlook
Platform bundling is consolidating buyer choice around unified threat management suites that merge firewall, endpoint detection, and encryption into single procurement contracts. Fortinet leverages its integrated security fabric to dominate mid-market retail deployments across North America. Palo Alto Networks competes through cloud-native architecture that simplifies hybrid infrastructure protection for multi-location chains. CrowdStrike sustains momentum with endpoint-centric models that reduce agent complexity on point-of-sale systems.
Retail cybersecurity encompasses the technologies, services, and protocols that protect transaction data, customer records, and operational continuity across physical and digital retail channels, typically integrating real-time threat detection with encryption standards such as AES-256 and TLS 1.3 for data in transit and at rest. Its primary commercial purpose centers on preventing revenue loss from breaches while preserving consumer trust in payment ecosystems. Deployment mode represents the most structurally consequential segment dimension, with cloud-based solutions capturing the fastest expansion as retailers abandon capital-intensive on-premises hardware refresh cycles. Solution type reveals a mature firewall category where margin pools have compressed, while managed detection and response services command premium pricing due to acute analyst talent scarcity.
PCI DSS, state-level consumer privacy statutes such as CCPA, and sector-specific FTC enforcement actions collectively elevate baseline security spending for any retailer processing card transactions. NIST cybersecurity framework adoption among Fortune 500 retailers further hardens procurement specifications that vendors must satisfy for enterprise eligibility. Stakeholders should monitor how quantum-resistant encryption standards reshape product roadmaps and whether managed security service providers can scale analyst capacity fast enough to capture the mid-market opportunity.
Market Dynamics
Cloud migration among retailers is compressing deployment timelines and collapsing traditional hardware refresh cycles into subscription-based consumption models that prioritize operational agility over capital ownership.
Growth Catalysts
- PCI DSS 4.0 mandates:The updated standard's enhanced authentication requirements are compelling merchants to upgrade point-of-sale encryption infrastructure ahead of enforcement deadlines.
- E-commerce transaction volumes:Digital payment surges across omnichannel retail networks are expanding attack surfaces and necessitating real-time fraud detection investments.
- United States state privacy laws:CCPA and its legislative progeny in Virginia, Colorado, and Connecticut are creating compliance-driven procurement cycles for customer data protection tools.
Market Restraints
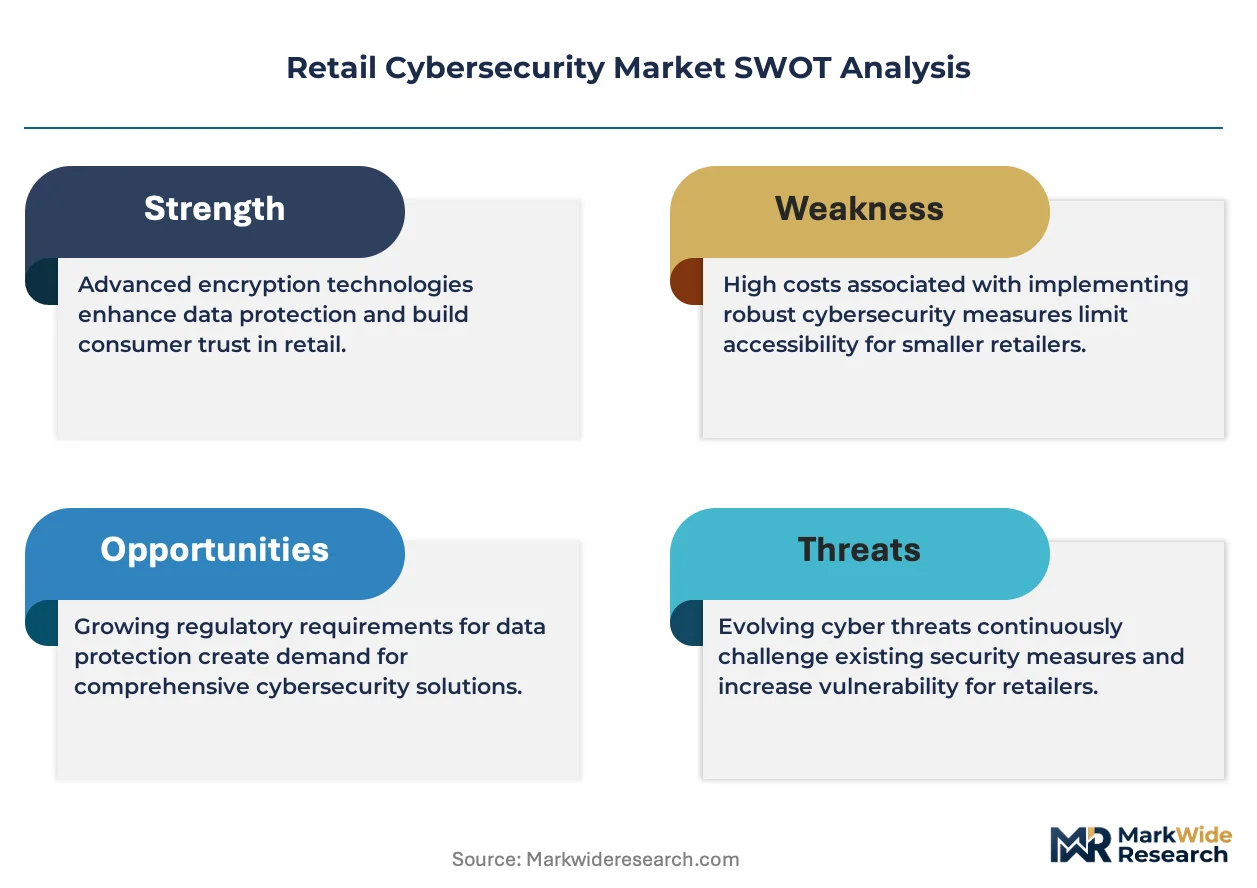
- Analyst talent scarcity:Managed detection and response services face capacity constraints as qualified security operations center personnel remain concentrated in high-cost metropolitan labor markets.
- Legacy POS hardware:Decade-old terminal estates in mid-market grocery and convenience chains resist firmware updates required for modern encryption protocols.
- Cloud concentration risk:Retail infrastructure migrations into hyperscaler environments create single-point-of-failure dependencies on AWS, Azure, and Google Cloud security postures.
Strategic Opportunities
- Quantum-resistant encryption:NIST's post-quantum cryptographic standards are opening product roadmaps for vendors capable of delivering lattice-based algorithm implementations.
- India retail digitization:UPI payment proliferation and ONDC network expansion are generating first-mover advantages for cybersecurity providers establishing local data center presence.
- Zero-trust architecture convergence:Microsegmentation and identity-aware networking are merging into unified platforms that reduce agent sprawl on distributed store endpoints.
Industry Challenges
- POS system integration complexity:Fragmented terminal vendor ecosystems force retailers to maintain multiple agent types and API connectors across heterogeneous store footprints.
- Third-party vendor risk:Supply chain compromises through compromised software updates require continuous monitoring of logistics, loyalty, and payment processor security postures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Cybersecurity Market |
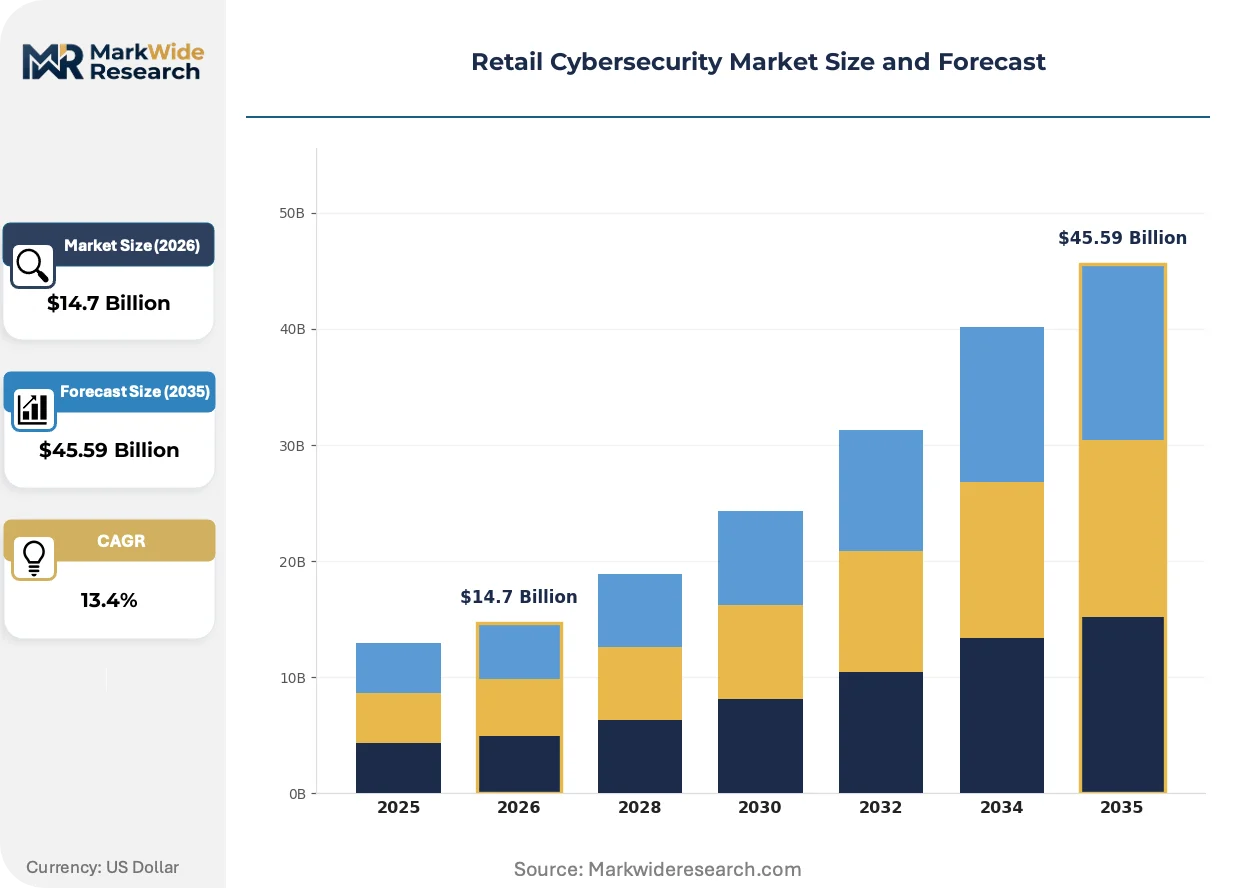
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $45.59 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Firewall, Intrusion Detection System, Antivirus, Encryption End User: Department Stores, E-commerce, Supermarkets, Specialty Retailers Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Service Type: Consulting, Implementation, Support & Maintenance, Training |
| Companies Covered | Fortinet, Check Point, CrowdStrike, McAfee, Proofpoint, Palo Alto Networks, Zscaler, Deepwatch, Microsoft Security, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Cybersecurity Market Strategic Shifts
Security fabric architectures are consolidating previously discrete functions into unified control planes that reduce operational overhead for resource-constrained retail IT organizations managing distributed store networks.
Extended detection and response platforms are rewriting how mid-market retailers approach threat visibility by correlating endpoint, network, and identity signals into single-pane-of-glass consoles that eliminate swivel-chair analysis. Department store chains with limited security staff are adopting these consolidated tools faster than independent boutiques. The technology is compressing vendor consolidation timelines as procurement teams abandon best-of-breed point solutions for integrated suites.
The European Union's Digital Operational Resilience Act is mandating stringent ICT risk management frameworks for payment service providers and their retail merchant clients. DORA's incident reporting requirements and third-party risk management provisions are elevating baseline security spending across the continental retail sector. Cross-border e-commerce platforms serving EU consumers are restructuring supplier contracts to ensure compliance with the act's January 2025 applicability date.
Retailers are consolidating vendor relationships around outcome-based service level agreements that tie payment to measurable breach prevention metrics rather than tool deployment counts. This procurement evolution is displacing traditional perpetual license models in favor of consumption-aligned contracts. Grocery chains in Germany and France are pioneering these arrangements with managed security service providers, establishing templates for continental adoption.
Retail Cybersecurity Market Segmentation
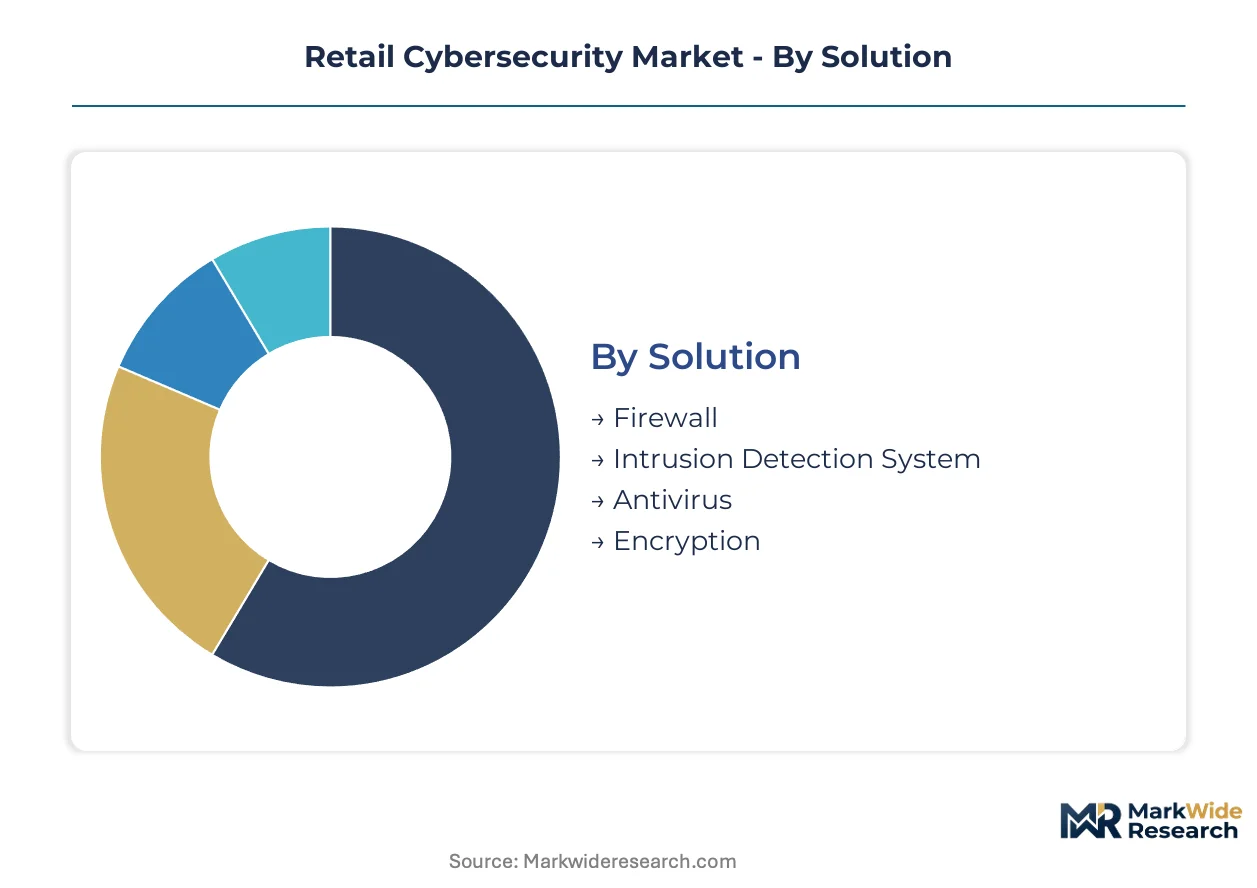
Retail cybersecurity procurement splits sharply between volume-driven commodity solutions and premium-priced managed services. Understanding where margin pools concentrate versus where transaction volumes flow determines vendor resource allocation and partnership strategy.
Solution:
Firewall and encryption solutions command premium pricing through compliance mandates, while antivirus and intrusion detection face commoditization pressure from bundled platform offerings.
- Firewall:Network perimeter appliances and next-generation firewalls enforce traffic segmentation between POS systems, back-office servers, and external payment gateways. Demand concentrates among mid-market grocery chains replacing decade-old stateful inspection hardware to meet PCI DSS 4.0 requirements. Margin compression intensifies as Fortinet and Palo Alto Networks bundle firewall functions into broader security fabrics.
- Encryption:AES-256 and TLS 1.3 implementations protect cardholder data in transit and at rest across distributed store networks. E-commerce platforms and omnichannel retailers drive fastest expansion as tokenization requirements expand beyond physical terminals to mobile wallets and buy-online-pickup-in-store workflows.
- Intrusion Detection System:Signature and behavioral monitoring tools identify anomalous traffic patterns across retail WANs.
- Antivirus:Endpoint protection agents guard POS terminals and back-office workstations against malware payloads.
Today's leader: Encryption. Tomorrow's challenger: Next-generation firewall platforms with integrated threat intelligence.
End User:
Customer scale and transaction velocity create divergent security requirements between high-frequency physical retail and digital-native commerce.
- E-commerce:Pure-play digital retailers and omnichannel platforms require web application firewalls, bot management, and real-time fraud detection at cloud scale. United States-based marketplace operators and direct-to-consumer brands drive fastest expansion as checkout flow security becomes a conversion rate optimization factor.
- Department Stores:Large-format retailers with complex loyalty programs and multi-brand portfolios face expanded attack surfaces from fragmented legacy systems. Procurement concentrates on unified threat management suites that reduce agent sprawl across heterogeneous store footprints.
- Supermarkets:High-volume, low-margin grocery operators prioritize cost-efficient endpoint protection for thousands of identical POS terminals.
- Specialty Retailers:Niche apparel, electronics, and home goods chains with limited IT staff favor outsourced security operations.
E-commerce platforms absorb the steepest expansion trajectory. Department stores represent the largest addressable wallet for integrated platform vendors.
Deployment:
Capital ownership preferences and internal technical capabilities determine whether retailers build, rent, or fully outsource security infrastructure.
- Cloud-Based:Subscription-delivered security services eliminate hardware refresh cycles and scale elastically with transaction volumes. United States multi-location chains migrating from legacy data centers to AWS and Azure environments drive fastest adoption as operational agility outweighs long-term cost concerns.
- Managed Services:Outsourced security operations centers monitor threats, patch systems, and respond to incidents on retailer behalf. Mid-market specialty retailers with no dedicated security staff concentrate demand here, though analyst talent scarcity constrains provider scaling.
- On-Premises:Customer-owned appliances and software licenses persist among retailers with strict data residency requirements or legacy integration dependencies.
- Hybrid:Split architectures combine cloud-delivered analytics with on-premises enforcement at store locations.
Cloud-based deployment claims current revenue leadership. Managed services present the structural opportunity as talent gaps widen.
Service Type:
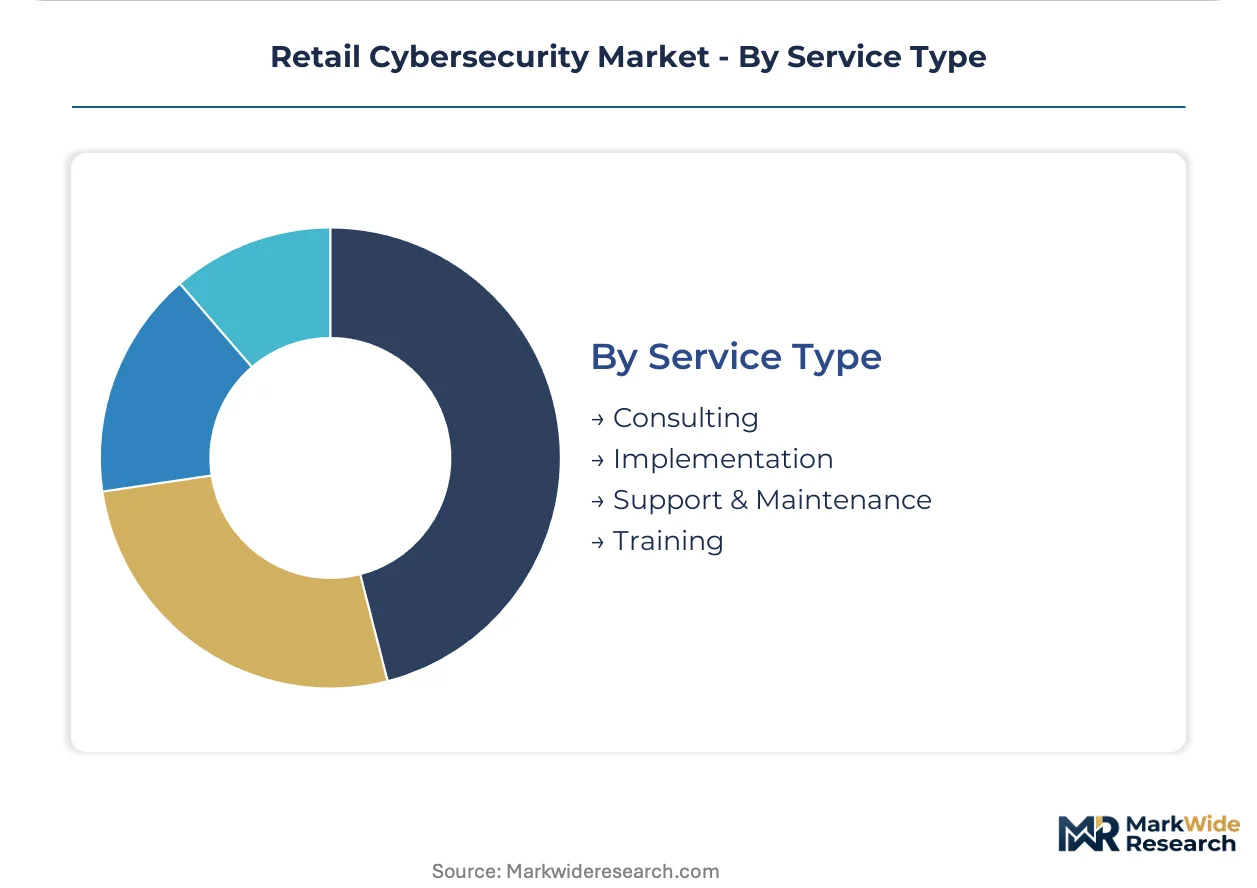
Professional services revenue tracks solution complexity and compliance audit frequency across retail verticals.
- Implementation:System integration, migration, and deployment services accompany new security technology adoption. E-commerce platform launches and PCI DSS remediation projects concentrate United States demand as retailers face enforcement deadline pressure.
- Consulting:Risk assessments, architecture design, and compliance readiness reviews guide procurement decisions. Fortune 500 retailers adopting NIST cybersecurity frameworks drive premium pricing for specialized advisory.
- Support & Maintenance:Ongoing technical assistance, patch management, and hardware replacement services.
- Training:Security awareness programs and certification preparation for retail IT staff.
Implementation services dominate current bookings. Consulting engagements represent the fastest-climbing margin pool as compliance complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The retail cybersecurity industry traces its commercial origins to United States payment card networks and Silicon Valley infrastructure providers that established encryption standards for early e-commerce platforms in the late 1990s.
United States
California-based e-commerce platforms and Texas-headquartered cloud infrastructure providers drive sustained demand for web application firewalls and bot management systems. State-level statutes including California's CCPA and Virginia's CDPA mandate customer data protection investments that accelerate procurement cycles. The New York financial services corridor concentrates managed security service providers serving Fortune 500 retailers with complex omnichannel footprints.
Germany
Automotive retail networks and grocery conglomerates with dense franchise operations require unified threat management across thousands of identical endpoints. The European Union's Digital Operational Resilience Act imposes stringent ICT risk frameworks on payment service providers and their merchant clients. The Rhine-Ruhr industrial belt hosts cybersecurity consultancies specializing in PCI DSS remediation for mid-market department store chains.
United Kingdom
London-centered fintech-retail hybrids and heritage department stores with legacy loyalty systems expand attack surfaces demanding microsegmentation solutions. The UK Information Commissioner's Office enforces GDPR-aligned penalties that elevate baseline security spending. The Cambridge technology cluster incubates quantum-resistant encryption startups targeting post-NIST standardization opportunities.
India
Unified Payments Interface proliferation and Open Network for Digital Commerce expansion generate first-mover demand for localized data center security architectures. The Reserve Bank of India's data localization mandates compel foreign cloud providers to establish domestic infrastructure. Bangalore's technology corridor attracts cybersecurity vendors establishing regional headquarters to serve Southeast Asian retail digitization.
Japan
Convenience store chains with dense urban footprints and aging point-of-sale terminals face firmware compatibility constraints requiring hybrid security architectures. METI cybersecurity guidelines for critical infrastructure extend to retail payment networks following high-profile supply chain incidents. The Tokyo-Osaka corridor concentrates system integrators bridging legacy mainframe environments with cloud-native detection platforms.
Retail Cybersecurity Market Competitive Environment
Premium-margin players sit above commodity-margin players across deployment sophistication, with cloud-native architectures commanding subscription multiples that on-premises appliance vendors cannot match. The vendor base stratifies into three tiers: integrated security fabric providers, endpoint-centric specialists, and managed detection service operators. Consolidation pressure intensifies as procurement teams abandon point solutions for unified platforms. Dominant competitive moves include strategic partnerships with hyperscaler cloud providers and geographic expansion through regional system integrator channels.
Within the integrated platform tier, Fortinet and Palo Alto Networks exemplify architecture providers that consolidate firewall, endpoint detection, and encryption functions into single procurement contracts. CrowdStrike occupies a position representing endpoint-centric specialists that reduce agent complexity on distributed point-of-sale systems. These three anchors demonstrate how vendor selection increasingly favors unified control planes over best-of-breed tool accumulation.
| Leading Market Players |
|---|
| Fortinet |
| Check Point |
| CrowdStrike |
| McAfee |
| Proofpoint |
| Palo Alto Networks |
| Zscaler |
| Deepwatch |
| Microsoft Security |
| Others |
Value Chain & Pricing Dynamics
Semiconductor wafer pricing indices cascade through cybersecurity hardware manufacturing into three distinct procurement tiers that separate Fortune 500 retailers from mid-market chains and independent boutiques.
Pricing Analysis
Consumption-based subscription models dominate retail cybersecurity procurement, with pricing stratifying across premium, standard, and economy tiers based on analyst support levels and compliance certification depth. Cost compression in the standard tier intensifies as Fortinet and Palo Alto Networks bundle firewall functions into broader security fabrics. Mid-market grocery chains exhibit highest price sensitivity due to thin operating margins, while omnichannel department stores absorb premium pricing for managed detection and response services.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced semiconductor fabrication and China for rare earth magnet components in hardware security modules. Raw material dependencies include silicon wafers, gallium nitride substrates, and specialized encryption chipsets. Tariff exposure on Chinese-manufactured network appliances elevates landed costs for North American retailers. Distribution runs through authorized reseller networks and hyperscaler marketplaces that consolidate vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCI DSS 4.0 enforcement deadlines compound regulatory-driven procurement cycles, transforming compliance from cost center to competitive differentiator for retailers processing card transactions.
For Market Incumbents: Anchor platform consolidation strategies around zero-trust architecture convergence to defend against cloud-native challengers. Deepen analyst capacity investments in lower-cost geographies to offset talent scarcity constraining managed services scaling. Fortify API connector libraries for fragmented POS terminal ecosystems to reduce customer switching incentives. For New Entrants and Emerging Players: Regional system integrators in India represent the most penetrable channel partner type for establishing local data center presence ahead of UPI payment proliferation. Target mid-market specialty retailers with limited security staff through outcome-based service level agreements that displace perpetual license incumbents. Prioritize quantum-resistant encryption roadmaps to capture post-NIST standardization premiums. For Investors and Strategic Acquirers: Asymmetric upside sits with endpoint-centric specialists possessing cloud-native detection platforms that reduce agent complexity on distributed store networks. Five-to-ten year viability hinges on analyst talent acquisition velocity outpacing competitor scaling. Monitor managed security service provider contract restructuring toward consumption-aligned pricing as inflection indicator for sector margin trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Convergence | Microsegmentation and identity-aware networking merge into unified platforms reducing agent sprawl on store endpoints. |
| Quantum-Resistant Encryption Development | Lattice-based algorithm implementations capture premium positioning ahead of NIST post-quantum cryptographic standardization. |
| Regional Data Center Establishment | Local infrastructure presence satisfies RBI data localization mandates for India retail digitization opportunities. |
| Outcome-Based Contract Restructuring | German and French grocery chains pioneer service level agreements tying payment to measurable breach prevention metrics. |
| Analyst Capacity Geographic Expansion | Mid-market managed detection and response scaling depends on security operations center talent outside high-cost metropolitan markets. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs at multi-location retail chains, security procurement officers at e-commerce platforms, channel partners distributing firewall appliances, and compliance consultants specializing in PCI DSS remediation with secondary validation. Regulatory filings from FTC enforcement actions, state attorney general data breach notifications, and hyperscaler capex disclosures anchored supply-side assessment. Bottom-up terminal-level demand estimates triangulated against top-down sector spending benchmarks.
Segment-weighting approaches distributed value across deployment mode, solution type, end-user vertical, and service complexity tiers throughout the forecast period. CAGRs derived from elasticity modeling of compliance deadline impacts and cloud migration velocity. Forecast inputs incorporated POS terminal replacement cycles, e-commerce transaction growth trajectories, and managed security service provider analyst hiring pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quantum computing advancement timelines and federal privacy legislation federalization. Assumptions reflect current enforcement postures and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
Banking Cyber Security Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Homomorphic Encryption Market
Cybersecurity
Data Center Logical Security Market
Cybersecurity
Advanced Malware Detection (AMD) Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
China Cybersecurity Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Domain Name System (DNS) Firewall Market
Cybersecurity
Cognitive Security Market
Cybersecurity
Global Network Security Policy Management Market
Cybersecurity
Nigeria Cybersecurity Market
Cybersecurity
SD-WAN Security Market