
 Global Chromatography Software Market | 2026-2036
Global Chromatography Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chromatography Software Market Foresight
Consolidation among contract research organizations and large pharmaceutical quality-control units is realigning purchasing power toward enterprise-wide chromatography data system contracts. Agilent Technologies leverages its instrument-software integration to anchor long-term laboratory relationships. Waters Corporation sustains premium positioning through specialized compliance architectures that dominate regulated pharmaceutical environments. Bruker Corporation competes by extending its mass-spectrometry software ecosystem into chromatography workflows for research institutes.
Chromatography software comprises digital platforms that control liquid and gas chromatography instruments, acquire detector signals at sampling rates exceeding 100 Hz, and execute peak-integration algorithms for quantitative chemical analysis. These systems serve primarily to ensure reproducible separation performance and generate audit-ready documentation for regulated substance characterization. Cloud-based deployment is capturing the fastest expansion as laboratories seek elastic computational capacity for high-throughput screening campaigns, while on-premise installations retain dominance in facilities handling proprietary drug-candidate data under strict intellectual-property protocols. Workflow automation solutions concentrate margin pools by reducing manual method-transfer steps between development and quality-control phases.
The FDA enforces 21 CFR Part 11 requirements for electronic records and signatures, compelling vendors to build immutable audit trails into every data-acquisition module. The European Medicines Agency applies Annex 11 guidelines that mandate risk-assessment documentation for computerized systems in GMP environments, creating divergent validation burdens across Atlantic markets. China's National Medical Products Administration aligns with international ICH Q2(R1) guidelines while imposing localized software-registration procedures that filter market access. Stakeholders must monitor evolving data-integrity enforcement patterns and decide whether to architect single global compliance platforms or maintain region-specific software variants.
Market Dynamics
Cloud-native chromatography data systems are compressing validation cycles and forcing incumbent vendors to rearchitect legacy codebases around containerized deployment models. This infrastructure shift redistributes competitive advantage toward software-first vendors with elastic subscription pricing.
Growth Catalysts
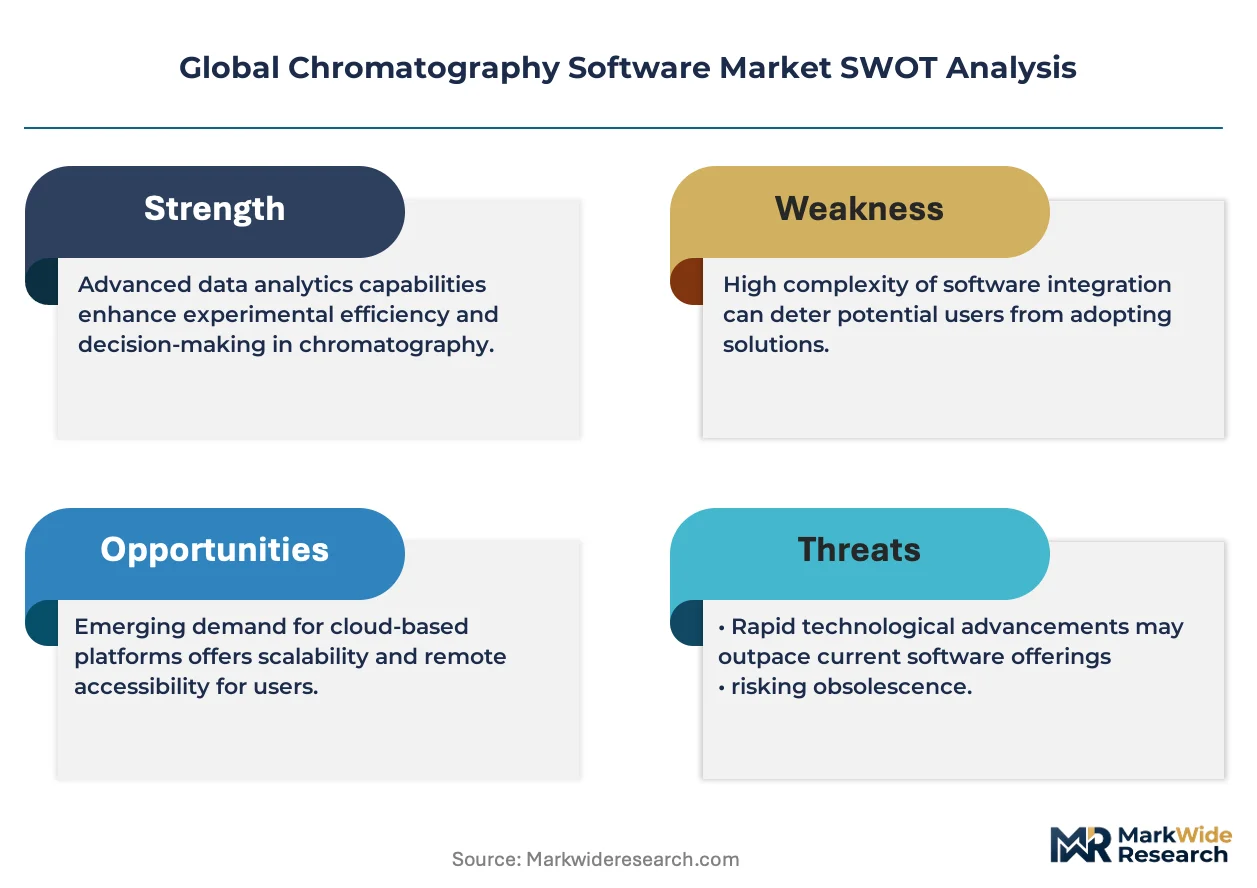
- FDA 21 CFR Part 11 enforcement:Pharmaceutical quality-control labs in the United States face intensified audit scrutiny, compelling replacement of paper-based data systems with compliant electronic records platforms that embed immutable audit trails.
- Biopharma cluster expansion:Contract development and manufacturing organizations in Germany and Switzerland are consolidating multi-site instrument fleets under single-vendor chromatography data systems to standardize method transfer.
- High-throughput screening automation:Robotics integration in Chinese pharmaceutical research institutes demands software capable of orchestrating parallel chromatography runs with real-time peak detection algorithms.
Market Restraints
- Specialized validation expertise scarcity:Computerized system validation engineers command premium compensation in regulated markets, inflating total cost of ownership for GMP-compliant chromatography software deployments.
- Legacy instrument lock-in:Proprietary data formats from aging liquid chromatography systems manufactured in the 2010s resist migration to modern open-architecture platforms.
- EU Annex 11 divergence:Risk-assessment documentation requirements for computerized systems in European GMP environments impose validation burdens that differ materially from FDA electronic records standards.
Strategic Opportunities
- India pharmaceutical export compliance:Domestic formulation manufacturers serving regulated markets require audit-ready chromatography data systems to satisfy CDSCO inspections and overseas regulator audits.
- AI-assisted peak integration:Machine learning algorithms trained on historical chromatograms promise to reduce manual integration disputes in quality-control release testing.
- Remote instrument monitoring:Cloud dashboards enabling real-time chromatography system health surveillance are penetrating contract research organizations seeking to minimize unplanned downtime across distributed lab networks.
Industry Challenges
- Data integrity remediation:Pharmaceutical manufacturers face costly retrospective validation exercises when audit trails reveal gaps in legacy chromatography system configurations.
- Hybrid deployment complexity:Laboratories attempting to bridge on-premise proprietary data storage with cloud analytics encounter API incompatibility between instrument control software and third-party platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chromatography Software Market |
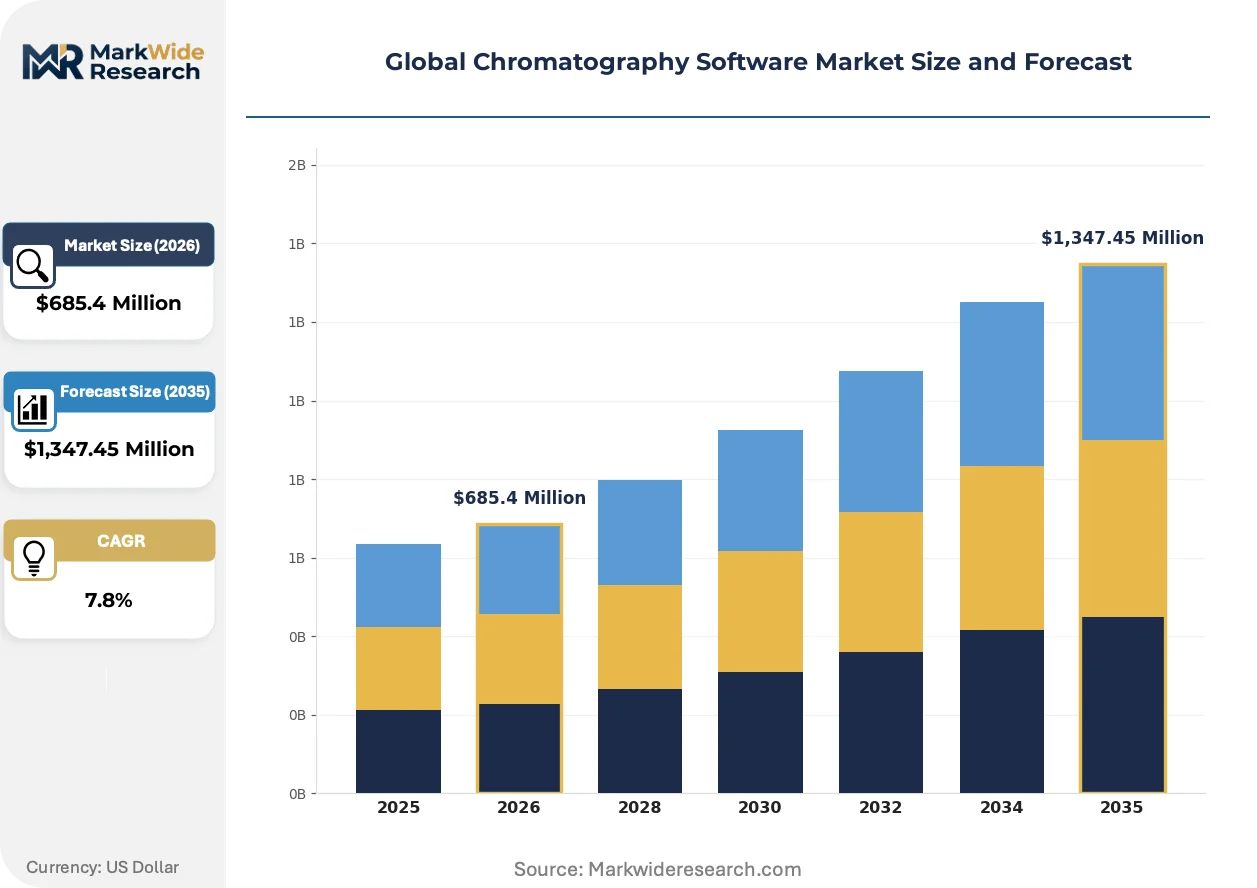
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Web-Based, Hybrid Solution Type: Data Acquisition, Data Analysis, Instrument Control, Reporting Tools, Workflow Automation Application: Pharmaceutical Research, Environmental Testing, Food & Beverage Analysis, Chemical Analysis, Forensics End User: Laboratories, Research Institutes, Quality Control Units, Contract Research Organizations |
| Companies Covered | Shimadzu Corporation, Bruker Corporation, Agilent Technologies, DataApex, Gilson, Waters Corporation, PerkinElmer, Scion Instruments, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chromatography Software Market Shifts & Advancements
Artificial intelligence and cloud infrastructure are converging to transform how chromatography data systems acquire, process, and govern analytical information. Vendors race to embed predictive capabilities while navigating divergent regulatory expectations across Atlantic and Pacific markets.
Machine learning-based peak detection is consolidating quantitative analysis workflows in high-volume pharmaceutical quality-control laboratories. These algorithms reduce analyst-to-analyst integration variability that previously consumed supervisory review hours. Waters Corporation and Agilent Technologies are embedding neural network models trained on decades of validated chromatograms, compressing method development timelines from weeks to days.
EMA Annex 11 guideline revisions are tightening risk-assessment documentation requirements for computerized systems in European GMP environments. Pharmaceutical manufacturers must now produce formalized validation master plans for chromatography software upgrades that previously qualified as like-for-like replacements. German and Swiss quality-control units are responding by embedding quality-by-design principles into software procurement specifications.
Subscription pricing for chromatography data systems is displacing perpetual license models in mid-sized contract research organizations. These buyers prioritize operational expenditure predictability over capital depreciation schedules. The shift concentrates vendor attention on recurring revenue metrics and customer success functions rather than upfront implementation services.
Global Chromatography Software Market Segmentation
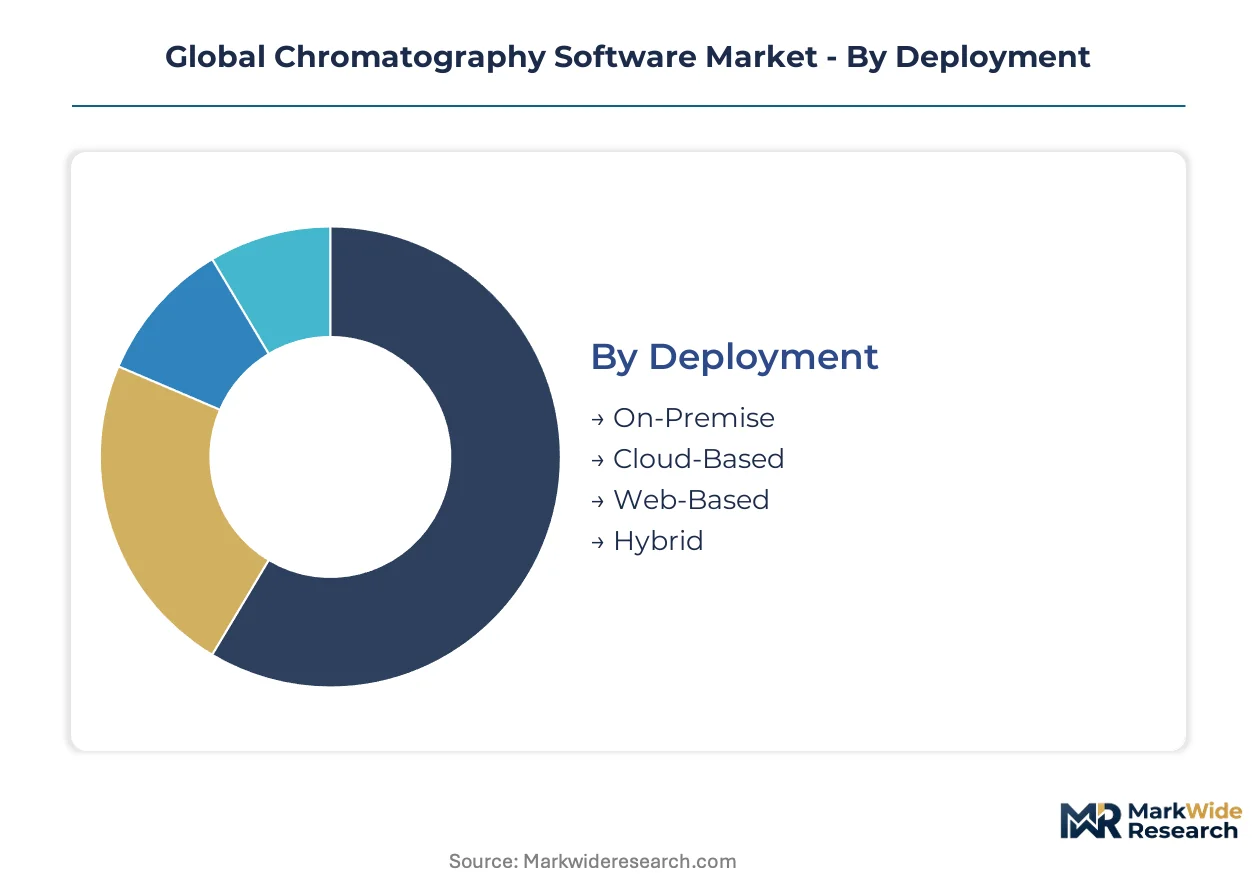
Chromatography software purchasing decisions diverge sharply across deployment architectures, solution capabilities, and end-use environments. Each segmentation axis reveals distinct margin structures, compliance burdens, and vendor competitive advantages that shape procurement patterns in regulated analytical laboratories.
Deployment:
On-premise installations command premium pricing for intellectual property protection, while cloud-native architectures compress validation cycles through containerized infrastructure.
- On-Premise:Local server installations with proprietary data storage dominate pharmaceutical quality-control facilities handling drug-candidate confidentiality under strict IP protocols. FDA 21 CFR Part 11 compliance requires immutable audit trails embedded within facility-controlled hardware, driving sustained demand despite higher capital expenditure profiles.
- Cloud-Based:Elastic computational capacity supports high-throughput screening campaigns across distributed contract research organization networks. Chinese pharmaceutical institutes in Shanghai and Beijing are adopting cloud-native chromatography data systems to orchestrate parallel instrument fleets without on-site IT infrastructure investments.
- Web-Based:Browser-accessible platforms reduce client-side software maintenance burdens for mid-sized environmental testing laboratories.
- Hybrid:Bridged architectures attempt to reconcile proprietary on-premise data repositories with cloud analytics capabilities, though API incompatibilities between legacy instrument control modules and third-party platforms create integration friction.
Mature deployment sits with On-Premise installations in regulated pharmaceutical environments. Newer deployment is concentrated in Cloud-Based architectures among contract research organizations seeking operational expenditure predictability.
Solution Type:
Workflow automation solutions capture expanding margin pools by eliminating manual method-transfer steps between development and quality-control phases.
- Data Acquisition:High-frequency detector signal capture at sampling rates exceeding 100 Hz demands specialized acquisition modules. German pharmaceutical manufacturers prioritize acquisition software with embedded EMA Annex 11 risk-assessment documentation capabilities.
- Workflow Automation:Integrated method transfer and batch scheduling systems compress analytical timelines from weeks to days. Swiss contract development organizations deploy automation suites to standardize multi-site instrument calibration protocols across Basel and Zurich facilities.
- Data Analysis:Peak integration algorithms with neural network training reduce analyst-to-analyst variability in quantitative release testing.
- Instrument Control:Unified command interfaces for liquid and gas chromatography systems streamline operator training requirements.
- Reporting Tools:Audit-ready documentation generators satisfy CDSCO inspection requirements for Indian pharmaceutical export compliance.
Established functionality concentrates in Data Acquisition modules. Steepest expansion trajectory belongs to Workflow Automation as laboratories eliminate manual transfer protocols.
Application:
Pharmaceutical research absorbs the majority of compliance-driven software investment, while environmental testing laboratories prioritize cost-efficient multi-instrument compatibility.
- Pharmaceutical Research:Drug development workflows require chromatography software with embedded FDA 21 CFR Part 11 electronic signatures and comprehensive audit trail architectures. United States biopharma clusters in Boston and San Francisco drive enterprise-wide chromatography data system contracts spanning discovery through quality-control phases.
- Environmental Testing:Regulatory monitoring of water and air contaminants demands high-throughput screening with standardized method libraries. Chinese environmental laboratories in Beijing deploy automated workflows to process EPA-equivalent compliance batches under MEE supervision.
- Food & Beverage Analysis:Pesticide residue and contaminant detection requires trace-level quantification with multi-detector signal correlation.
- Chemical Analysis:Petrochemical and specialty chemical manufacturers prioritize instrument interoperability across heterogeneous vendor fleets.
- Forensics:Toxicology and controlled substance identification laboratories require defensible chain-of-custody documentation with tamper-evident data handling.
Regulatory intensity peaks in Pharmaceutical Research applications. Fastest adoption velocity appears in Environmental Testing as Chinese laboratories expand monitoring capacity under tightened emissions standards.
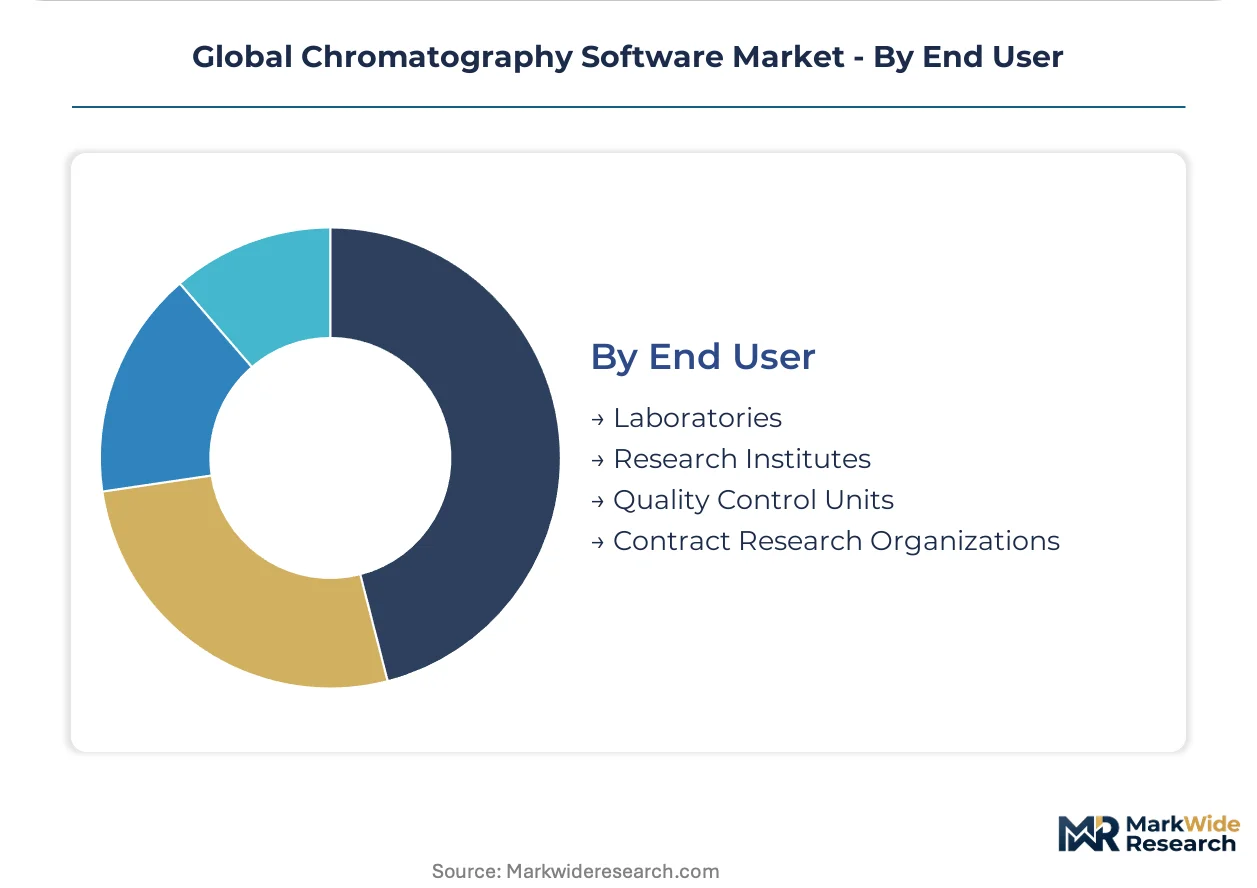
End User:
Contract research organizations are consolidating purchasing power toward multi-site enterprise licenses, while quality-control units demand single-vendor integration for compliance consistency.
- Contract Research Organizations:Multi-site analytical service providers require standardized chromatography data systems to ensure method transferability across distributed laboratory networks. Indian CROs serving regulated export markets invest in audit-ready platforms to satisfy simultaneous FDA and EMA inspection protocols.
- Quality Control Units:Pharmaceutical release testing laboratories mandate immutable data trails with supervisory review workflows embedded in software architecture. German quality-control facilities in Ludwigshafen and Frankfurt enforce vendor-specific compliance architectures that dominate regulated environments.
- Laboratories:Academic and government research facilities prioritize open data formats and instrument interoperability over proprietary ecosystem lock-in.
- Research Institutes:Basic science institutions in China and Japan emphasize flexible method development tools with minimal validation overhead for exploratory chromatography applications.
Established purchasing concentration rests with Quality Control Units in regulated pharmaceutical manufacturing. Emerging volume expansion is concentrated in Contract Research Organizations as consolidation creates enterprise-scale procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud infrastructure anchors North American chromatography software development, while Basel's pharmaceutical density and Shanghai's biotech expansion shape demand poles across three continents.
United States
FDA 21 CFR Part 11 enforcement drives pharmaceutical quality-control labs toward compliant electronic records platforms. Boston's biopharma cluster generates enterprise-wide chromatography data system contracts spanning discovery through release testing. San Francisco Bay Area cloud-native vendors compress validation cycles for contract research organizations.
Germany
EMA Annex 11 risk-assessment documentation requirements tighten validation burdens for GMP-compliant software deployments. Ludwigshafen and Frankfurt quality-control facilities enforce vendor-specific compliance architectures that dominate regulated European environments. Swiss contract development organizations in Basel standardize multi-site instrument fleets under single-vendor systems.
China
NMPA alignment with ICH Q2(R1) guidelines combines with localized software-registration procedures to filter market access. Shanghai and Beijing pharmaceutical institutes adopt cloud-native architectures to orchestrate parallel instrument fleets. MEE supervision drives environmental testing laboratories toward automated high-throughput screening workflows.
India
CDSCO inspection protocols compel domestic formulation manufacturers to deploy audit-ready chromatography data systems. Hyderabad and Mumbai contract research organizations consolidate purchasing power toward multi-site enterprise licenses serving simultaneous FDA and EMA export markets. Indian pharmaceutical exporters face intensified overseas regulator scrutiny.
Switzerland
Swissmedic requirements for computerized system validation anchor premium software positioning in Alpine pharmaceutical manufacturing. Basel and Zurich facilities embed quality-by-design principles into procurement specifications for chromatography software upgrades. Swiss contract development organizations prioritize method transfer standardization across distributed laboratory networks.
Global Chromatography Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and AI-assisted peak integration. The vendor base concentrates around instrument-software integration specialists and compliance-focused platform providers. Three archetypes dominate: integrated instrument vendors, standalone software specialists, and cloud-first analytics platforms. Competitive moves center on strategic partnerships for regulatory validation bundles and portfolio diversification into adjacent spectroscopy data systems.
Within the integrated instrumentation tier, Agilent Technologies and Waters Corporation exemplify contrasting compliance strategies, while Thermo Fisher Scientific occupies a position spanning reagent supply through data analytics. Bruker Corporation sits within the mass-spectrometry extension archetype, leveraging detector signal processing expertise into chromatography workflows. Japanese precision instrument manufacturers represented by Shimadzu Corporation anchor the Asia-Pacific supply base with embedded software-hardware bundles.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Bruker Corporation |
| Agilent Technologies |
| DataApex |
| Gilson |
| Waters Corporation |
| PerkinElmer |
| Scion Instruments |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Enterprise-perpetual versus cloud-subscription bifurcation generates divergent margin architectures across deployment tiers, with on-premise installations anchoring premium pricing through validation-bundled service contracts while SaaS offerings compress upfront commitments into recurring revenue streams. This structural split concentrates supply chain leverage with instrument-integrated vendors in regulated pharmaceutical environments and with software-native providers in contract research networks.
Pricing Analysis
Validation-bundled service contracts separate enterprise-tier perpetual licenses from unvalidated cloud-subscription tiers, with FDA 21 CFR Part 11 compliance documentation commanding substantial premiums over research-grade deployments. Price differentiation rests on certification depth and instrument integration density, with German quality-control facilities absorbing higher costs for EMA Annex 11 risk-assessment architectures. Cost compression in mid-market cloud offerings is intensifying because containerized deployment reduces implementation overhead. Contract research organizations exhibit highest price sensitivity, while pharmaceutical quality-control units prioritize compliance assurance over procurement savings.
Supply Chain Analysis
FDA 21 CFR Part 11 and EMA Annex 11 qualification requirements gate vendor participation, filtering software distribution through certified implementation partners in regulated markets. Development concentration centers on the United States, Germany, and China, with cloud infrastructure provisioning drawing from hyperscaler networks in Northern Virginia, Frankfurt, and Shanghai. Raw material dependencies encompass chromatography instrument firmware, detector signal processing modules, and audit-trail database engines. Single-source vulnerability sits with legacy instrument data format lock-in. Distribution runs through direct enterprise sales teams for pharmaceutical manufacturers and channel partners for environmental testing laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is consolidating purchasing power toward enterprise-scale vendors, forcing smaller specialists into acquisition or niche retreat. Cloud-native architectures and AI-assisted peak integration capabilities are separating investable platforms from legacy codebases facing remediation obsolescence.
For Market Incumbents: Deepen instrument-software integration moats by embedding neural network peak detection directly into acquisition firmware, neutralizing standalone analytics competitors. Extend validation service capabilities into automated compliance documentation, capturing recurring revenue from EMA Annex 11 risk-assessment burden escalation. Vertical integration into cloud infrastructure provisioning secures margin capture from subscription pricing displacement.
For New Entrants and Emerging Players: The mid-market price-point gap between Agilent-Waters premium tiers and open-source alternatives offers white-space entry for containerized chromatography data systems with modular compliance add-ons. Environmental testing laboratories in China present the most penetrable segment, with MEE supervision driving automated workflow demand without legacy validation overhead. A channel-centric go-to-market through regional instrument distributors accelerates footprint expansion.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native specialists given FDA enforcement intensity accelerating replacement cycles for paper-based legacy systems. Long-term viability over the next decade favors platforms with elastic subscription economics and embedded AI capabilities. Target acquisition archetypes include workflow automation specialists with validated method-transfer engines. The signal to watch is CDSCO inspection protocol tightening for Indian pharmaceutical exporters, which would compress procurement timelines for audit-ready platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Peak Integration Launch | Machine learning algorithms trained on Waters Corporation chromatogram archives reduce analyst variability in quality-control release testing. |
| Cloud-Native Platform Migration | Containerized deployment compresses validation cycles for Chinese pharmaceutical institutes orchestrating parallel instrument fleets. |
| Regulatory Validation Partnership | Collaboration with German compliance consultants embeds EMA Annex 11 risk-assessment documentation into procurement specifications. |
| Workflow Automation Acquisition | Method-transfer standardization capabilities address Swiss contract development organization consolidation across Basel and Zurich facilities. |
| Subscription Pricing Transition | Operational expenditure predictability aligns with mid-sized contract research organization preference over capital depreciation schedules. |
Research Methodology
Independent corroboration across regulatory filing databases, instrument vendor disclosures, and pharmaceutical quality-control procurement records underwrites the qualitative findings in this study. Primary interviews with chromatography data system administrators, regulatory affairs specialists at contract research organizations, software validation engineers, and laboratory informatics directors combined with secondary validation from FDA warning letter archives, EMA inspection deficiency reports, and NMPA software registration filings. Bottom-up demand modeling across deployment architectures and top-down market sizing through vendor revenue analysis established convergent estimates.
Comparable-period anchoring to historical validation cycle durations and compliance enforcement intensity patterns structured the projection horizon. The analytical framework modeled deployment mode, solution capability tier, end-user organization scale, and regional regulatory cluster segmentation throughout the forecast period. CAGRs derived from instrument installation base expansion rates and software attach-ratio trends, with cloud-native adoption velocity and AI feature penetration serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical quality-control deployments carry tighter precision than academic research installations due to documented procurement transparency. Forecasts reflect assumptions regarding sustained FDA 21 CFR Part 11 enforcement intensity and EMA Annex 11 guideline stability. A model refresh is warranted upon material change in NMPA software-registration procedure stringency or hyperscaler cloud infrastructure availability in China.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Digital Marketing Software Market
Software & Services
Apache Spark Market
Software & Services
Dealer Management System Market
Software & Services
Spain Sports Management Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Lease Accounting Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Global Voip Software Market
Software & Services
Meditation Software Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Global Client Portal Software Market
Software & Services
Newsroom Software Market
Software & Services
Italy HR Payroll Software Market