
 Commercial Drone Software Market | 2026-2036
Commercial Drone Software Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Drone Software Market Insights
Platform licensing revenue is reshaping margin capture in the commercial drone software value chain, pulling value away from hardware-centric models toward recurring software subscriptions. Skydio leverages its vertically integrated autonomy stack to sustain premium positioning in defense and public safety verticals. Anduril Industries anchors its growth on Lattice AI-driven mission autonomy, while Altitude Angel competes through airspace management infrastructure that controls UTM corridors across multiple European jurisdictions.
Commercial drone software encompasses the embedded and cloud-native programs that govern flight planning, real-time navigation, sensor fusion, data processing, and fleet orchestration for unmanned aerial systems operating in commercial environments, typically interfacing with autopilot hardware through MAVLink or proprietary protocols and processing geospatial outputs at sub-centimeter accuracy for industrial decision-making. Flight management solutions dominate current procurement volumes as operators prioritize mission safety and regulatory compliance, while data analytics capabilities are expanding fastest as agricultural imaging and construction monitoring applications generate terabyte-scale datasets requiring automated extraction. Mapping and surveying solutions occupy mature positions with established photogrammetry workflows, though inspection and monitoring segments are deepening vertical integration as infrastructure consultants demand end-to-end defect detection pipelines.
The FAA's Part 107 framework and BVLOS waiver system shape operator certification requirements and software validation standards in the United States, while EASA's Specific Category regulations under EU Regulation 2019/947 mandate conformity assessments that filter market access across European member states. The FCC governs radio frequency allocations for command-and-control links, directly constraining telemetry range and reliability specifications that software architectures must accommodate. Stakeholders must monitor pending remote identification rulemakings and spectrum reallocation proceedings that will determine which platform architectures achieve regulatory scalability without hardware retrofit burdens.
Market Dynamics
Platform licensing revenue is compressing hardware margins and redistributing value toward recurring software subscriptions, forcing autopilot manufacturers to defend position through vertical control over autonomy stacks.
Growth Catalysts
- FAA Part 107 framework:Remote pilot certification requirements are standardizing operator competence thresholds across United States commercial corridors, reducing insurance friction and accelerating fleet deployment timelines.
- Precision farming imaging:Agricultural producers are integrating multispectral analytics into seasonal crop management, generating sustained demand for flight planning automation and terabyte-scale data processing pipelines.
- BVLOS waiver expansion:Beyond-visual-line-of-sight operational approvals are unlocking long-range infrastructure inspection contracts that require sophisticated mission autonomy and airspace deconfliction software.
Market Restraints
- Radio frequency spectrum scarcity:FCC command-and-control link allocations constrain telemetry range specifications, forcing software architectures to accommodate degraded signal environments without hardware retrofit.
- Sensor hardware concentration:High-resolution photogrammetry and LiDAR module supply concentrates among East Asian component fabricators, exposing flight management vendors to input cost volatility and qualification delays.
- EASA conformity assessment complexity:EU Regulation 2019/947 Specific Category requirements impose multi-jurisdiction validation burdens that filter market access and extend time-to-revenue for platform entrants.
Strategic Opportunities
- Brazilian agricultural expansion:ANVISA regulatory harmonization with FAA standards is opening certification pathways for North American flight management platforms in South American soybean and sugarcane monitoring.
- AI-driven defect detection:Convolutional neural network convergence with thermal imaging is enabling automated crack identification in concrete infrastructure, displacing manual inspector dispatch for bridge and dam assessments.
- Utility vegetation management mandates:FERC transmission line clearance requirements are institutionalizing recurring drone-based corridor surveys, creating subscription revenue anchors for fleet orchestration software.
Industry Challenges
- Autonomy engineer scarcity:Computer vision and sensor fusion expertise concentrates among defense contractors and academic laboratories, constraining commercial software teams' ability to validate safety-critical navigation algorithms.
- Legacy GIS integration friction:Municipal infrastructure agencies operate decades-old geospatial databases that resist API-native drone data ingestion, forcing middleware development and deployment cost inflation.
- Remote ID compliance retrofit:Pending FAA broadcast requirements threaten hardware obsolescence for installed commercial fleets, complicating software vendors' upgrade pathway planning and customer retention strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Drone Software Market |
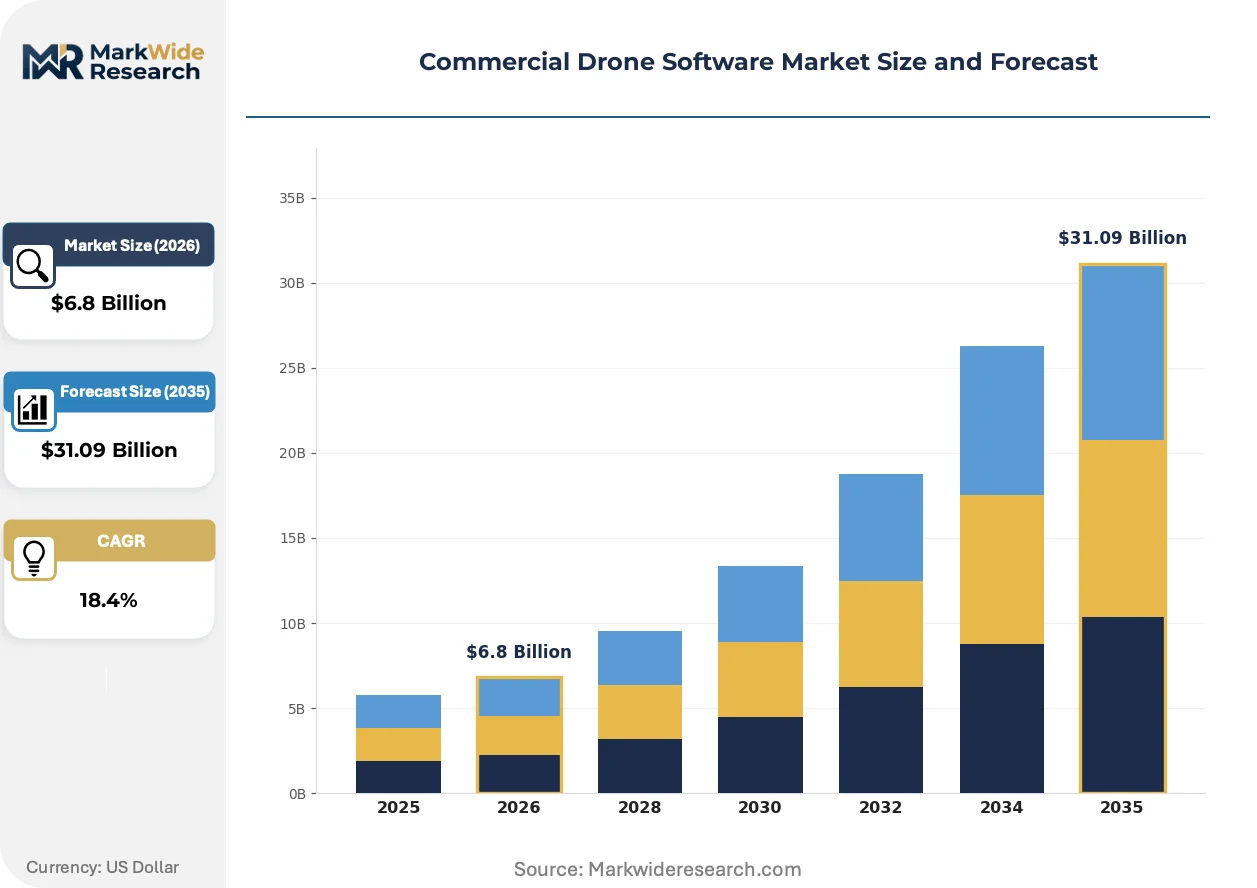
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premise, Hybrid, Edge Computing Solution Type: Flight Management, Data Analytics, Mapping & Surveying, Inspection & Monitoring, Delivery Management Application: Agricultural Imaging, Construction Monitoring, Environmental Analysis, Public Safety Surveillance, Media Production End User: Precision Farming Firms, Infrastructure Consultants, Environmental Agencies, Emergency Responders, Entertainment Houses |
| Companies Covered | Airspace Link, Drone Harmony, Skydio, EagleView, GeoCue Group, Anduril Industries, Votix, Loveland Innovations, Altitude Angel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Drone Software Market Trends and Innovations
Edge computing architectures are relocating sensor processing from ground stations to onboard compute modules, compressing latency for time-critical navigation decisions while reducing telemetry bandwidth requirements.
Neural network-based obstacle detection is digitizing safety assurance workflows that previously required human visual observers during complex terrain operations. Mining and construction operators in Western Australia and Chilean copper belts are deploying these systems for autonomous pit wall inspection. The technology is digitizing risk allocation between software vendors and end-user operators, shifting liability frameworks toward product certification models.
EASA's forthcoming U-space regulatory package is mandating automated airspace management interfaces for all commercial operations above specified density thresholds. This framework is forcing flight management platforms to embed real-time traffic deconfliction protocols that interface with national UTM corridors. German and French infrastructure inspectors are prioritizing software vendors with pre-validated U-space interoperability, creating certification-driven procurement segmentation.
Subscription-based fleet management is displacing perpetual license sales as dominant commercial terms. Agricultural cooperatives and utility consortia are consolidating purchasing through multi-year platform agreements that bundle software, training, and regulatory compliance support. This pattern concentrates most visibly across United States Midwest grain belts and Texas-Oklahoma energy corridors, where operator scale justifies dedicated customer success functions.
Commercial Drone Software Market Segmentation
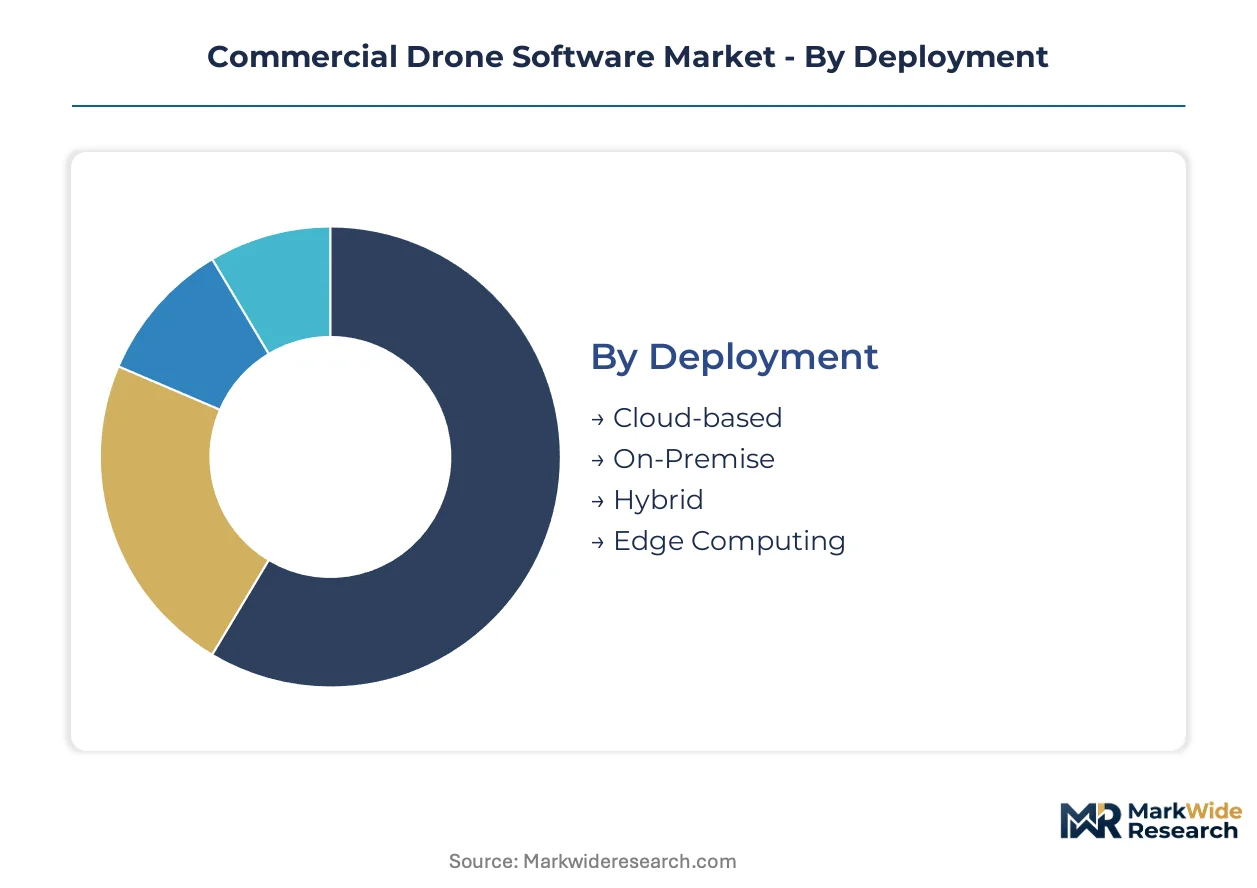
Software architectures in commercial drone operations diverge sharply across deployment models, solution types, and end-user sophistication levels. Segmentation reveals where procurement budgets concentrate and which capability bundles command premium positioning.
Deployment:
Cost tier determines infrastructure investment thresholds and recurring operational expenditures for operator fleets.
- Cloud-based:Centralized compute resources process telemetry and sensor data through remote servers, eliminating local hardware maintenance. Agricultural cooperatives across United States Midwest grain belts prioritize this model for seasonal scalability without capital deployment.
- On-Premise:Dedicated server installations within operator facilities govern data sovereignty and latency-sensitive workflows. Defense contractors and critical infrastructure operators mandate air-gapped architectures to satisfy security clearance requirements.
- Hybrid:Split architectures route mission-critical navigation locally while pushing archival analytics to cloud reservoirs. Construction monitoring firms leverage this balance for real-time safety decisions alongside long-term project documentation.
- Edge Computing:Onboard processing modules execute sensor fusion and obstacle detection without ground station dependency. Mining operators in Western Australian pit operations deploy these systems where telemetry links face terrain interference.
Cloud-based deployments command the established base. The steepest expansion runs through Edge Computing.
Solution Type:
Application maturity shapes margin structures and competitive density across software categories.
- Flight Management:Core autopilot interfaces governing waypoint navigation, geofencing enforcement, and telemetry logging through MAVLink protocols. FAA Part 107 compliance automation drives concentrated procurement among United States commercial certification holders.
- Data Analytics:Automated extraction pipelines transforming multispectral imagery and LiDAR point clouds into actionable intelligence. Precision farming operations generate sustained demand for crop health algorithms that integrate with seasonal input decisions.
- Mapping & Surveying:Photogrammetry workflows producing orthomosaic outputs and digital elevation models at sub-centimeter accuracy. Surveying engineering firms maintain established procurement relationships for cadastral and topographic deliverables.
- Inspection & Monitoring:Defect detection systems combining thermal imaging with structural assessment protocols for infrastructure integrity. FERC-mandated transmission line clearance programs institutionalize recurring revenue for vegetation management modules.
- Delivery Management:Route optimization and payload handling systems for last-mile logistics operations. Experimental BVLOS corridors in select United States jurisdictions test validation frameworks for pharmaceutical and retail distribution.
Flight Management anchors current revenue volumes. Data Analytics climbs fastest as imaging datasets scale.
Application:
Customer workflow integration determines software customization depth and implementation complexity.
- Agricultural Imaging:Multispectral and thermal analytics for crop stress detection, irrigation planning, and yield forecasting. Brazilian soybean producers and United States corn belt operators drive cross-hemisphere demand cycles.
- Construction Monitoring:Progress documentation and earthwork volume calculations for project control. General contractors in Texas-Oklahoma energy corridors bundle drone data with BIM integration services.
- Environmental Analysis:Ecosystem mapping, pollution tracking, and conservation boundary enforcement. EPA-affiliated watershed monitoring programs specify automated flight planning for repeatable transect coverage.
- Public Safety Surveillance:Search pattern automation and situational awareness for emergency response coordination. Wildfire management agencies prioritize thermal detection algorithms for hotspot identification.
- Media Production:Cinematic flight path programming and gimbal control for broadcast and film capture. Entertainment houses in Los Angeles and New York production clusters demand precision repeatability for visual effects integration.
Agricultural Imaging holds the deepest installed base. Construction Monitoring gains share fastest through infrastructure spending.
End User:
Procurement sophistication separates enterprise-scale operators from specialized service providers.
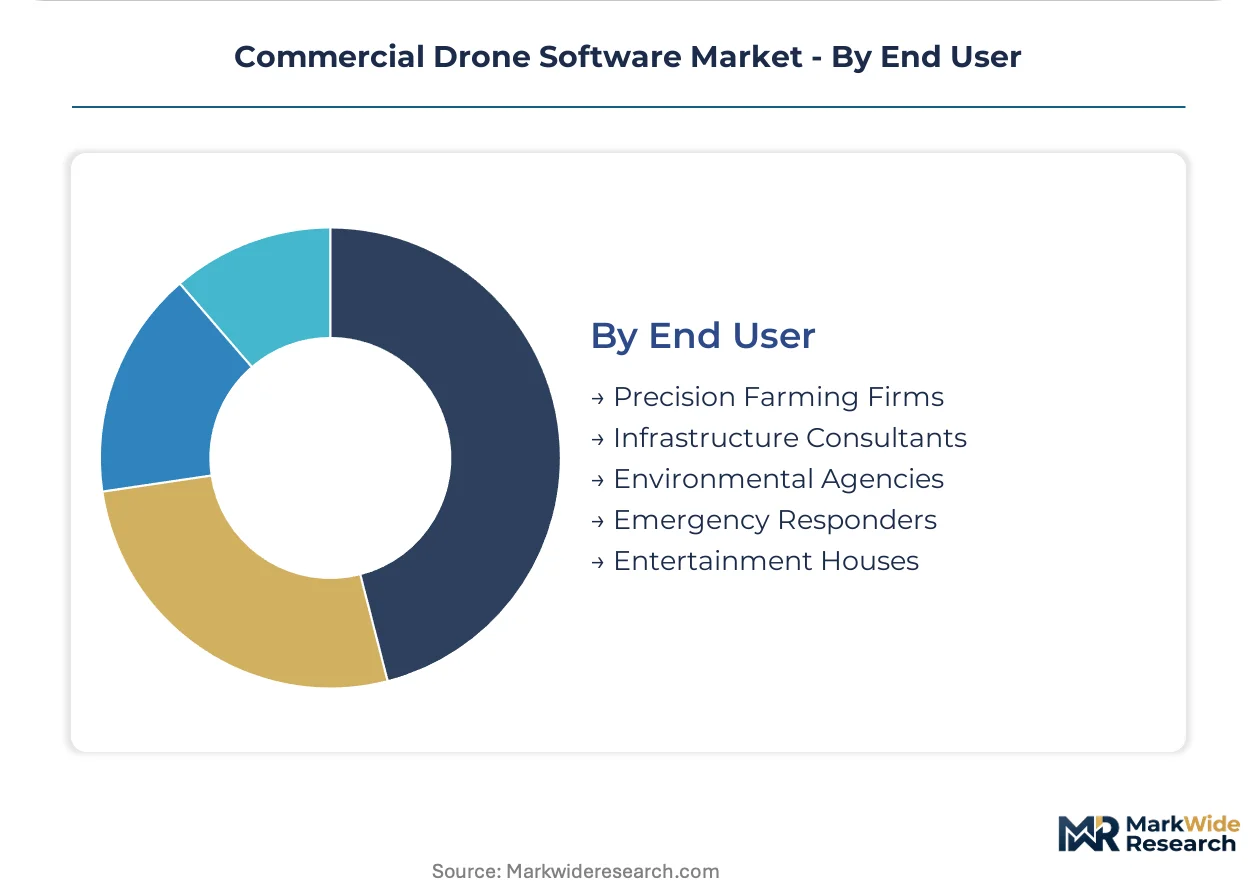
- Precision Farming Firms:Large-scale agricultural operators managing multispectral analytics across thousand-acre holdings. These customers negotiate multi-year platform agreements bundling software, training, and regulatory compliance support.
- Infrastructure Consultants:Engineering and inspection service providers delivering structural assessments for transportation and utility clients. Bridge and dam inspection contracts require end-to-end defect detection pipelines with liability documentation.
- Environmental Agencies:Government and nonprofit organizations conducting ecosystem monitoring and enforcement. Federal procurement specifications mandate FAA certification and data security protocols.
- Emergency Responders:Fire departments, search-and-rescue units, and disaster management authorities. Thermal imaging integration and night operation capabilities determine vendor selection for these operators.
- Entertainment Houses:Production companies and broadcast networks requiring cinematic capture and live transmission. Los Angeles-based studios prioritize vendor relationships with cinema-grade gimbal integration.
Precision Farming Firms dominate current procurement volumes. Infrastructure Consultants expand most rapidly through federal inspection mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across procurement environments. United States buyers absorb premium pricing for regulatory-validated platforms, while Brazilian operators prioritize cost-efficient seasonal deployments. European conformity assessments filter price-sensitive entrants from high-integrity corridors.
United States
FAA Part 107 certification holders drive concentrated procurement across agricultural and infrastructure verticals. BVLOS waiver expansion under DOT inspection mandates compresses time-to-operation for long-range utility surveys. Texas-Oklahoma energy corridors anchor fleet management subscription growth among mid-scale operators.
Germany
Engineering service providers demand U-space pre-validated flight management systems for infrastructure inspection contracts. EASA Specific Category conformity assessments under EU Regulation 2019/947 extend validation timelines but secure premium positioning for compliant vendors. Bavarian industrial clusters integrate drone data into legacy manufacturing quality systems.
Brazil
ANVISA regulatory harmonization with FAA standards accelerates North American platform certification for soybean and sugarcane monitoring. Agricultural cooperatives prioritize seasonal scalability over year-round licensing commitments. São Paulo-based precision farming firms consolidate multispectral analytics procurement through cooperative purchasing structures.
United Kingdom
Civil Aviation Authority remote pilot frameworks standardize operator competence for construction monitoring and environmental surveying applications. London-based infrastructure consultants bundle drone inspection with BIM integration services. Scottish wind farm operators drive demand for offshore-capable mission autonomy software.
Australia
CASA-certified operators deploy edge-computing architectures for autonomous pit wall inspection in Western Australian mining belts. Thermal imaging integration for wildfire hotspot detection anchors public safety procurement. Queensland agricultural corridors adopt cloud-based flight planning for seasonal crop stress monitoring.
Commercial Drone Software Market Competitive Landscape
Defense-anchored autonomy stacks and civilian airspace management platforms split the market into distinct capability tiers. Consolidation pressure concentrates among flight management vendors defending hardware-software integration against pure-play software entrants. Three archetypes dominate: vertically integrated drone manufacturers with captive software, independent flight planning specialists, and infrastructure-scale airspace orchestration providers. Competitive moves center on regulatory certification pre-positioning and multi-year fleet management subscription anchoring.
Within the vertically integrated tier, Skydio and Anduril Industries exemplify defense-derived autonomy stacks repurposed for commercial adjacencies. Altitude Angel occupies a distinct position among airspace management specialists, leveraging pre-validated UTM corridor control across multiple European jurisdictions. These three anchors illustrate divergent paths to margin capture: hardware-captive licensing versus infrastructure-scale orchestration fees.
| Leading Market Players |
|---|
| Airspace Link |
| Drone Harmony |
| Skydio |
| EagleView |
| GeoCue Group |
| Anduril Industries |
| Votix |
| Loveland Innovations |
| Altitude Angel |
| Others |
Pricing and Supply Chain Analysis
East Asian photogrammetry sensor fabricators concentrate supply for high-resolution imaging modules, anchoring cost structures for flight management vendors and compressing margin pools toward software licensing tiers that escape hardware input volatility.
Pricing Analysis
Extended service contracts and regulatory compliance support bundles drive lifetime value capture beyond initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification validation depth and fleet scale. Cost compression in standard tiers intensifies because agricultural cooperatives negotiate seasonal licensing without year-round commitments. Precision farming firms exhibit highest price sensitivity, while defense contractors absorbing FAA-validated platforms show lowest elasticity.
Supply Chain Analysis
Supplier-financing facilities from East Asian component vendors extend payment terms for LiDAR and thermal imaging modules, easing working capital pressure on flight management software developers. Manufacturing concentrates in China, South Korea, and Japan for sensor hardware, while cloud compute infrastructure draws from United States and European data center clusters. Single-source vulnerability runs through photogrammetry sensor supply. Distribution runs through direct enterprise sales for large fleet operators and cooperative purchasing structures for agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around U-space interoperability mandates, where EASA regulatory convergence forces flight management vendors into ecosystem partnerships that determine procurement access across European infrastructure corridors.
For Market Incumbents: Entrench position through captive autonomy stack development and pre-validated UTM corridor certification that locks out pure-play software entrants lacking hardware integration depth. BVLOS waiver expansion threatens margin pools for vendors without airspace deconfliction capabilities. Priority lever rests on backward integration into edge computing modules for mining and public safety verticals. For New Entrants and Emerging Players: Brazilian agricultural cooperatives seeking seasonal scalability without capital deployment represent the most penetrable entry point for cloud-native flight planning platforms. Mid-scale infrastructure consultants in Texas-Oklahoma energy corridors lack dedicated customer success functions from incumbent vendors. Go-to-market angle centers on cooperative purchasing facilitation and ANVISA regulatory navigation support. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flight management specialists holding FAA Part 107 compliance automation but lacking AI-driven defect detection capabilities. Long-term viability hinges on autonomy algorithm differentiation beyond regulatory table stakes. Signal to watch: BVLOS waiver approval velocity as indicator of addressable market expansion for mission autonomy software.| Strategic Initiative | Industry Significance |
|---|---|
| U-space Pre-validation Investment | EASA compliance automation secures procurement preference among German infrastructure inspectors. |
| Edge Computing Module Acquisition | Onboard processing capability displaces ground station dependency for Australian mining operators. |
| Brazilian Regulatory Partnership | ANVISA harmonization pathways accelerate platform certification for South American agricultural expansion. |
| AI Defect Detection Development | Convolutional neural network integration enables automated concrete crack identification for FERC-mandated inspections. |
| Cooperative Purchasing Facilitation | Midwest grain belt agricultural consortiums consolidate procurement through multi-year platform agreements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA waiver filings, EASA conformity assessment databases, hyperscaler capex disclosures, and agricultural cooperative procurement records. Primary interviews engaged fleet operations managers at precision farming firms, autonomy engineers at defense contractors, regulatory affairs leads at flight management vendors, and UTM infrastructure specialists at national aviation authorities. Bottom-up triangulation across operator deployment scales and top-down validation against regulatory filing volumes anchor market sizing.
Forecast inputs include deployment model adoption curves, BVLOS waiver approval trajectories, and segmentation across solution type, application vertical, and end-user sophistication. Modeled dimensions span cloud versus edge compute architecture, flight management versus data analytics solution mix, and regional regulatory framework clusters. CAGRs derive from installed base expansion rates and annual recurring revenue per operator benchmarks. Industry-specific inputs incorporate multispectral imaging dataset growth and U-space implementation timelines.
Stress conditions across FAA rulemaking velocity, East Asian sensor supply disruption, and agricultural commodity price cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization and autonomy algorithm validation pathways. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United Kingdom IT Services Market
Software & Services
Global Presentation Software Market
Software & Services
Discount Management Software Market
Software & Services
Team Collaboration Software Market
Software & Services
Referral Marketing Software Market
Software & Services
Grant Management Software Market
Software & Services
Problem Management Software Market
Software & Services
Ccaas Software Market
Software & Services
Design Collaboration Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Towing Software Market
Software & Services
Software Testing Tools Market
Software & Services
Blogger Outreach Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Session Support Software Market