
 Rice Bran Wax Market | 2026-2036
Rice Bran Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Bran Wax Market Outlook
Carnauba wax is rebalancing rice bran wax economics as Brazilian supply volatility and price spikes push formulators toward Asian-origin alternatives. Strahl & Pitsch leverages its century-old compounding expertise to sustain premium positioning in North American cosmetic channels. Koster Keunen anchors European demand through its specialized natural wax distribution network. Nisshin OilliO Group dominates captive supply from Japan's rice milling belt, controlling upstream access to crude bran oil feedstock.
Rice bran wax is a hard, crystalline lipid extracted from dewaxed rice bran oil, typically melting between 79°C and 85°C and comprising primarily aliphatic esters, free fatty acids, and hydrocarbons. It functions as a gelling agent, binder, and surface modifier across cosmetics, food coatings, and candle formulations. Cosmetic Grade commands the largest volume share as clean-label beauty standards tighten ingredient disclosure requirements. Pharmaceutical Grade represents the fastest-expanding margin pool, driven by excipient validation work and oral dosage form applications. Industrial Grade applications in coatings and polishes face slower growth as waterborne formulations displace solvent-based systems requiring wax additives.
FDA food-contact regulations and EPA chemical substance reporting requirements shape product standards and market access for U.S.-destined rice bran wax. REACH registration and the EU Green Deal's bio-based content targets are accelerating purity certification investments among European suppliers. India's BIS quality standards and FSSAI food additive approvals are creating compliance thresholds for export-oriented Indian processors like Indo Amines Ltd. Stakeholders must monitor feedstock competition from rice bran oil's food and biodiesel applications, as crushing economics determine wax availability and pricing trajectories.
Market Dynamics
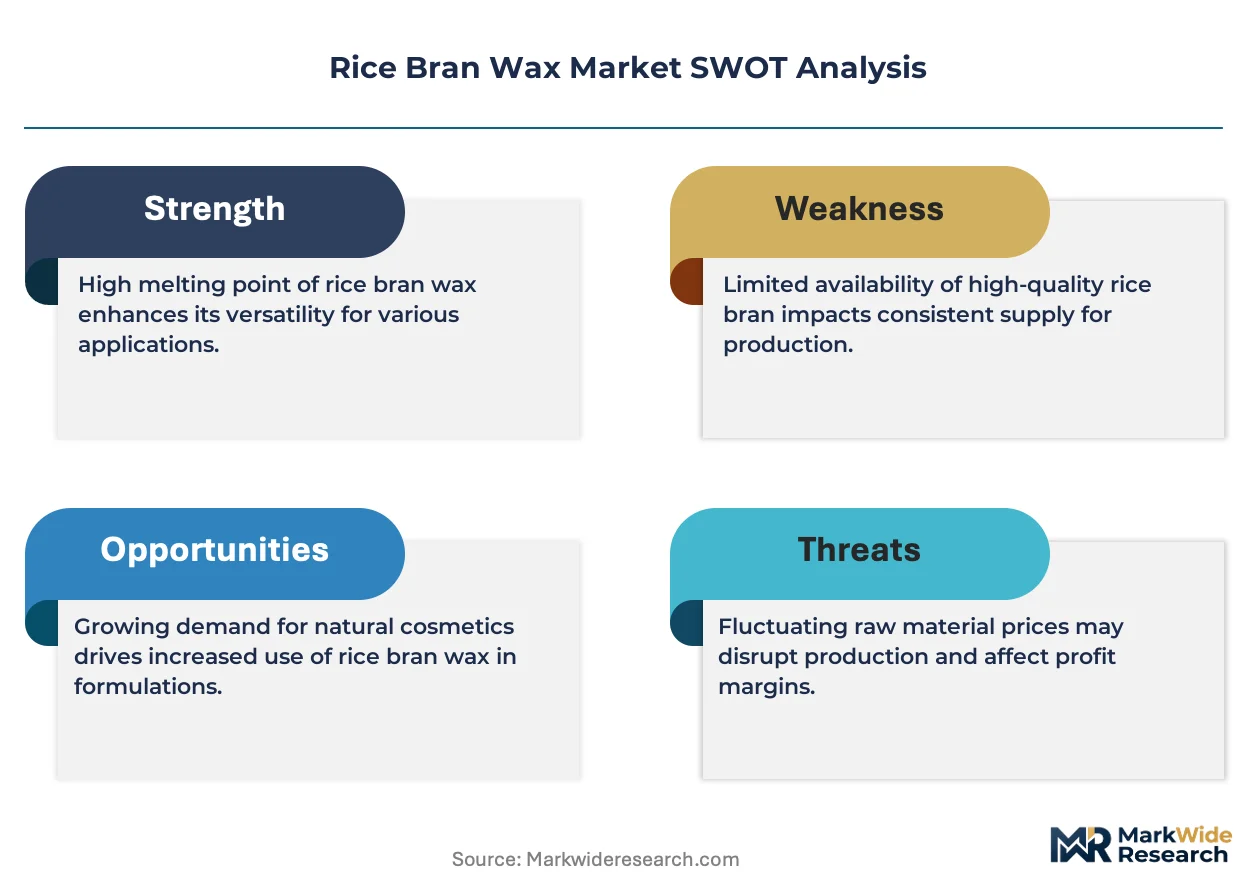
Feedstock competition from rice bran oil's food and biodiesel applications is compressing wax availability, forcing processors to secure crushing economics through long-term milling contracts or captive supply arrangements.
Growth Catalysts
- Clean-label cosmetic mandates:Formulators are substituting rice bran wax for synthetic emollients as EU Green Deal bio-based content targets and FDA food-contact disclosure rules tighten ingredient transparency requirements.
- REACH registration acceleration:European suppliers are investing in purity certification to meet ECHA compliance thresholds, opening premium channel access for certified pharmaceutical-grade material.
- Japan's rice milling concentration:Domestic cosmetic formulators anchor regional offtake through direct procurement from the Kanto and Kansai milling belts, securing supply chain proximity advantages.
Market Restraints
- Crude bran oil price volatility:Crushing economics fluctuate with edible oil and biodiesel demand, transmitting cost instability directly to wax extraction margins.
- Brazilian carnauba wax substitution:Supply volatility from South American palm sources periodically compresses rice bran wax pricing power despite its functional equivalence.
- Waterborne coating displacement:Industrial-grade applications in solvent-based polishes face demand erosion as architectural coatings shift to acrylic and polyurethane systems.
Strategic Opportunities
- Pharmaceutical excipient validation:Oral dosage form applications represent an underpenetrated margin pool as CDSCO and FDA drug master file pathways mature for lipid-based binders.
- India export certification:BIS quality standards and FSSAI food additive approvals are creating compliance moats for processors targeting Middle Eastern and African markets.
- Biopolymer compounding convergence:Rice bran wax functions as a nucleating agent in PLA and PHA formulations, aligning with EU Green Deal packaging mandates.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel FDA food-contact, REACH registration, and BIS quality standard approvals extend product launch cycles by 18-24 months.
- Specialized extraction talent scarcity:Dewaxing process optimization and crystallization control require expertise concentrated among Japanese and European technical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Bran Wax Market |
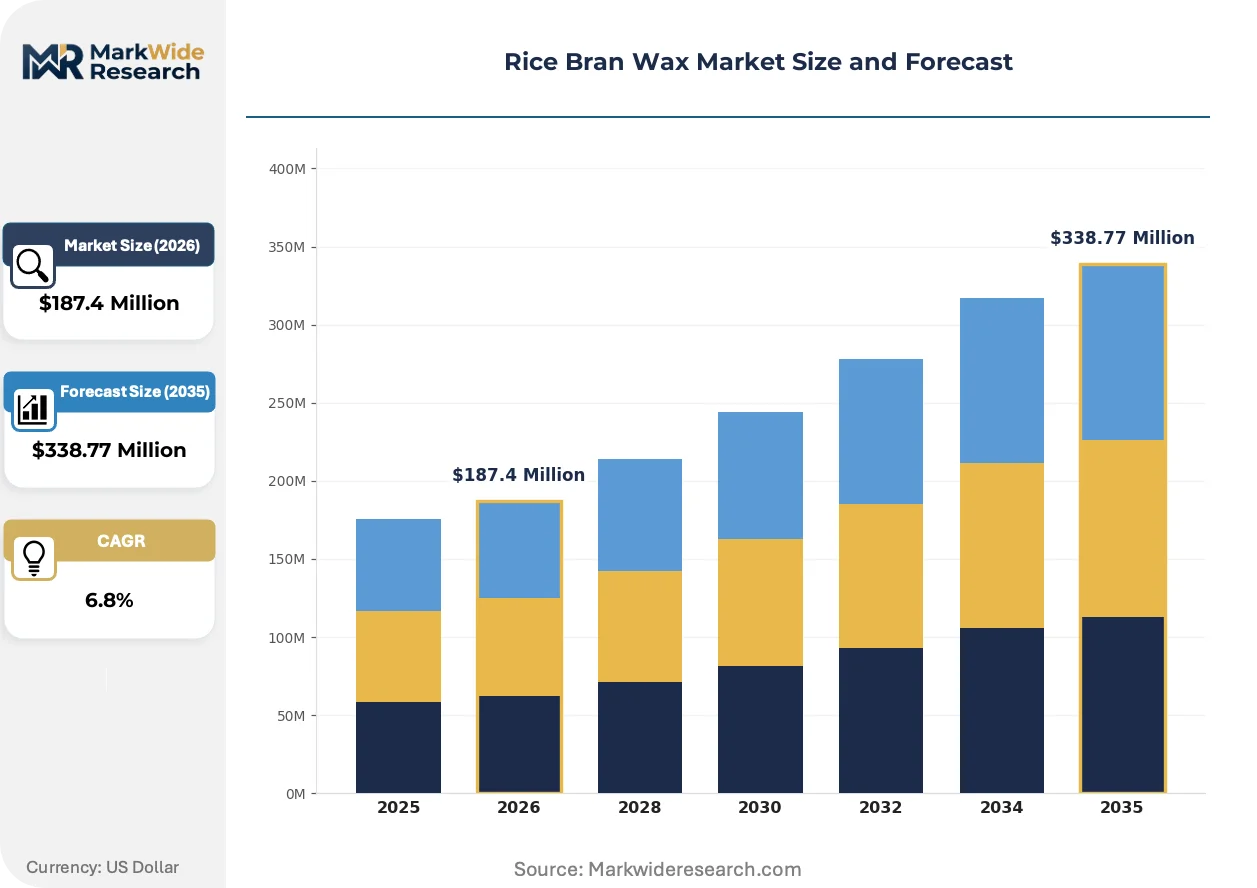
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Food Grade, Industrial Grade, Pharmaceutical Grade Application: Skin Care, Food Products, Candles, Coatings Distribution Channel: Online Stores, Retail Outlets, Direct Sales, Wholesalers End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Companies, Chemical Industry |
| Companies Covered | Strahl & Pitsch, SVROIL, Koster Keunen, Vantage Specialty Chemicals, Nisshin OilliO Group, Ltd., Clariant AG, Poth Hille, Indo Amines Ltd, Croda International Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Bran Wax Market Strategic Shifts
Supercritical CO2 extraction methods are overtaking traditional solvent dewaxing as the dominant purification technology, reshaping cost structures and purity benchmarks simultaneously.
Supercritical CO2 extraction systems operate at near-ambient temperatures, preserving heat-sensitive aliphatic ester profiles while eliminating hexane residue concerns. Pharmaceutical manufacturers in Germany and Switzerland are specifying CO2-derived material for oral dosage forms. This technology is overtaking conventional solvent refining in premium-grade supply contracts, compressing margins for legacy hexane-based processors.
REACH registration deadlines under ECHA's 2023-2025 substance evaluation wave are forcing European distributors to document full supply chain substance volumes. Importers must now verify crude bran oil origin down to specific milling facilities to satisfy extended safety data sheet requirements. Cosmetic Grade material faces the steepest compliance burden, with formulators demanding third-party certification for every production lot.
Direct procurement from Japanese rice milling cooperatives is displacing traditional distributor intermediaries among North American cosmetic compounders. Strahl & Pitsch and Koster Keunen are establishing technical service partnerships with end-users rather than pure resale relationships. This channel restructuring concentrates in California and New Jersey formulation clusters, where clean-label beauty brands prioritize supply chain provenance verification.
Rice Bran Wax Market Segmentation
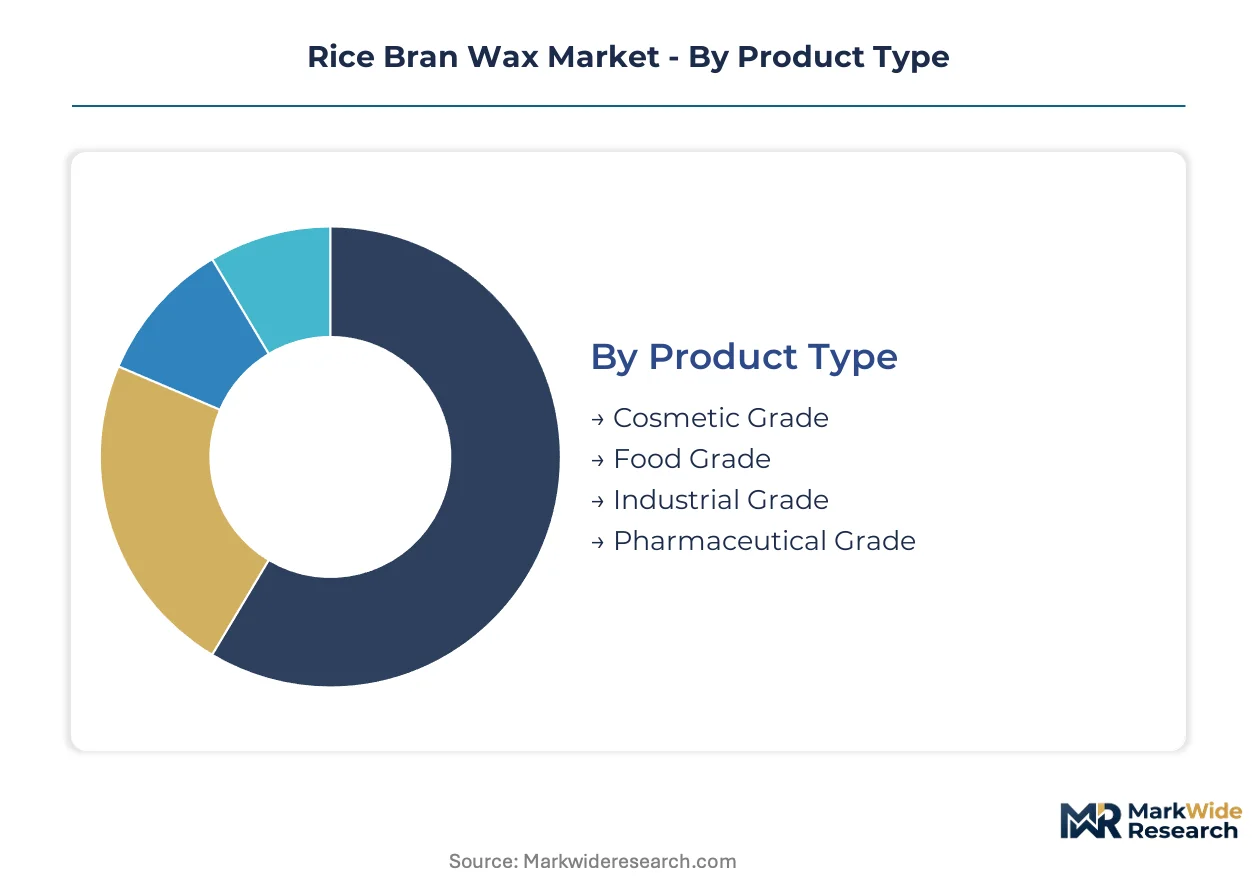
Segmentation in rice bran wax tracks how purity grades align with regulatory thresholds and end-use performance requirements. Procurement patterns diverge sharply between bulk industrial buyers and specialized cosmetic or pharmaceutical formulators seeking certified supply chains.
Product Type:
Standalone wax grades serve discrete regulatory environments, while embedded multi-grade formulations increasingly appear in cross-certified applications.
- Cosmetic Grade:Refined to aliphatic ester purity levels exceeding 85% with controlled crystallization for emulsion stability. Demand concentrates in Japanese and German clean-label beauty manufacturing where EU Green Deal bio-based mandates and FDA disclosure rules enforce ingredient traceability.
- Pharmaceutical Grade:Validated through FDA drug master file and CDSCO excipient pathways for oral dosage binders. European compounding pharmacies and Indian generic manufacturers anchor offtake as lipid-based tablet formulations displace synthetic alternatives.
- Food Grade:Meets FDA food-contact and FSSAI additive specifications for coating applications.
- Industrial Grade:Functions in solvent-based polishes and candle formulations facing waterborne displacement pressures.
Volume placements concentrate in Cosmetic Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
Cost tiers separate premium-positioned skin care formulations from commodity candle and coating uses where wax functions as a replaceable input.
- Skin Care:Rice bran wax provides occlusive film-forming and viscosity modification in clean-label moisturizers and color cosmetics. California and New Jersey formulation clusters prioritize Japanese-origin material for supply chain provenance verification.
- Food Products:Edible coatings for confectionery and fresh produce rely on food-grade certification through FDA and FSSAI frameworks.
- Candles:Blending component in natural wax formulations competing with soy and paraffin alternatives.
- Coatings:Surface modifier in solvent-based polishes facing demand erosion from acrylic waterborne systems.
Premium pricing accrues to Skin Care applications; Food Products deliver the steadiest volume baselines.
Distribution Channel:
Customer type determines channel selection, with large compounders bypassing intermediaries while smaller formulators rely on technical service partnerships.
- Direct Sales:Dominates pharmaceutical and large cosmetic procurement where batch certification and technical service integration matter. Strahl & Pitsch and Koster Keunen anchor North American and European direct relationships with end-formulators.
- Online Stores:Emerging channel for specialty cosmetic ingredient sampling and small-batch procurement.
- Retail Outlets:Limited to consumer candle and hobbyist craft applications.
- Wholesalers:Handles industrial-grade bulk movement to coating and polish manufacturers.
Direct Sales commands the highest margin capture; Online Stores are climbing the fastest as digital procurement penetrates mid-tier formulators.
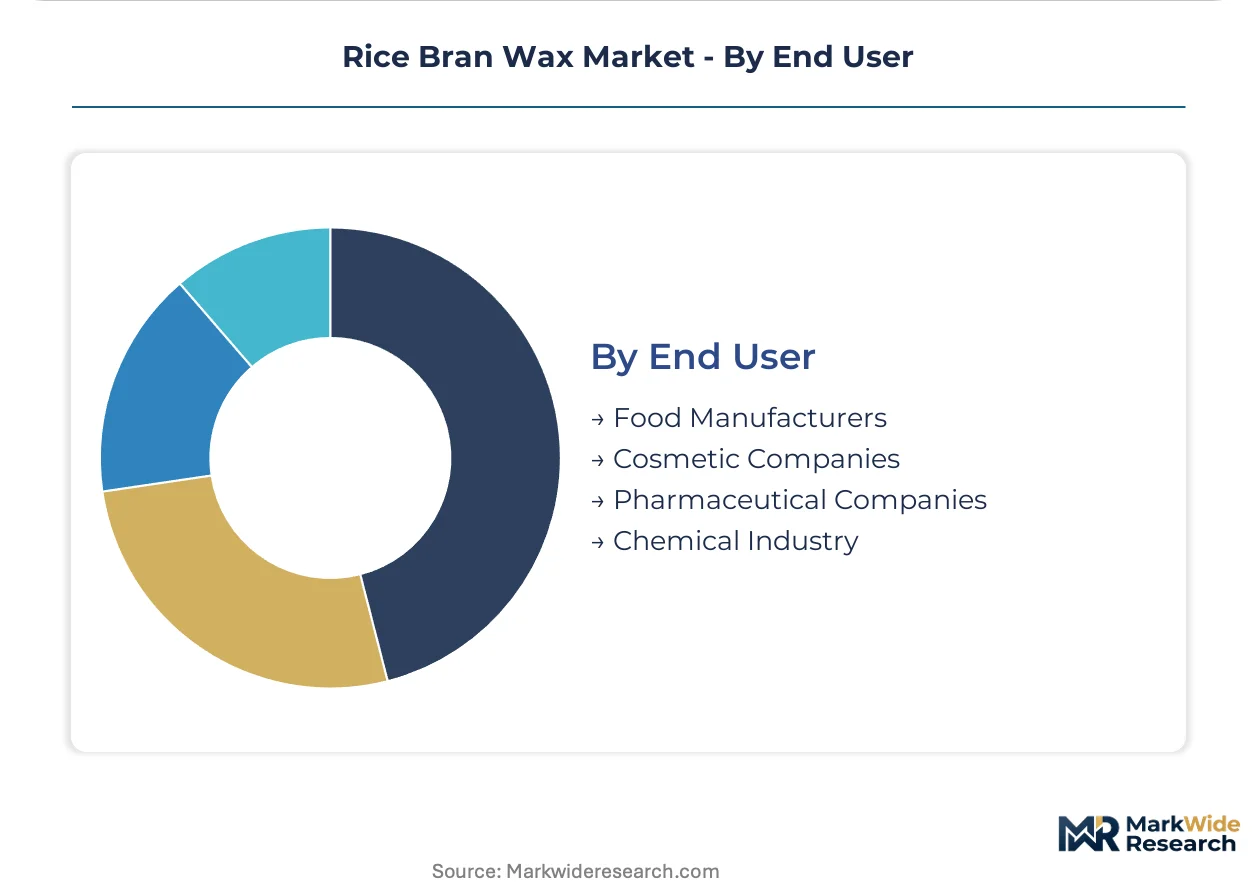
End User:
Supply concentration aligns with geographic clustering of downstream processing capabilities and regulatory expertise.
- Cosmetic Companies:Drive specification-setting through clean-label mandates and bio-based content targets. Japanese domestic formulators and German natural beauty brands enforce the strictest purity and provenance requirements.
- Pharmaceutical Companies:Expanding excipient validation programs in Germany, Switzerland, and India create certified demand pools.
- Food Manufacturers:Coating and confectionery processors in Japan and the United States absorb food-grade volumes.
- Chemical Industry:Coating and polish compounders facing formulation shifts away from solvent-based systems.
Cosmetic Companies anchor current volume; Pharmaceutical Companies are expanding most quickly as excipient pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese cosmetic formulators and German natural beauty brands drive the steepest specification requirements for rice bran wax. Procurement clusters concentrate in three distinct regulatory zones with divergent purity mandates.
Japan
Domestic milling cooperatives in Kanto and Kansai supply captive feedstock to Nisshin OilliO Group and regional cosmetic compounders. METI bio-based content guidelines enforce supply chain provenance verification for clean-label beauty exports. Tokyo and Osaka formulation labs specify aliphatic ester purity above 85 percent for emulsion stability.
Germany
REACH registration deadlines under ECHA's substance evaluation wave compel distributors to document crude bran oil origins down to specific milling facilities. EU Green Deal packaging mandates accelerate biopolymer compounding applications where rice bran wax functions as a nucleating agent. Cologne and Hamburg harbor cosmetic ingredient clusters prioritize CO2-extracted pharmaceutical-grade material.
United States
California and New Jersey clean-label beauty brands disintermediate traditional distributors through direct technical service partnerships. FDA food-contact regulations and EPA chemical substance reporting requirements shape purity benchmarks for coating applications. Los Angeles and Newark procurement offices verify Japanese-origin supply chains for provenance marketing claims.
India
Indo Amines Ltd and domestic processors target Middle Eastern and African export markets through BIS quality standard compliance. FSSAI food additive approvals and CDSCO excipient validation pathways create certification moats for pharmaceutical-grade production. Gujarat and Maharashtra refining hubs compete on crushing economics against food and biodiesel applications for rice bran oil feedstock.
Switzerland
Pharmaceutical compounding pharmacies and generic manufacturers anchor demand for lipid-based tablet binders validated through Swissmedic pathways. German and Swiss supercritical CO2 extraction specifications dominate premium-grade supply contracts. Basel formulation clusters specify hexane-free material for oral dosage form applications.
Rice Bran Wax Market Competitive Environment
Strategic partnerships dominate the current landscape as distributors pivot from pure resale to technical service integration. The vendor base separates into three tiers: Japanese upstream controllers with captive milling supply, European specialists with REACH-registered distribution networks, and Asian processors competing on export certification. Two archetypes define positioning: provenance-verified premium suppliers and scale-driven commodity refiners. Competitive moves concentrate on backward integration into rice milling belts and supercritical CO2 extraction capacity expansion.
Among Japanese upstream controllers, Nisshin OilliO Group occupies a position exemplifying captive supply architecture from Kanto and Kansai milling cooperatives. European specialists include Koster Keunen B.V., a Netherlands-based entity representing REACH-registered distribution archetypes, and Strahl & Pitsch, a century-old compounder anchoring North American cosmetic channels through direct technical relationships rather than intermediary resale. These three entities represent distinct geographic and structural positions within the market's tiered competitive geometry.
| Leading Market Players |
|---|
| Strahl & Pitsch |
| SVROIL |
| Koster Keunen |
| Vantage Specialty Chemicals |
| Nisshin OilliO Group, Ltd. |
| Clariant AG |
| Poth Hille |
| Indo Amines Ltd |
| Croda International Plc. |
| Others |
Value Chain & Pricing Dynamics
Crude bran oil futures volatility cascades through rice bran wax extraction economics, compressing margins for hexane-based processors while amplifying premiums for CO2-extracted pharmaceutical grades. Japanese milling cooperatives leverage captive supply to enforce three-tier pricing stratification across cosmetic, pharmaceutical, and industrial grades.
Pricing Analysis
Volume placements concentrate in industrial-grade bulk contracts while margin capture accrues to pharmaceutical-grade certifications. Price differentiation hinges on aliphatic ester purity thresholds and REACH registration status, with Swiss and German buyers paying premiums for hexane-free material. Cost compression in industrial tiers is intensifying because waterborne coating displacement erodes solvent-based wax demand. Small-scale cosmetic formulators exhibit highest price sensitivity; pharmaceutical compounders in Basel and Hamburg demonstrate lowest sensitivity due to excipient validation requirements.
Supply Chain Analysis
Specialized extraction talent scarcity in Japan and Germany constrains supercritical CO2 capacity expansion despite pharmaceutical demand surges. Geographic supply concentration centers on Japan, India, and the Netherlands, with Kanto milling cooperatives and Gujarat refining hubs anchoring upstream availability. Raw material dependencies rest on rice bran oil feedstock competition from food and biodiesel applications, hexane solvent supply chains, and CO2 extraction equipment imports. Single-source vulnerability from Brazilian carnauba wax substitution periodically disrupts rice bran wax pricing power. Distribution runs through direct technical service partnerships for premium grades and wholesaler networks for industrial bulk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rice bran wax competitive dynamics have devolved into a vertical-integration race, with processors securing captive milling supply or supercritical CO2 extraction capacity to defend margin structures against feedstock volatility.
For Market Incumbents: Deepen backward integration into Kanto and Kansai milling cooperatives to lock in crude bran oil offtake before biodiesel demand escalates. Expand CO2 extraction capacity in European pharmaceutical corridors to capture excipient validation premiums. Carnauba wax supply volatility from Brazil threatens pricing power; defend through long-term cosmetic brand partnerships with provenance verification requirements. For New Entrants and Emerging Players: Online ingredient marketplaces offer the lowest-friction entry vector for mid-tier cosmetic formulators seeking small-batch pharmaceutical-grade sampling. White-space opportunities concentrate in Indian export certification for Middle Eastern and African markets, plus biopolymer nucleating agent applications for EU Green Deal packaging mandates. Target CDSCO excipient validation services as a technical service wedge. For Investors and Strategic Acquirers: Distressed-cycle entries favor REACH-registered European distributors with established pharmaceutical channel relationships during ECHA substance evaluation waves. Long-term viability over a five-to-ten-year horizon rests on supercritical CO2 extraction technology ownership and captive milling supply arrangements. Monitor Brazilian carnauba harvest forecasts as the key inflection signal for rice bran wax substitution demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milling Cooperatives | Nisshin OilliO Group's captive supply from Kanto and Kansai secures feedstock priority against biodiesel competition. |
| Supercritical CO2 Capacity Expansion | Swiss and German pharmaceutical compounders specify hexane-free material for oral dosage form applications. |
| REACH Registration Acceleration | ECHA compliance deadlines force distributors to document crude bran oil origins down to specific milling facilities. |
| Direct Technical Service Partnerships | Strahl & Pitsch and Koster Keunen disintermediate traditional resale through end-formulator relationships in California and New Jersey. |
| Biopolymer Nucleating Agent Validation | EU Green Deal packaging mandates create demand for rice bran wax in PLA and PHA formulations. |
Study Parameters
Multi-period observation of crude bran oil price indices, REACH registration filings, and cosmetic formulation procurement patterns anchored the trend analysis, supplemented by interviews with rice milling cooperative managers, supercritical CO2 extraction plant engineers, pharmaceutical excipient procurement leads, and clean-label cosmetic brand formulators. Secondary validation drew from ECHA substance evaluation databases, FDA food-contact regulation filings, FSSAI additive approval records, and Japanese METI bio-based content guidelines. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrices modeled grade-tier supply volumes against end-use demand across skin care, pharmaceutical, food coating, and candle applications over the projection horizon. Segmentation dimensions included purity certification level, extraction technology type, geographic regulatory cluster, and channel structure. CAGRs were derived from trend extrapolation of feedstock availability constraints and substitution elasticity against carnauba wax. Forecast inputs incorporated rice bran oil crushing economics and ECHA registration timeline assumptions.
The model holds under stable Brazilian carnauba supply and sustained EU Green Deal bio-based mandates; deviation in rice harvest yields or accelerated waterborne coating displacement would shift volume-mix projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Squalane Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Ethoxylates Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Petrolatum Market
Oleochemicals
Global White Oil Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market